

Key Takeaways
- Comgest Global Investors’ latest 13F shows it added to NVIDIA and opened a new stake in Arista Networks in the third quarter.
- NVIDIA has fallen 29% since Sept. 30 after its CEO resigned, while Arista is close to its quarter-end price.
- Analysts’ average targets sit well above both stocks, with the most upside in NVIDIA, at 68%.
- NVIDIA, at about 13x forward earnings, is the one the numbers back best, and its Nov. 17 report is the first test.
A $4.3 billion fund just put more money behind the companies building AI data centers. Comgest Global Investors’ 13F for the quarter ended Sept. 30, filed Nov. 9, shows its biggest new or added positions included NVIDIA (NVDA) and Arista Networks (ANET).
That $4.3 billion is what its 13F holds in US stocks, across 56 positions, and both now sit in its top 10.
A bigger NVIDIA bet, then a 29% drop
Comgest held 1.06 million NVIDIA shares on Sept. 30, 52% more than three months earlier. They were worth $241 million at the quarter’s end, 5.6% of its 13F.
The stock has fallen 29% from its Sept. 30 price since. Jensen Huang resigned as CEO before the open on Nov. 12, after the board said on Nov. 8 it would look into reports that he had been the target of a foreign intelligence effort. HSBC then cut the stock to Hold with a $170 target, citing the open succession question and tighter US export rules.
That leaves NVIDIA at about 13x forward earnings, below every quarter-end reading TIKR has going back to 2014. Analysts’ consensus target has come down from its late-October peak of $329, but it’s still well above the $233 of a year ago:
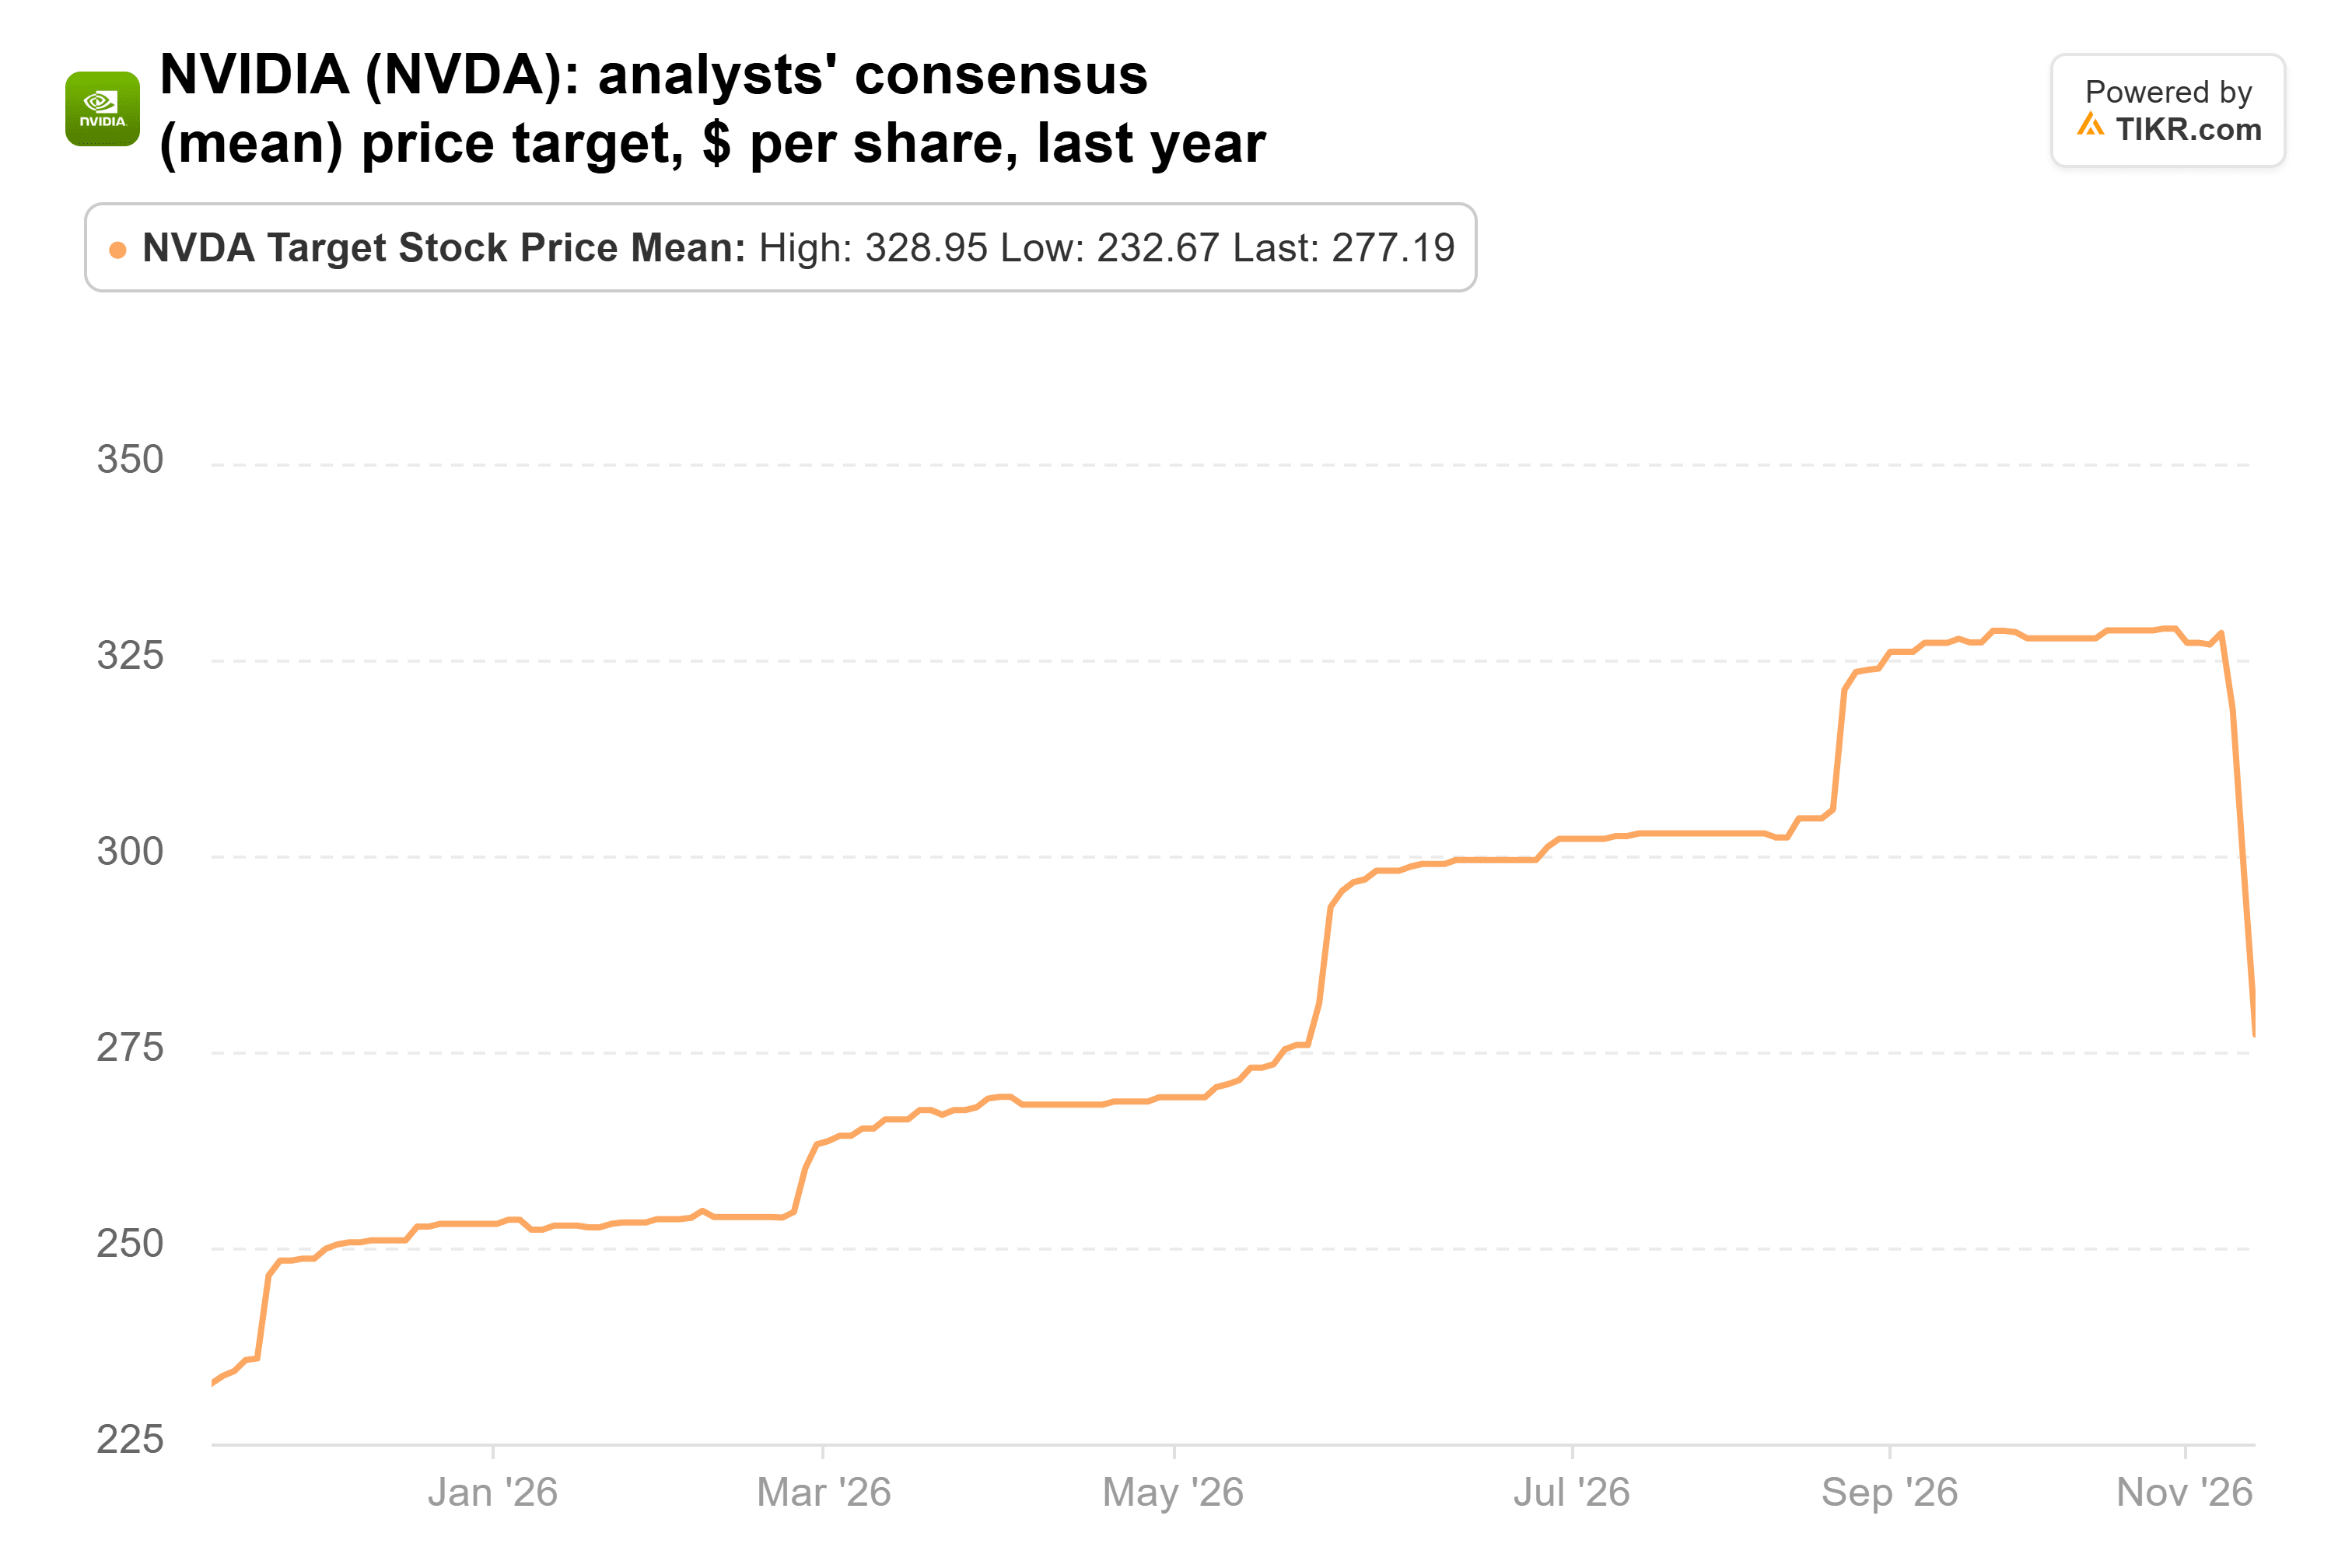
Even the Street’s lowest target, HSBC’s $170, sits above the stock.
TIKR tracks 63 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Broadcom is a bet on two AI labs
Comgest nearly quadrupled its Broadcom (AVGO) stake in the third quarter, to 565,678 shares worth $199 million on Sept. 30, or 4.6% of its 13F. The stock is 1% below its Sept. 30 price.
Broadcom’s AI chip revenue was $16.7 billion in the quarter ended Aug. 2, up 221% from a year earlier, and management expects about $115 billion of it in fiscal 2027 and $230 billion in fiscal 2028. But at least 21 of the roughly 30 gigawatts management sees across those two years go to Anthropic and OpenAI. And Broadcom backstops up to about $29 billion of leases for Anthropic’s chips, more than its $24.0 billion of cash on Aug. 2.
Rothschild & Co Redburn downgraded the stock to Neutral on Nov. 13 and cut its target to $398 from $595, arguing the labs have to become self-financing before that upside shows up. At about 20x forward earnings, Broadcom trades below its five-year average of 24x on TIKR. The rest of the Street hasn’t backed off, and the consensus target has climbed from $395 to $533 over the past year, its high:
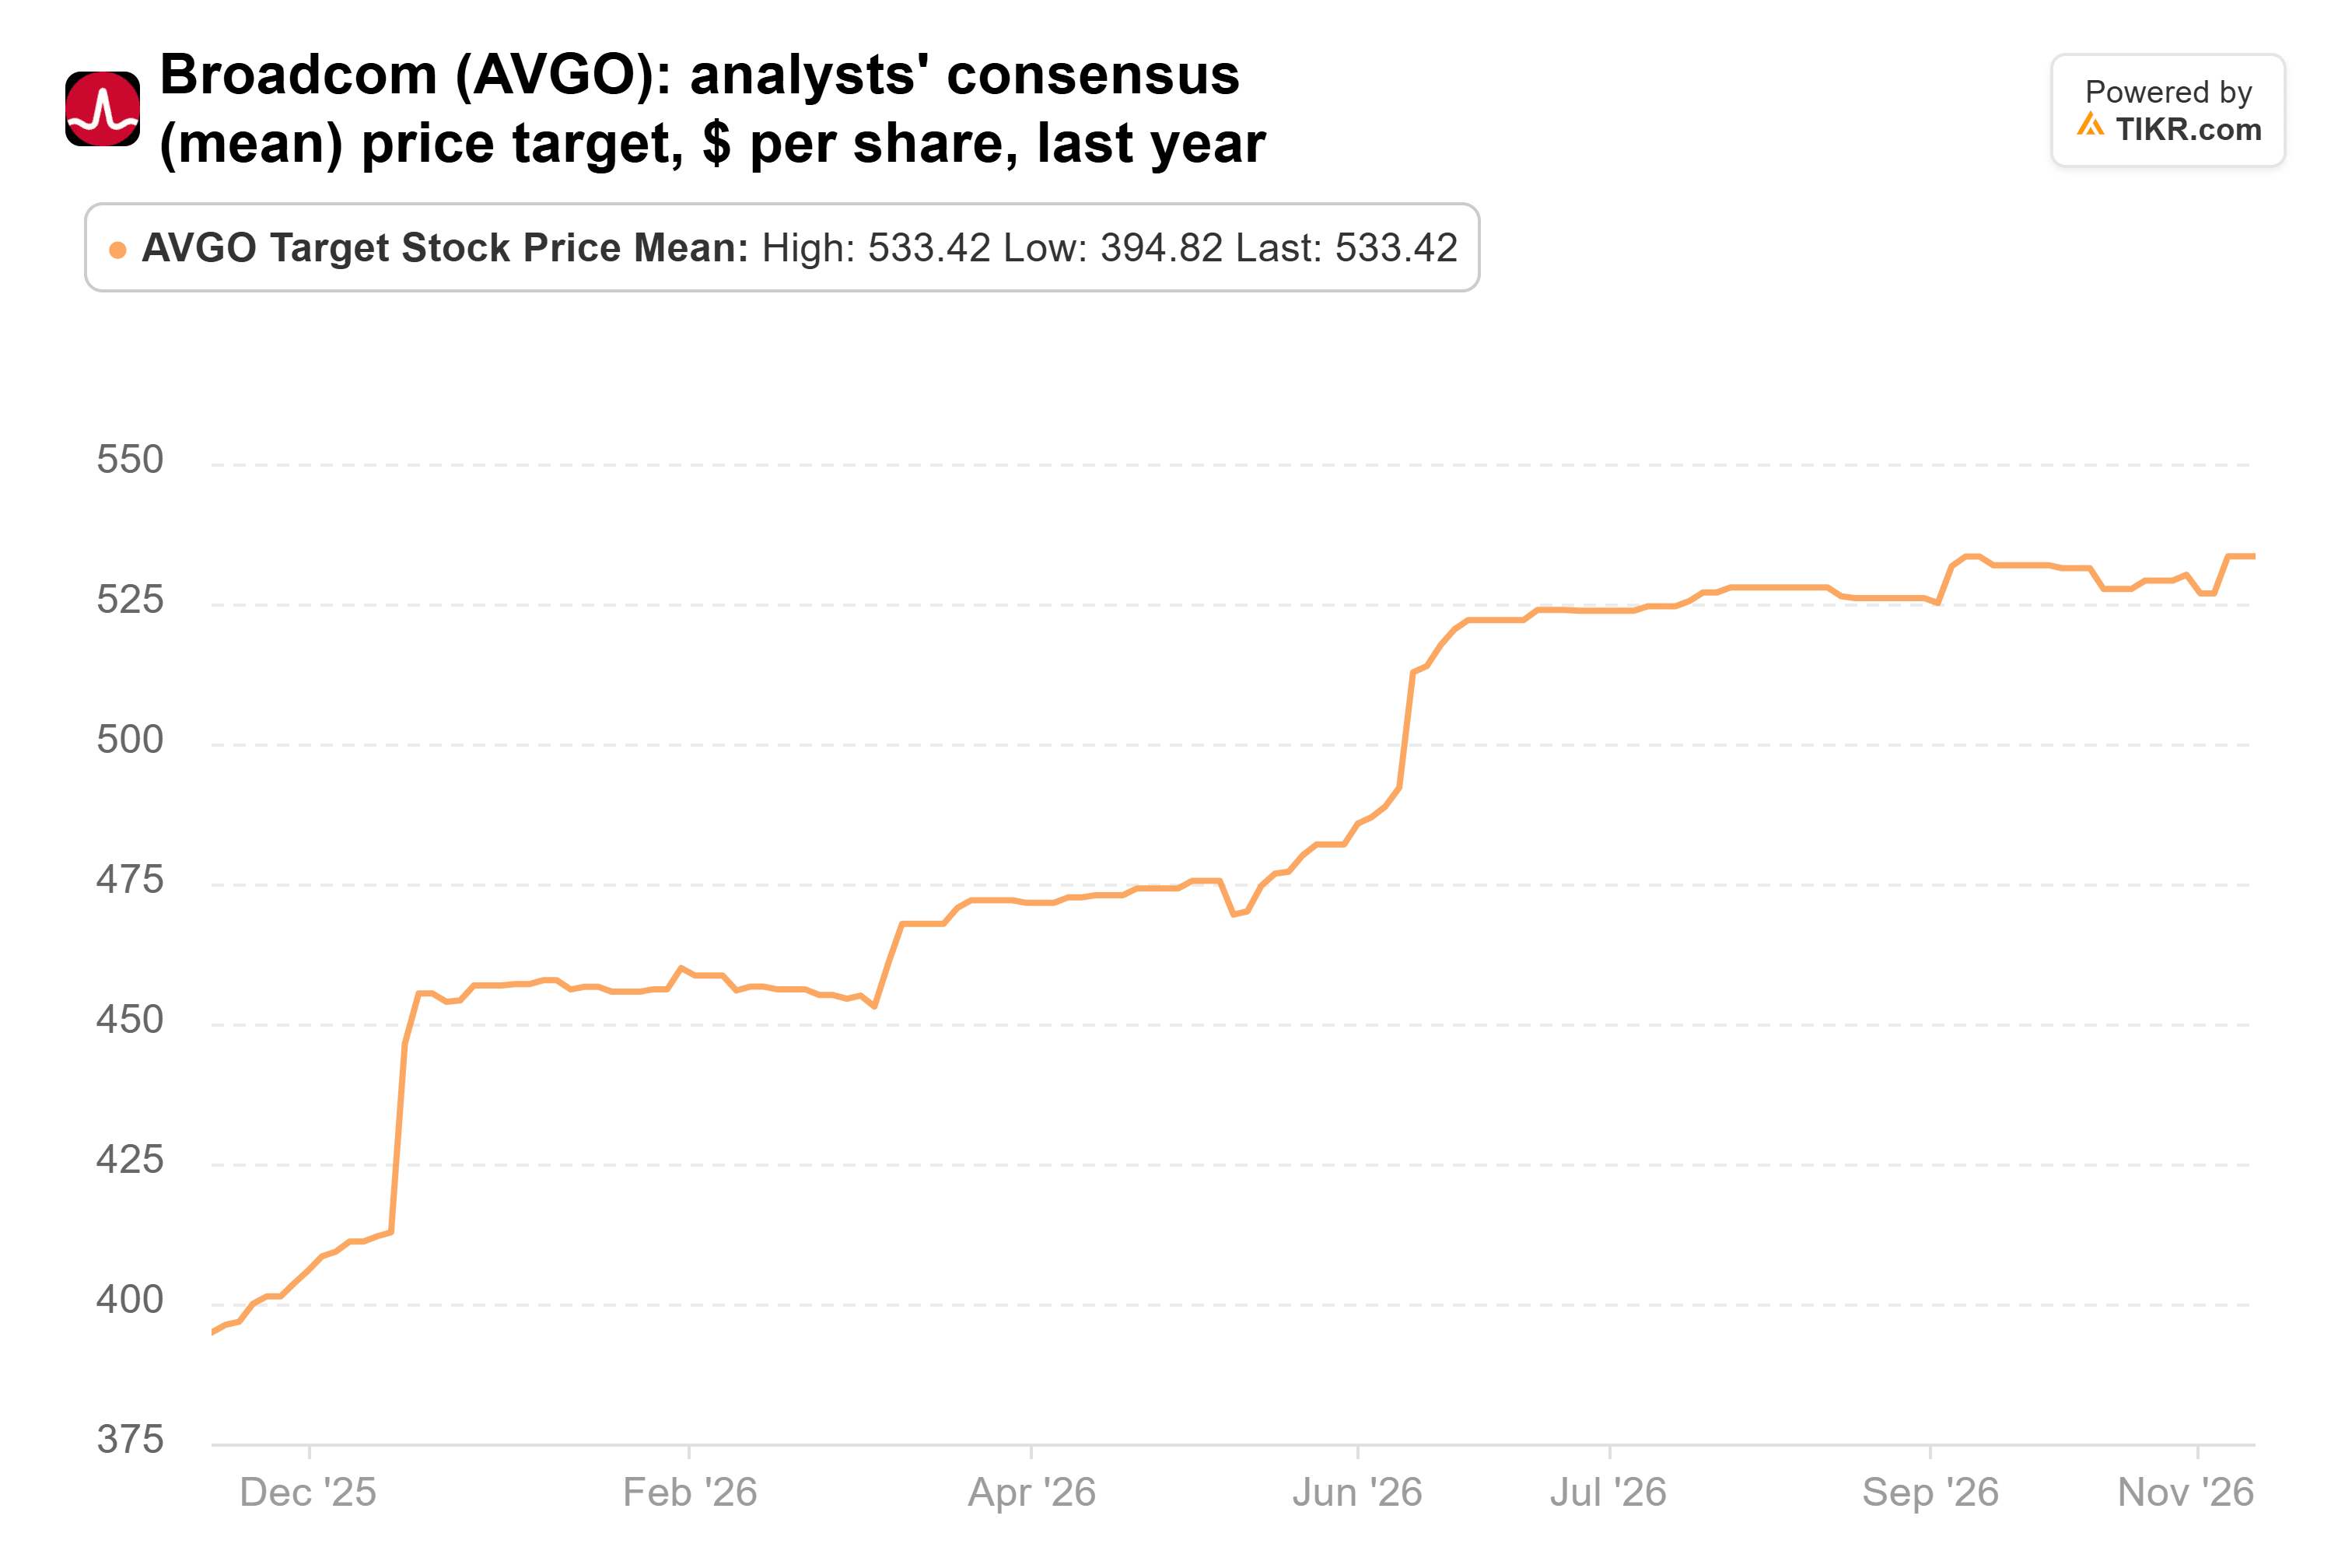
The numbers back Comgest here, as long as both labs keep paying their bills.
Arista is the new name, and its outlook just got bigger
Arista is the only one of the three Comgest didn’t own three months earlier. Comgest held 757,834 shares on Sept. 30, worth $154 million and 3.6% of its 13F, and the stock is 3% below its Sept. 30 price.
That’s despite a strong third-quarter report on Nov. 3. Revenue rose 58.5% to $3.66 billion, and management guided 2027 revenue to about $18.5 billion, against the $16.4 billion analysts expected going in. The stock fell with AI networking stocks on fears that the Democrats’ midterm sweep will slow data center building, though none of Arista’s cloud customers has announced a spending cut.
Arista trades at about 35x forward earnings, in line with its average since 2014 and below its one-year average of 42x. The risk is how much it’s betting on that outlook: purchase commitments reached $11.4 billion at the end of September, up from $9.7 billion three months earlier. Analysts’ consensus target has climbed from $164 to $250 over the past year:
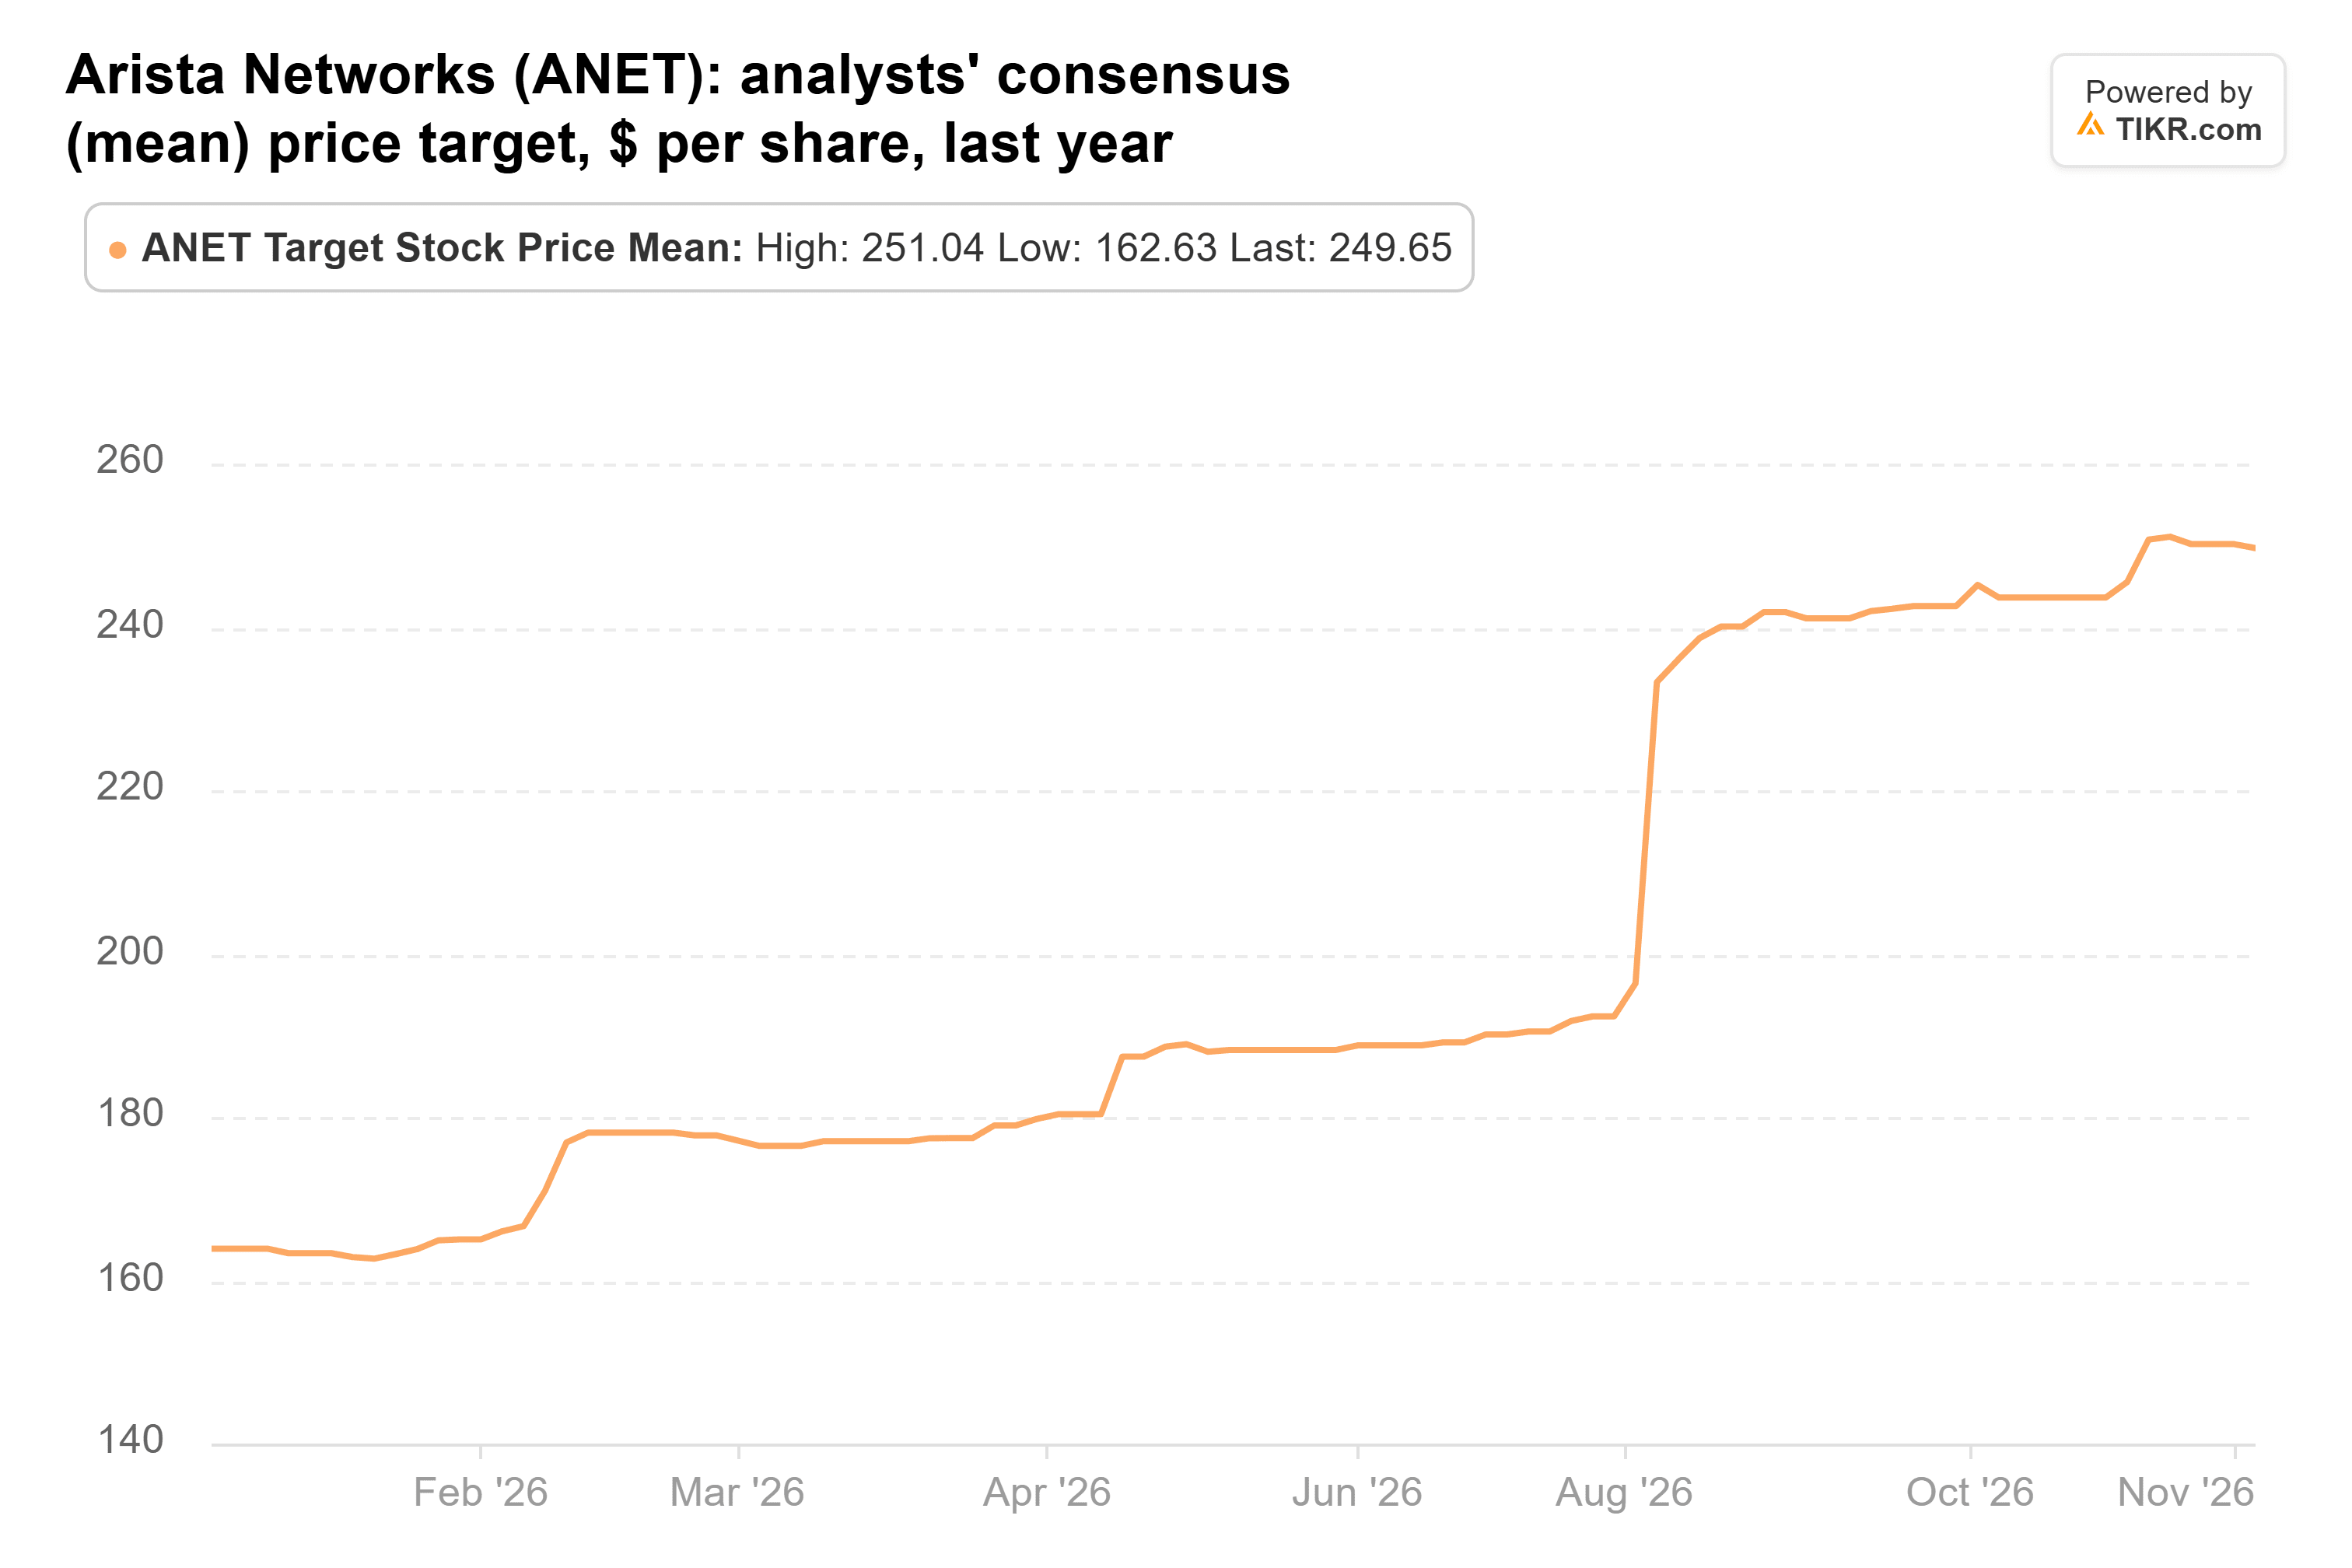
That’s 27% above the last close.
NVIDIA is the one I’d buy
If I could only buy one of the three right now, it’d be NVIDIA. It’s the only one that’s gotten meaningfully cheaper since Sept. 30, it trades at the lowest multiple of the three, and the Street’s average target sits 68% above the last close. And the business hasn’t missed: revenue beat the top of management’s guidance in each of the last three quarters.
Arista is a close second, since its outlook just got better and the stock still trades below its one-year average multiple. Broadcom’s growth is just as real, but more of it depends on two customers that still need outside financing.
The risk with NVIDIA is plain: it has no permanent CEO, and tighter export rules could cut into sales outside the US and Taiwan. We’ll know more on Nov. 17, when NVIDIA reports against its guide of $108.0 billion of revenue, plus or minus 2%, and gives its first outlook since Huang left. Comgest’s next 13F, due in mid-February, will show whether it held on.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


