Key Takeaways
- Hims & Hers grew third-quarter revenue 49% to $890.4 million but swung to a $33 million net loss as gross margin fell to 57%.
- Subscribers fell to nearly 2.8 million from nearly 2.9 million in June, and the CFO tied this to deliberately paced marketing spend.
- The Eli Lilly deal brings Zepbound onto the platform from $299 a month but at the same self-pay prices sold everywhere else.
- Hims cut its 2026 adjusted EBITDA outlook to $257 million to $277 million, and the fourth-quarter report is the next test.
Hims & Hers Health (HIMS) heads into its busiest month of the year with less margin to spare. Third-quarter revenue jumped 49% to $890.4 million, just below the $892.9 million analysts expected. Gross margin, however, fell to 57% from 74%, and the company swung to a $33 million net loss.
Shares slid more than 3% in volatile after-hours trading once the numbers landed.
Hims is pitching a two-part fix. A November 6 deal lets patients buy Eli Lilly (LLY) Zepbound on the platform from $299 a month, adding to the Novo Nordisk (NVO) Wegovy access Hims secured in March. Then Peptides+ launches later this month.
“The platform people can rely on for their health every day, in every category, and every market, is the platform that will transform the industry,” CEO Andrew Dudum said in the results release. Building it has gotten expensive, though.
Faster sales, thinner margins
The quarter split cleanly in two:
- Domestic revenue rose 21% to $657.1 million, while international revenue more than quadrupled to $233.3 million.
- Monthly revenue per average subscriber climbed 30% to $105.
- Subscribers grew 13% from a year earlier to nearly 2.8 million, down from nearly 2.9 million in June.
That last line explains part of the selloff. CFO Yemi Okupe said Hims was “intentionally pacing marketing spend ahead of several planned expansions” in the fourth quarter.
Revenue growth has now accelerated for two straight quarters…
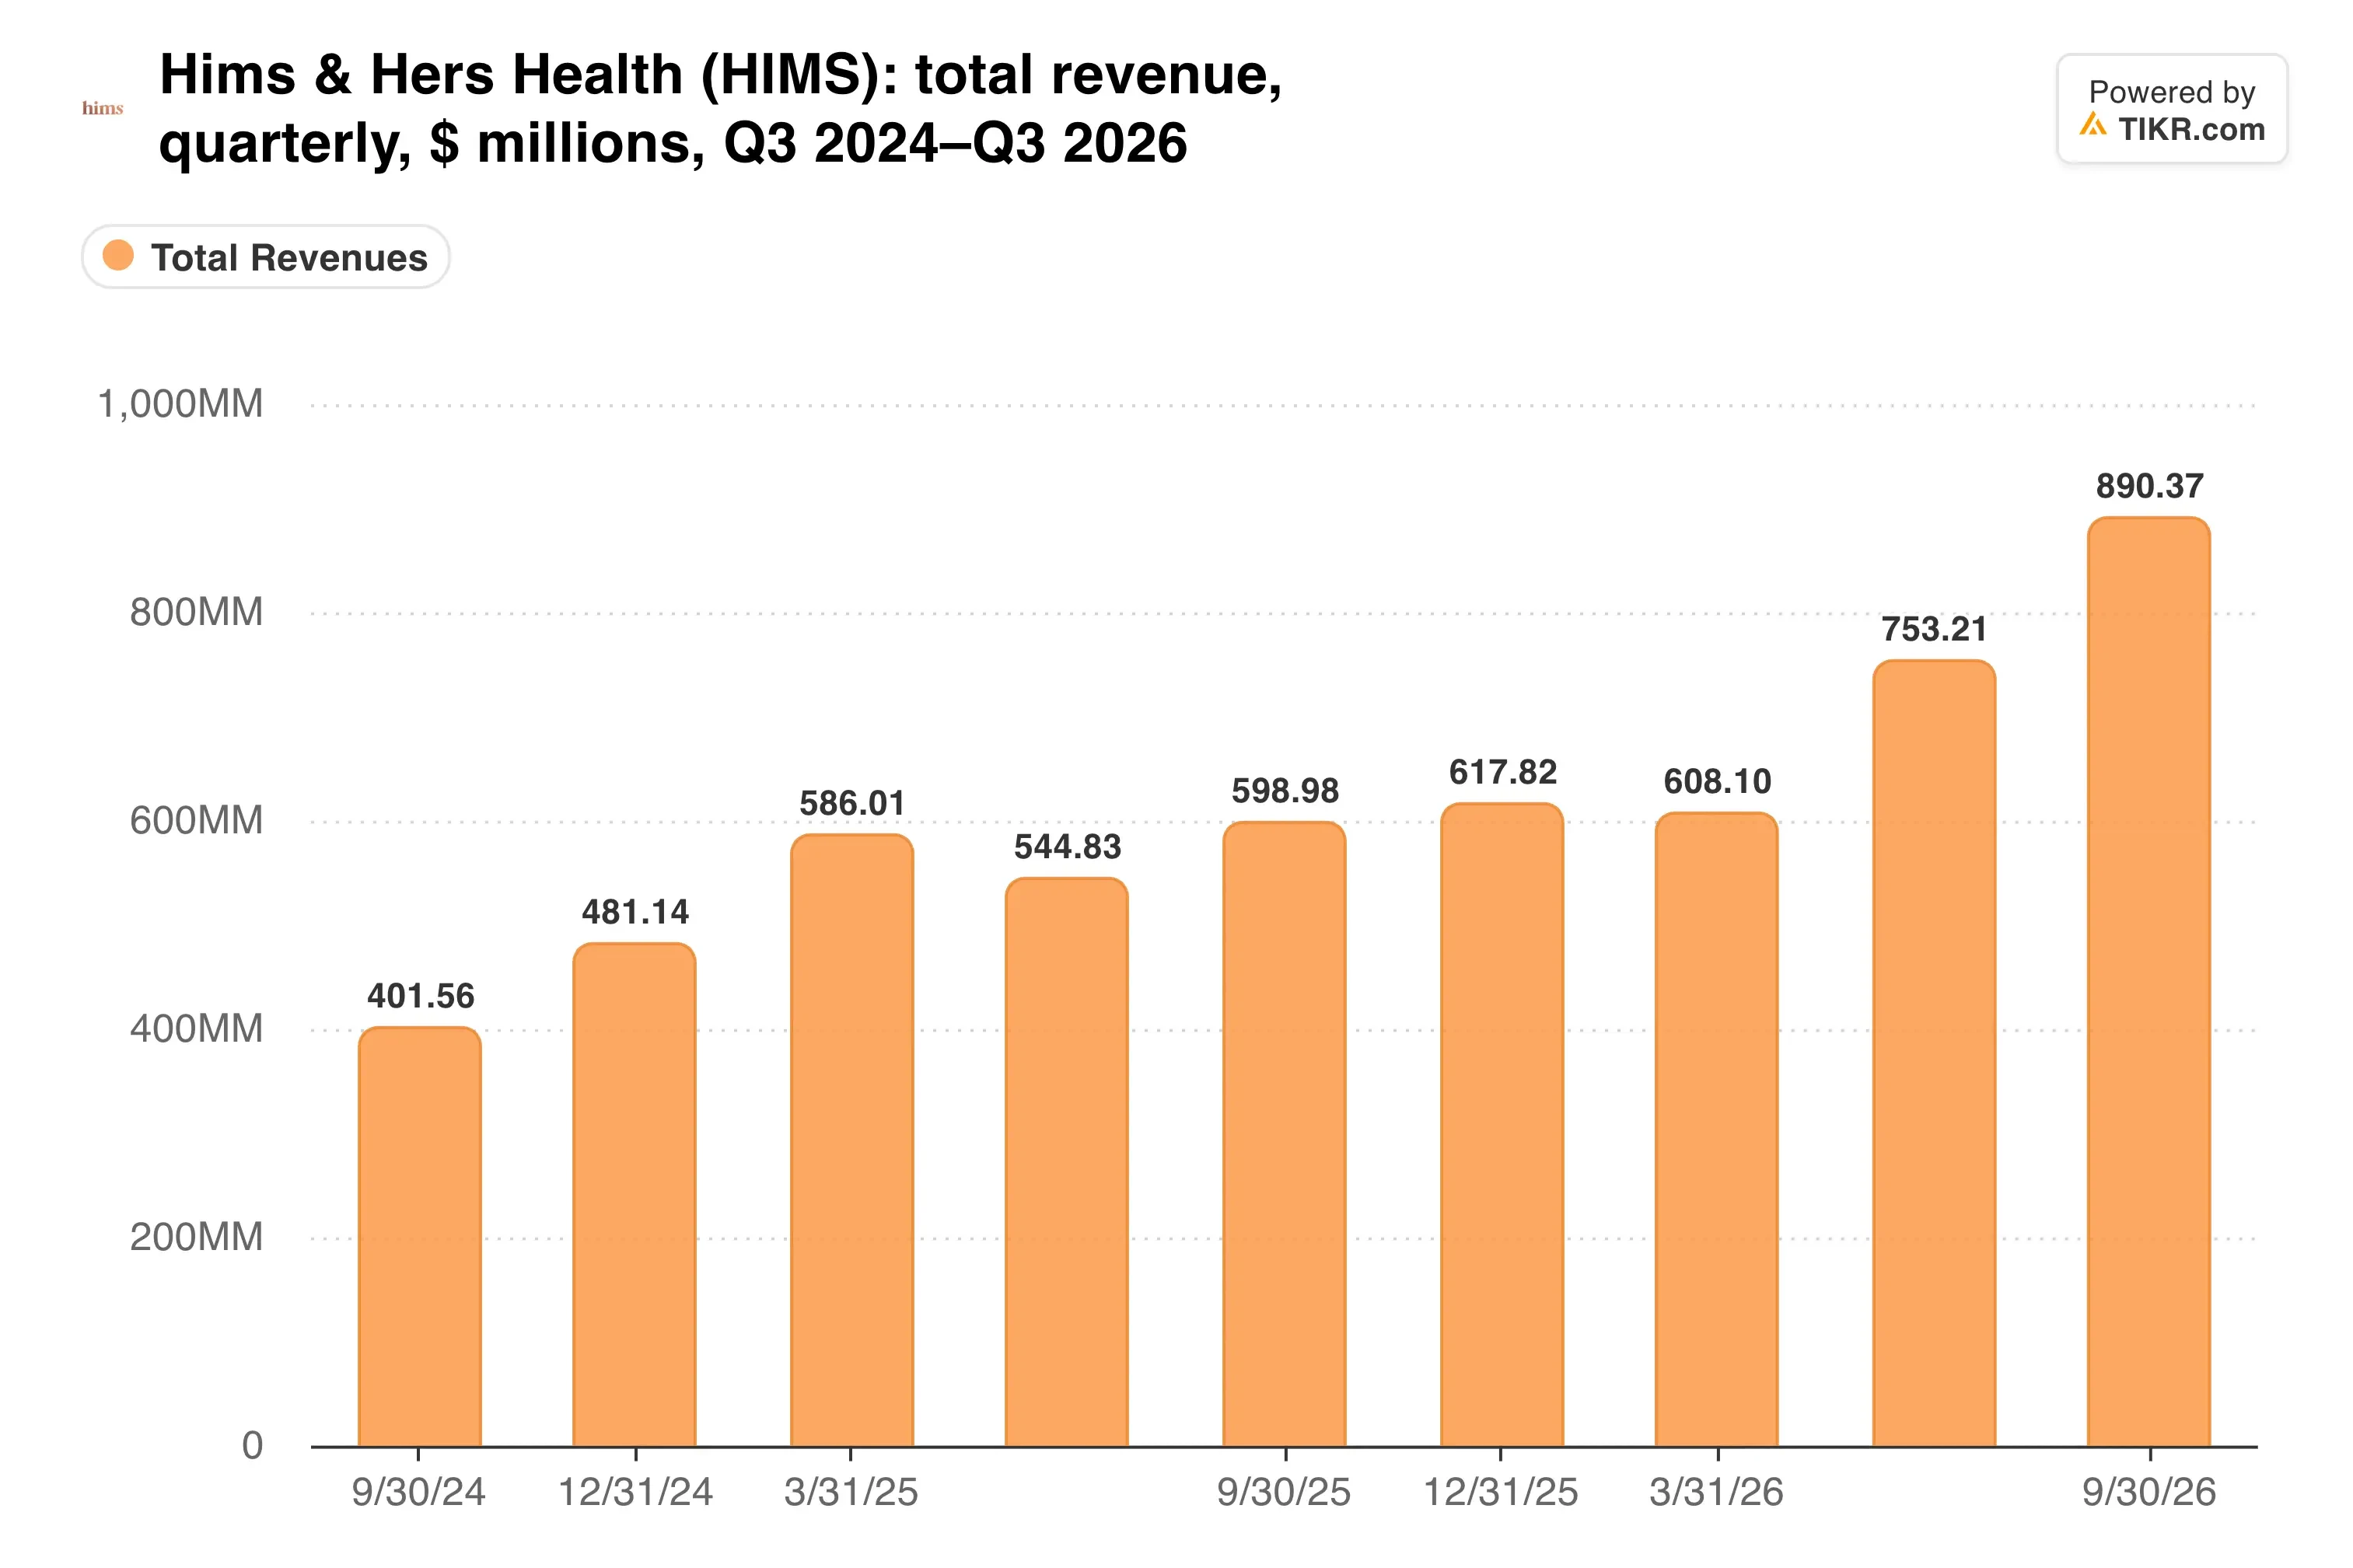
So the top line holds up. The cost of producing it is the real problem.
Branded drugs squeeze the margin
Gross margin fell because Hims leaned into costlier branded weight-loss drugs and expanded abroad. Morningstar analyst Keonhee Kim told Reuters the branded mix lifts revenue per subscriber but will keep weighing on gross margin in the near term.
How far has it dropped?
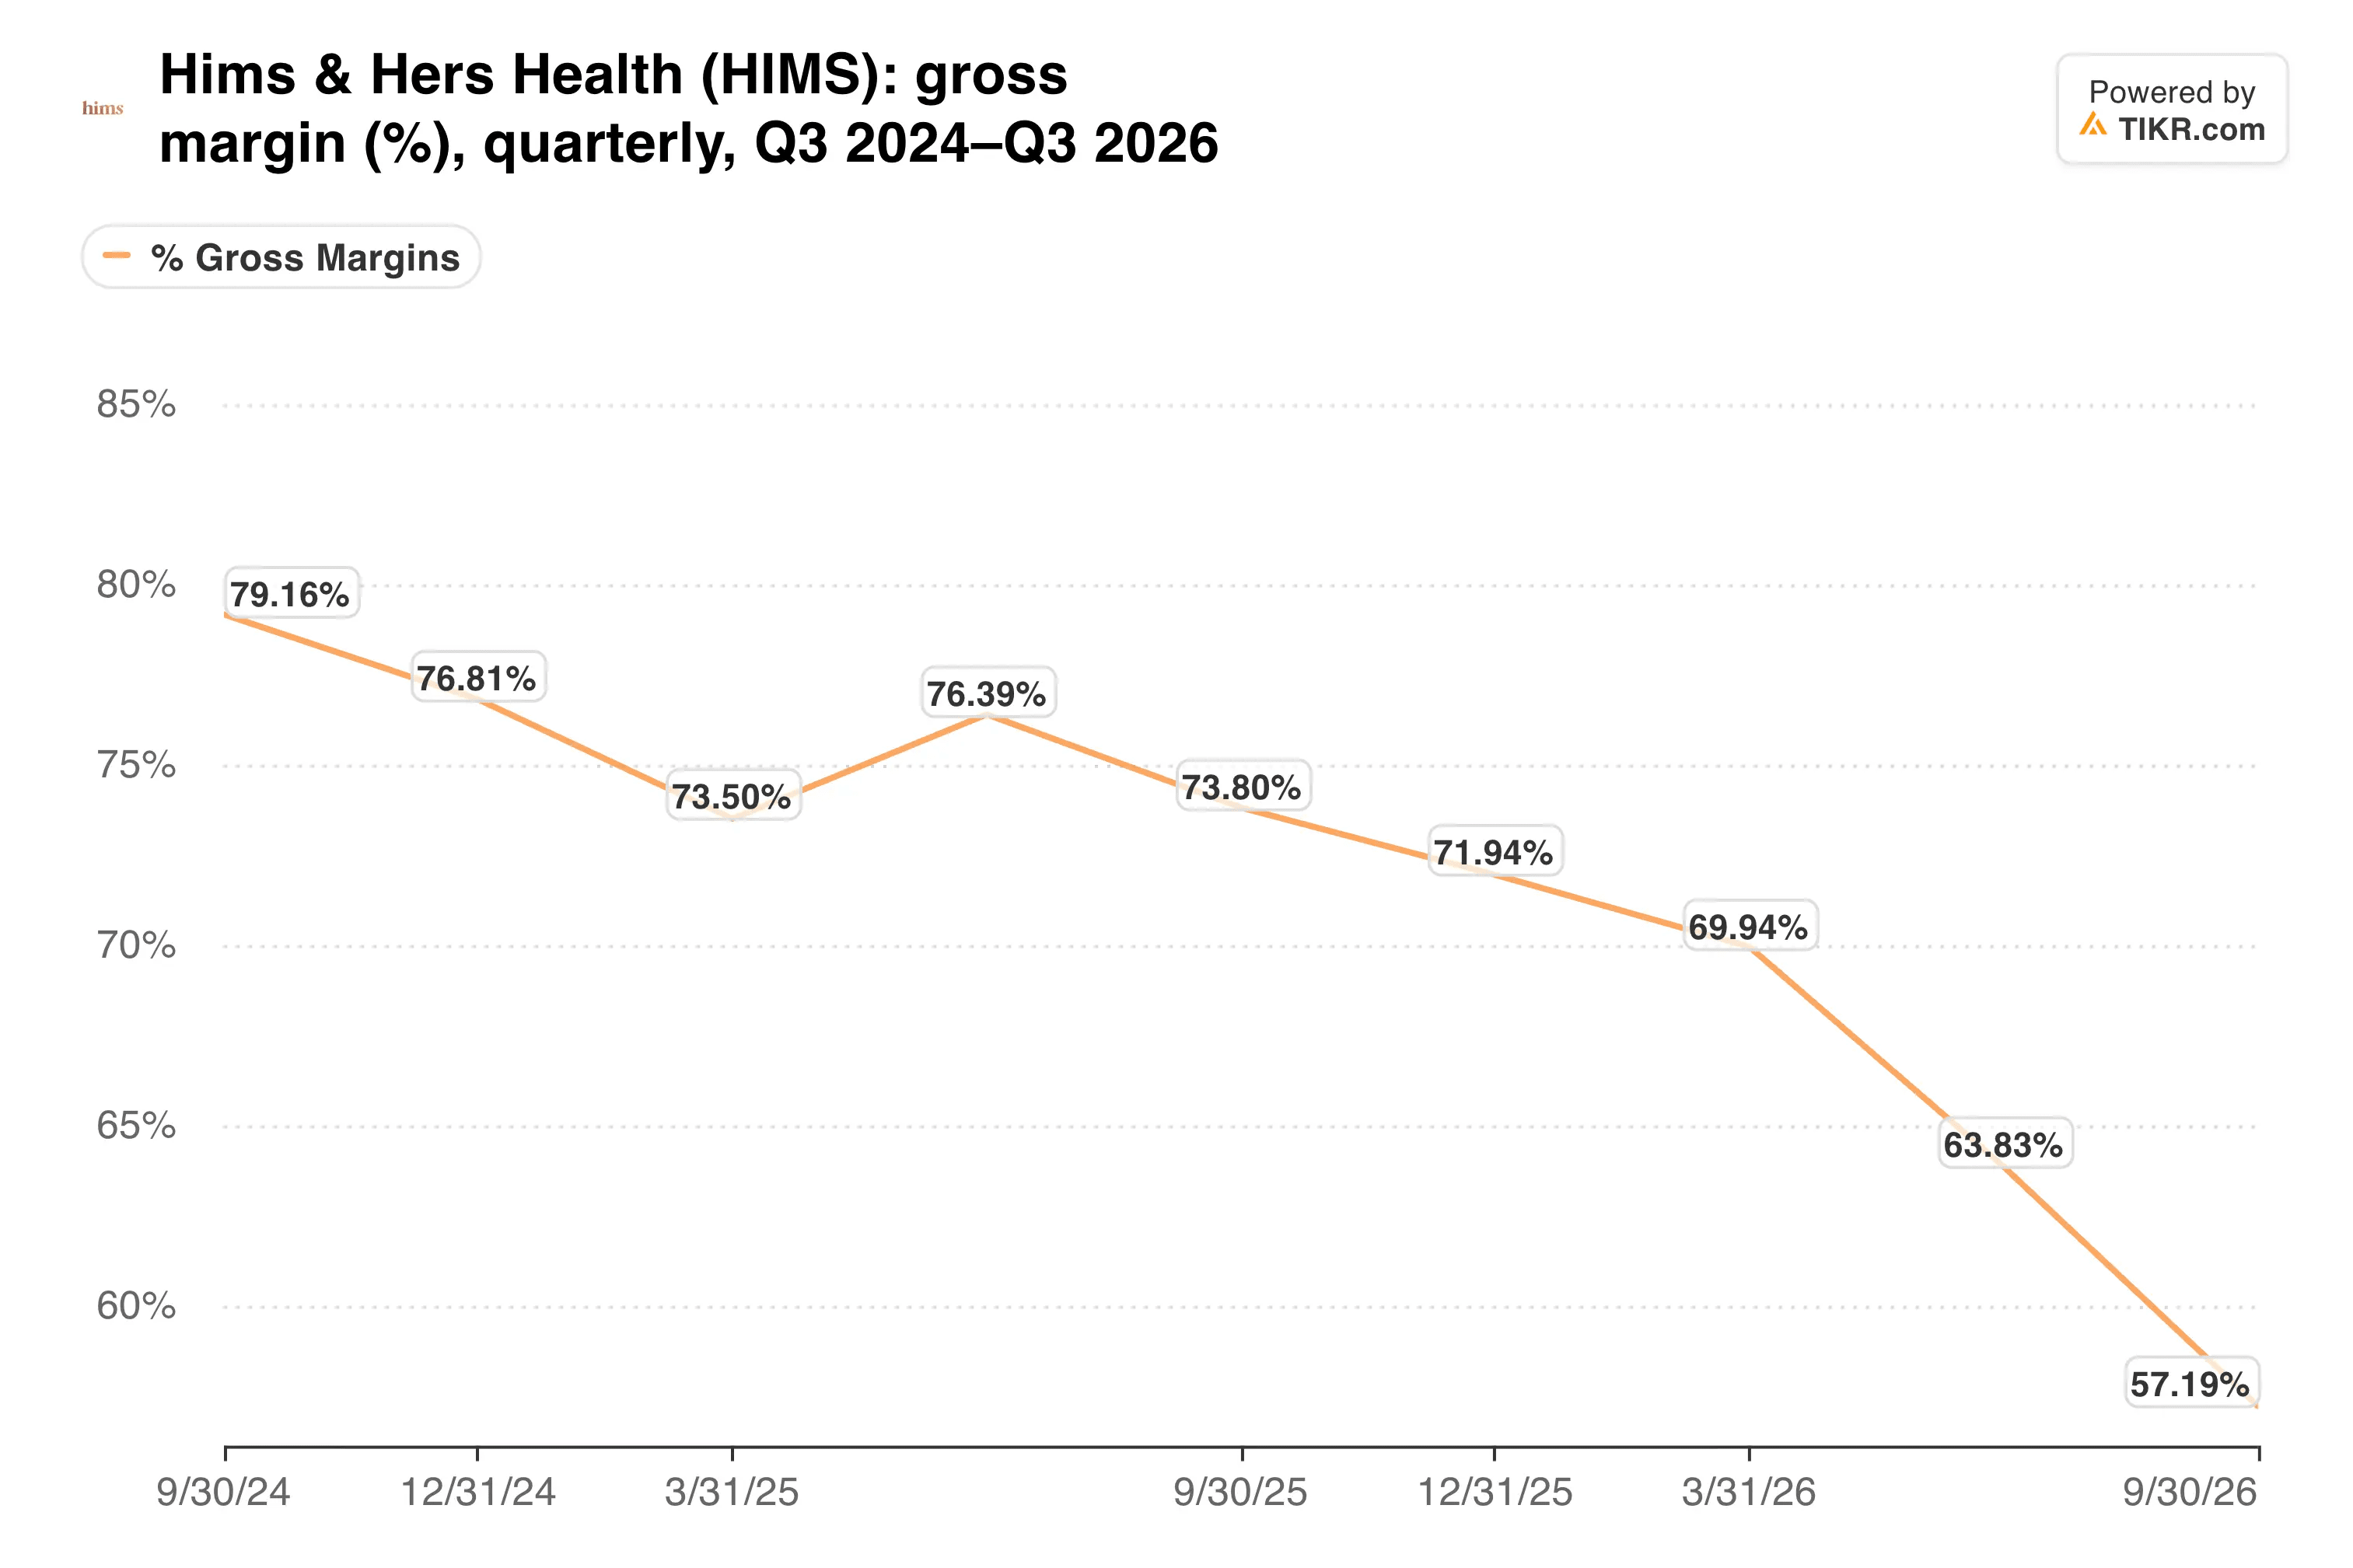
That’s a 17-point slide in a year. Lilly’s deal adds volume, yet it barely changes the unit economics. Patients pay the same self-pay prices available anywhere, and Hims committed never to offer compounded copies of Lilly’s GLP-1 drugs.
The upside is reach. Lilly told Reuters that 40% to 45% of Zepbound sales already come through self-pay channels, and Okupe expects the partnership to help retention.
Peptides+ is the higher-margin bet. It starts with NAD+, sermorelin and glutathione, and Hims plans to make BPC-157 and TB-500 in the US later. Those rely on regulatory enforcement discretion, since none carries FDA approval.
TIKR tracks 16 analysts on Hims & Hers. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Hims & Hers, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Hims & Hers’ Analyst Ratings
Peptides won’t rescue 2026
Okupe said peptide revenue should be immaterial through the year. Meanwhile, Hims cut its 2026 adjusted EBITDA outlook to $257 million to $277 million, from $275 million to $325 million. It also narrowed revenue guidance to $3.13 billion to $3.15 billion.
Fourth-quarter guidance calls for $875 million to $895 million in revenue and adjusted EBITDA of $70 million to $90 million.
Cash generation has thinned out as well.
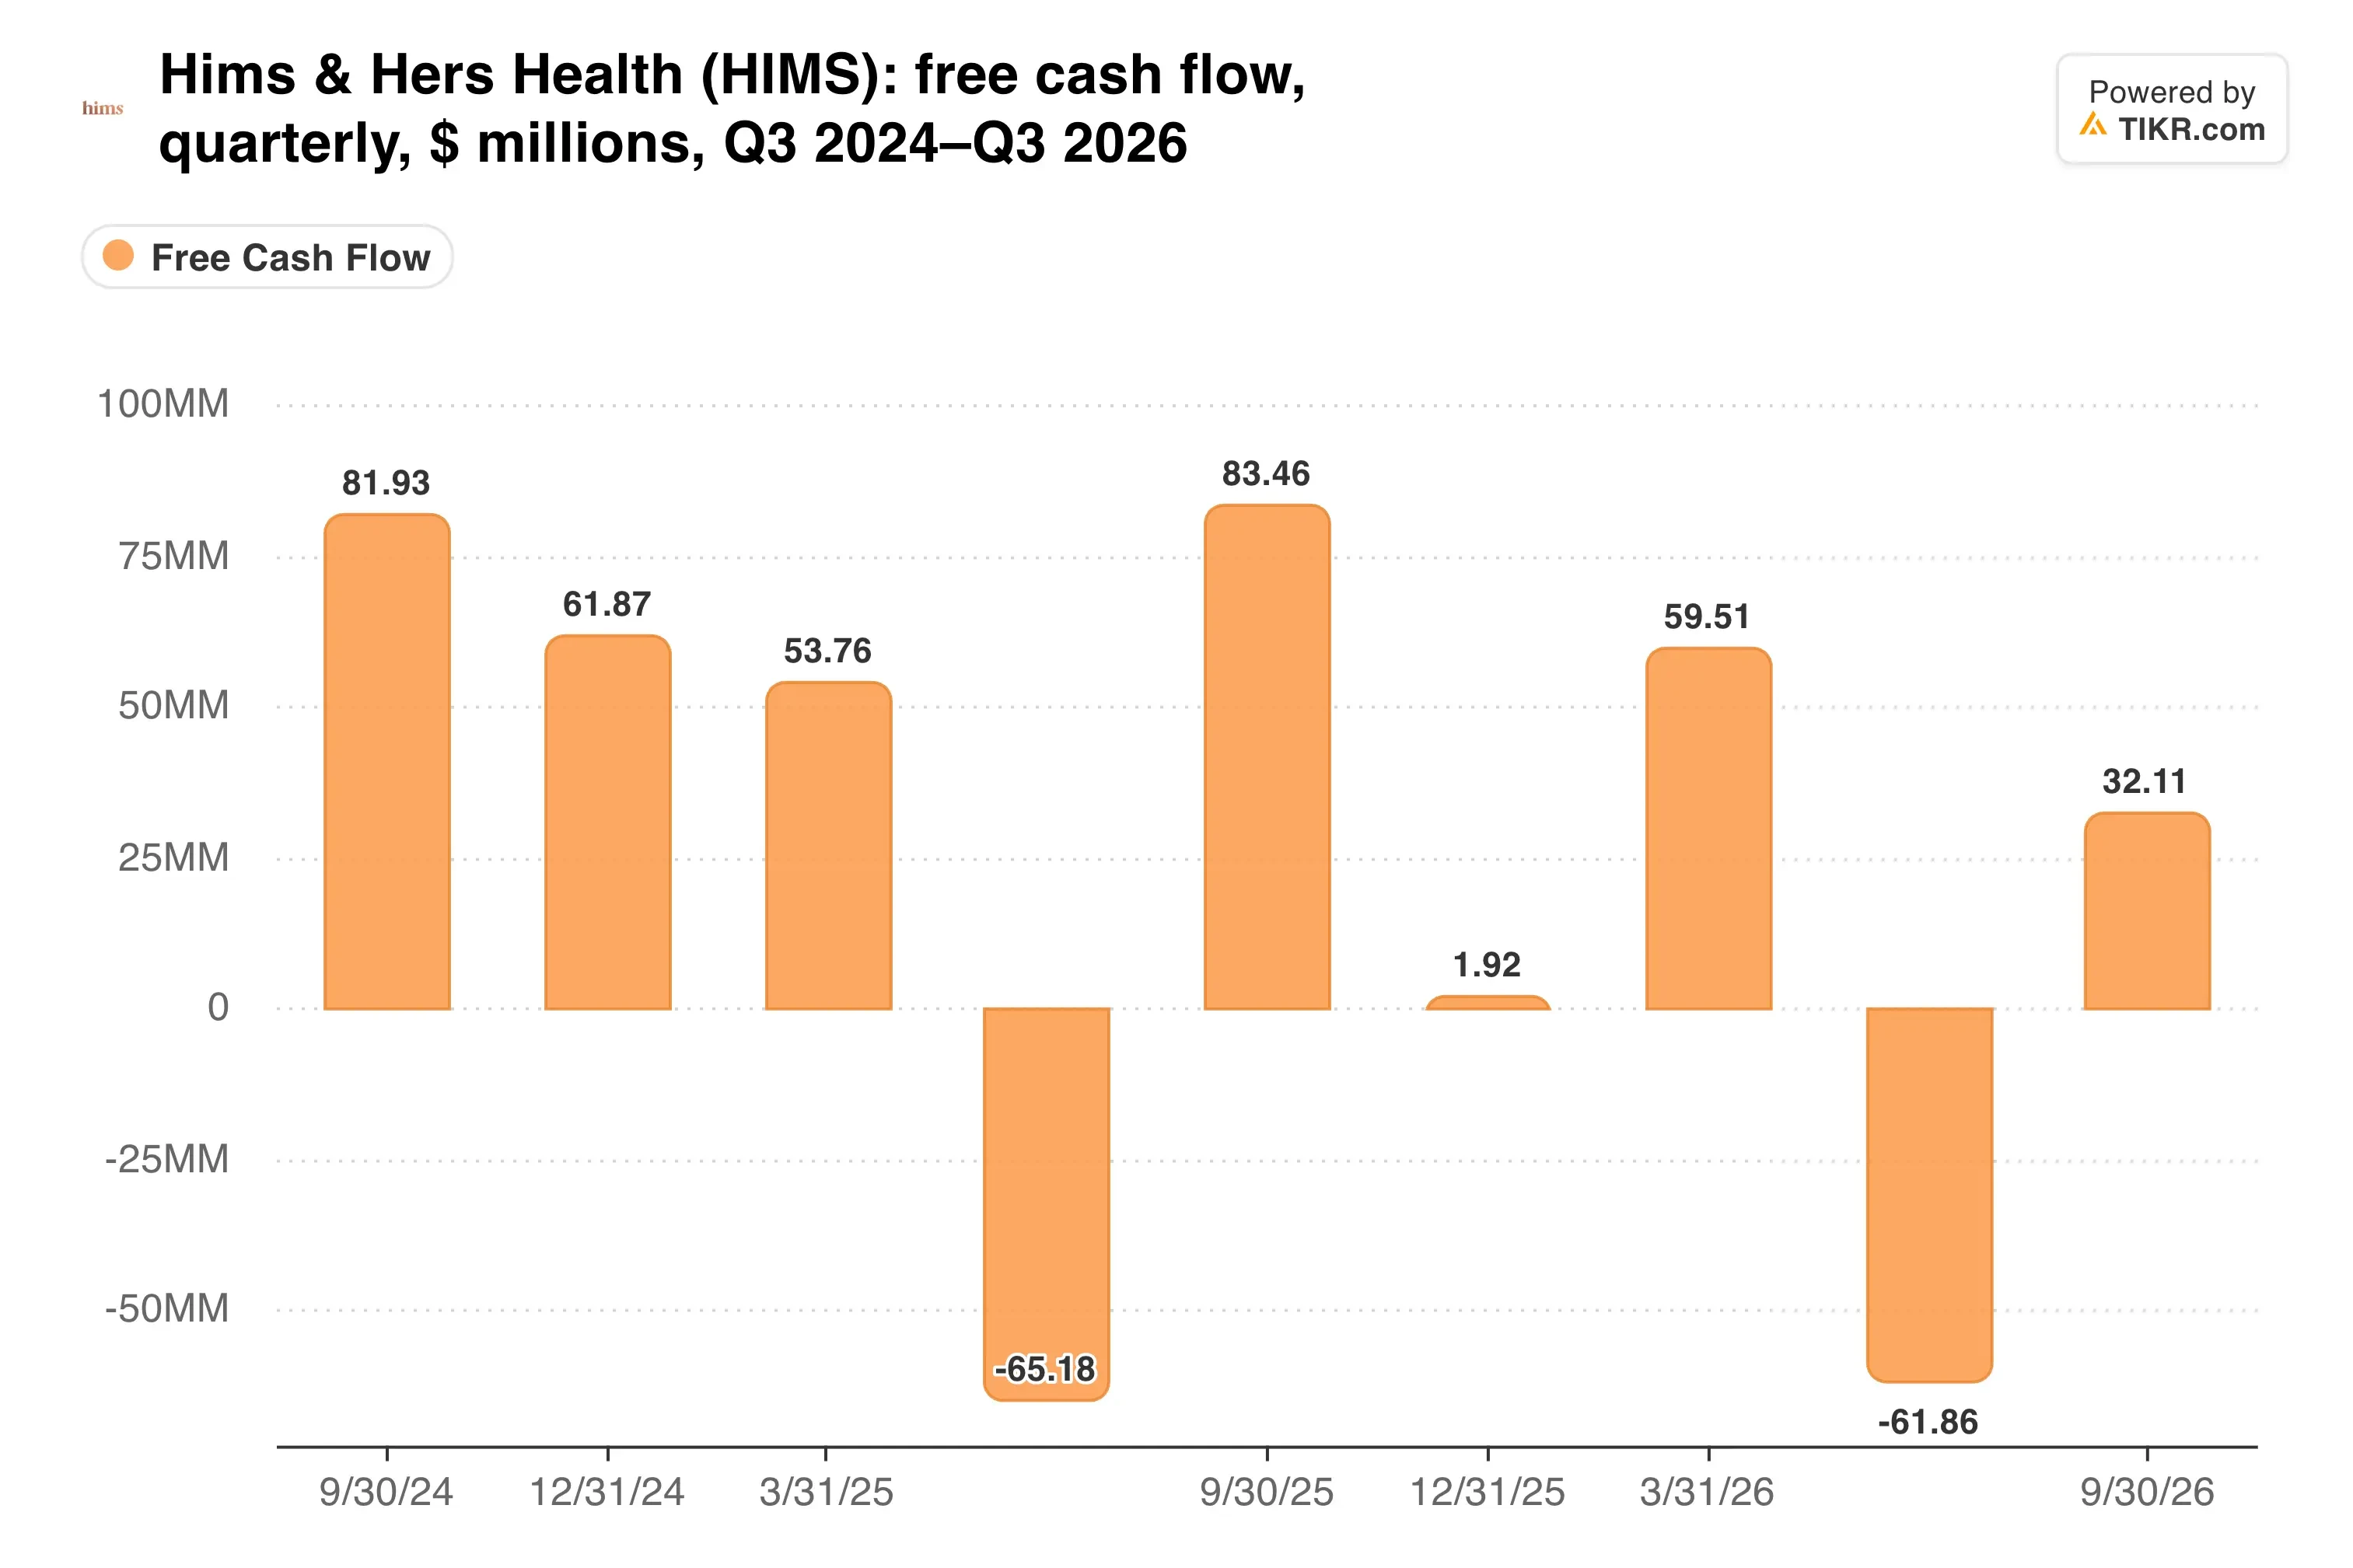
Free cash flow fell to $26.0 million from $79.4 million a year earlier. Hims still targets $6.5 billion in revenue and $1.3 billion in adjusted EBITDA by 2030, so the climb from here is steep.
My take: The revenue engine works, and the Lilly deal closes a gap that used to send patients elsewhere. But every new growth lever so far, from branded drugs to overseas markets, has cost margin. I’d want proof that subscribers come back before paying up for the peptide story.
The fourth-quarter report, expected in late February, is the next checkpoint. It will show whether subscribers grew again with marketing switched back on, and whether gross margin found a floor near 57%.
So what is Hims & Hers stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Hims & Hers could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!