Key Takeaways
- Alphabet’s Class A shares fell 12.6% on Oct. 29, a record drop, and its Class C shares now trade about 18% below Berkshire Hathaway’s June price.
- Alphabet’s trailing P/E of about 15x leans on stake gains. Without them, it’s closer to 26x.
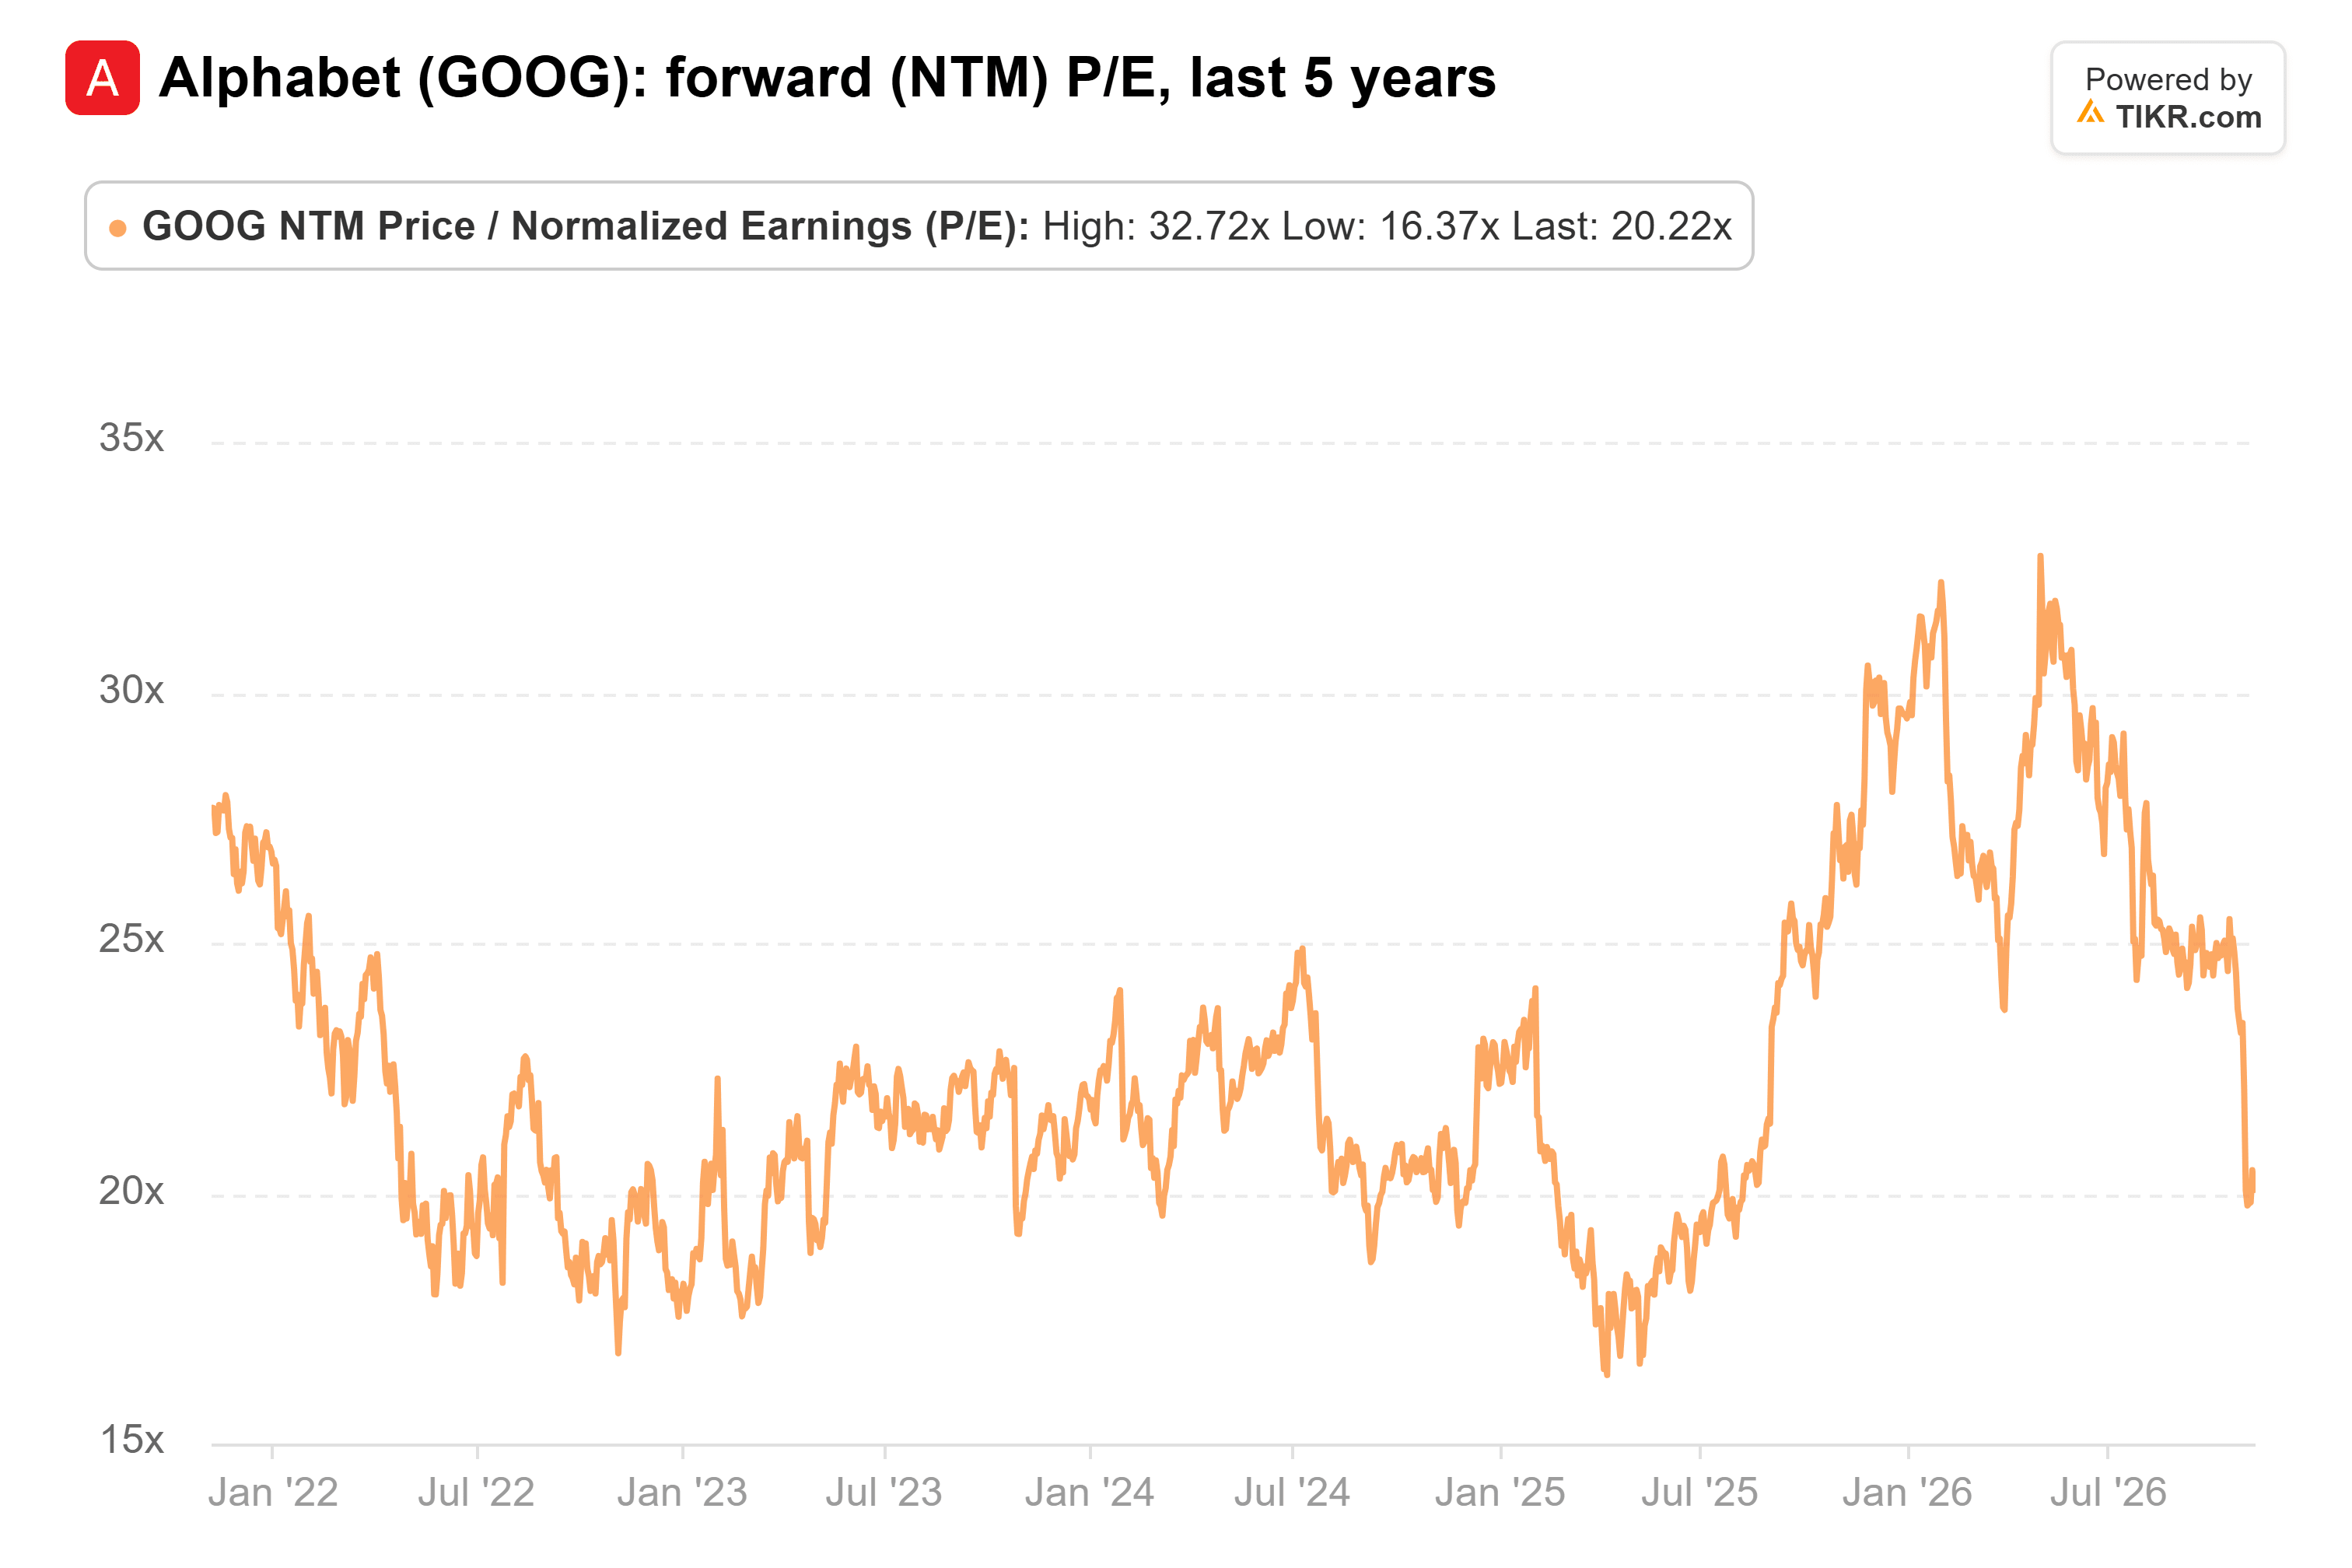
- On analysts’ normalized estimates, the stock trades at 20.2x forward earnings, below its five-year average of 22.5x.
- Free cash flow has turned negative as capex more than doubles, so I’d buy in pieces.
Alphabet (GOOG) had the worst day in its history on Oct. 29, when its Class A shares fell 12.6% after a third-quarter report that narrowly missed revenue estimates and showed negative free cash flow. At $283.93 on Nov. 6, the Class C shares sat about 18% below the $348.20 a share Berkshire Hathaway (BRK-B) paid in June in a $10 billion private placement.
One r/ValueInvesting post put the question bluntly: “Google now below Buffett’s price. Are you buying?”
Below Berkshire’s June Price, Not Its First
Berkshire’s first buy came much cheaper. It held 17.85 million Alphabet shares at the end of the third quarter of 2025, worth $4.34 billion, or about $243 a share.
The June placement is the cleanest price on record ($351.81 for Class A, $348.20 for Class C), since 13F filings show only what Berkshire held, not what it paid. At June 30, it held about 106 million shares across both classes, worth about $30 billion at Nov. 6 prices.
Berkshire can afford years of being early, though. What matters is what Alphabet earns, and its headline earnings include a lot of money the business didn’t make.
TIKR Tracks 58 Analysts on Alphabet. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alphabet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alphabet’s Analyst Ratings
Alphabet’s Earnings Are Padded by Its Stakes
Scott Galloway called Alphabet a buying opportunity at 15x earnings. Alphabet’s investment gains and losses run through net income, but the accounting differs: listed holdings such as SpaceX are marked to market, while private stakes are generally revalued when observable transactions or impairments warrant an adjustment. In the first nine months of 2026, its net gains on equity securities came to $127.3 billion, more than its $121.0 billion of operating income. The second quarter’s $99.0 billion gain supplied $6.26 of its $9.11 in EPS, and the third quarter’s $8.7 billion loss cut EPS by $0.55.
Strip those swings out of the last four quarters and EPS comes to about $11, or nearer 26x. The stakes are real assets, though. Alphabet held $94.1 billion of SpaceX shares at June 30, most of it under sale limits. I’d count them as part of what Alphabet owns and price the stock on what the business earns.
At 20x Forward, Alphabet Is Cheaper Than Usual
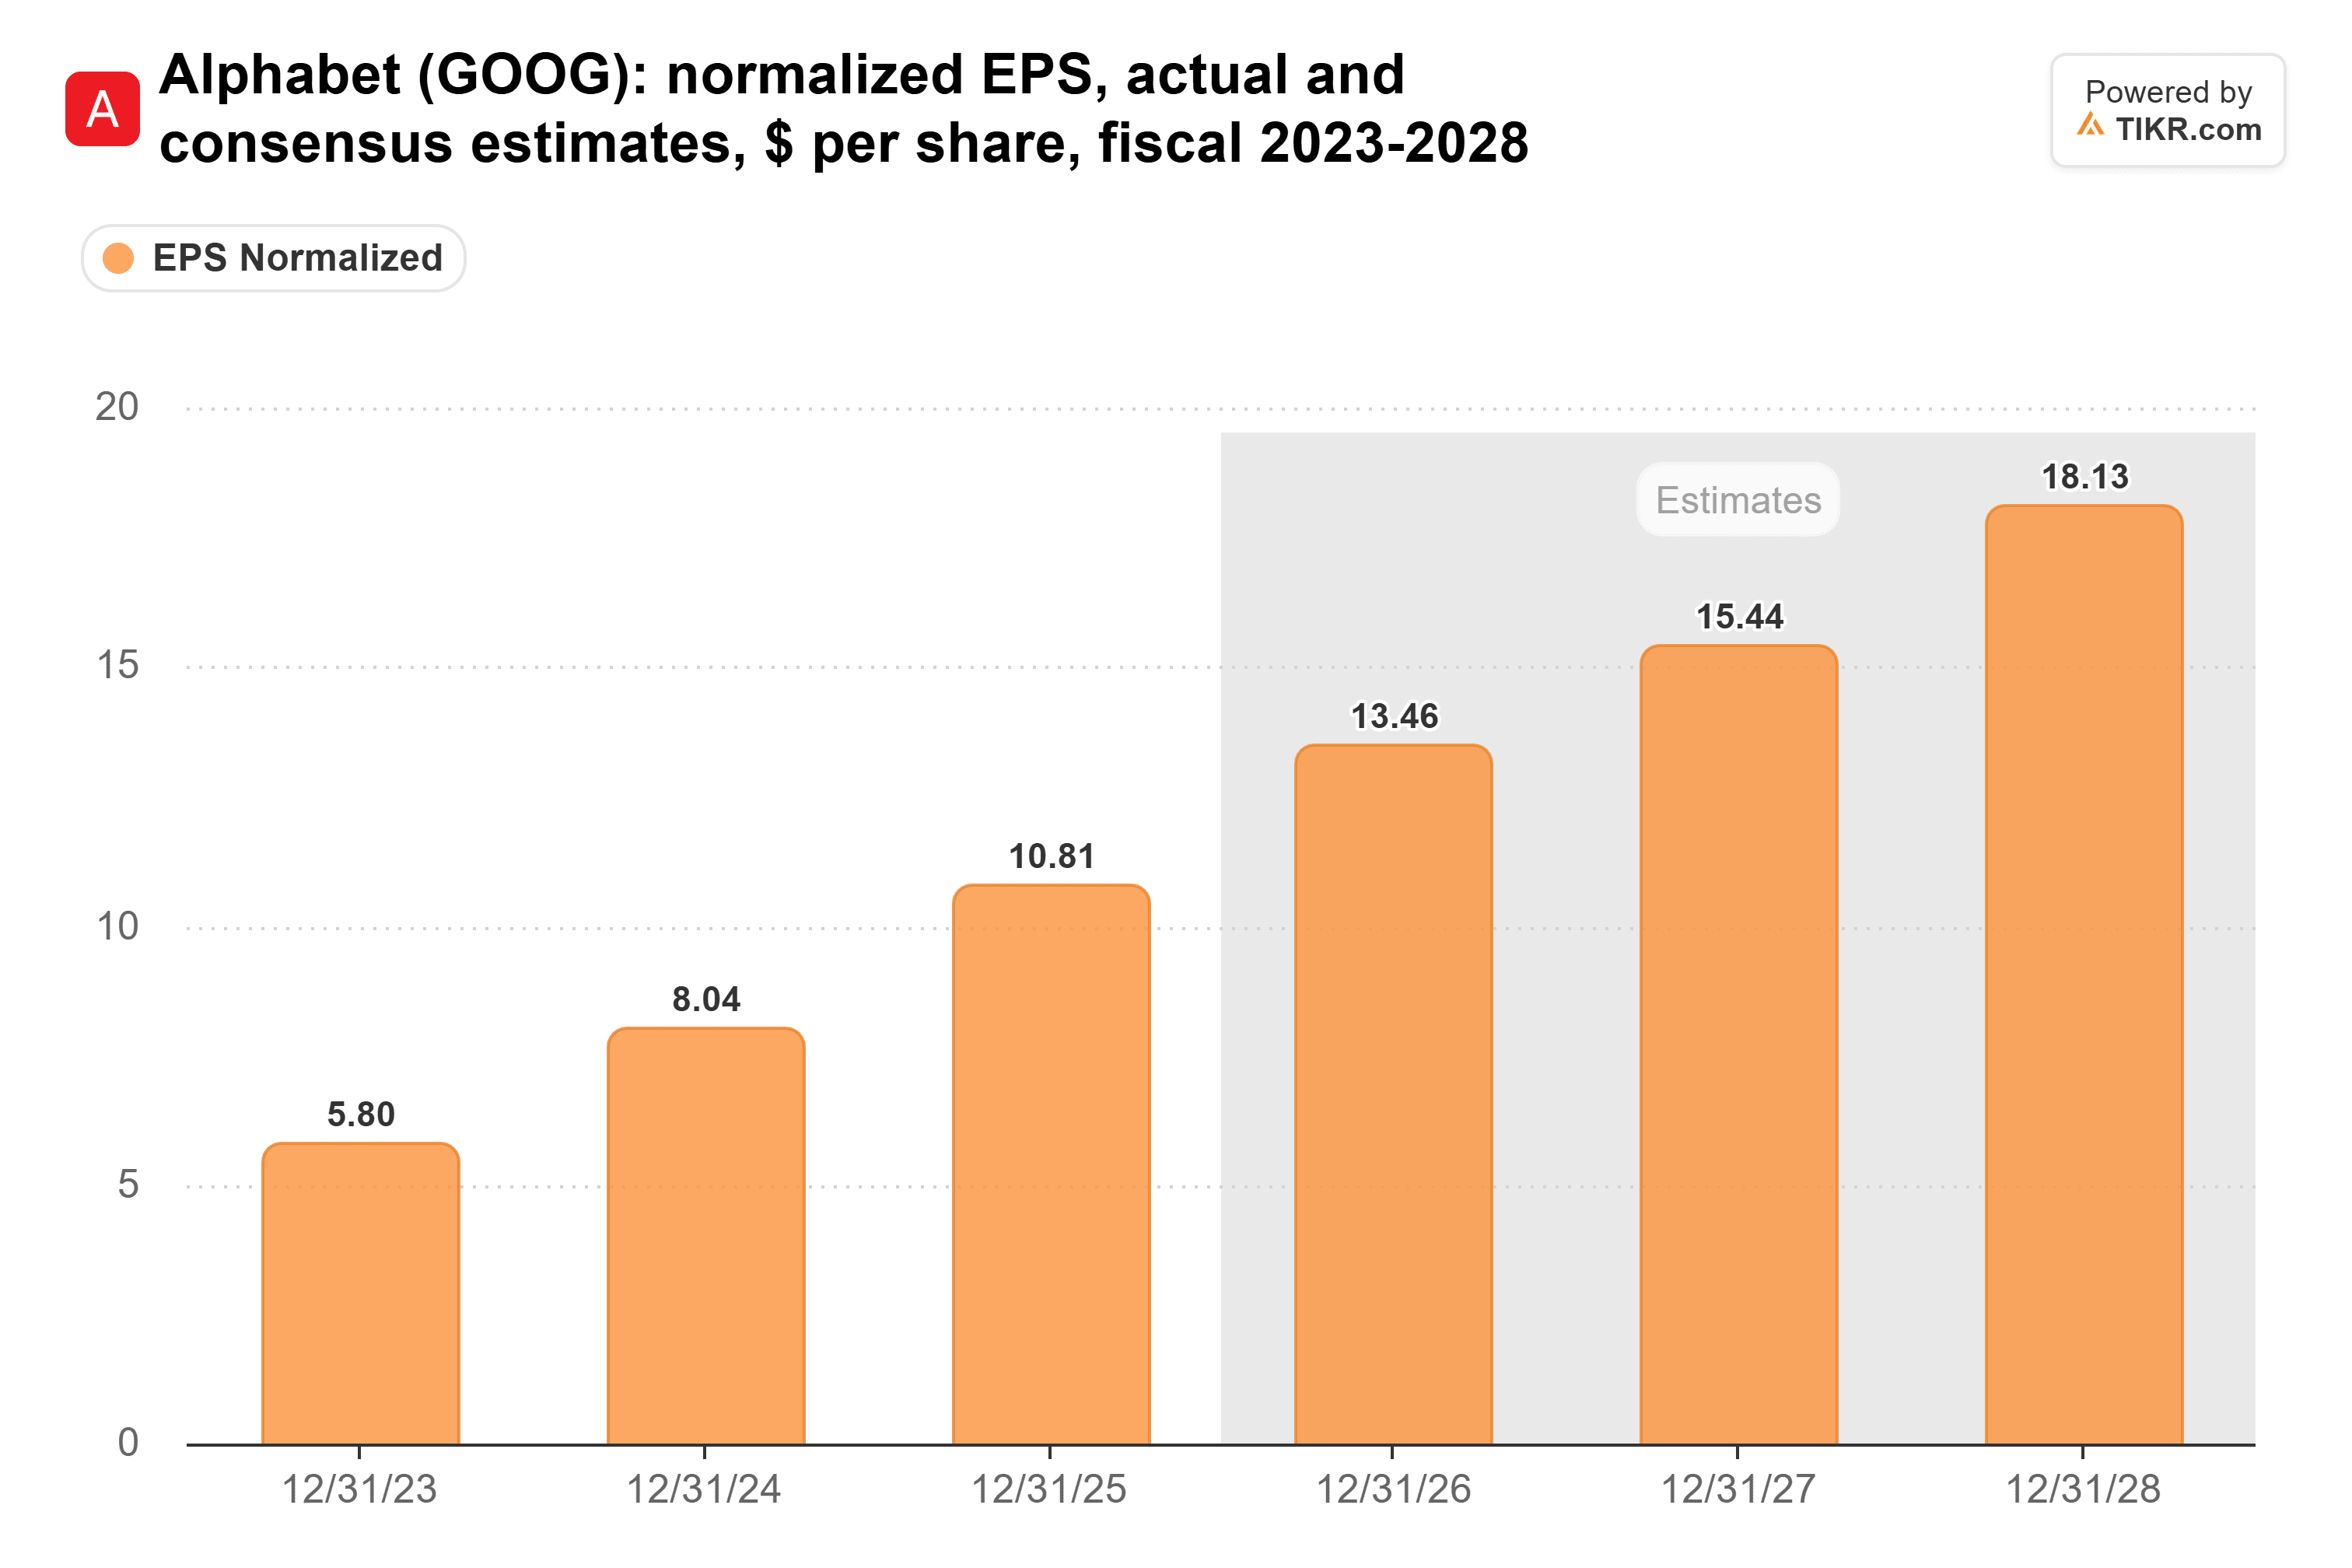
Analysts don’t forecast stake gains, so their normalized EPS estimates follow the business, rising from $13.46 in 2026 to $18.13 by 2028:
On those estimates, Alphabet traded at 20.2x forward earnings on Nov. 6, below its five-year average of 22.5x and well off April’s 32.7x peak:
The Cash Is the Real Worry
Alphabet’s free cash flow stayed between $60.0 billion and $73.3 billion a year from 2021 to 2025:
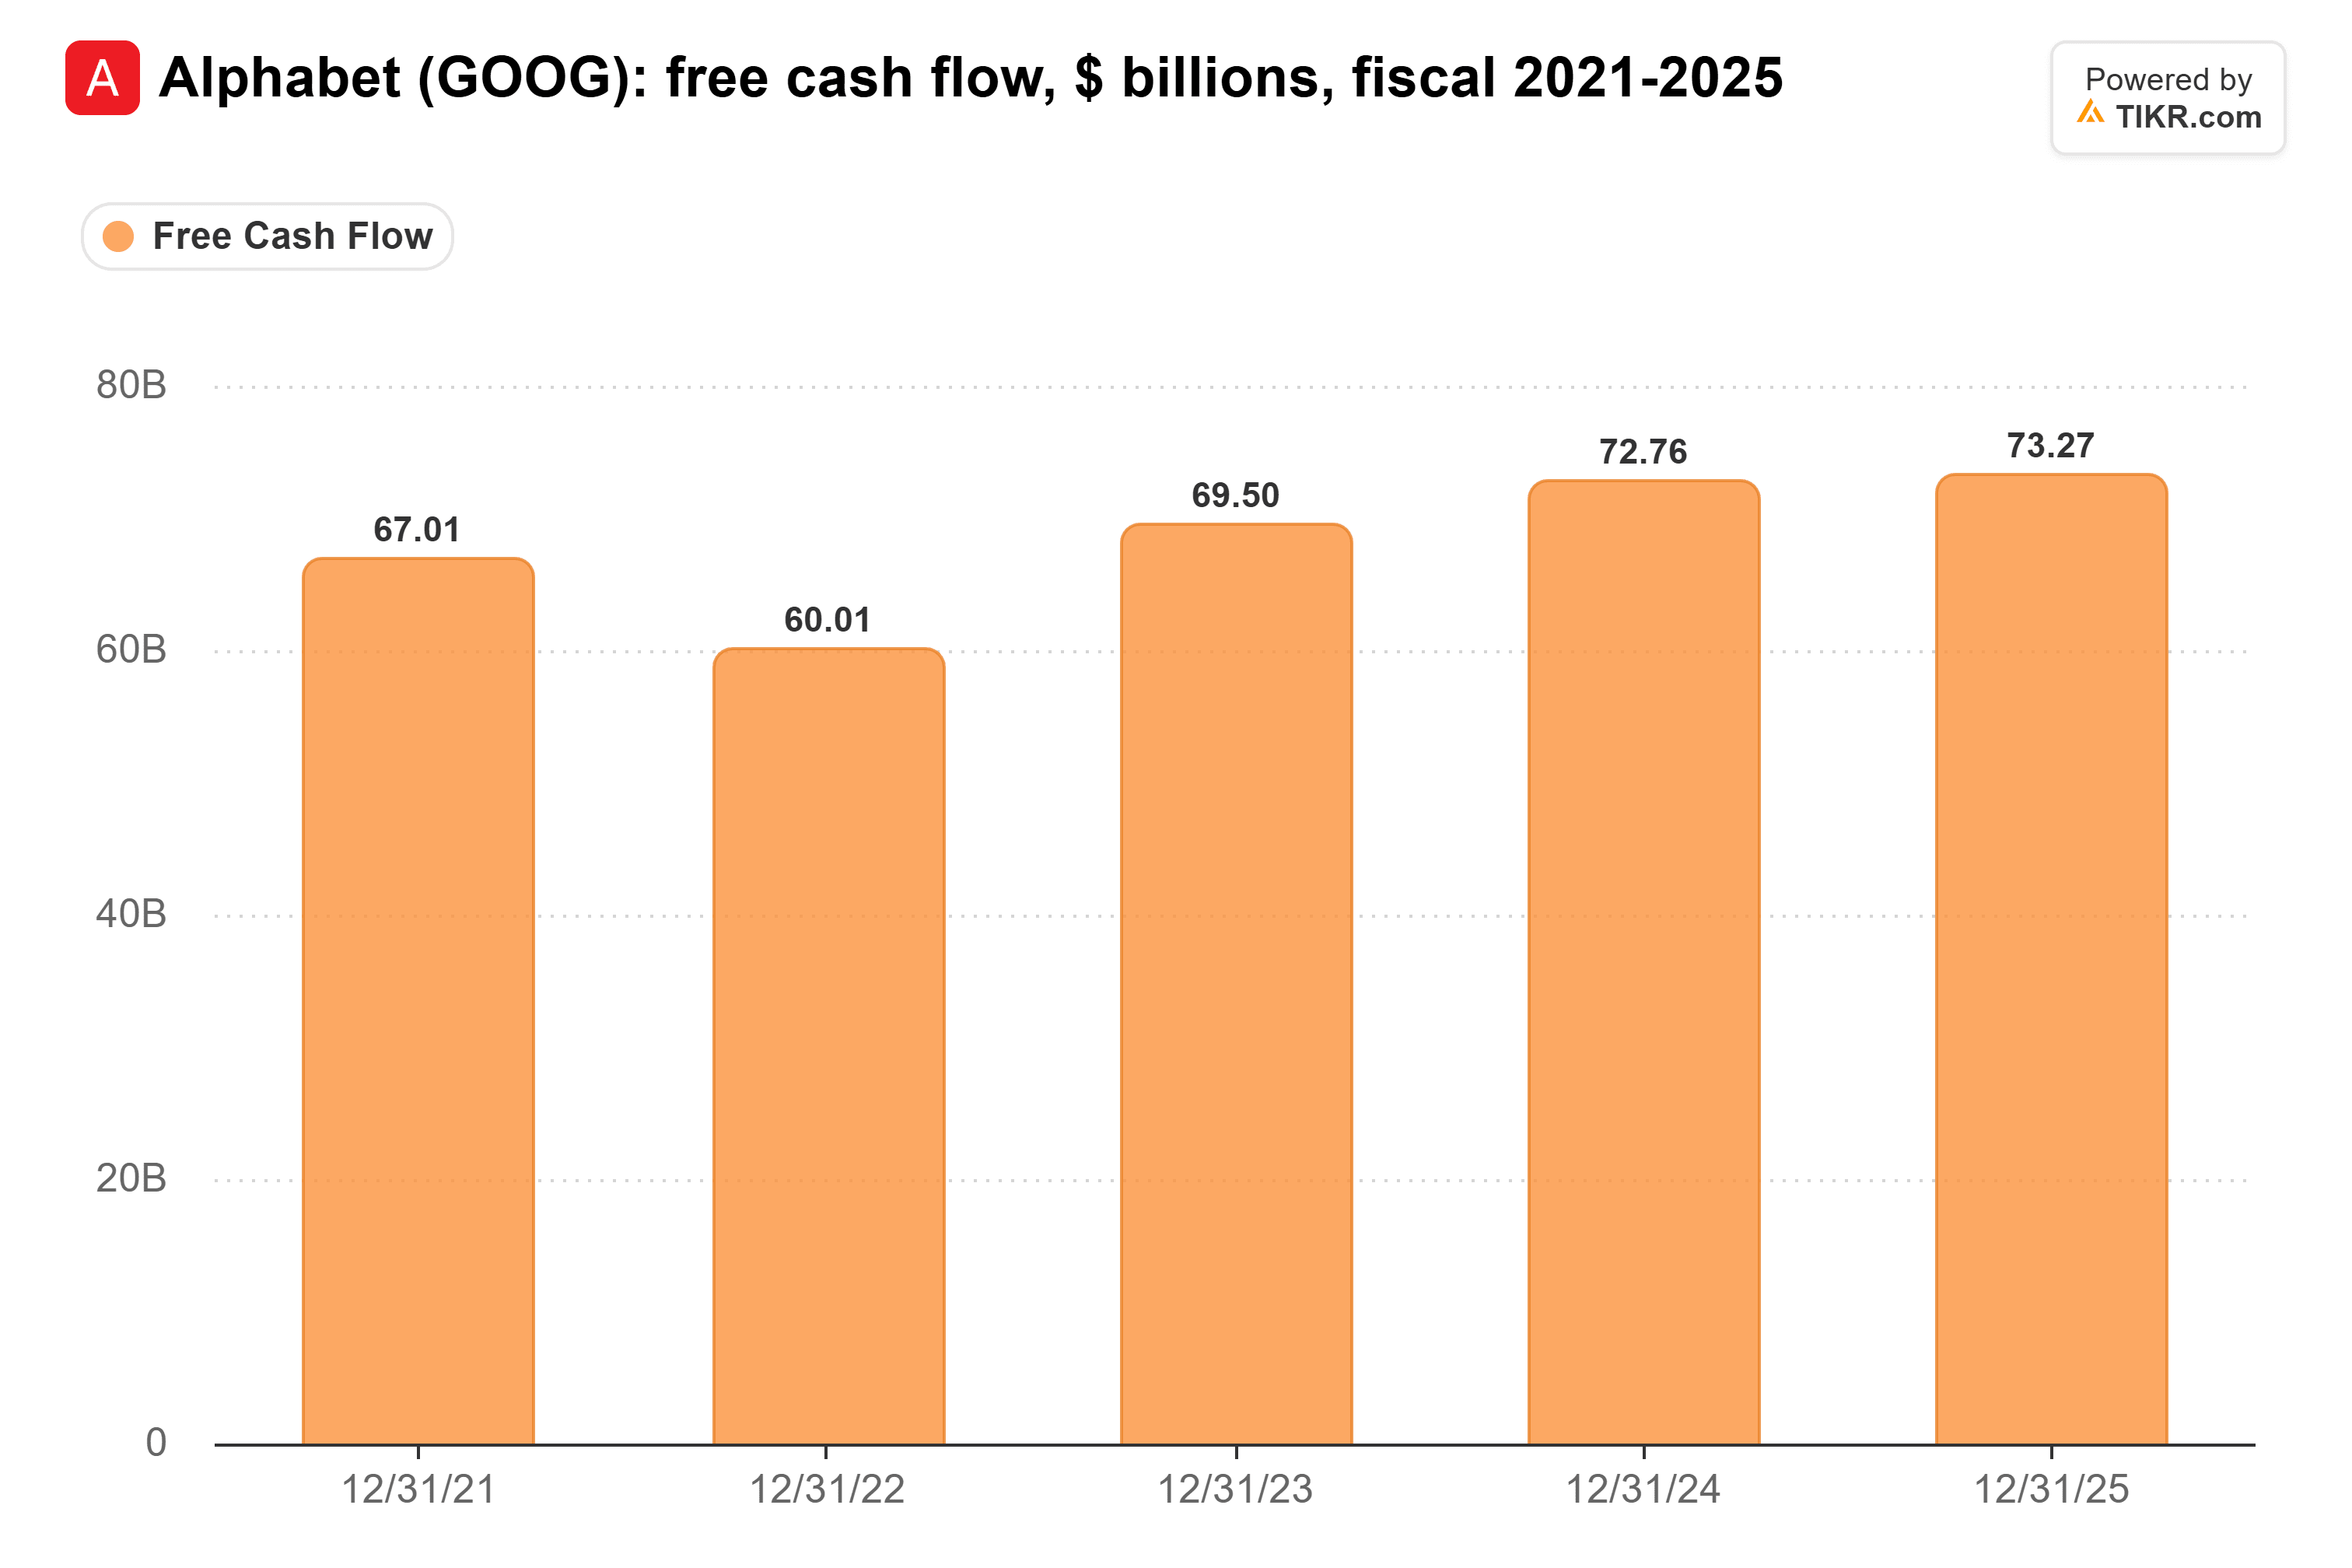
In the 12 months to Sept. 30, it was $19.7 billion. Alphabet kept its 2026 capex guidance at $195 billion to $205 billion, against $91.4 billion in 2025, and expects a significant increase in 2027. Analysts now see free cash flow of negative $18.0 billion in 2026 and negative $41.8 billion in 2027. Alphabet hasn’t bought back a share this year, and it sold $12.4 billion of new stock in the third quarter alone.
Why I’d Buy Alphabet Stock in Pieces
At 20.2x forward earnings, I only need analysts’ estimates to hold up roughly as forecast, so I’d start buying Alphabet here, a little at a time. The risk is the spending. Consensus depreciation climbs from $21.1 billion in 2025 to $77.9 billion in 2028, and if revenue lags, the estimates fall with it. The fourth-quarter report, which Alphabet usually releases in early February, should put a number on 2027 capex.
So What Is Alphabet Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alphabet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!