Key Takeaways
- FormFactor fell 12% today despite record third-quarter revenue of $280.5 million and an outlook above estimates.
- The outlook implies flat revenue and a lower gross margin as its existing factory nears its limits.
- Teradyne also guided flat, and Onto Innovation’s early-November report is the next read on advanced packaging.
- The stock’s forward P/E was already below its five-year average before today’s drop.
FormFactor (FORM) sank 12% today, even after record revenue and an outlook above estimates.
The catch: next quarter looks a lot like this one. Test partner Teradyne (TER) guided flat this week too, while advanced-packaging peer Onto Innovation (ONTO) has yet to report.
A record quarter, then a pause
FormFactor beat after Wednesday’s close: revenue of $280.5 million, up 38% from a year ago, against $270.5 million expected.
But its $285 million revenue guide is only about 2% above the third quarter. And gross margin, which rose for four straight quarters through June, is set to fall:
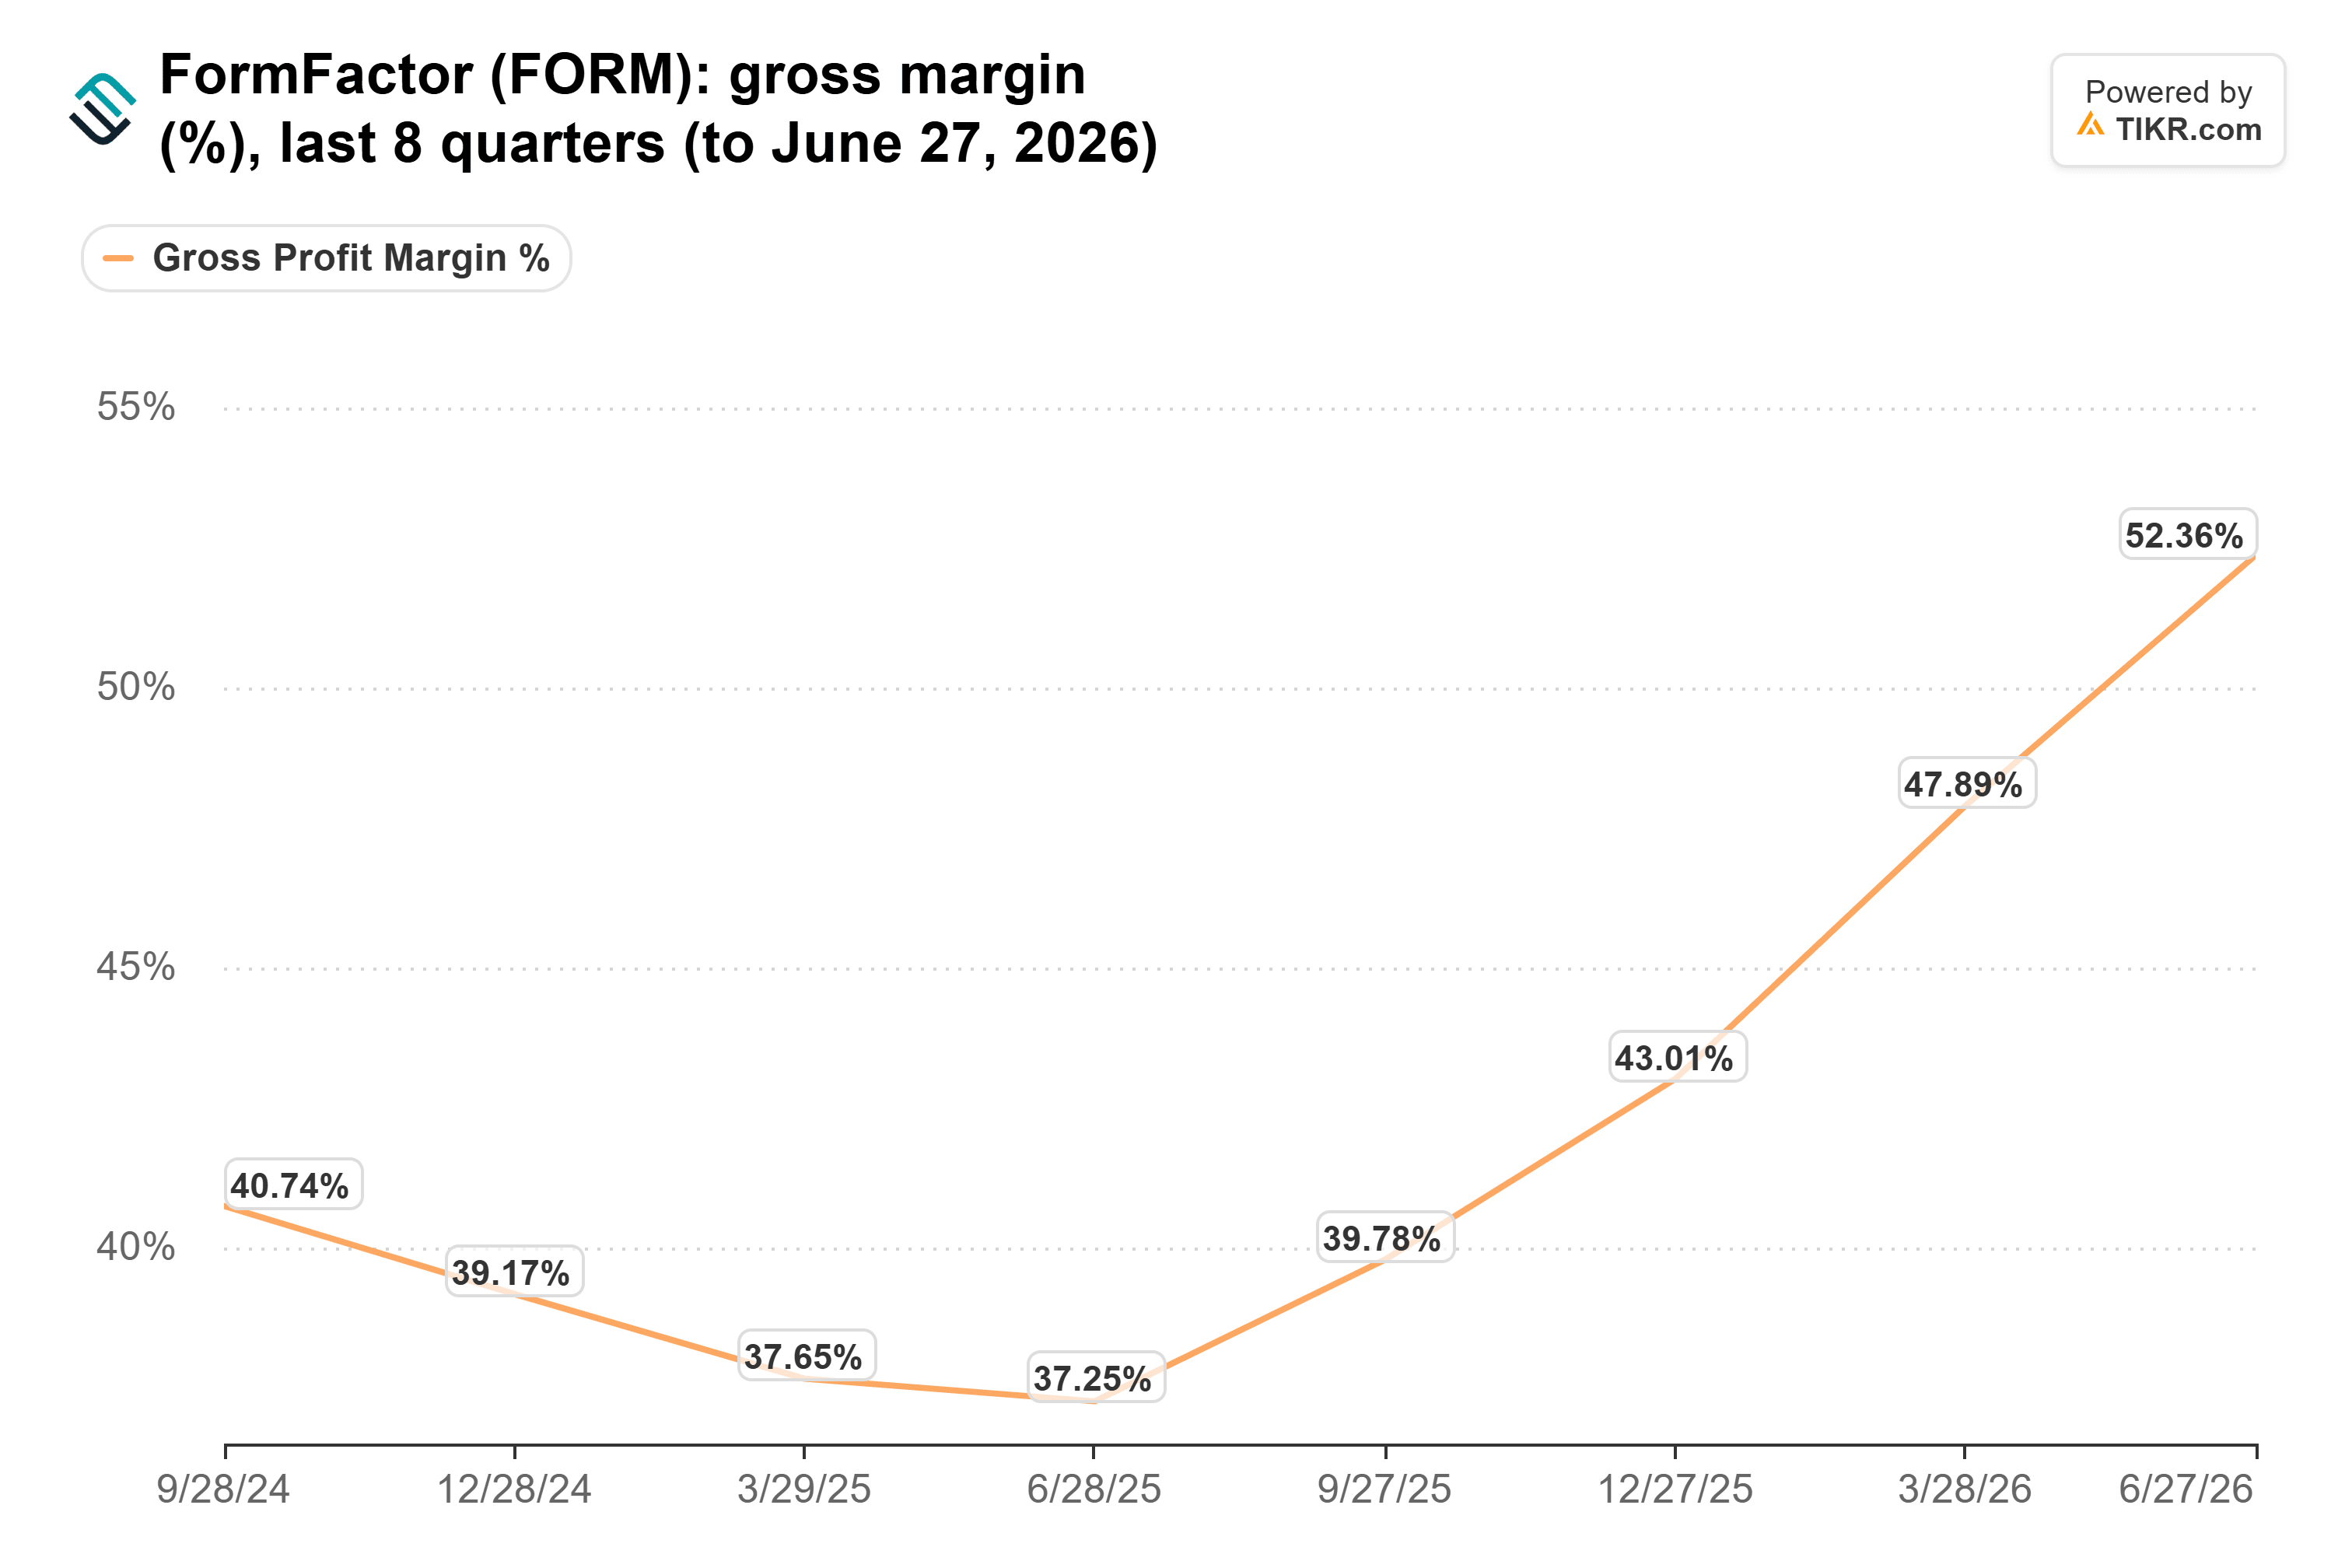
The third quarter pushed it to an adjusted 56.5%. The guide of 54% gives back 2.5 percentage points.
The factory is full
CEO Mike Slessor explained: “While the productivity gains from our existing manufacturing footprint are moderating as we approach its capacity limits, we are bringing our new Farmers Branch factory online.”
Farmers Branch just shipped its first production unit, and management sees it reaching $400 million of annual capacity by the end of next year.
Analysts expect revenue to top $1 billion this year, then grow a slower 19% in 2027:
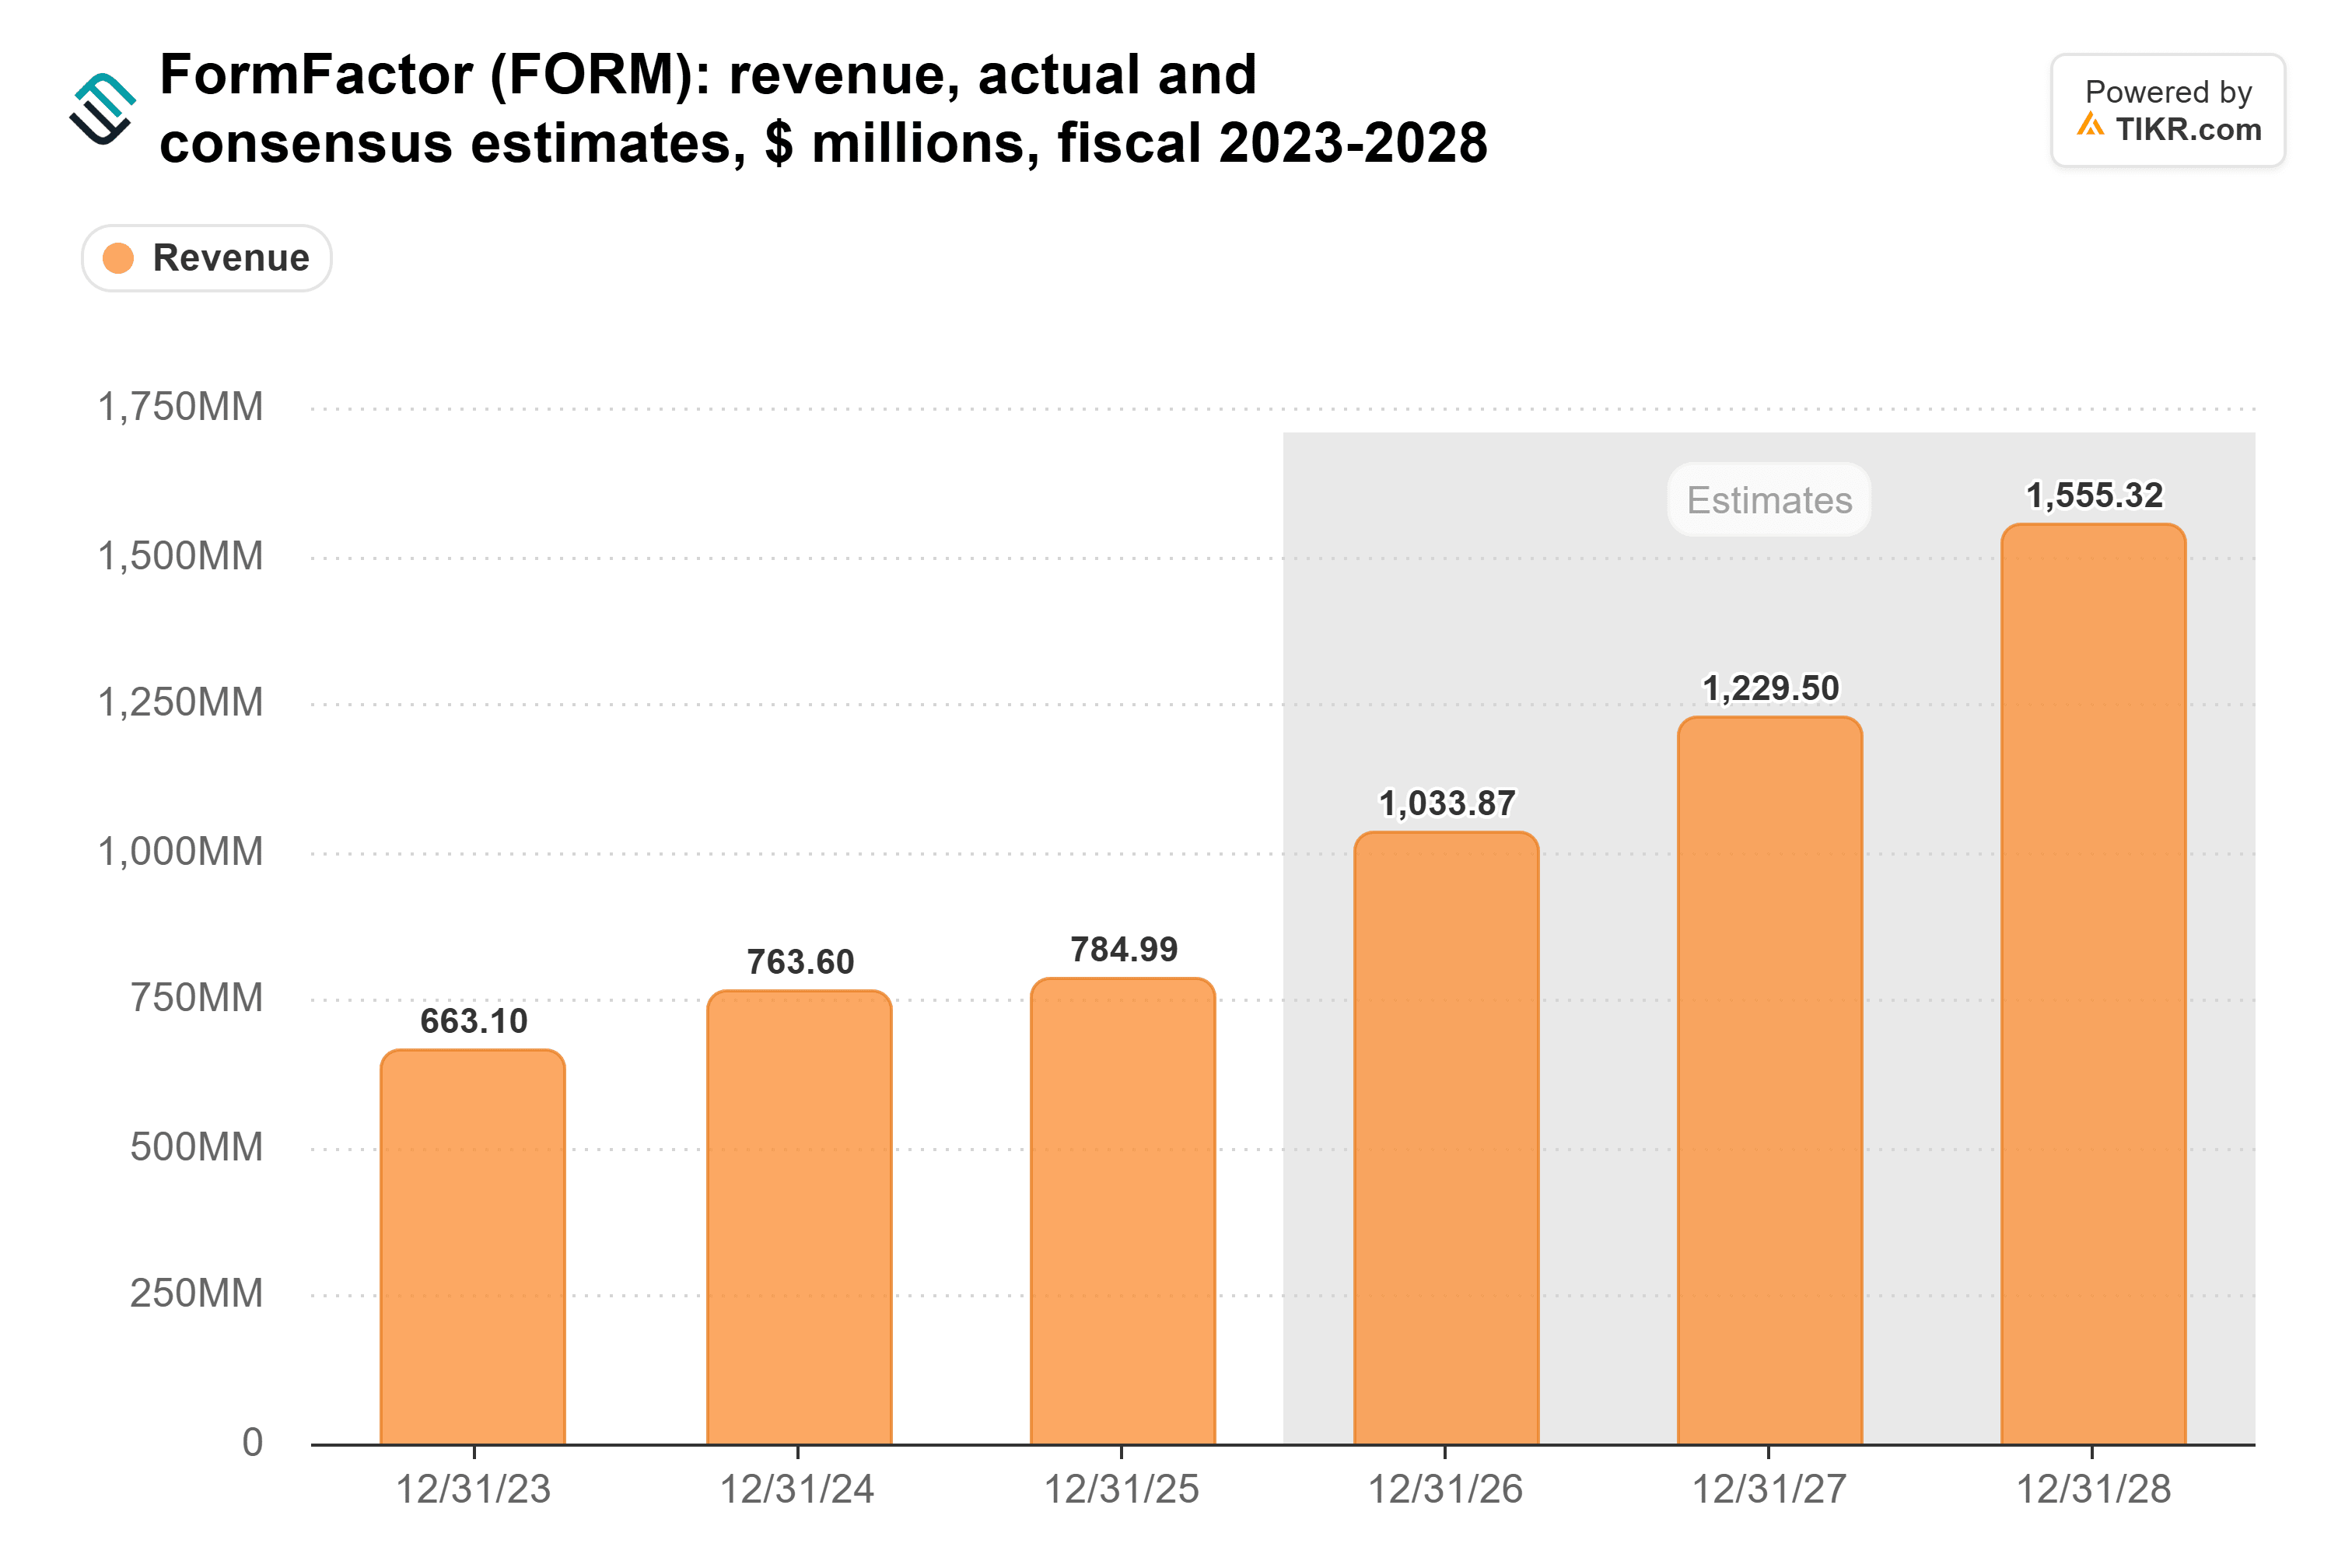
Nothing here argues for cutting those estimates, since demand isn’t the constraint.
TIKR tracks 10 analysts on FormFactor. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on FormFactor, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See FormFactor’s Analyst Ratings
Teradyne and Onto point different ways
Teradyne’s third-quarter revenue jumped 70% from a year ago to $1.31 billion. But revenue dipped from the second quarter, its fourth-quarter guide is flat again, and its release cites no capacity squeeze. So how much of FormFactor’s pause is really the factory?
Onto Innovation points the other way. It posted record revenue of $343 million in its second quarter and a backlog above $1 billion. Its early-November report, against a $380 million to $400 million guide, will test whether this is FormFactor’s own bottleneck.
The multiple was already reasonable
FormFactor’s forward P/E was 31x at Wednesday’s close, below its five-year average of 35x and far from April’s 84x peak:
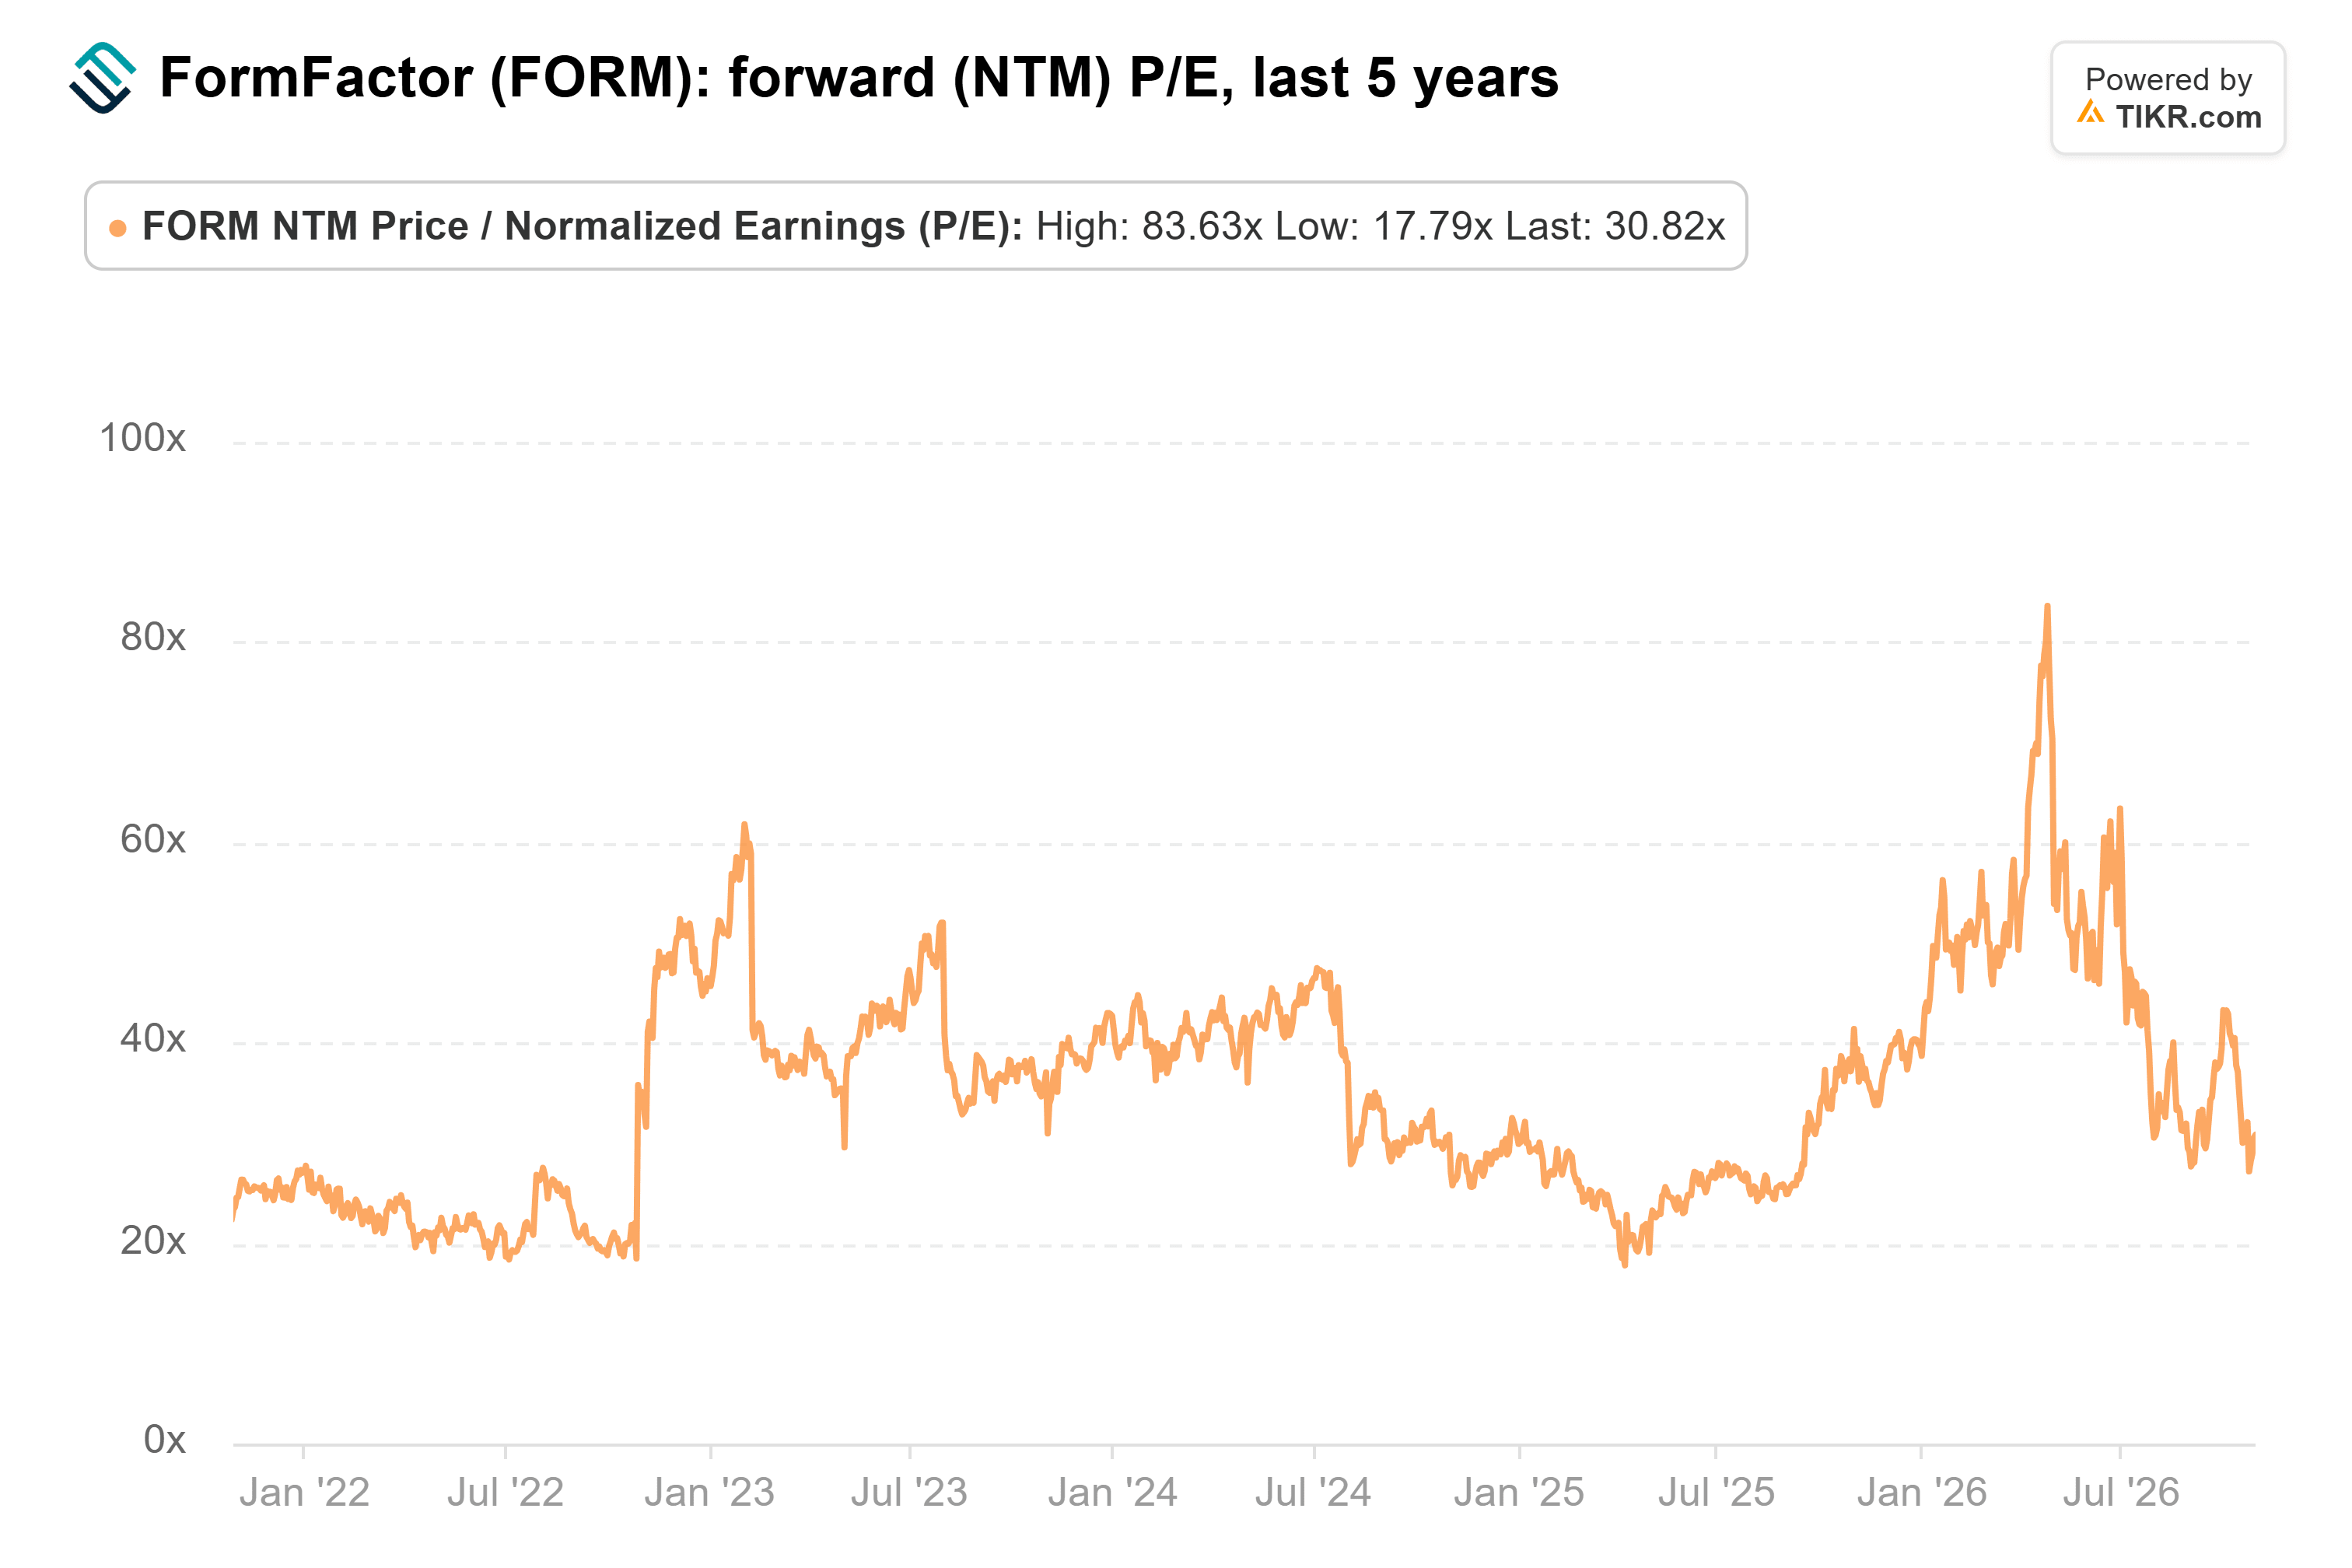
My take: The demand is there, and the fix is already shipping. At today’s price, about 27x forward earnings, waiting out a few flat quarters looks reasonable to me.
Of course, new factories don’t always ramp on schedule. Watch whether gross margin holds near 54% when FormFactor reports early next year.
So what is FormFactor stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what FormFactor could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!