Key Takeaways
- Bandwidth shares fell 13% as in-line full-year guidance overshadowed a third-quarter beat.
- The guidance implies slower fourth-quarter growth after a sharp run-up in the stock’s valuation.
- CEO David Morken says AI agents will drive more voice and text traffic, and a new Salesforce deal backs him up.
- Rival Twilio makes the same AI-agent pitch, so its next outlook faces the same test.
Bandwidth (BAND) posted a record quarter this morning and still sank 13%, as its full-year guidance only matched expectations.
Its growth case rests on AI agents, the same pitch rival Twilio (TWLO) makes. And this quarter, Salesforce (CRM) named Bandwidth its first certified international carrier for its native Contact Center.
TIKR tracks 7 analysts on Bandwidth. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bandwidth, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bandwidth’s Analyst Ratings
The beat wasn’t enough
Third-quarter revenue rose 22% to a record $234 million, just above the $233.15 million analysts expected.
But 2026 guidance of $905 million to $910 million in revenue and $1.73 to $1.79 in adjusted EPS lands right on consensus of $905.7 million and $1.75. Analysts already expected that much for 2026, and a far smaller gain for 2027:

Nothing in that range moves the 2026 estimates. It also implies fourth-quarter growth of roughly 17% to 19%, down from the third quarter’s 22%.
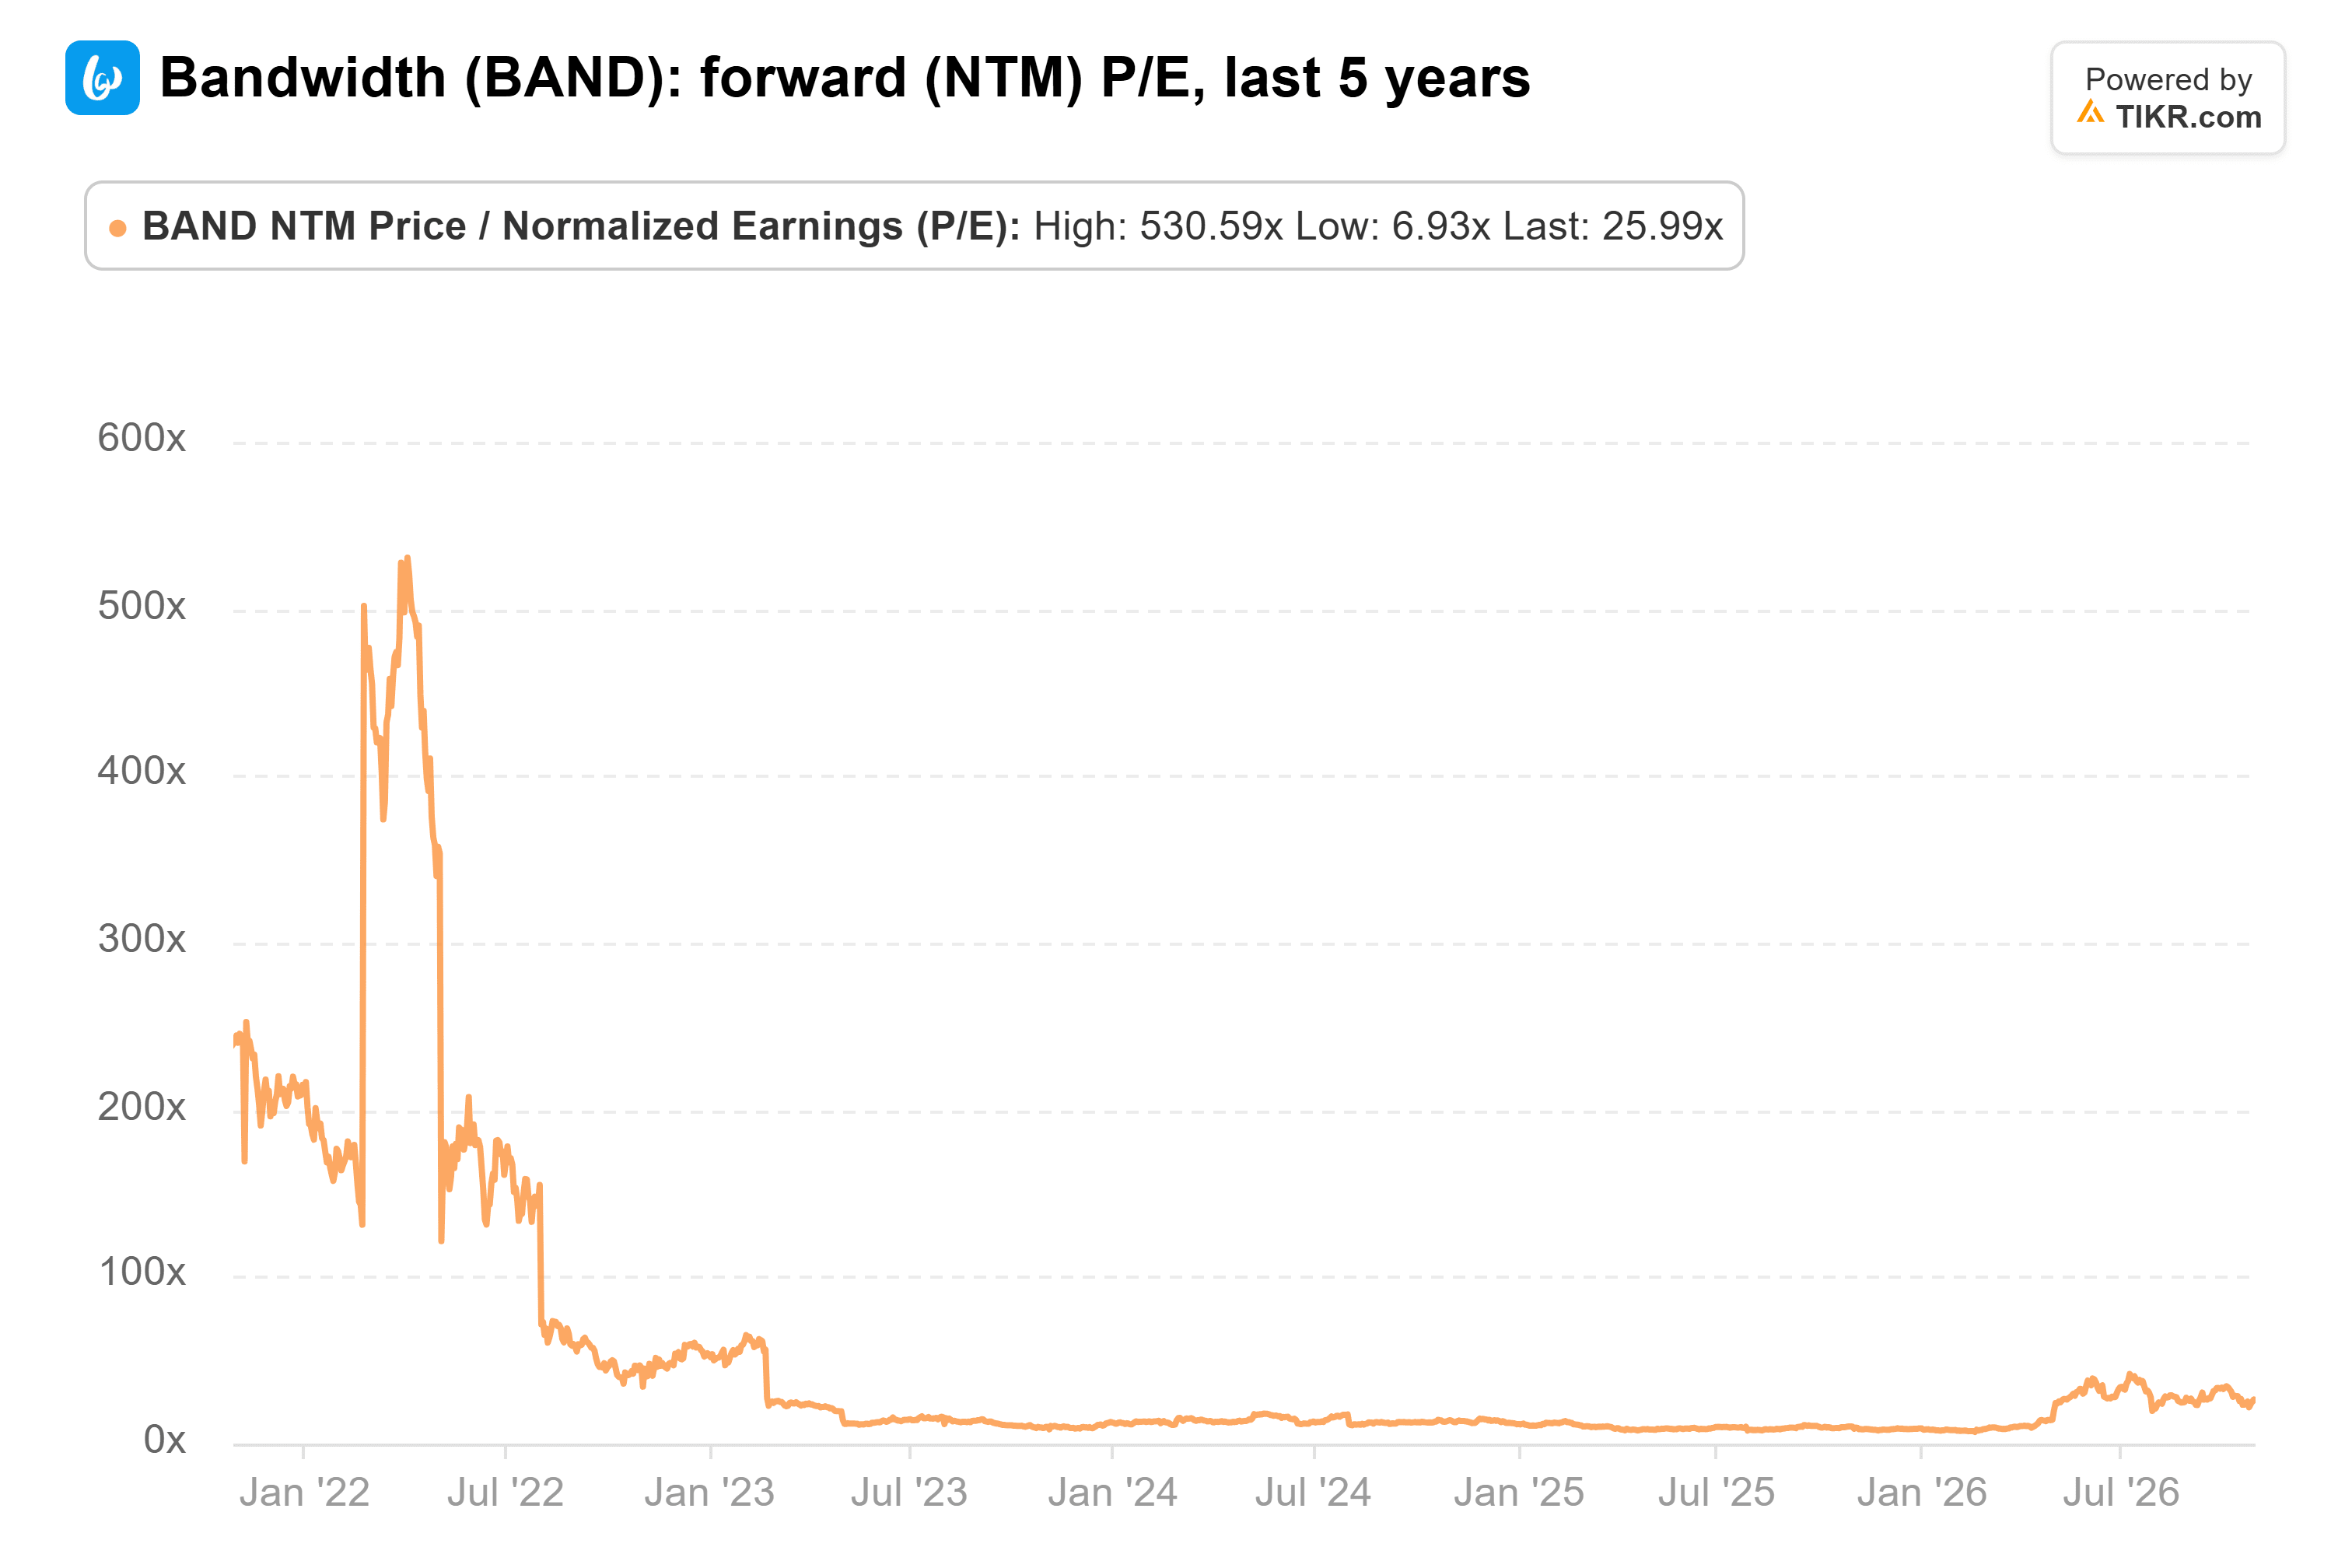
That’s a tough sell for a stock that traded at 26x forward earnings before the report, up from 6.9x in February:
Agents need phone lines
CEO David Morken said AI agents “will need to reach people by voice and text.” He added that Bandwidth “will continue to scale as SI generates more conversations between people and agents.” (SI is Bandwidth’s term for super intelligence.)
The deal takes Bandwidth’s network into Salesforce’s contact center in more than 25 countries. For Salesforce, it’s one piece of a bigger push: Agentforce annual recurring revenue passed $1.5 billion as of July 31. Salesforce’s early-December report should show how much of that agent work runs over the phone.
In August, Twilio raised its 2026 organic growth outlook to 13% to 13.5%, from 9.5% to 10.5%, and it trades at 41x forward earnings. If in-line guidance did this to Bandwidth, Twilio’s outlook faces a higher bar in its third-quarter report.
The 2027 number is the one to watch
My take: Nothing here says Bandwidth’s business is breaking. Free cash flow jumped to $33 million from $13 million a year earlier. The stock had just priced in more than an in-line year.
Of course, Bandwidth’s 2027 outlook calls for double-digit growth in Cloud Communications revenue. If that lifts the Street’s 2027 estimates, today’s drop could look like an overreaction.
So what is Bandwidth stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bandwidth could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!