Key Takeaways
- Walmart beat third-quarter estimates and raised its outlook again, with grocery growing at a mid-single-digit rate.
- Walmart accounted for 22% of General Mills’ fiscal 2026 net sales.
- General Mills’ North America Retail organic sales fell 3% in fiscal 2026 and again last quarter, despite price cuts.
- General Mills reports Dec. 17 on the quarter when it began lapping its price cuts.
Walmart (WMT) beat revenue and earnings estimates for its third quarter on Nov. 19 and raised its full-year outlook for the second time this fiscal year. One supplier with a lot riding on that traffic is General Mills (GIS).
Walmart accounted for 22% of General Mills’ net sales in fiscal 2026, the year ended May 31, and 31% of North America Retail, the segment that earned 68.2% of its segment operating profit, per its 10-K. Walmart was also 22% of Campbell’s(CPB) fiscal 2026 sales. Conagra Brands (CAG) just posted a 5.4% volume drop in Grocery & Snacks, and J.M. Smucker (SJM) reports on Nov. 24.
Walmart’s Grocery Aisles Are Busy
Revenue rose 5.2% to $188.8 billion, ahead of the $187.2 billion in Bloomberg’s consensus. U.S. same-store sales rose 2.9%, in line with forecasts, and grocery grew at a mid-single-digit rate on share gains and higher unit volumes. Walmart now expects adjusted EPS of $2.84 to $2.89, up from $2.80 to $2.87.
General Mills Needs the Traffic
General Mills cut base prices across about two-thirds of its North America Retail portfolio, and the segment’s organic net sales still fell 3% in fiscal 2026. They fell another 3% in the quarter to Aug. 30, with volume down 2 points and price/mix down 1. Analysts don’t expect the top line to come back:
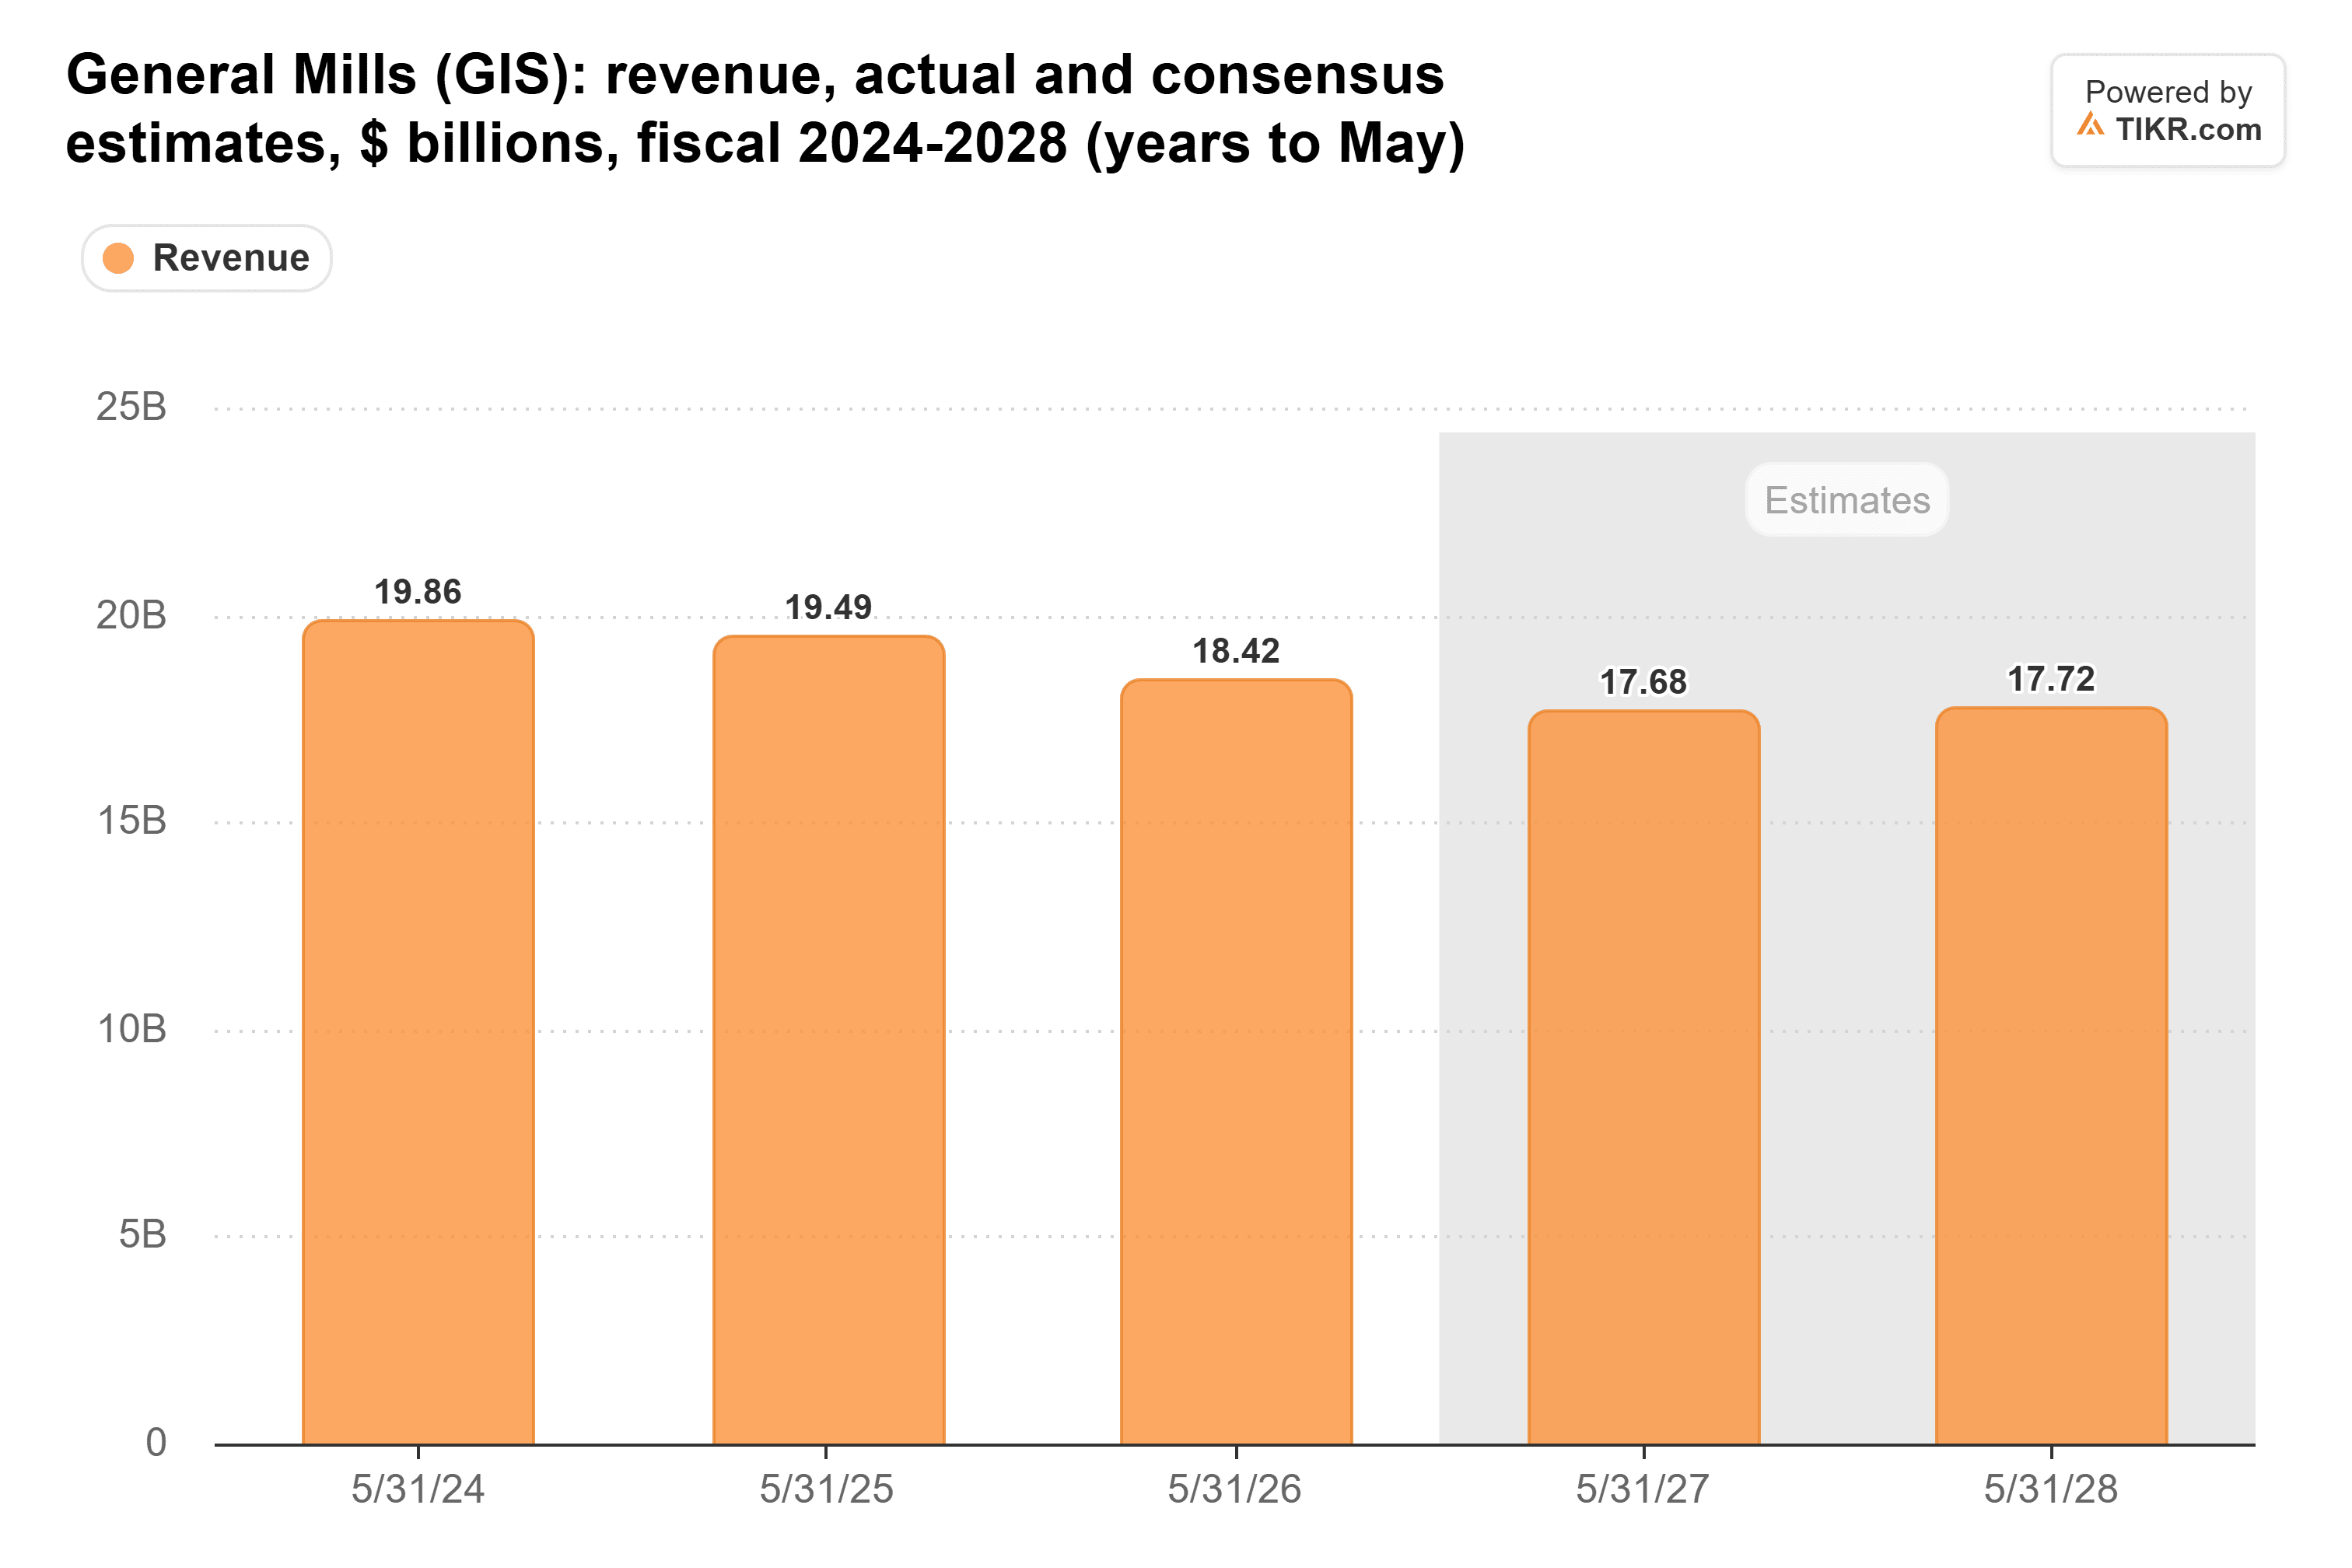
Divestitures, including U.S. yogurt, explain part of the slide from $19.9 billion in fiscal 2024. Still, analysts see a flat $17.7 billion in fiscal 2027 and 2028, set before Walmart reported.
Its biggest customer keeps growing. Every quarter here beat the same quarter a year earlier:
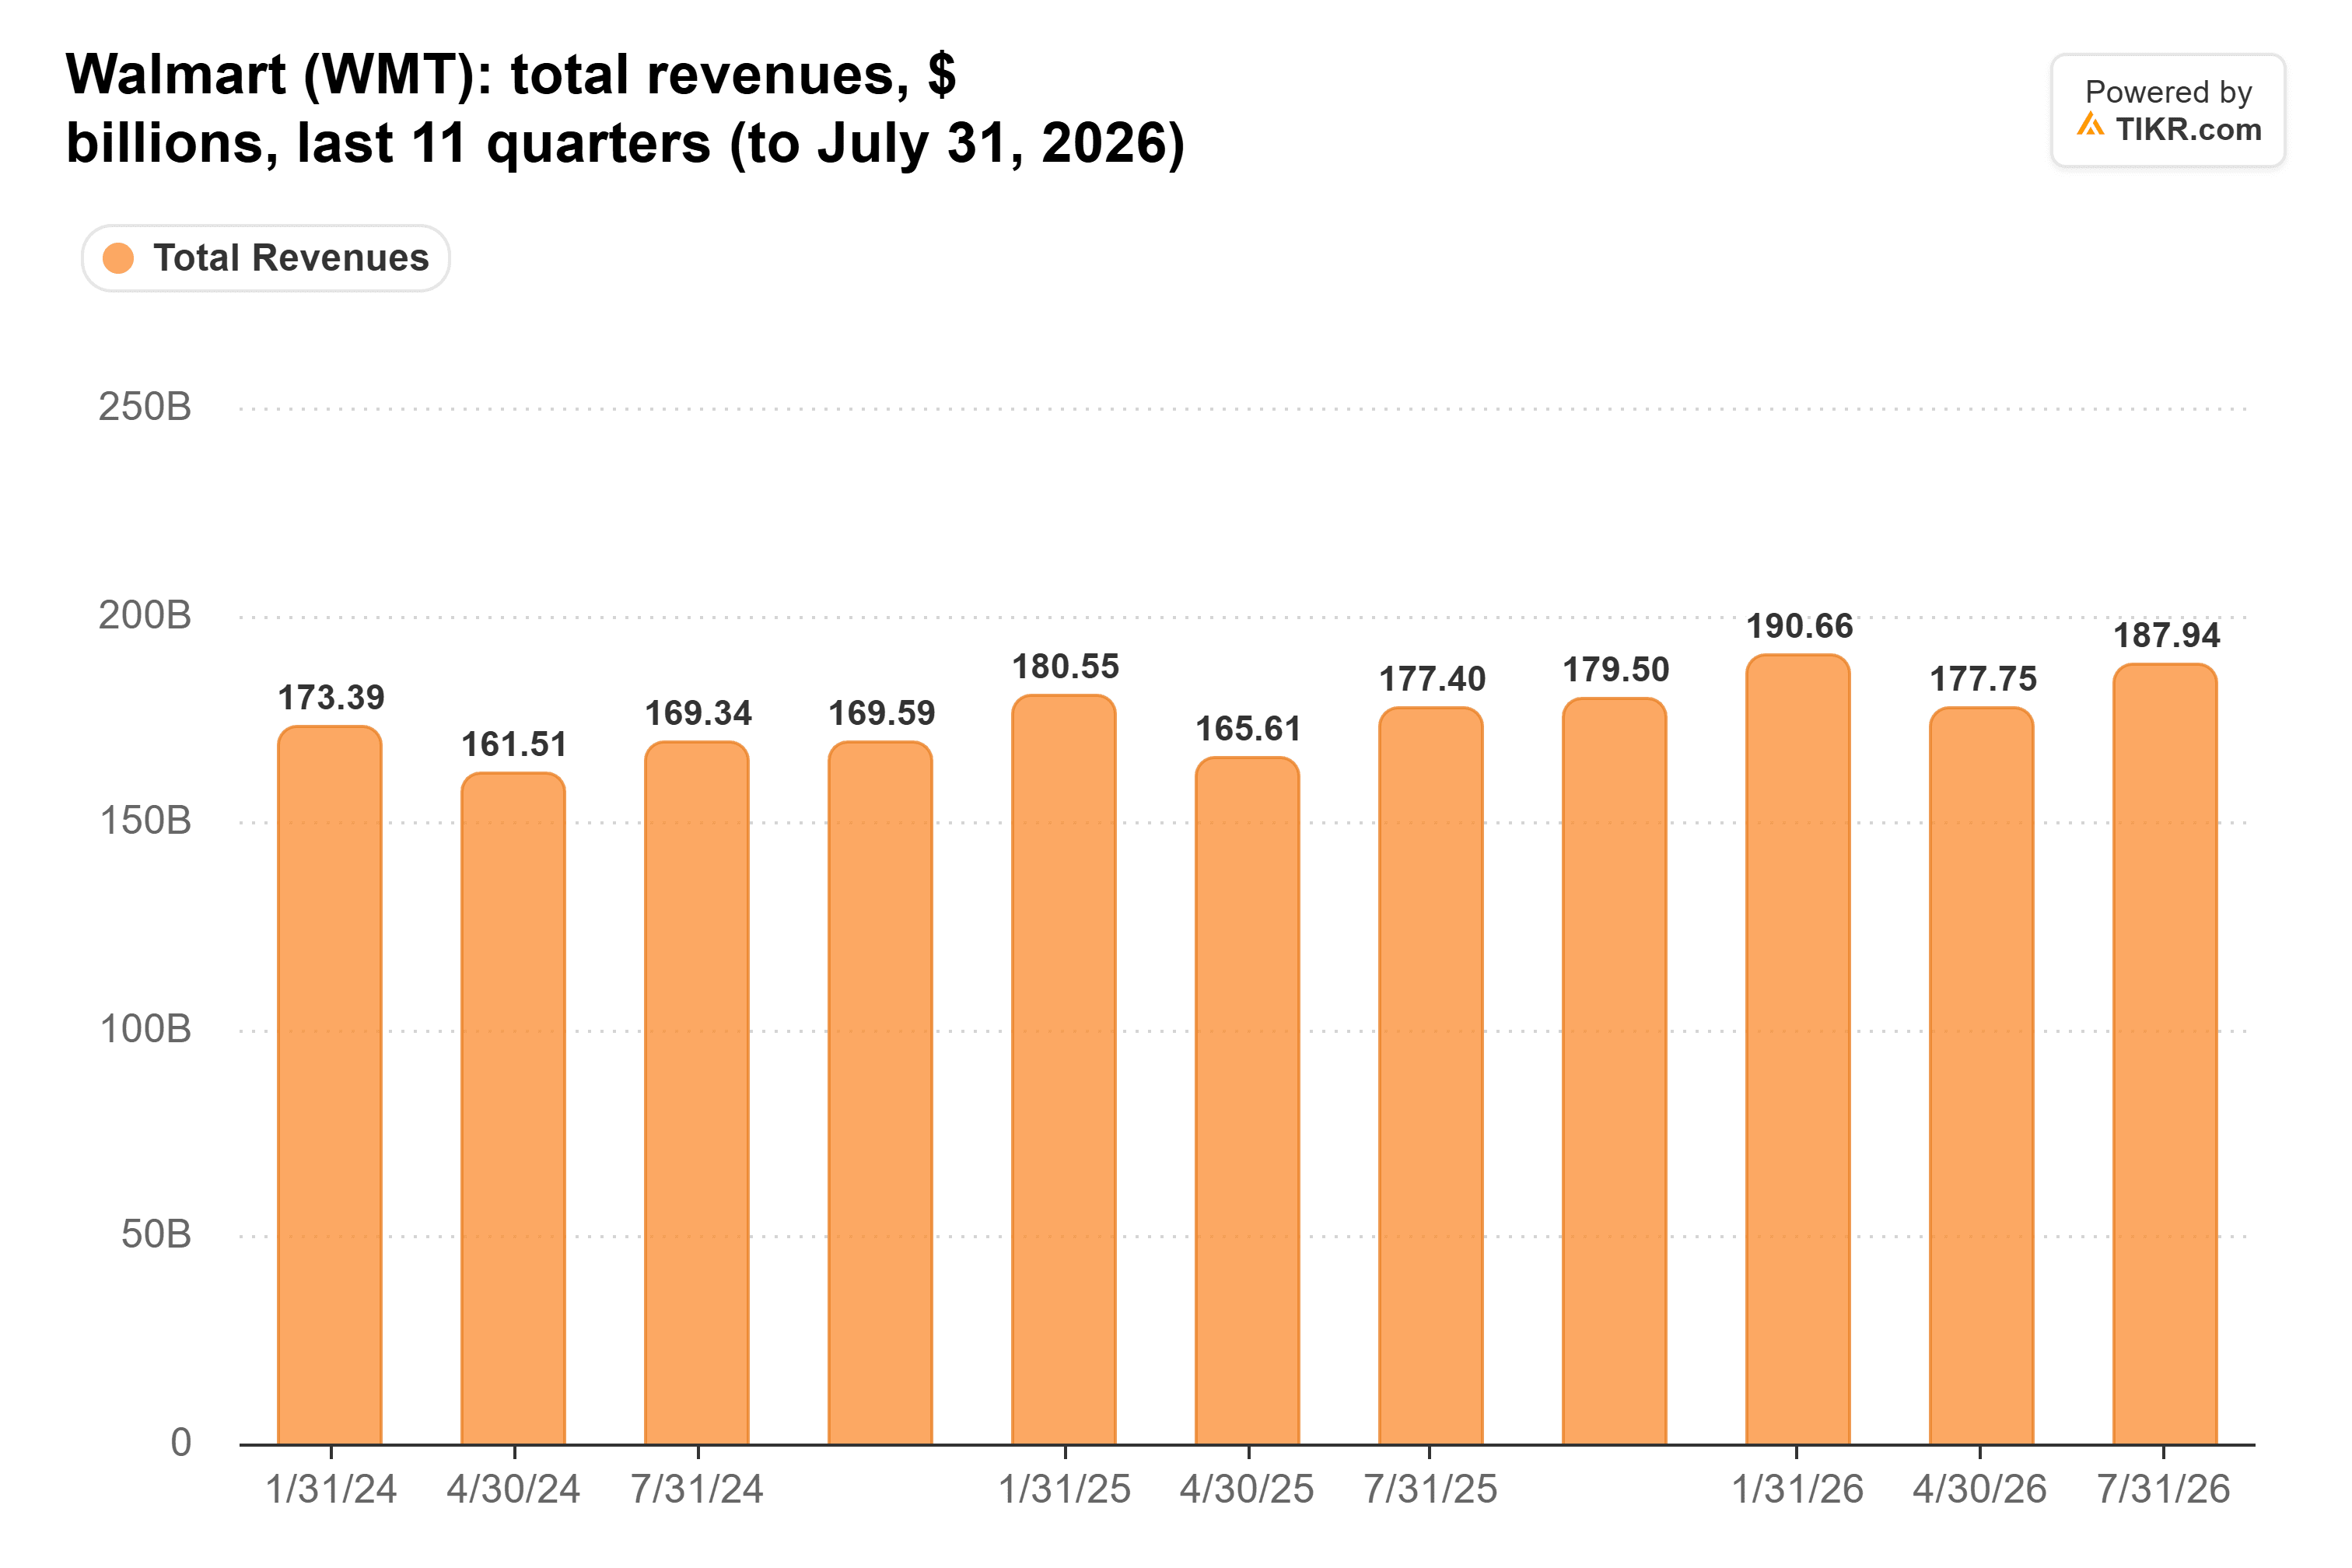
The quarter to Oct. 31 added another, at $188.8 billion against $179.5 billion. General Mills sells about $4 billion a year through Walmart: small change for a retailer with $706 billion in fiscal 2026 net sales, and more than a fifth of General Mills’ business.
TIKR Tracks 20 Analysts on General Mills. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on General Mills, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See General Mills’ Analyst Ratings
Private Label Got There First
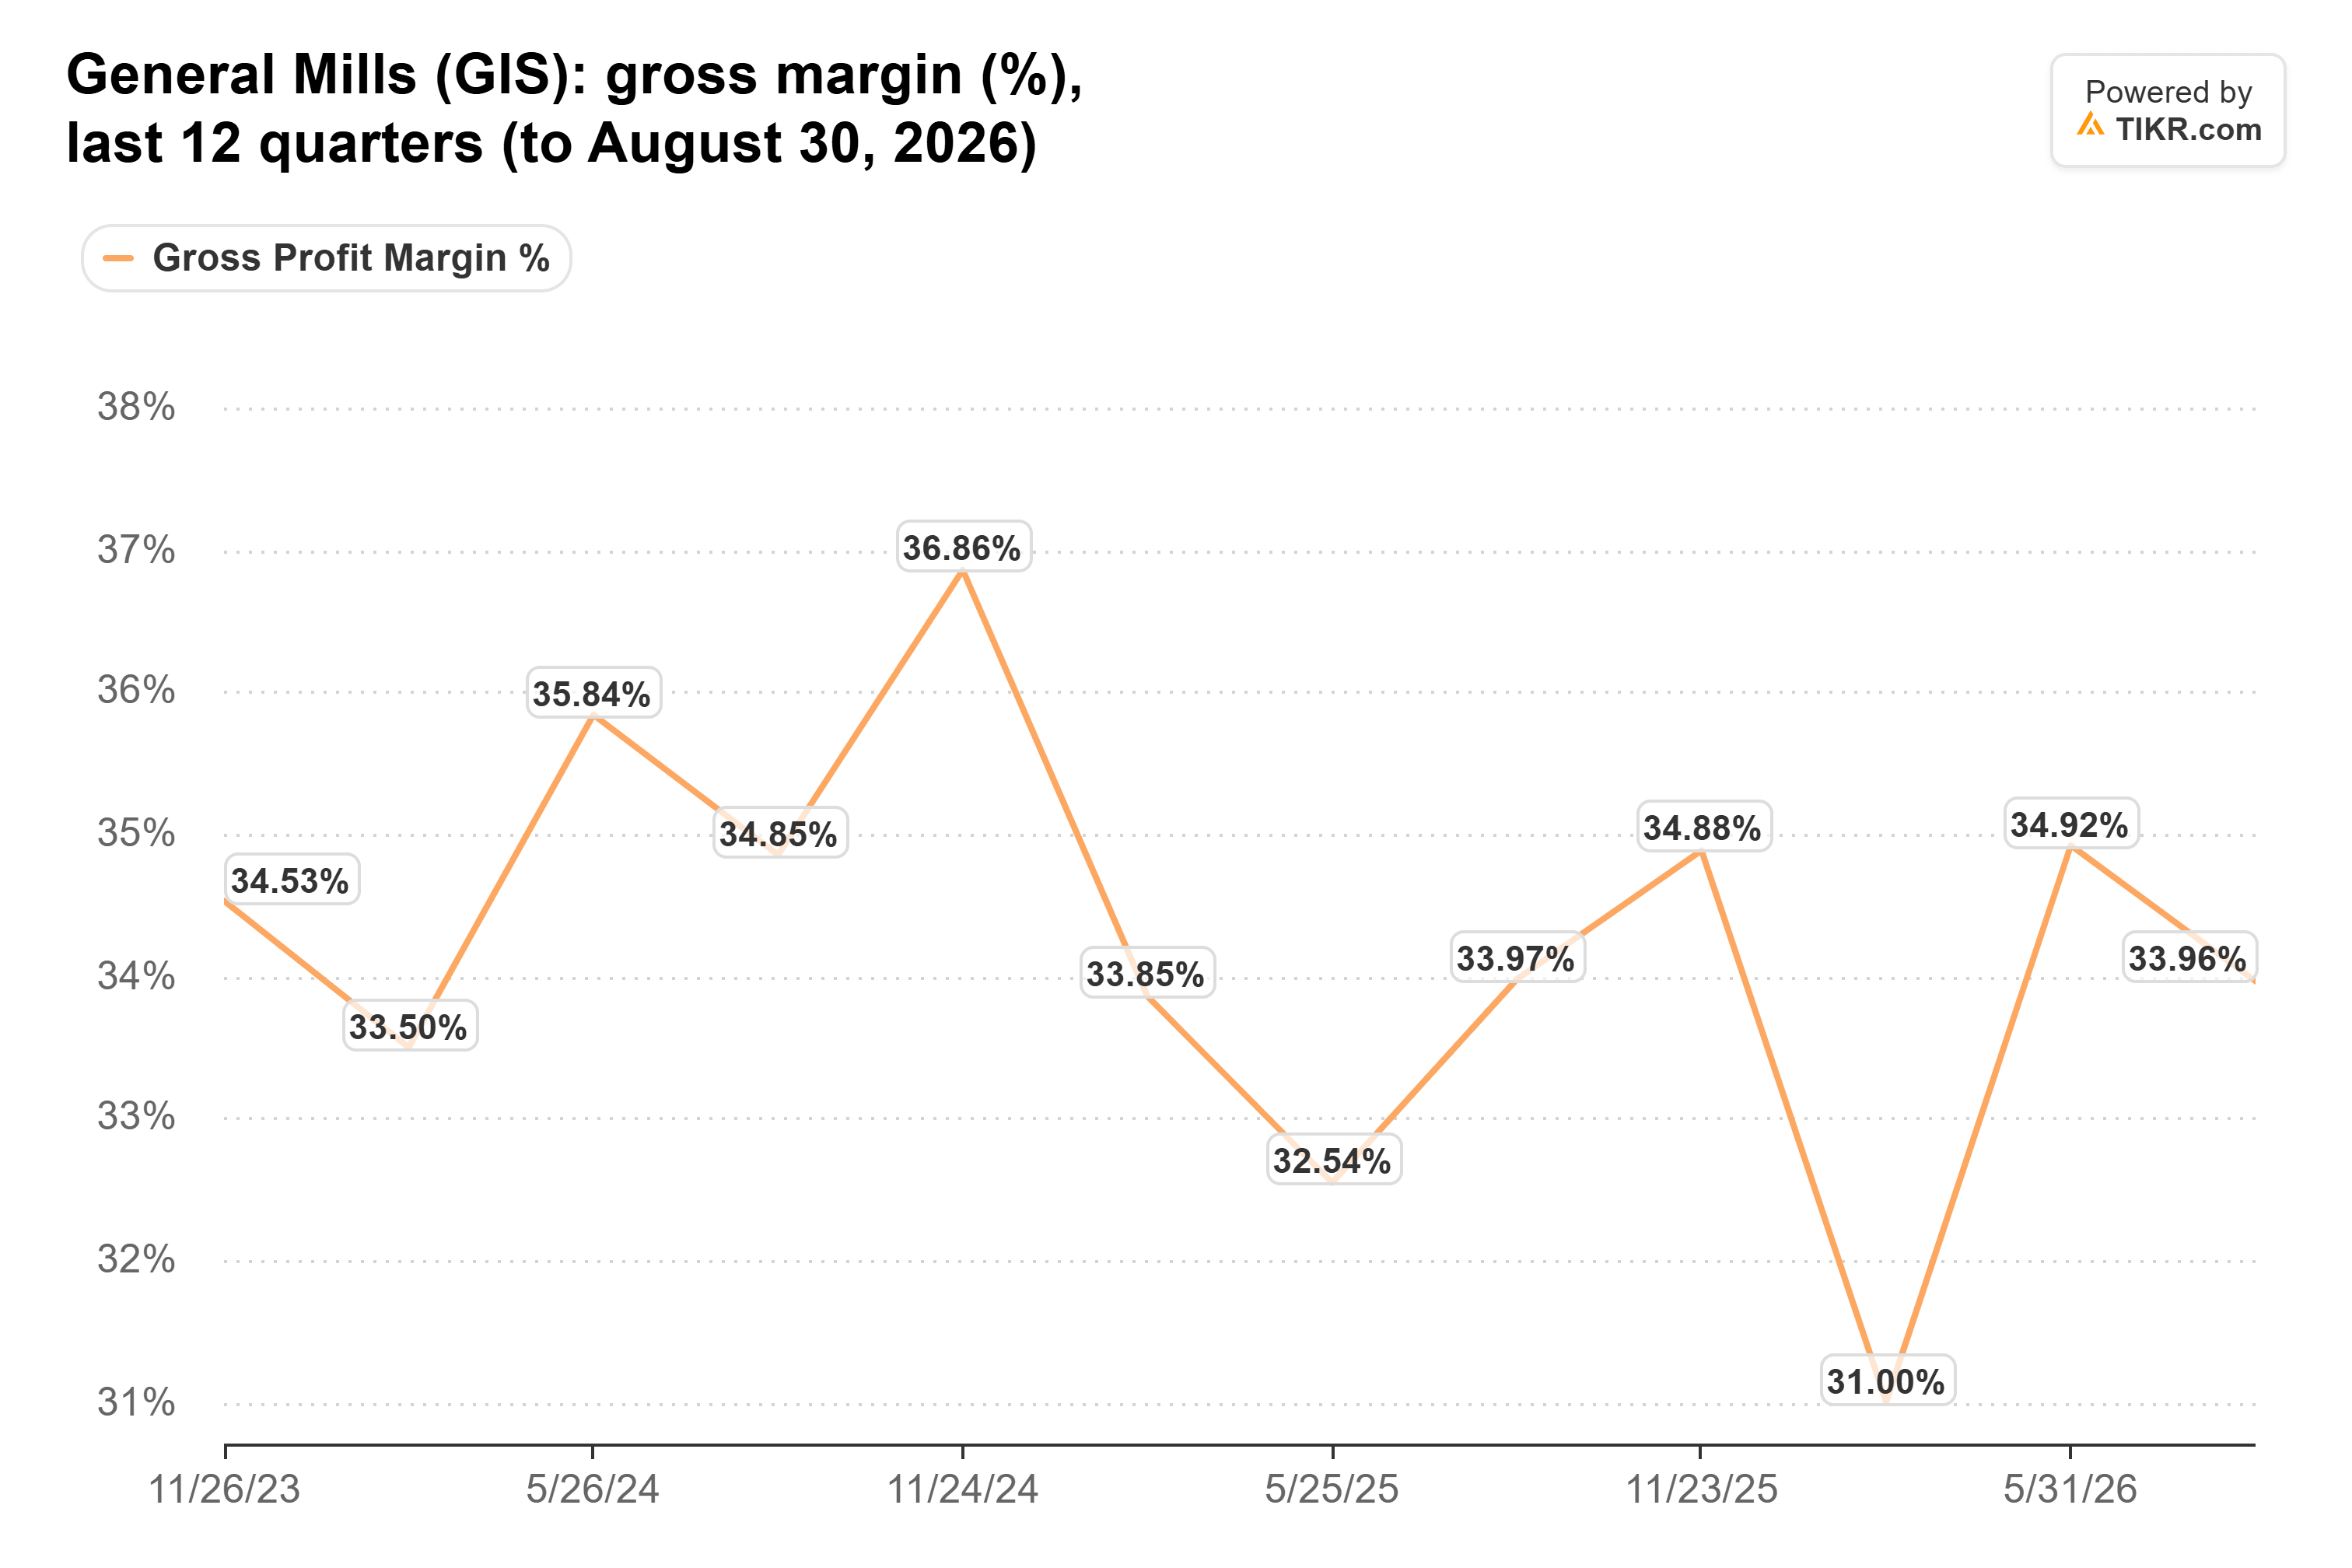
On the fiscal 2026 fourth-quarter call, COO Dana McNabb said private label had gained share in pretty much all of General Mills’ categories a year earlier, small brands too. The price cuts answered that: base volume where General Mills invested went from a 10% decline in fiscal 2025 to 1% growth by the fourth quarter of fiscal 2026. Gross margin is still below its November 2024 high:
Conagra shows the other path: price/mix added 3.4% in Grocery & Snacks, and volume fell 5.4%.
What General Mills Has to Show in December
Campbell’s reports on Dec. 9. General Mills reports its second quarter on Dec. 17, the last before McNabb becomes CEO on Jan. 1, and she expects price/mix to improve as it starts lapping last year’s cuts.
North America Retail’s organic sales are the number to watch. Near flat with positive price/mix would improve on last quarter. Another 3% decline would leave the segment shrinking at the same pace. Neither isolates Walmart: General Mills reports organic sales across all retailers, and price/mix can lift dollars while volume falls. General Mills needs Walmart’s quarter far more than Walmart does, and with flat sales expected through fiscal 2028, December is where it starts collecting or doesn’t.
So What Is General Mills Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what General Mills could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!