Key Takeaways
- Elon Musk told the DealBook Summit that NVIDIA’s board made a mistake pushing out Jensen Huang.
- Musk is also a big NVIDIA customer through SpaceX, and Jim Cramer says that customer wants lower chip prices, a real risk to NVIDIA’s gross margin.
- SpaceX’s capital spending hit $19.6 billion last quarter, and it rents NVIDIA computing power to Anthropic, which puts it in the same market as Nebius.
- NVIDIA already expects its gross margin to bottom at 71% to 72% this quarter, so the margin is the number to watch in its next report.
Elon Musk took the stage at the New York Times DealBook Summit a day after NVIDIA (NVDA) gave its first report without Jensen Huang. Musk called Huang “an old friend of mine” and told Andrew Ross Sorkin that dropping him was like being the Chicago Bulls in the middle of a winning streak:
“…you kick Michael Jordan off your team. Doesn’t seem like a smart decision to me.”
But Musk isn’t only talking as a friend. Through SpaceX (SPCX) he’s a big NVIDIA customer, and SpaceX rents that computing power to Anthropic (ANT). That makes SpaceX a seller of NVIDIA compute, like Nebius (NBIS), and every seller wants cheaper chips.
CNBC’s Jim Cramer summed up the tension on X: “I can’t blame @elonmusk for chastising Nvidia. Big Client. But also wants lower prices. That’s the real battle behind the scenes.”
Friends still haggle.
TIKR tracks 62 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
Analysts are counting on NVIDIA’s pricing
None of this shows up in NVIDIA’s results yet. Third-quarter revenue came in at $115.8 billion, well above the top of its guidance range, and the company raised its outlook. Analysts expect normalized EPS to more than triple, from $4.77 in the year ended January 2026 to $16.61 in the year ending January 2028:
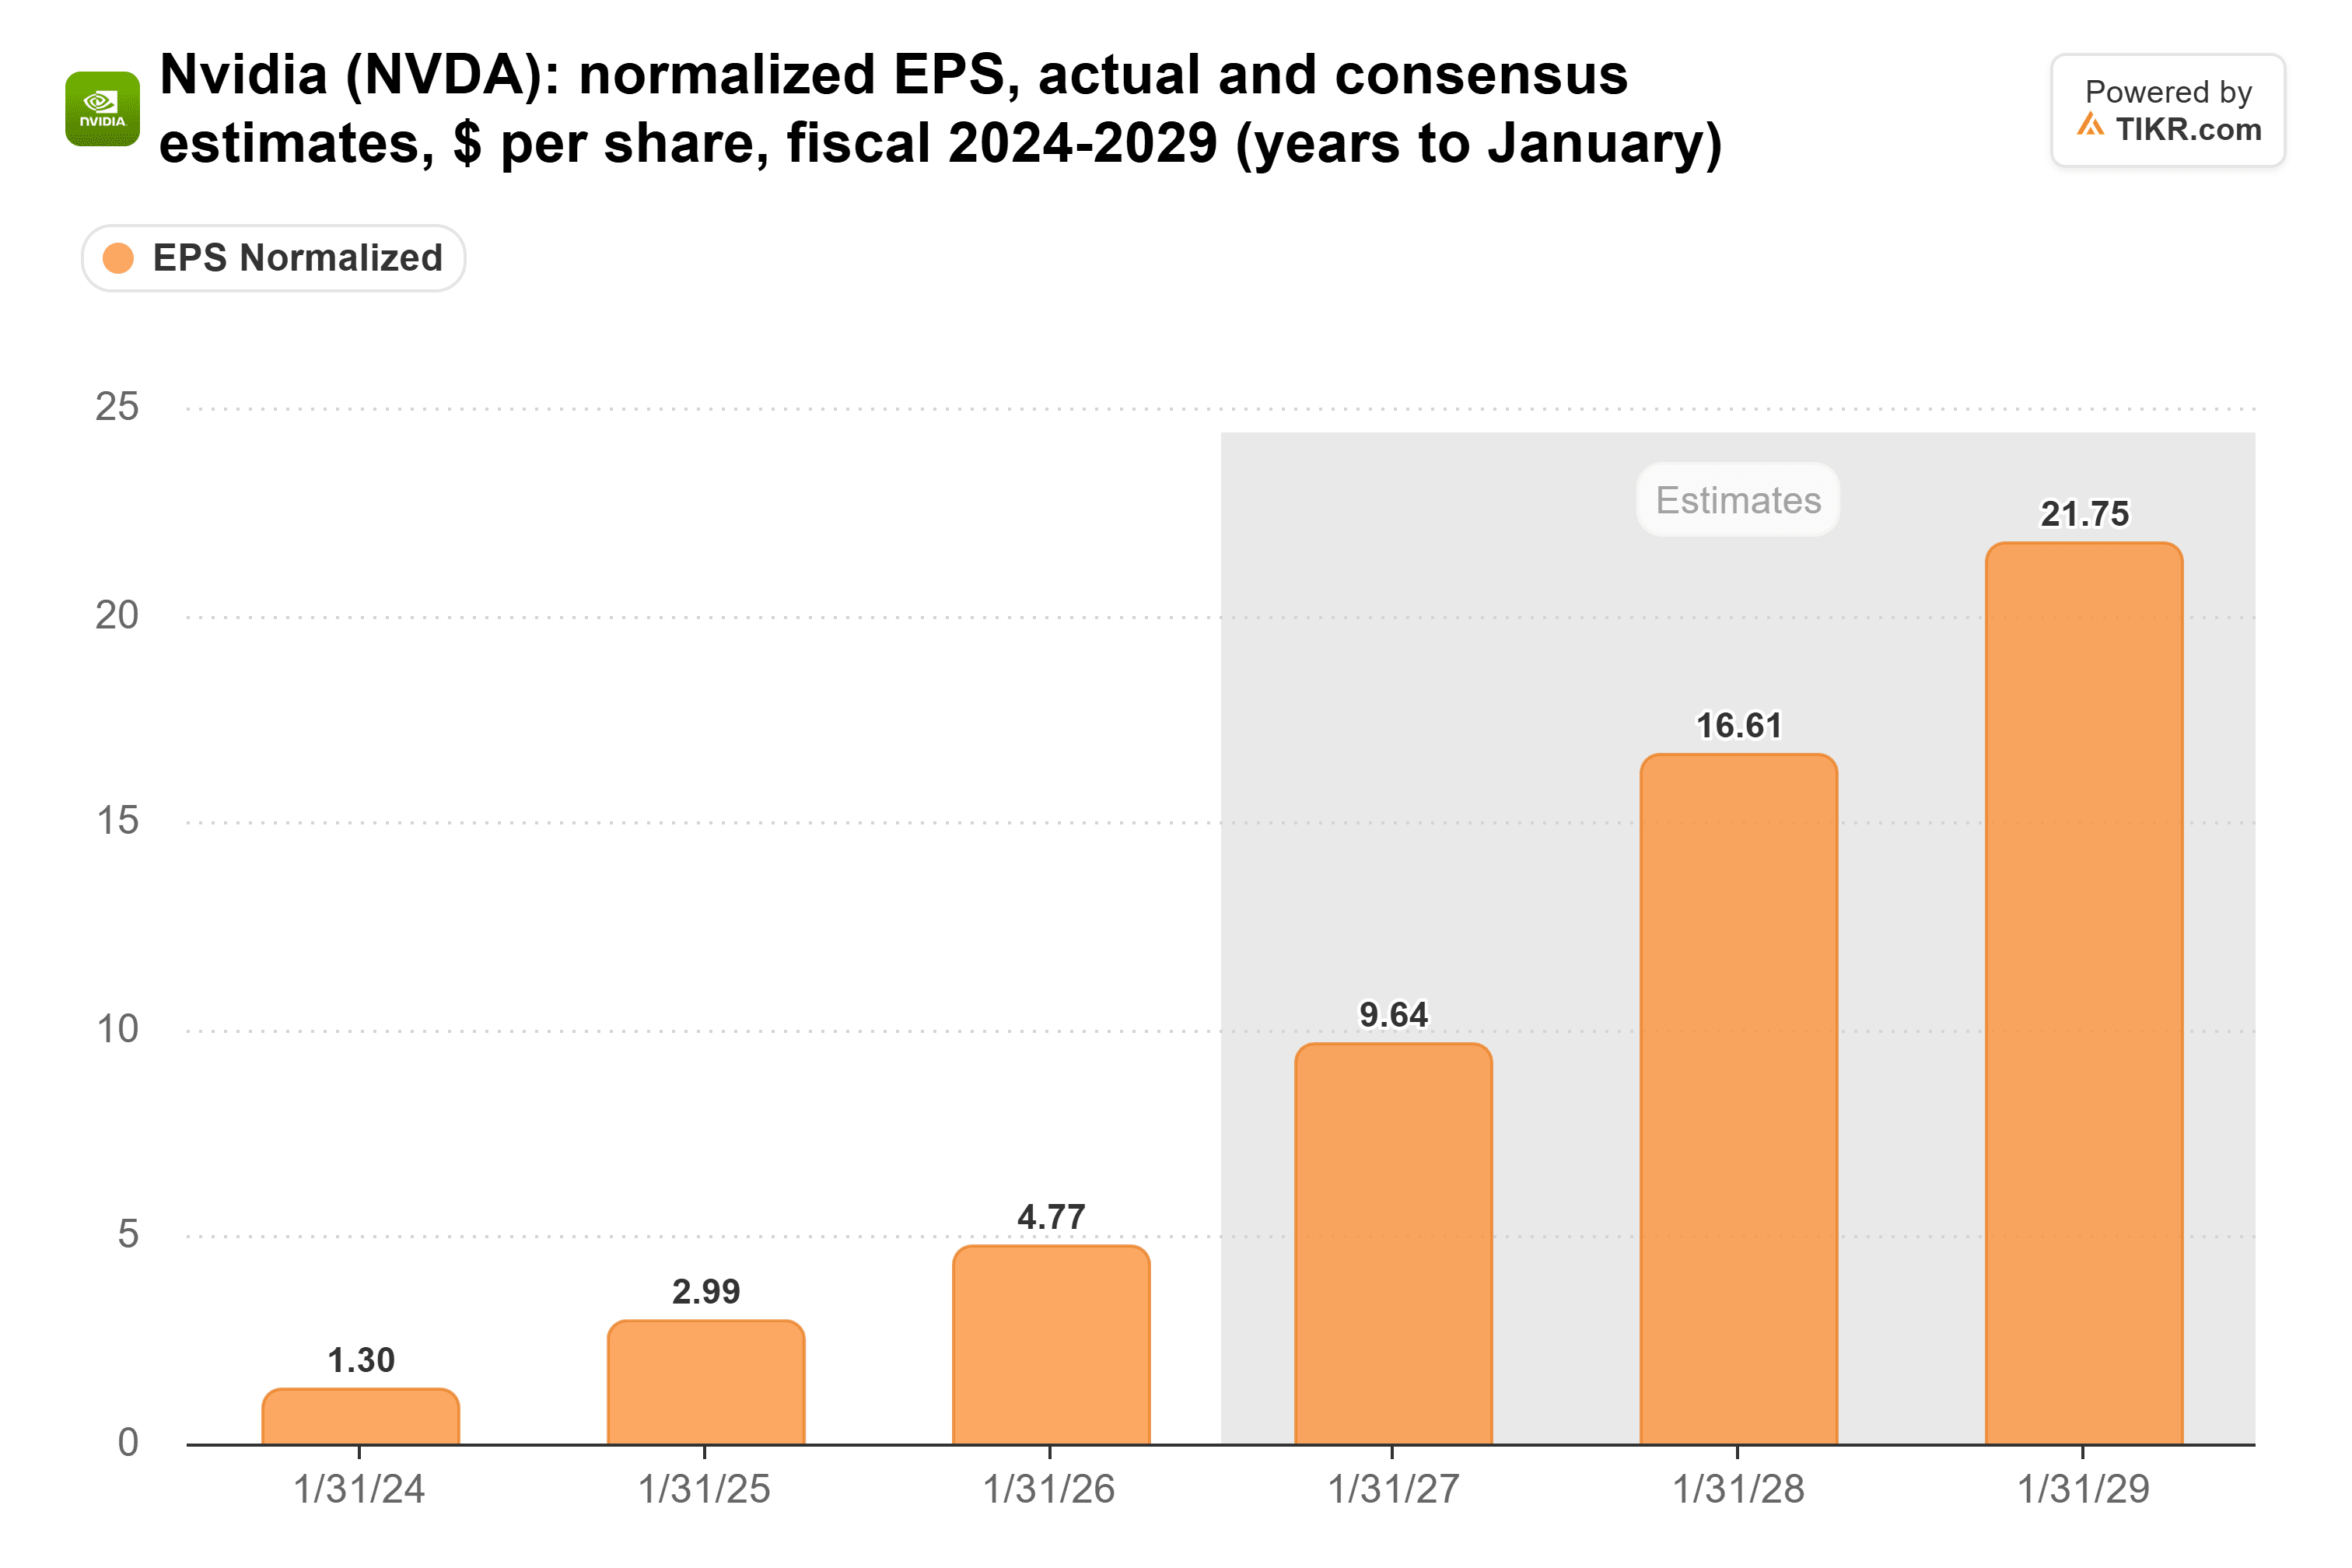
Musk’s comments alone won’t move those estimates. A price fight with buyers his size would.
That earnings path depends on NVIDIA’s GAAP gross margin, which has stayed above 71% in each of the last three fiscal years:
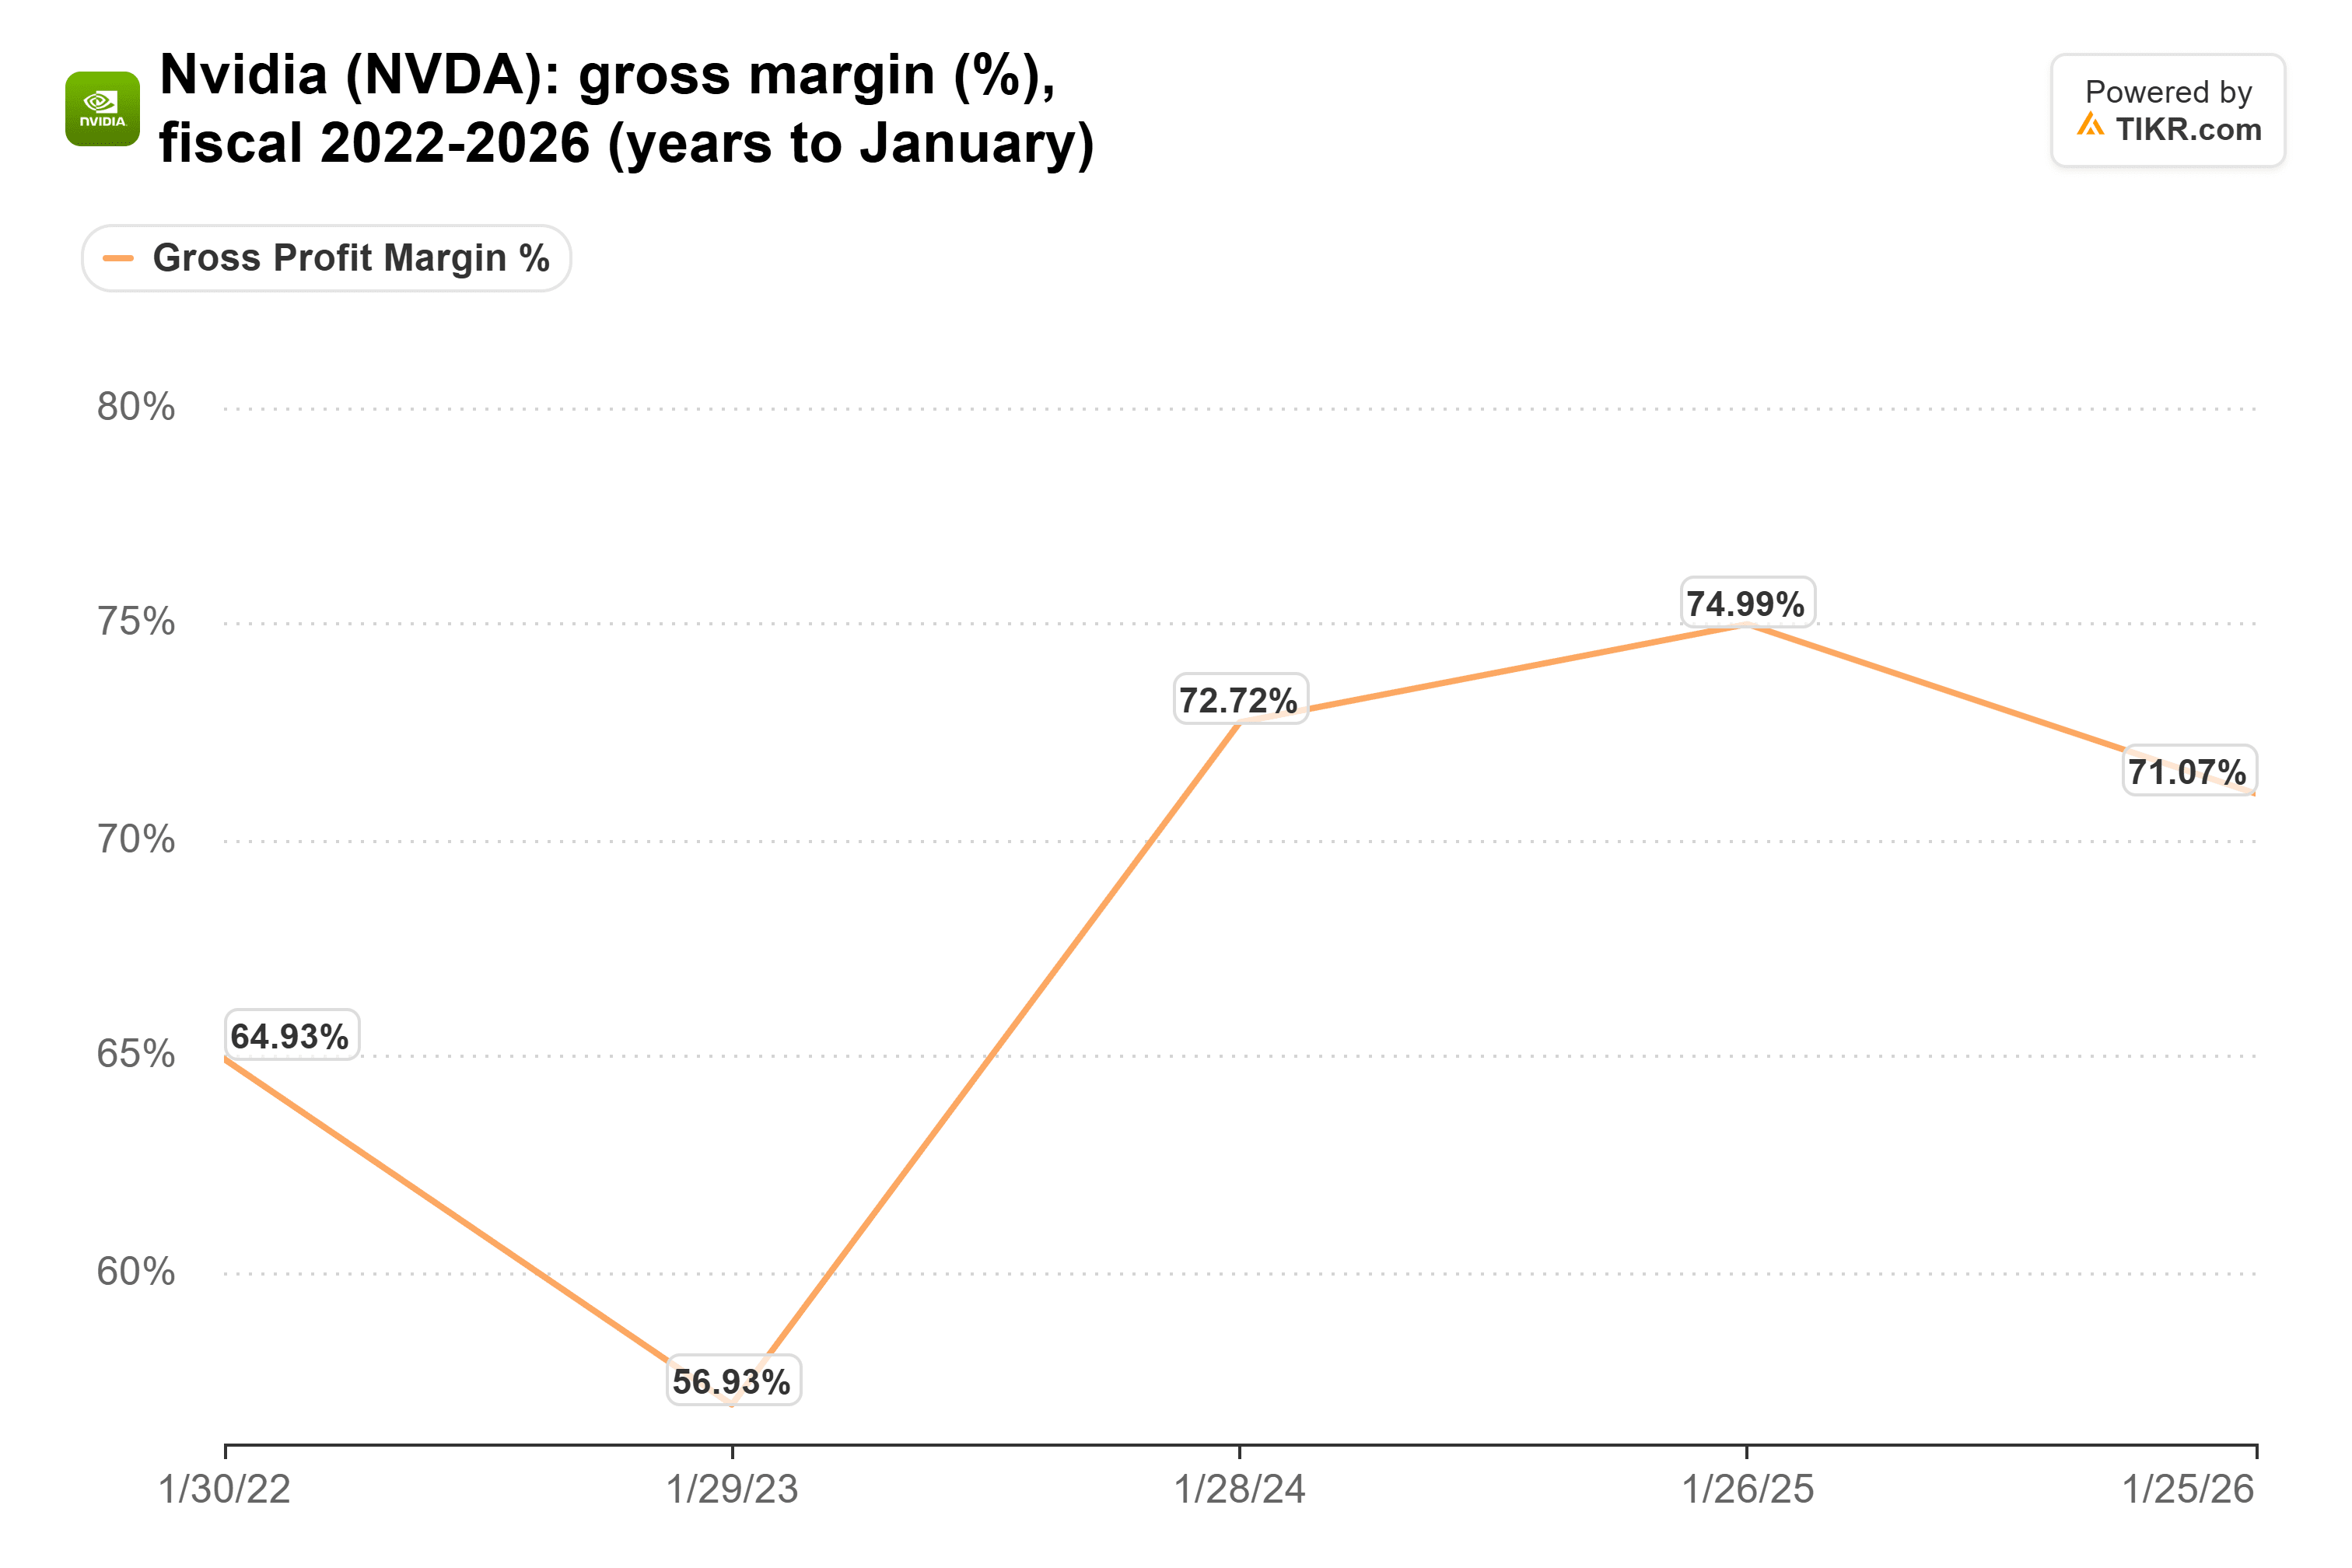
Fiscal 2026’s dip to 71.1% included a $4.5 billion charge on H20 chips meant for China, which accounts for about 2 points by itself. Fiscal 2023’s 56.9% shows how fast that margin can fall when demand cools. Management already expects gross margin to bottom at 71% to 72% in the quarter ending in January as memory costs climb. Buyers pushing on price would squeeze it from the other side.
SpaceX is buying enough to push back
SpaceX’s capital spending hit $19.6 billion in the quarter to Sept. 30, 2026, 2.8x the $6.96 billion a year earlier (that figure covers all of SpaceX, rockets and satellites included):
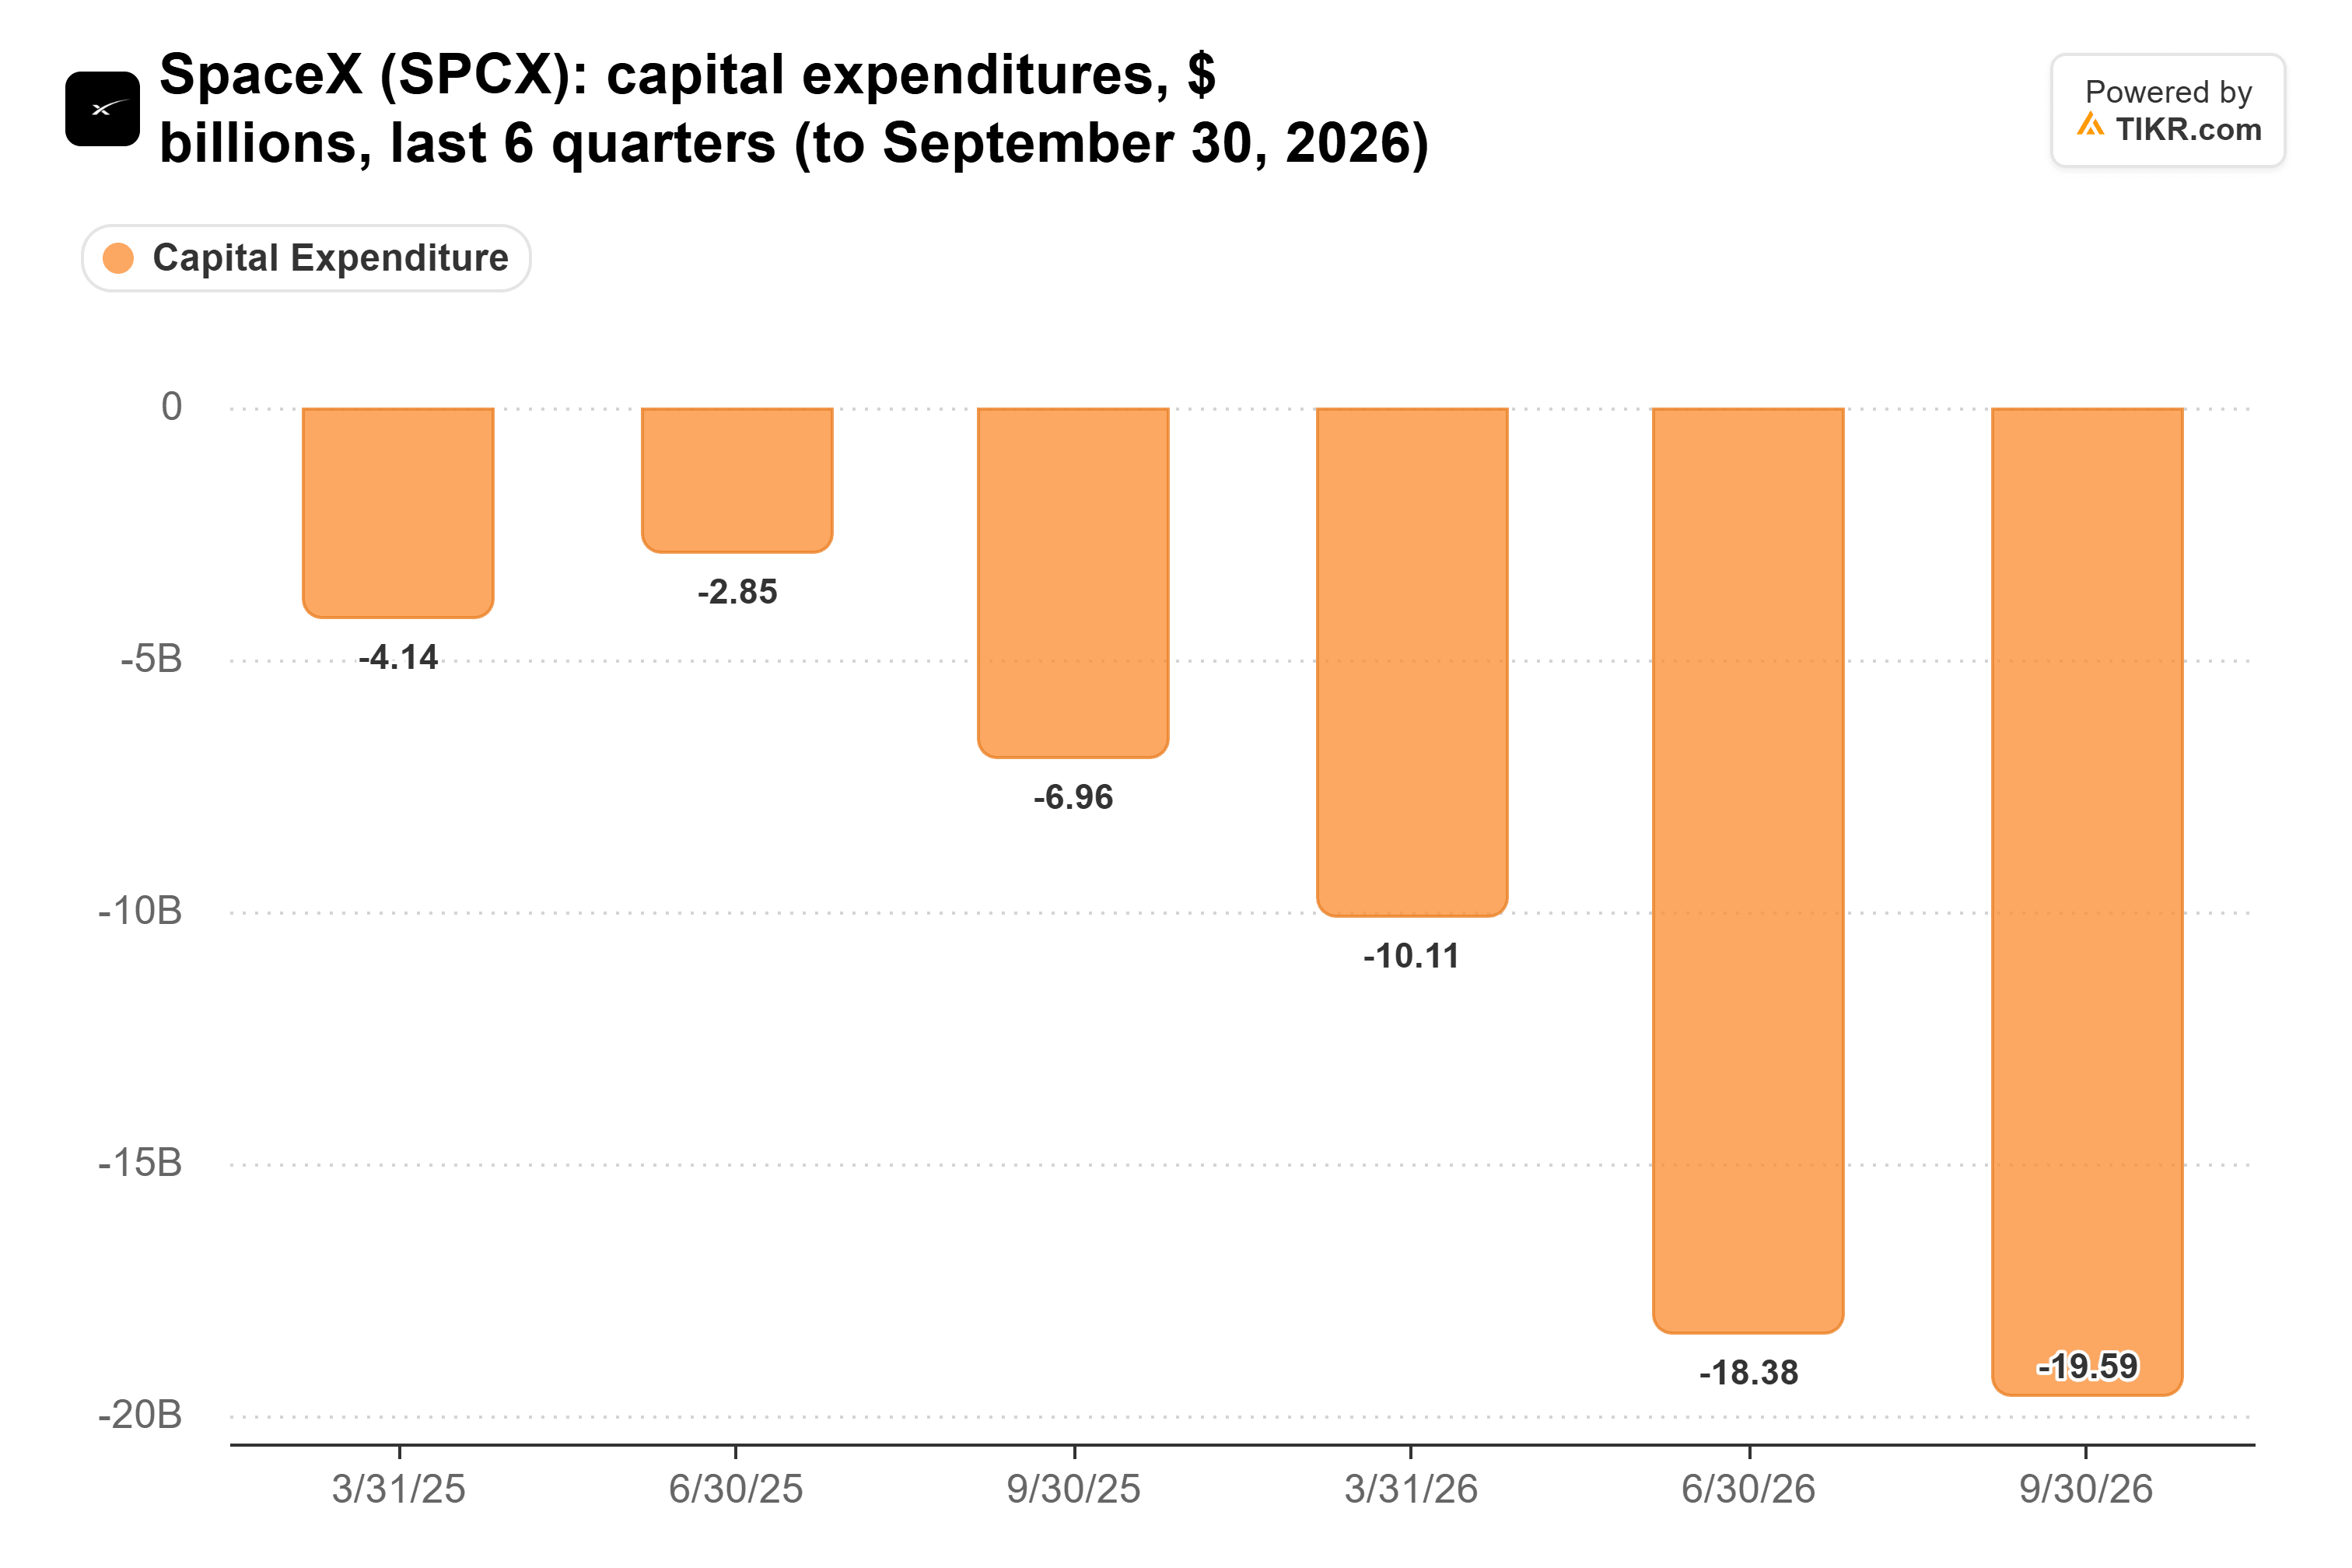
Cramer says Anthropic pays SpaceX as much as $3.1 billion a month for compute at full capacity, running on SpaceX’s NVIDIA chips. So every dollar SpaceX saves on NVIDIA’s price widens its margin on that rental income.
Then there’s supply. Musk replied “Interesting” to an X user shopping for B300 capacity, who claimed “there’s way more B300 sitting unsold than people think.” If he’s right, Nebius would feel it too. Its third-quarter revenue jumped to $980.8 million from $146.1 million a year earlier. But after $354.7 million of depreciation and amortization, it kept only about $50 million of GAAP operating income. Softer rental prices on NVIDIA’s newest chips would eat into that fast.
Keep an eye on the margin
Nothing Musk said at DealBook was about what SpaceX pays, and the “battle” is Cramer’s own read. Still, the way I see it, buyers that make money renting NVIDIA’s chips out are a slow squeeze on its margin while demand stays strong. The test comes when NVIDIA reports in late February: if gross margin lands below the 71% to 72% guide, the buyers are winning. Of course, one X post about unsold nodes is only an anecdote, and SpaceX’s ramp could keep NVIDIA sold out for a while yet.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!