Key Takeaways
- NVIDIA raised its fiscal 2028 revenue growth forecast to about 75% from 70% in its first report since Jensen Huang resigned as CEO.
- The market already priced in slower growth, so the raise makes NVIDIA’s low multiple look like a bargain.
- NVIDIA trades at 13x forward earnings, its lowest in five years, and about 10x the EPS analysts expect for fiscal 2028.
- DA Davidson’s Gil Luria warns growth could come in at 25% to 50%, and the January-quarter results in late February are the next test.
NVIDIA (NVDA) just reported its first quarter since Jensen Huang resigned as CEO, and its board said it’s not bringing him back.
The outlook improved anyway! On Tuesday’s third-quarter call, interim CEO and CFO Colette Kress raised the forecast for fiscal 2028, the year ending January 2028: “We expect revenue to grow approximately 75% year-over-year, up from 70% and off what is now a higher fiscal 2027 base.”
Plenty of people expected the opposite. Gil Luria, head of technology research at DA Davidson, said on Wednesday’s episode of Prof G Markets: “I didn’t think that they’d even touch guidance for next year.”
That’s a big deal for a stock priced for something to go wrong. Before the report, Creative Planning’s Charlie Bilello summed up the setup on X: “Either the stock is incredibly cheap or earnings expectations are way too high.”
Kress just made the first option a lot easier to believe.
TIKR tracks 63 analysts on Nvidia. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Nvidia, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Nvidia’s Analyst Ratings
The raise comes off a bigger base
The quarter gave Kress plenty of cover. Revenue hit $115.8 billion, up 103% from a year earlier and well ahead of expectations. NVIDIA guided the January quarter to $127.4 billion-$132.6 billion of revenue.
Kress also said the cloud industry’s backlog reached $2.5 trillion, up from $2 trillion three months earlier.
Add the January-quarter guide’s midpoint to the first three quarters, and fiscal 2027 revenue comes to about $424 billion. Grow that 75%, and fiscal 2028 lands around $740 billion. The chart below shows analysts expected less than that:
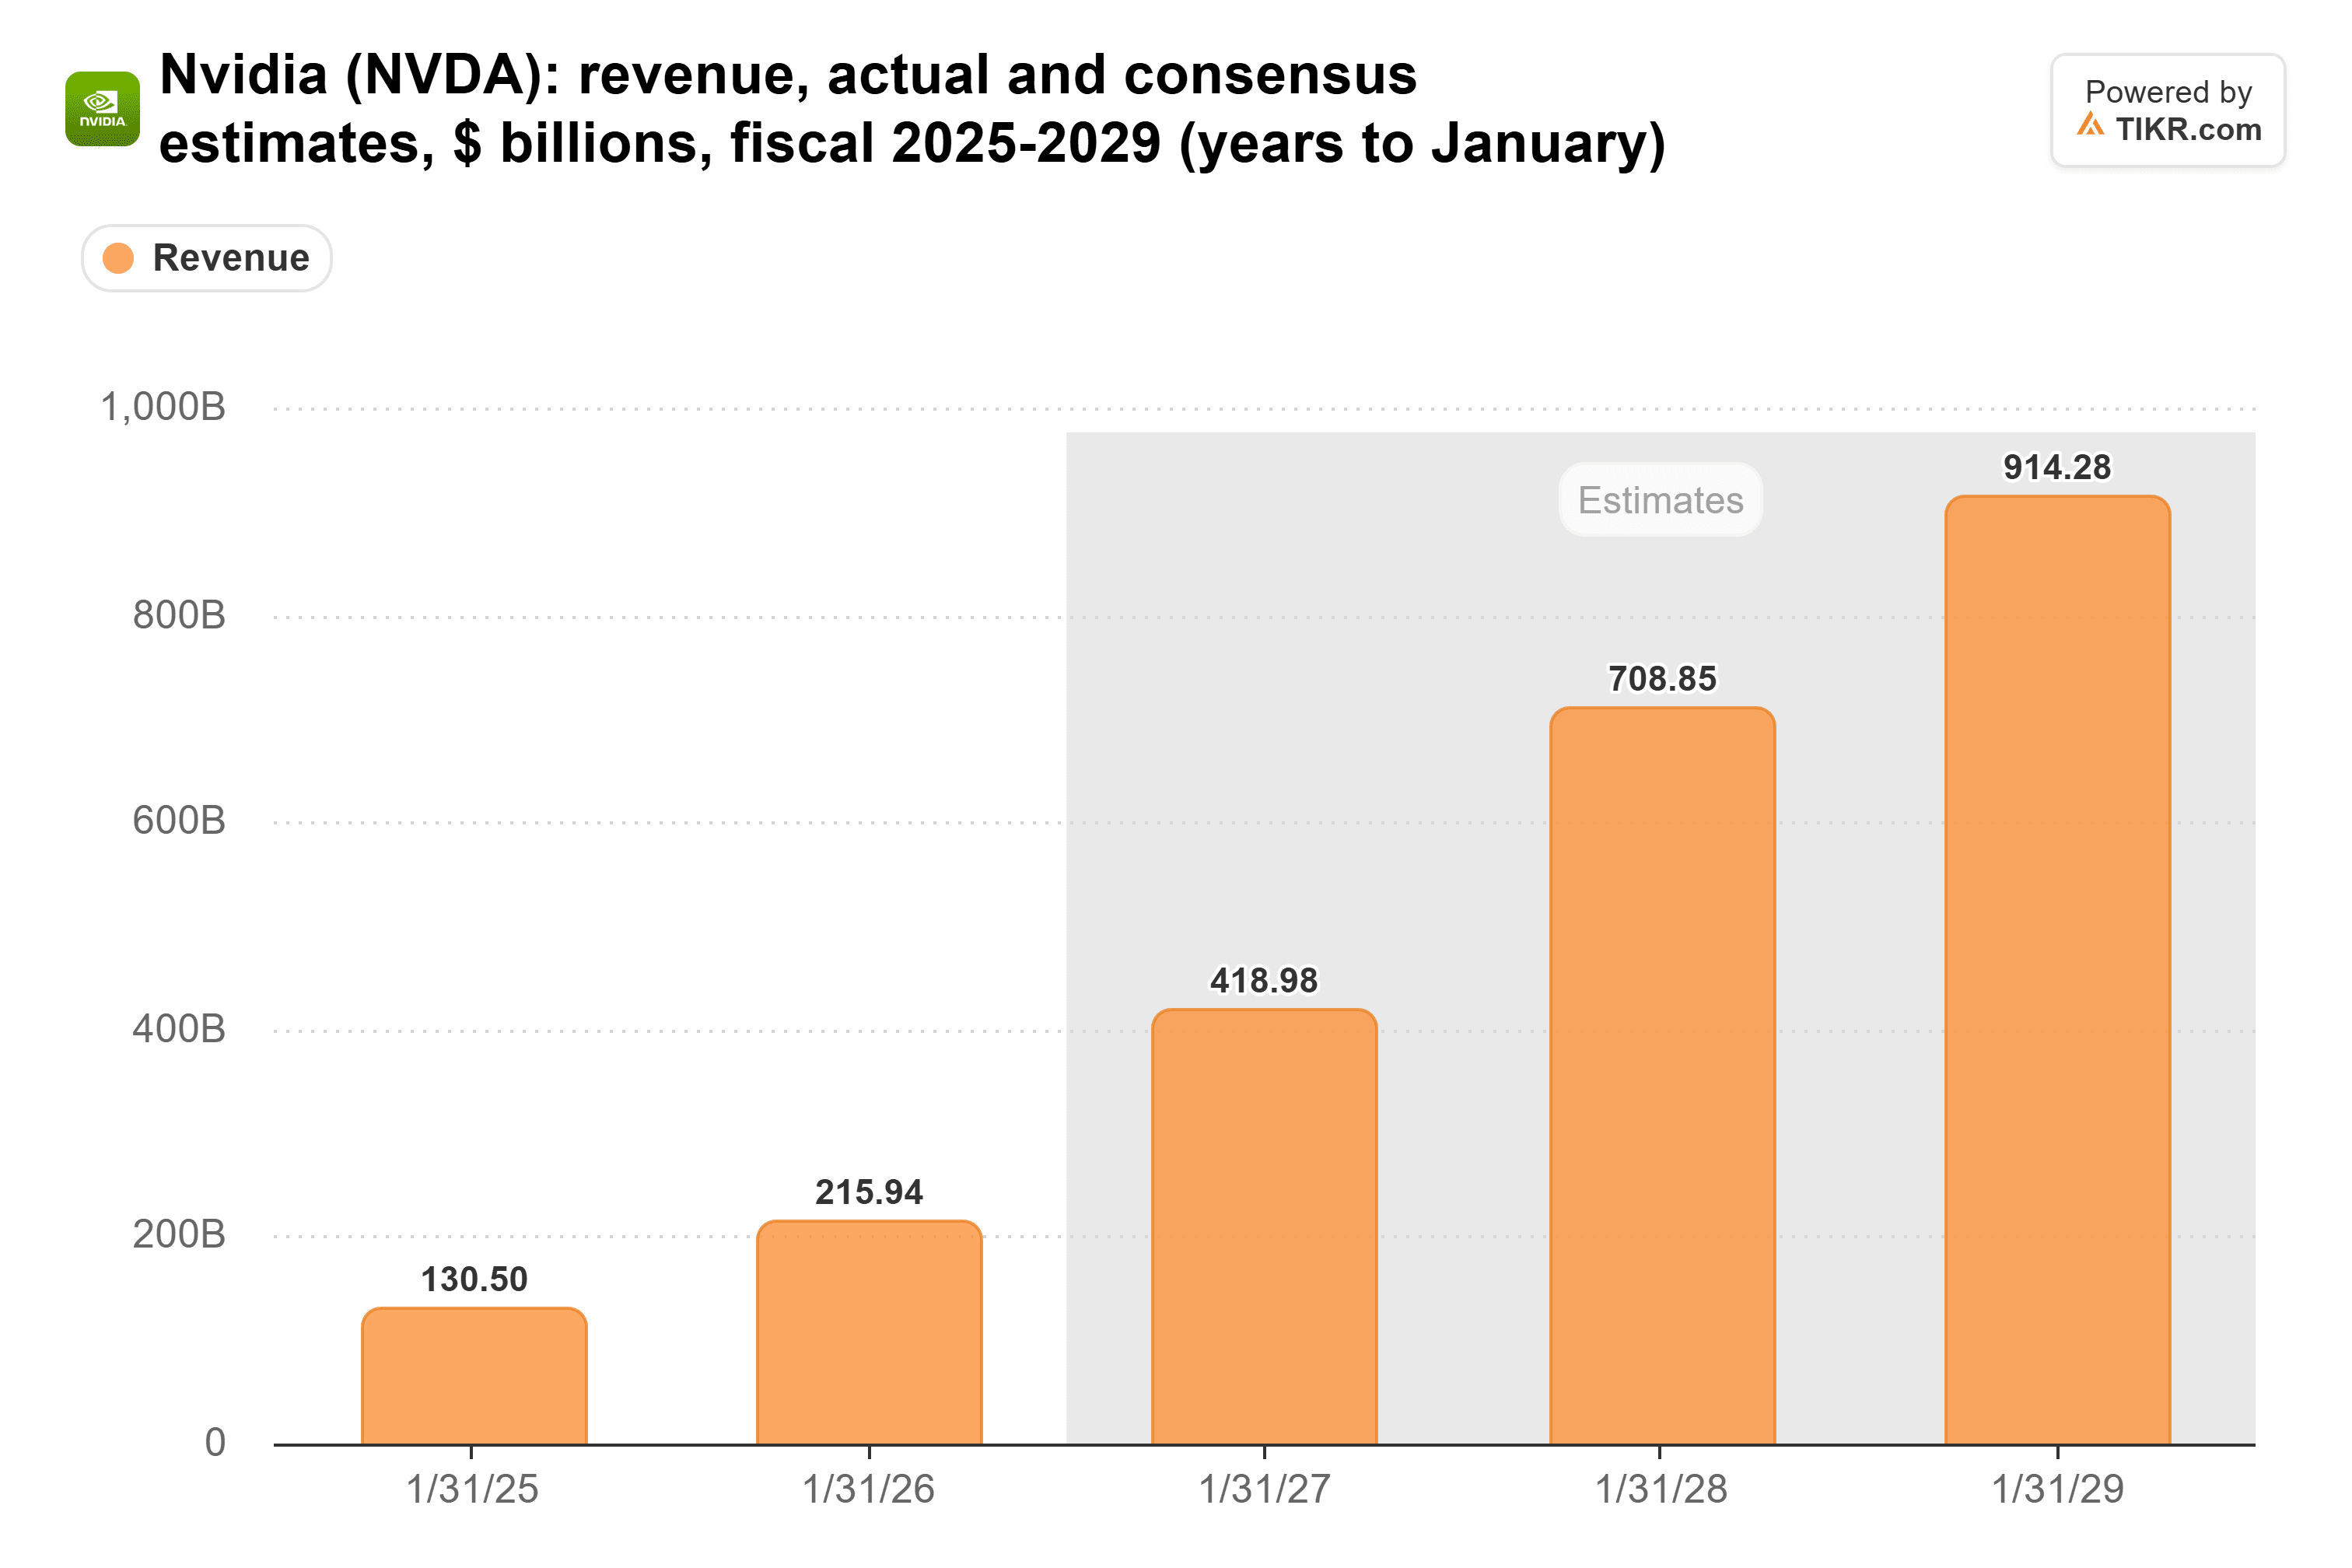
Most of the $709 billion consensus for fiscal 2028 was set before the raise, and it should move up.
13x for all that
Even so, NVIDIA trades at about 13x forward earnings, its lowest point in five years. The chart shows how far it sits below its five-year average of 36x and its peak near 70x in May 2023:
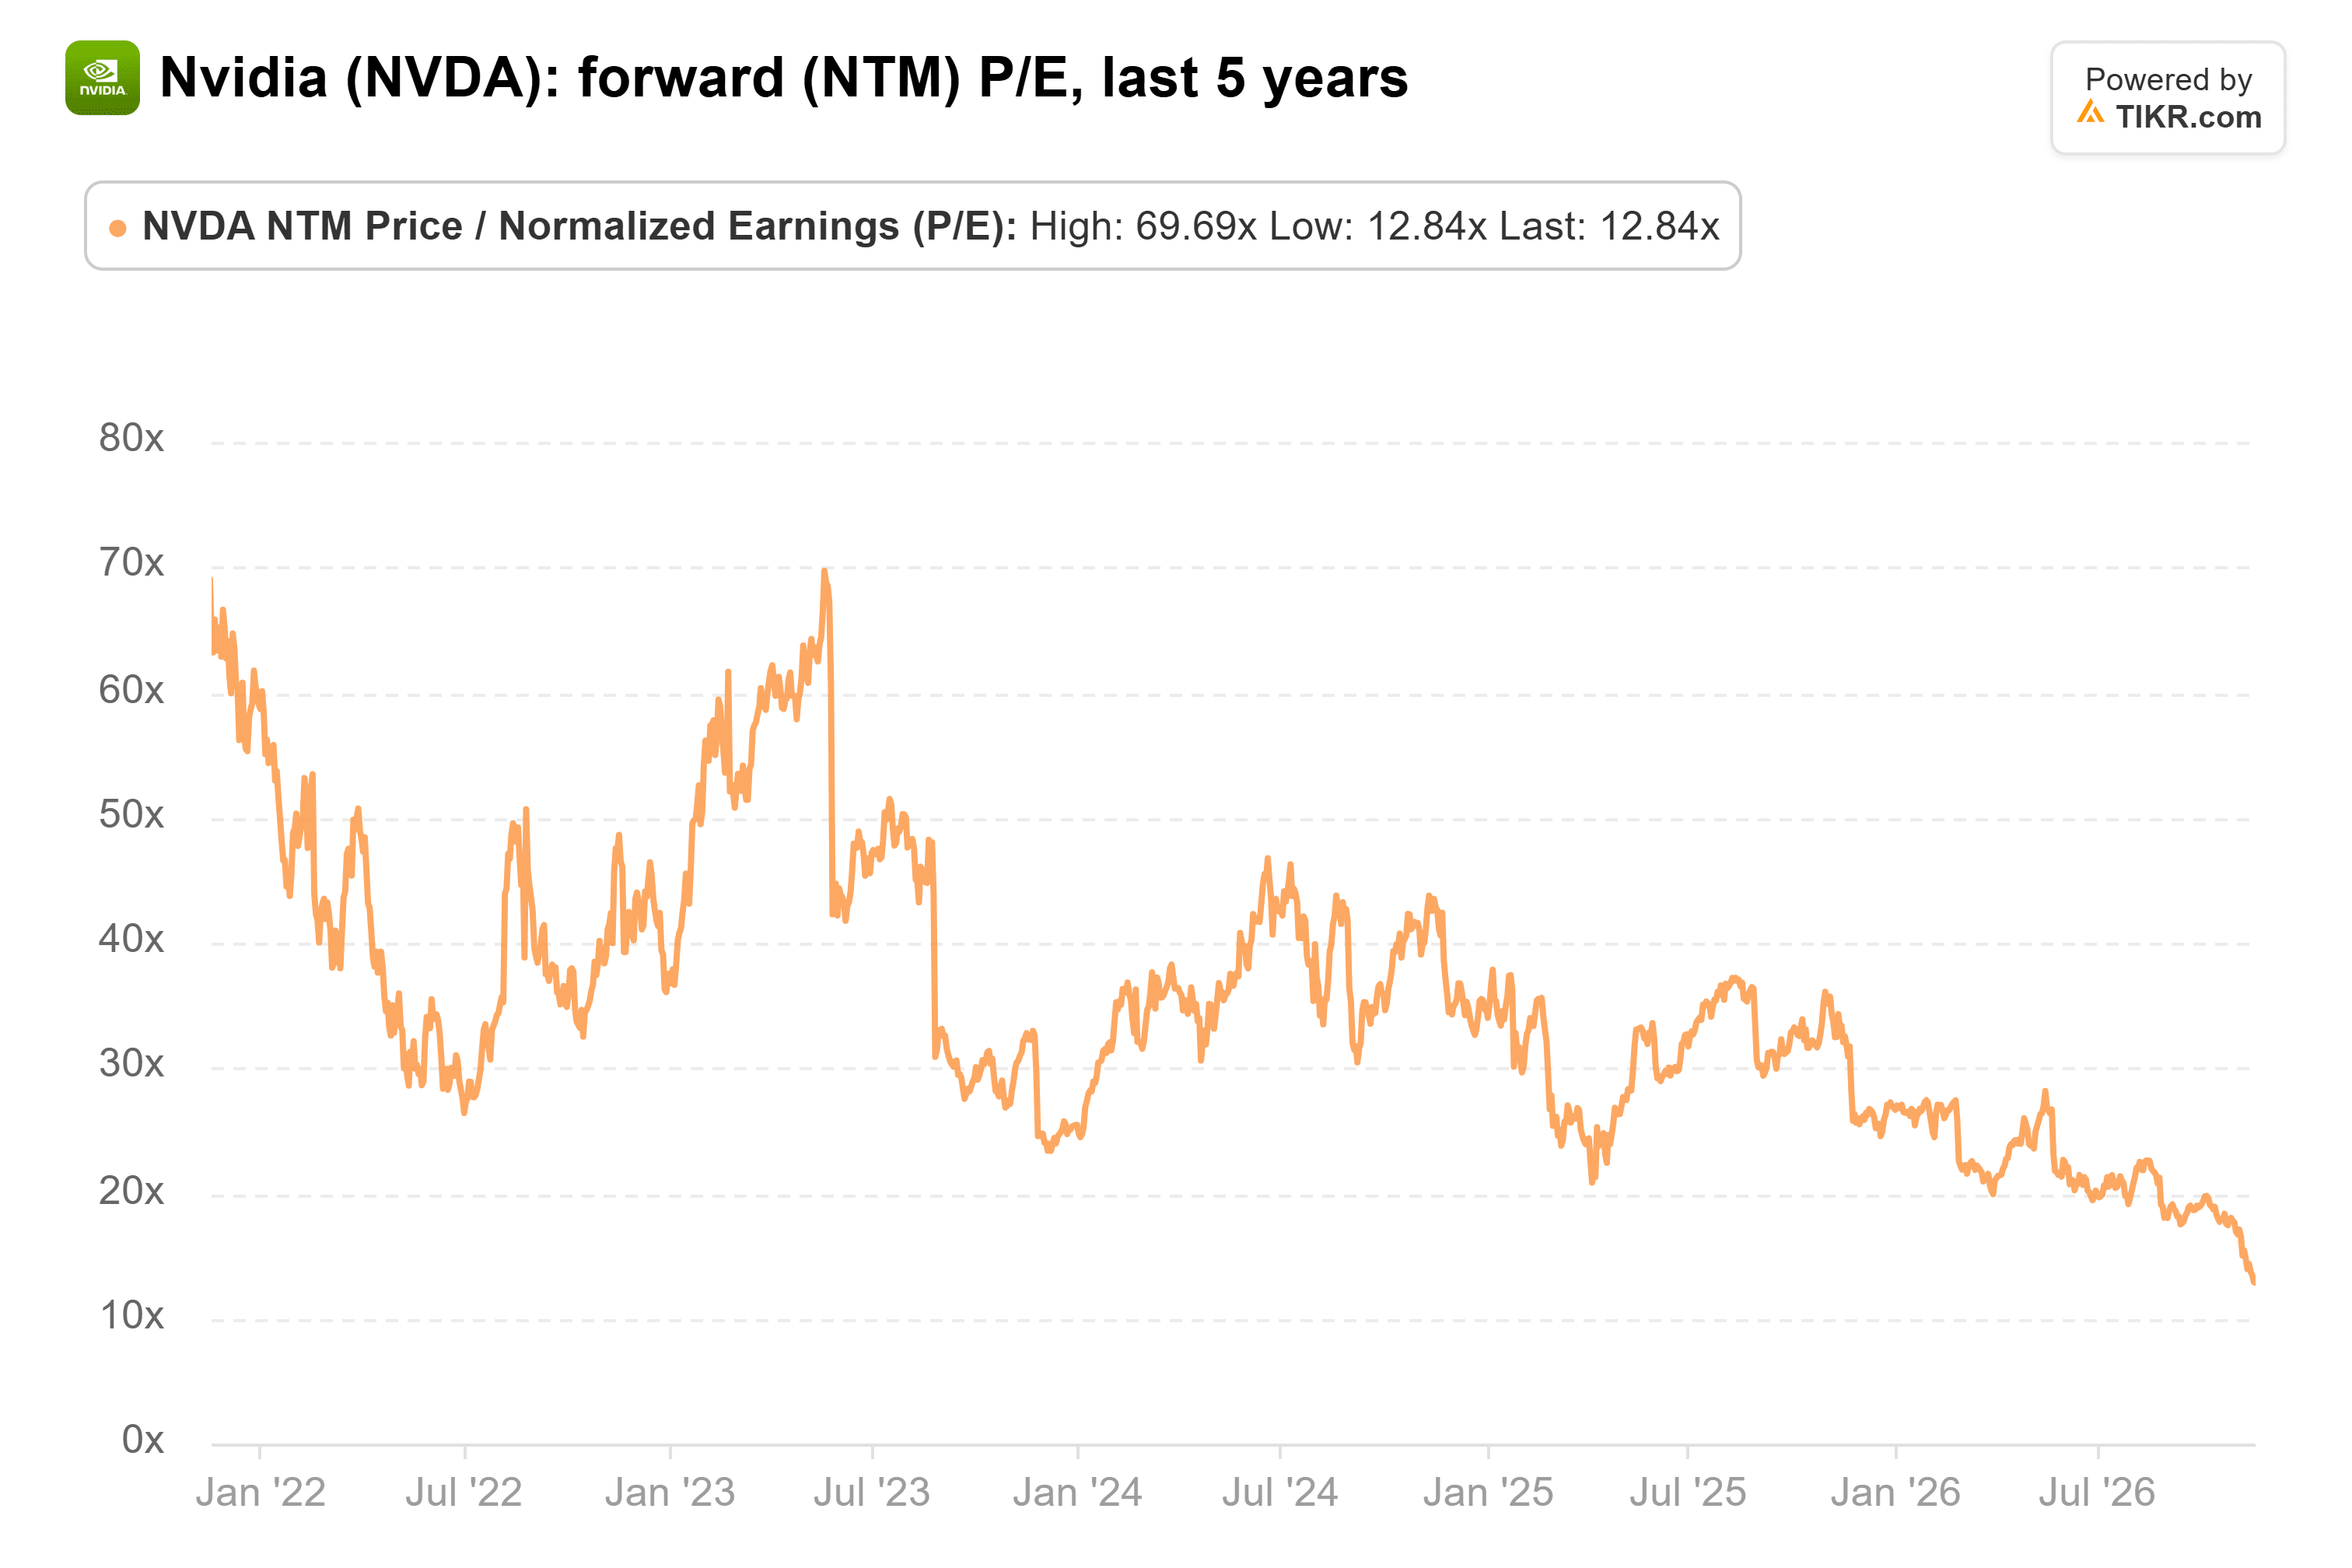
My read: part of that drop is a discount for losing Huang, and part is the worry Bilello named, that the estimates are too high.
But analysts expect normalized EPS of $16.24 in fiscal 2028, more than 3x the $4.77 NVIDIA earned in fiscal 2026:
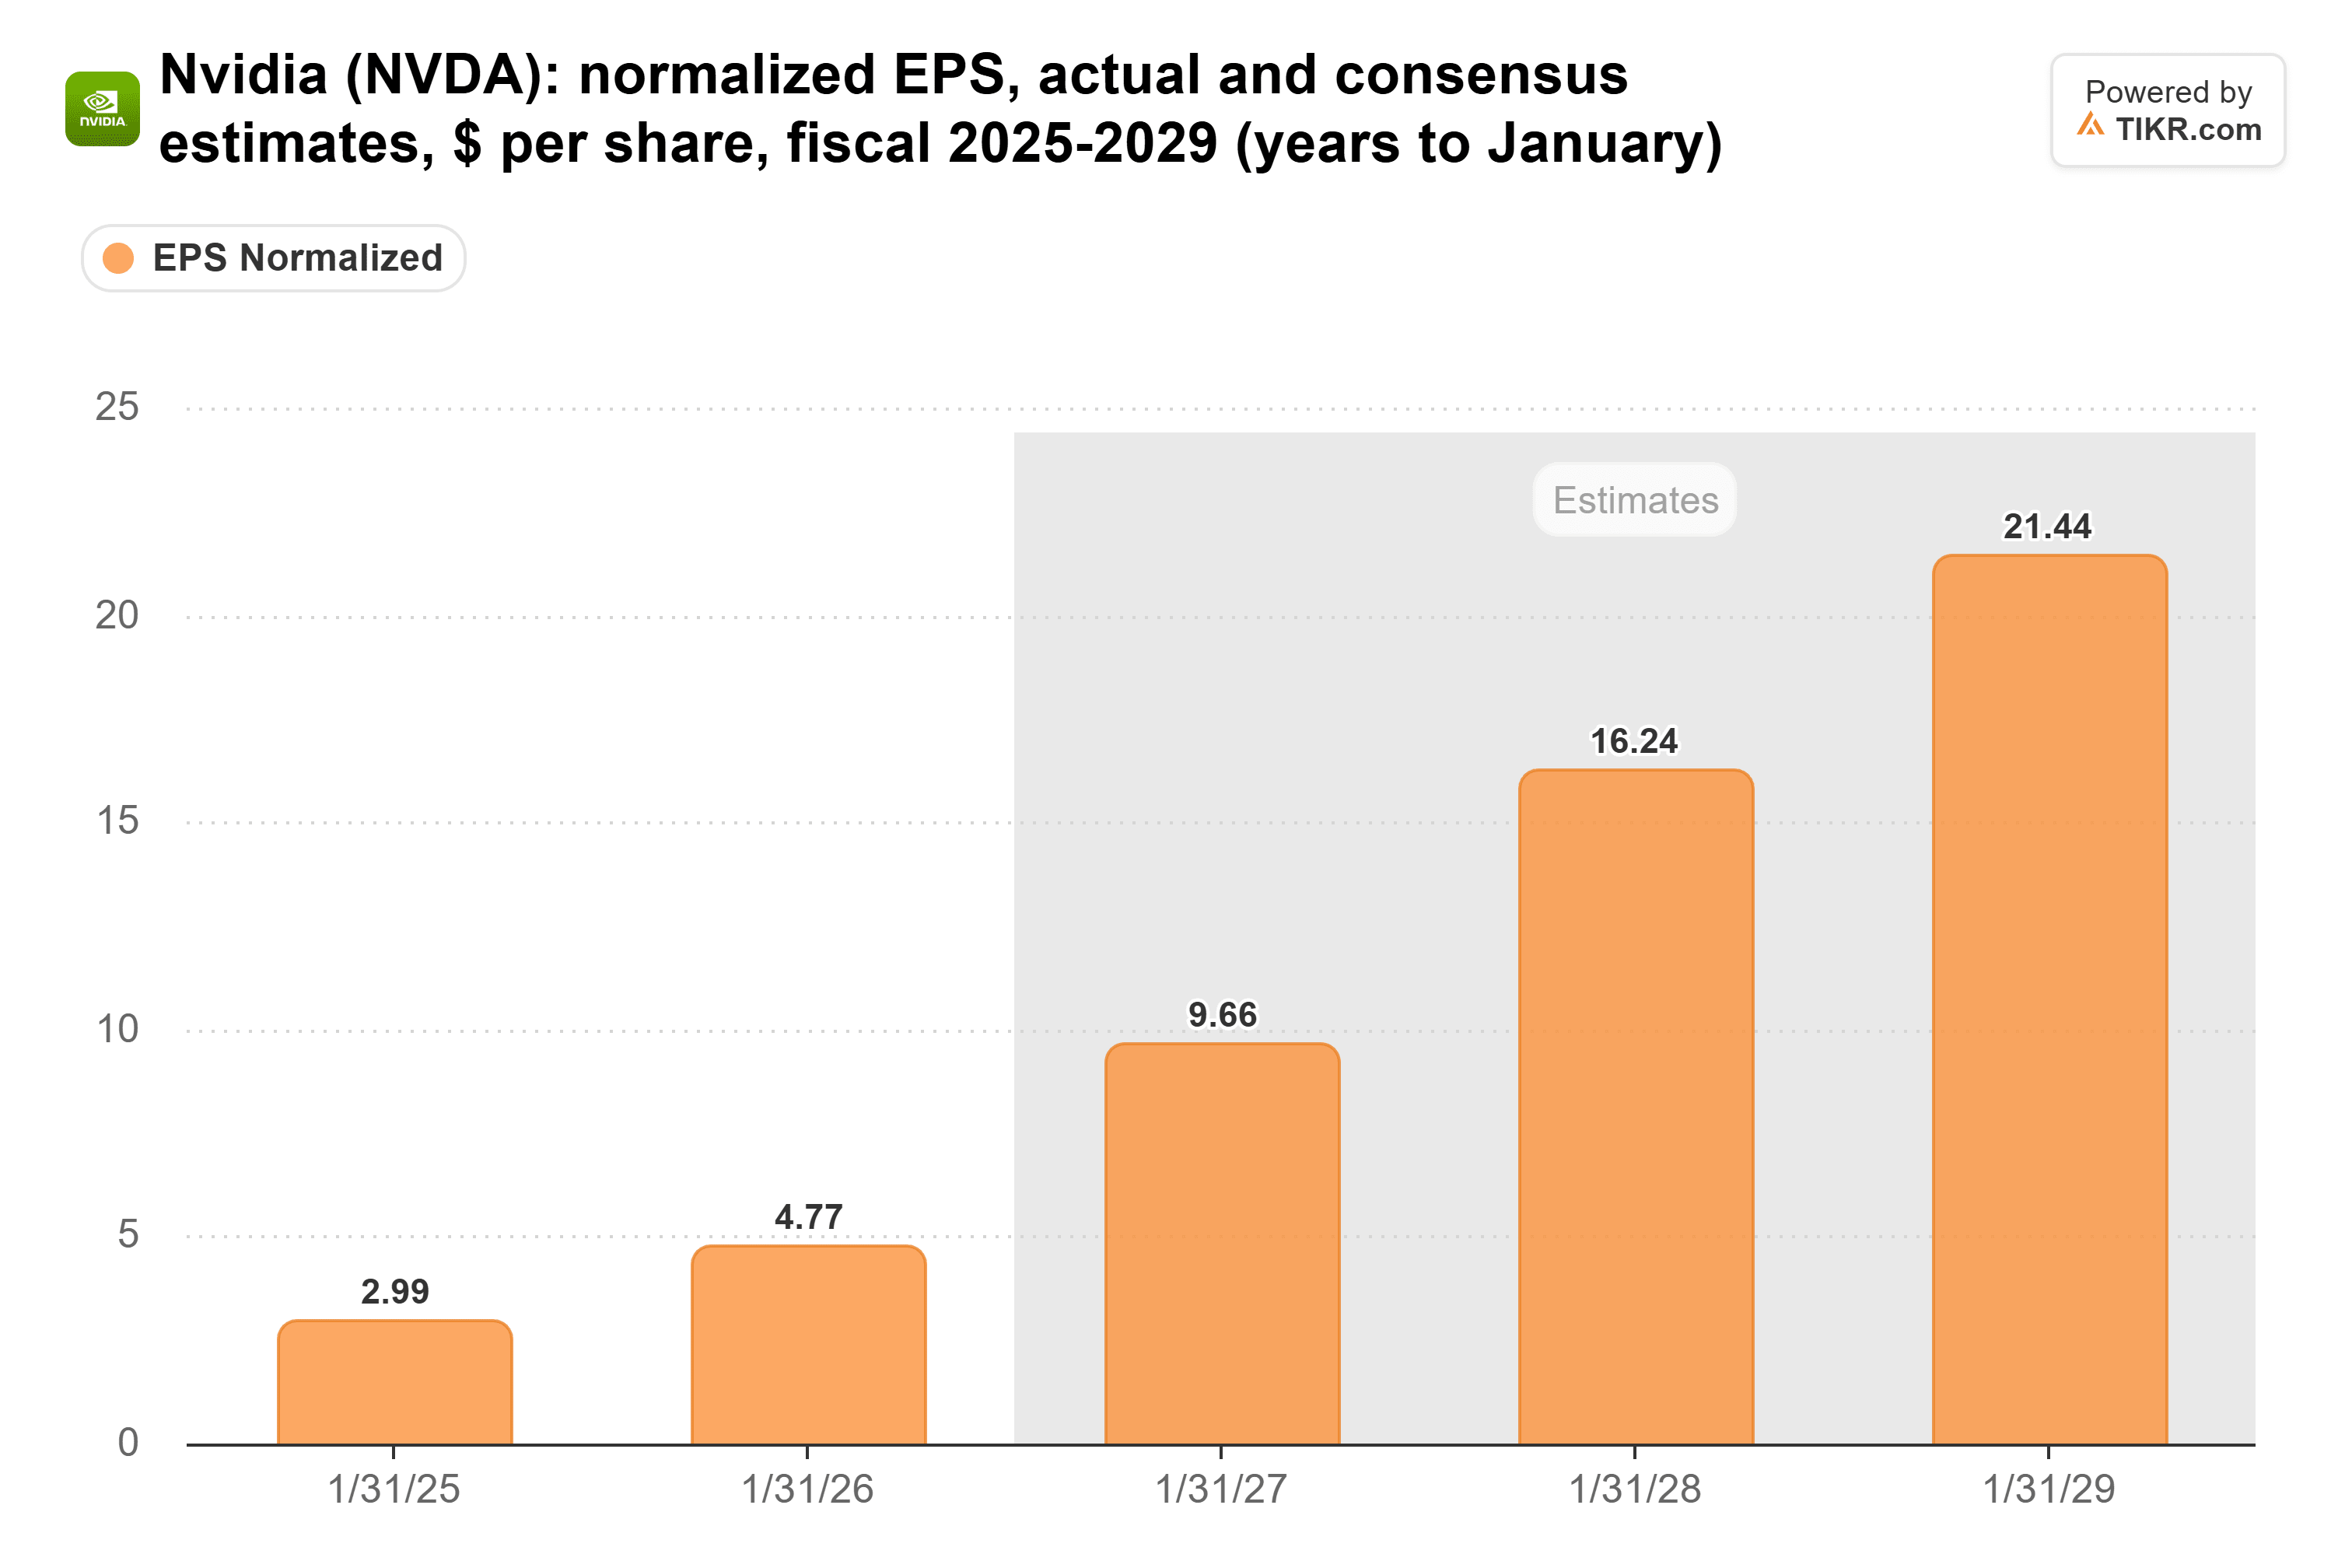
Price the stock on that $16.24 alone, and it trades at about 10x. Whatever discount the market puts on NVIDIA without Huang, it now applies to a lot more profit.
Luria’s slower case is already priced in
Luria thinks tighter credit and political pushback on new data centers could slow the whole AI build-out: “When we say NVIDIA is going to grow 75% next year, that’s a proxy for the whole ecosystem. Maybe we don’t grow 75%. Maybe we grow 25% to 50%.”
But he also thinks the market has priced the slowdown in: “So yeah, the next step could be lower estimates for next year. It looks like that’s already in the stock.”
I agree with him there, and that’s the bull case. At 13x, the stock is already priced for growth well short of 75%, so anything near Kress’s number is upside the market isn’t paying for.
The risk is on NVIDIA’s balance sheet. Customers are taking longer to pay: days sales outstanding rose to 64 from 60 in July.
The next test is the January quarter, reported in late February. If revenue lands near the $130 billion midpoint and gross margin bottoms around the 71.5% NVIDIA guided, Kress’s 75% will look like a number she can hit.
So what is NVIDIA stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what NVIDIA could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!