Key Takeaways
- Ferguson shares jumped 12% today after third-quarter sales rose 9.5% to $9.0 billion and it raised full-year sales guidance to about 7% growth.
- Non-residential sales grew 15% on large projects, while residential grew 6% in a weak housing market.
- Core & Main and Watsco are seeing the same split.
- Ferguson’s deals pushed net debt to 1.7x adjusted EBITDA and paused buybacks, but the quarter earned the jump.
Ferguson Enterprises (FERG) stock jumped 12% today after third-quarter sales of $9.0 billion beat the $8.69 billion analysts expected, and Ferguson raised its full-year guidance.
CEO Kevin Murphy called it “a challenging residential market” on the call, but non-residential sales jumped 15%. Its rivals see the same split: Core & Main (CNM) is getting strong growth from big projects, and Watsco (WSO) is growing residential sales in the same housing market.
Big projects carried the quarter
Organic growth was 7.0%, and acquisitions added 2.7%. Residential grew 6% despite weak new construction and soft repair work in the US. Ferguson credits share gains for the non-residential jump, with open orders growing and bidding strong.
Its year-to-date results and FloWorks, a flow control business it bought on Aug. 31, lifted sales guidance to about 7% growth, from mid-single digits. Adjusted EPS rose 7.9% to $3.43. Going into the report, analysts expected adjusted earnings to keep climbing about 8%-11% a year.
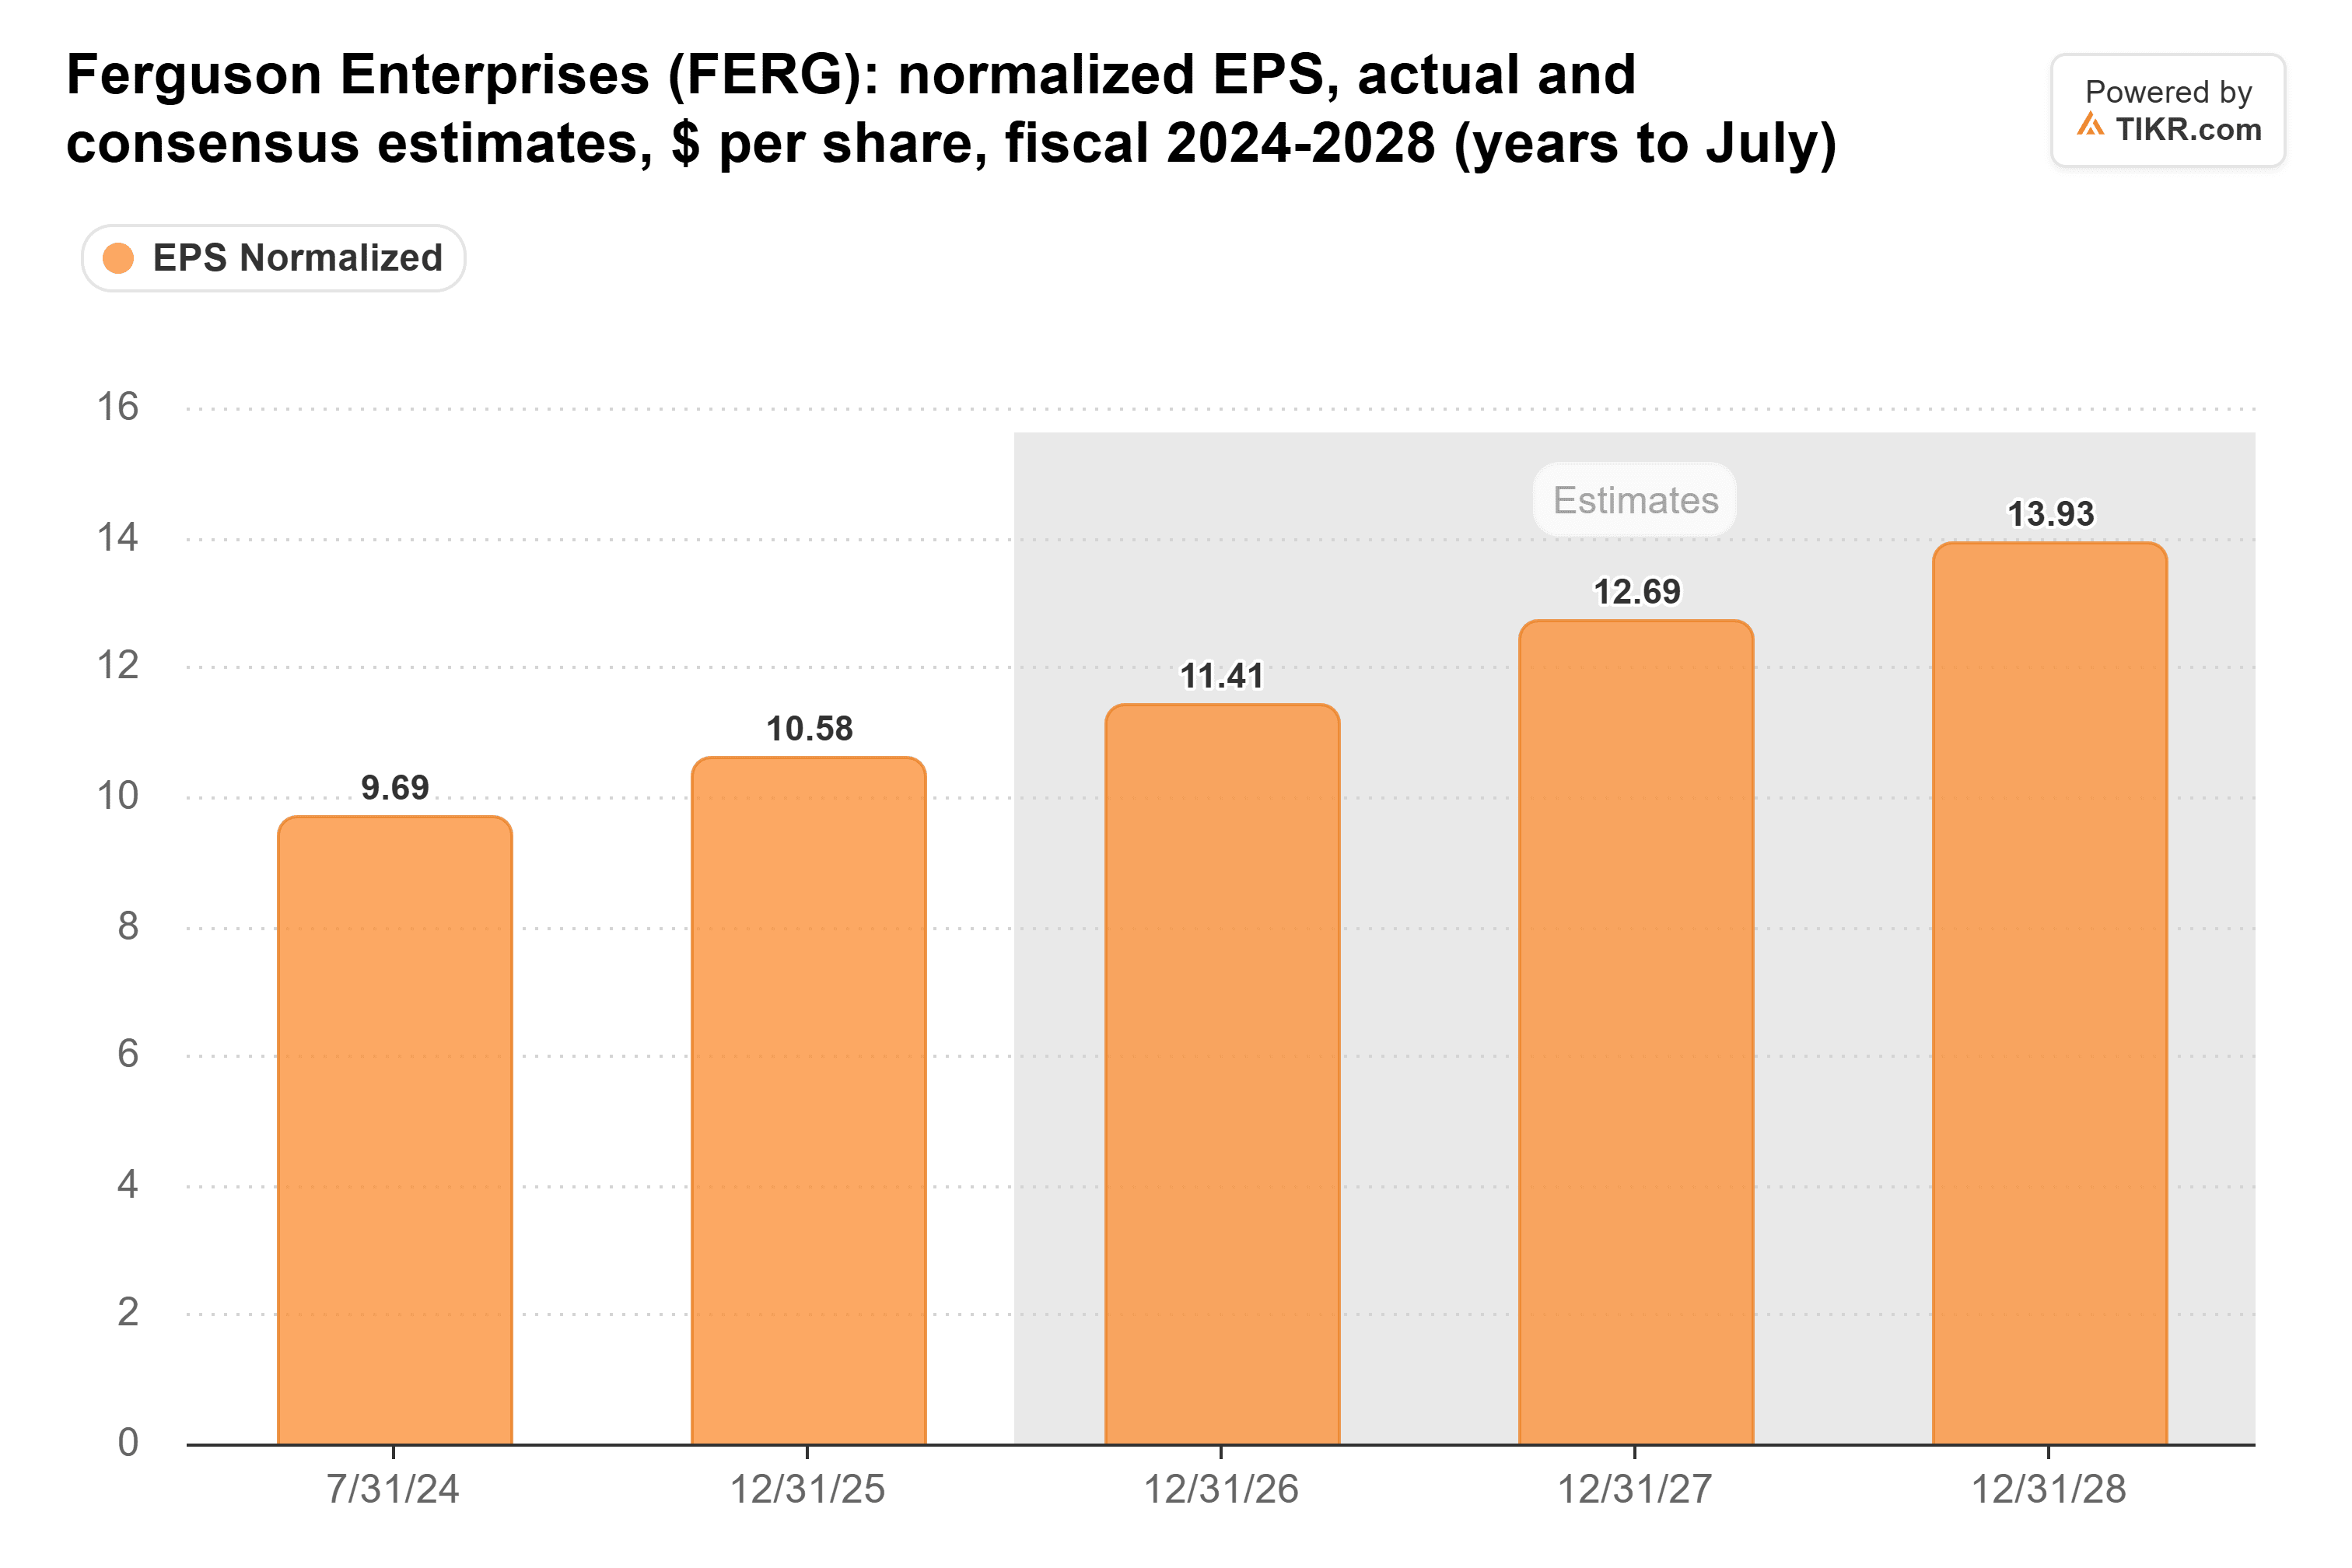
The raised outlook gives them more reason to lift those estimates than cut them, though interest expense guidance rose to about $235 million, from $200 million.
TIKR tracks 24 analysts on Ferguson Enterprises. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Ferguson Enterprises, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Ferguson Enterprises’ Analyst Ratings
Peers are seeing the same split
Core & Main’s sales grew just 2.5% in the quarter to Aug. 2, but CEO Mark Witkowski said “Fire protection and large capital projects, including treatment plants and data centers, delivered strong growth.” Its next report will show whether that demand is lifting everyone or Ferguson is taking share.
Watsco backs up the housing side. Its residential HVAC equipment sales rose 7% in the third quarter, excluding acquisitions, close to Ferguson’s 6%.
The deals come with a bill
Ferguson’s 11 acquisitions this year pushed net debt to 1.7x adjusted EBITDA, from 1.0x a year earlier, and paused buybacks until leverage nears the low end of its 1x-2x target.
And investors are paying up for it. Ferguson traded at 20x forward earnings at the last close, above its five-year average of 19x.
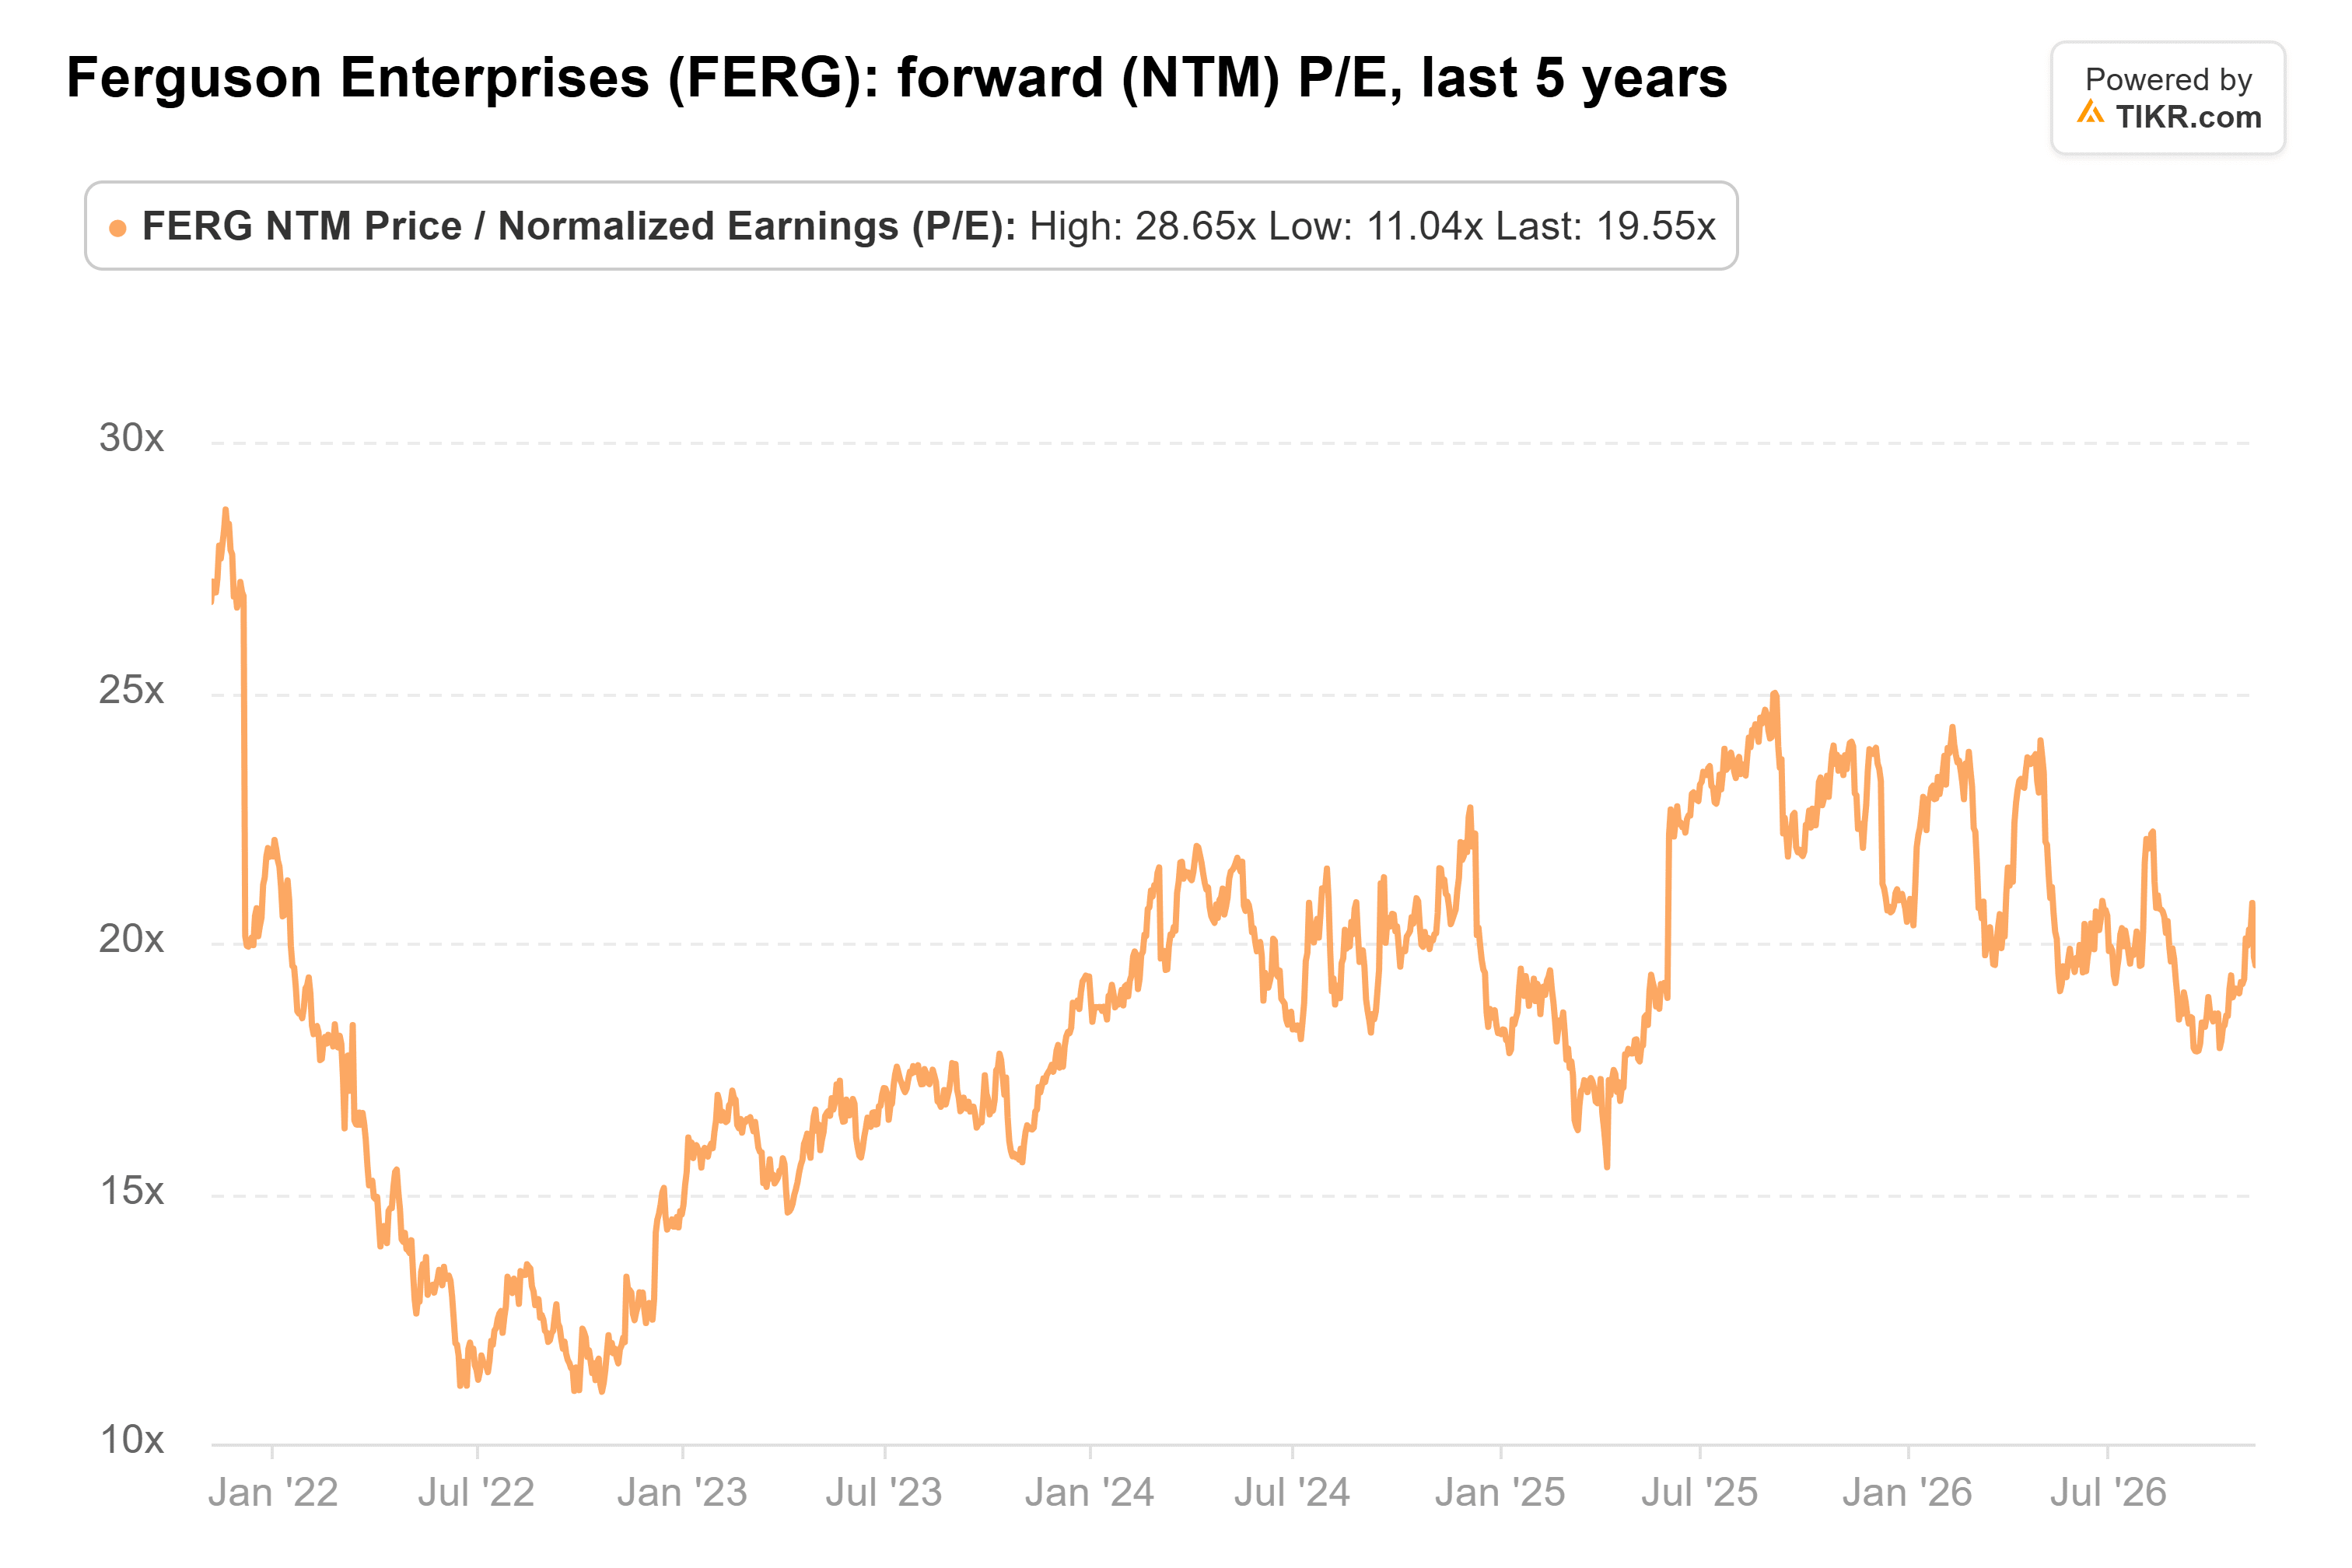
At today’s price, it’s about 22x, though still well short of its late-2021 peak of 29x.
Still, I think the jump is deserved. The risk is that project bidding cools before the debt comes down, so its open orders are the number to watch in its mid-February report.
So what is Ferguson stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Ferguson could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!