Key Takeaways
- Fabrinet shares fell 33% in the past month as AI optics stocks sold off on fears about AI funding, and Lumentum, Marvell and Coherent fell even further.
- Fabrinet’s fiscal first-quarter revenue rose 51% to a record $1.47 billion, and its guidance for this quarter beat what analysts expected.
- Marvell agreed to buy Lumentum, which Northland counts among Fabrinet’s key customers, so it’s not yet clear whether Lumentum’s work stays with Fabrinet.
- Analysts expect earnings to keep climbing, yet the stock trades well below its usual forward multiple. That makes it look like a buy ahead of its February report.
Fabrinet (FN) stock is down 33% in the past month, despite record revenue in its latest quarter.
The whole AI optics trade sold off. The Nasdaq 100 fell 14% over the same month, but Lumentum (LITE), which Northland counts among Fabrinet’s key customers, lost 52%. Marvell Technology (MRVL), which agreed on Nov. 2 to buy Lumentum, lost 51%, and Coherent (COHR) fell 43%.
Wall Street got nervous about who pays for AI
On Oct. 12, Broadcom CEO Hock Tan said capital might become the biggest limit on the AI buildout, and Intel CEO Lip-Bu Tan raised the same worry on the same panel. Optical stocks slid in the sessions that followed, and Fabrinet lost 19% from its Oct. 9 close to its Oct. 14 close. Analysts cut their targets going into the report: B. Riley twice, to $385 from $598, Susquehanna to $600 from $850, and JPMorgan to $465 from $695.
Demand at Lumentum is holding up: StoneX gave it a Buy and a $1,200 target when it initiated coverage on Oct. 26, arguing Lumentum is sold out into 2029. But Lumentum’s holders will get a fixed 4.5 Marvell shares for each Lumentum share, so since the deal, its stock has mostly tracked Marvell’s. For Fabrinet, the question is whether Marvell keeps the Lumentum work Fabrinet builds once the deal closes, which the companies expect in the first half of 2028.
StoneX also gave Coherent a Buy and a $425 target that day. Coherent still fell harder than Fabrinet, a sign that investors are worried about AI spending as a whole.
TIKR tracks 9 analysts on Fabrinet. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Fabrinet, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Fabrinet’s Analyst Ratings
The quarter was a blowout
Fabrinet’s report after the close on Nov. 2 showed a business growing fast. In the fiscal first quarter, the three months to Sept. 25, revenue jumped 51% year over year to a record $1.47 billion, ahead of the $1.4 billion analysts expected. Non-GAAP EPS climbed to $4.34 from $2.92, against $4.19 expected. Data center revenue rose 78% to $777 million, more than half the total. CEO Seamus Grady credited “broad-based demand across multiple significant programs” and new products ramping up.
The outlook was even better. Management guided this quarter’s revenue to 1.6-1.65 billion, against $1.48 billion expected, and non-GAAP EPS to 4.77-4.92, against $4.43. The board also added $103 million to its buyback, leaving about $200 million available. The stock jumped 15% on Nov. 3, then gave most of that back by Friday, including a 14% drop on Nov. 5, when the Nasdaq 100 had its worst day since March 2020.
The estimates keep climbing
Analysts expect Fabrinet’s earnings to keep growing for years:
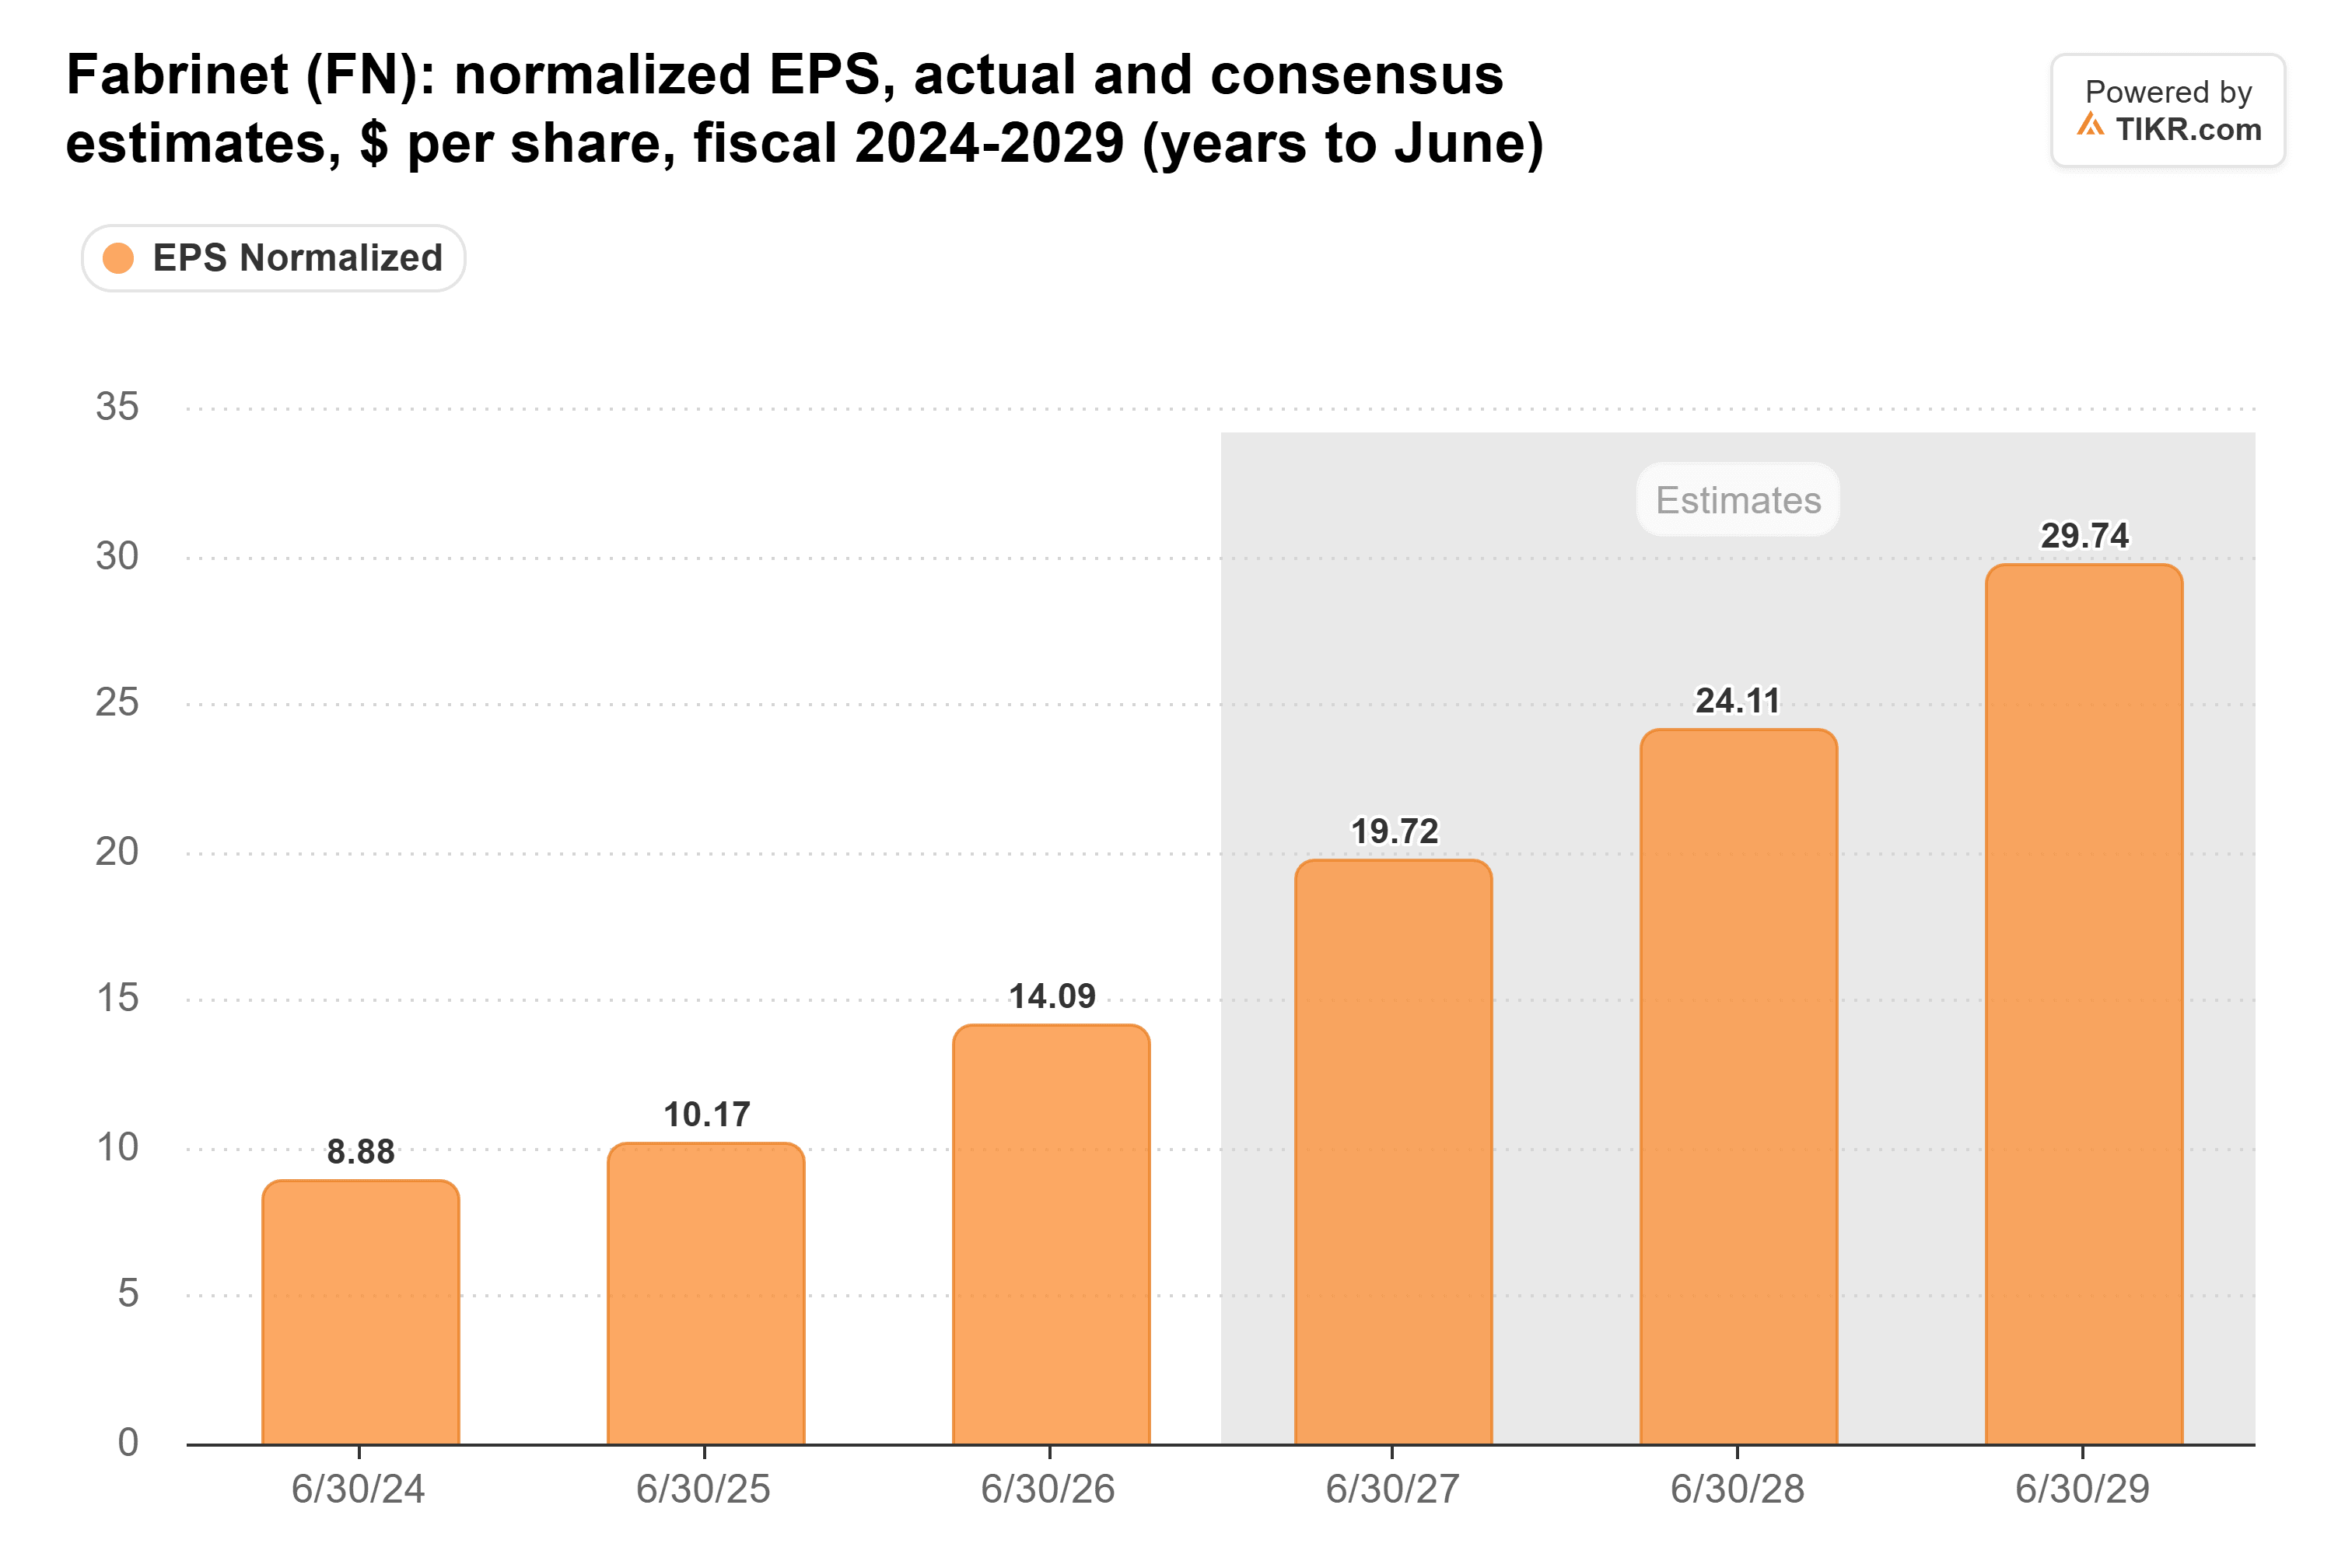
Consensus calls for normalized EPS of $19.72 in fiscal 2027 (the year to June 2027) and $24.11 in fiscal 2028, up from $14.09 in fiscal 2026. Analysts have already raised that fiscal 2028 figure from $21.96 before the report, and this quarter’s guidance gives them no reason to cut it.
Yet the stock is cheap against its own history:
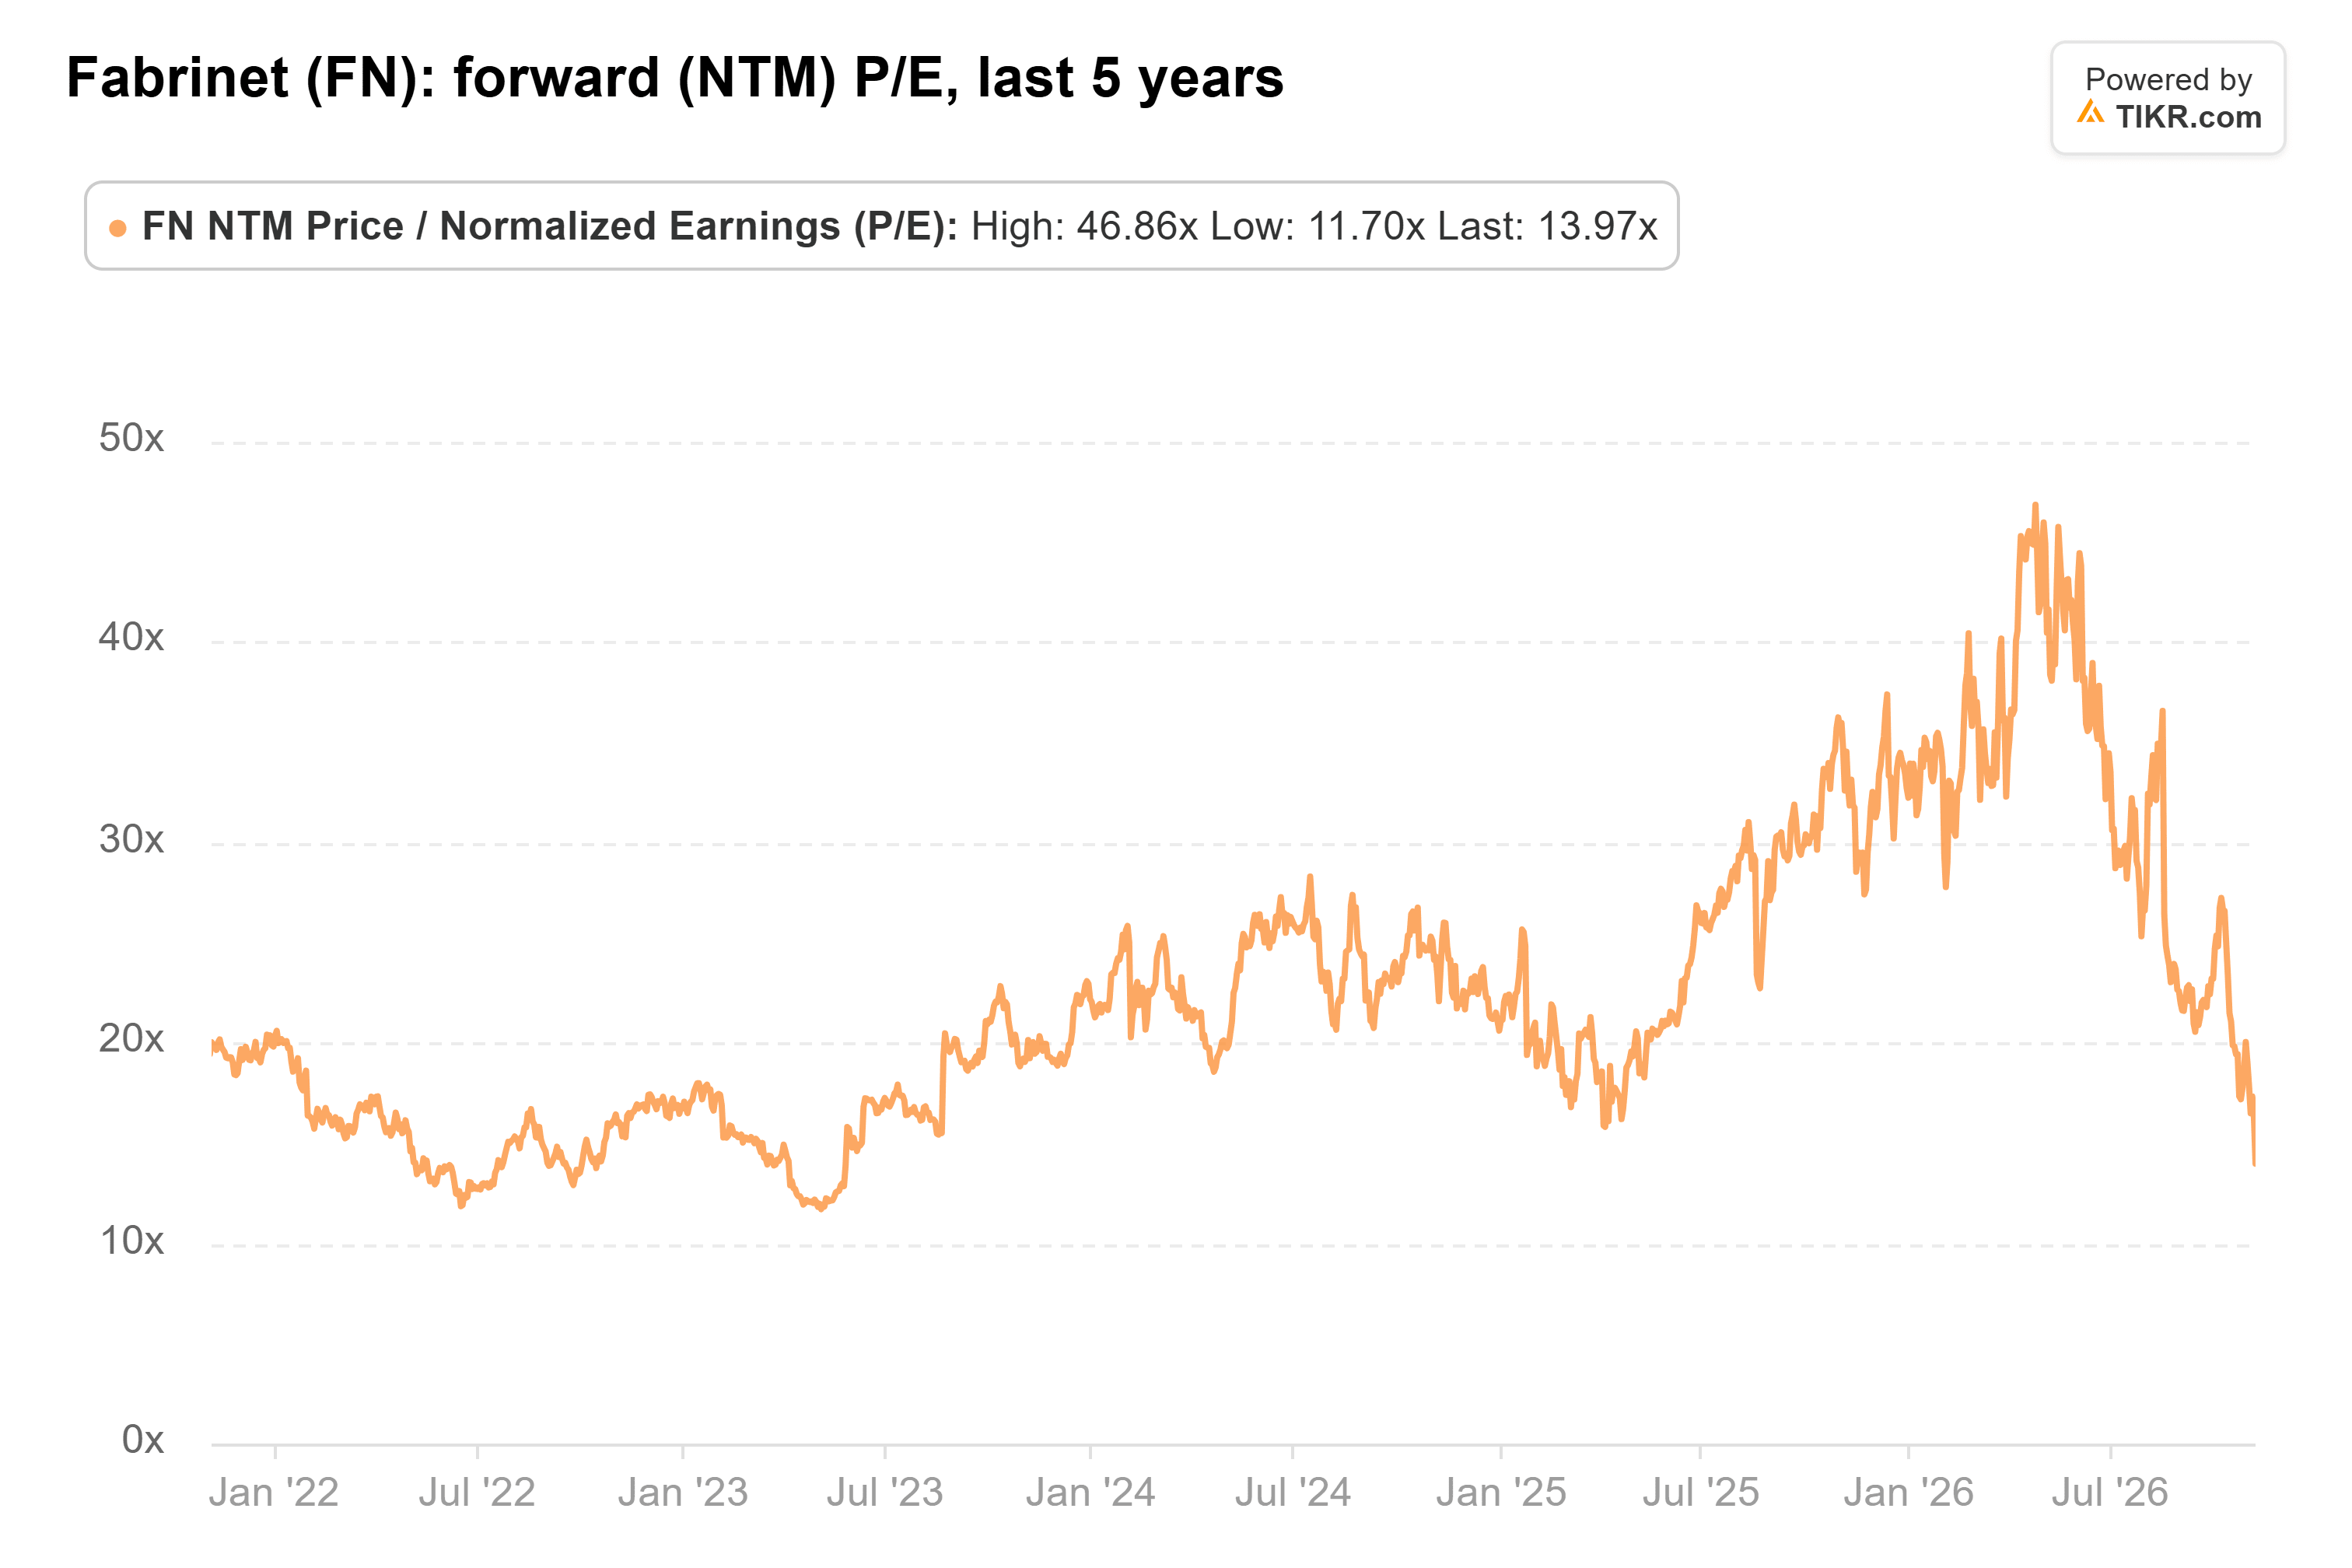
At the Nov. 5 close, Fabrinet traded at 14x forward earnings, against a five-year average of 22x. Even after Friday’s bounce, it sits well under that average.
Time to load up
Barclays, JPMorgan and B. Riley all updated their targets after the report, and all three sit above Friday’s close. Barclays cut to $496 and kept its Overweight rating. JPMorgan raised to $475 and B. Riley cut to $364, both with Neutral ratings. Fabrinet lists its reliance on a small number of customers among its risks, so a lot rides on Lumentum’s work staying put under Marvell, and on the hyperscalers’ budgets. The new capacity isn’t cheap, either: free cash flow was an outflow of $137 million in the quarter.
Fabrinet looks like a buy at this price, and estimates should keep rising as long as AI spending holds up. The next check is the fiscal second-quarter report in early February. If the big spenders cut their budgets before then, analysts would have good reason to lower those numbers.
So what is Fabrinet stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Fabrinet could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!