Key Takeaways
- Everpure shares rose 12% after fiscal third-quarter revenue grew 51% to $1.46 billion, ahead of the $1.33 billion analysts expected.
- Everpure is giving up gross margin to win share, and its profit guidance went up much more than its revenue guidance, which shows the trade is paying off.
- Rivals NetApp and HPE both report in the next two weeks.
- The stock traded at 28x forward earnings before today’s jump, below its five-year average of 31x.
Everpure (P) shares jumped 12% today after fiscal third-quarter revenue grew 51% to $1.46 billion, well ahead of the $1.33 billion analysts expected. It also raised its full-year guidance for the third straight quarter.
The growth came from hardware: product revenue rose 77%, against 19% for subscriptions. CEO Charles Giancarlo called it “a market share game” on Wednesday’s call, and the other players are NetApp (NTAP) and HPE (HPE).
Profit is growing faster than sales
Everpure now expects fiscal 2027 revenue of $5.20 billion-$5.21 billion, up from $5.03 billion-$5.07 billion. It raised its non-GAAP operating income guide by about 14% at the midpoint, to $1.08 billion-$1.09 billion. The revenue guide rose only about 3%. The quarter’s non-GAAP operating margin rose to 23.6% from 20.3% a year earlier. Analysts expect normalized EPS of $2.81 this fiscal year and $4.22 next year:
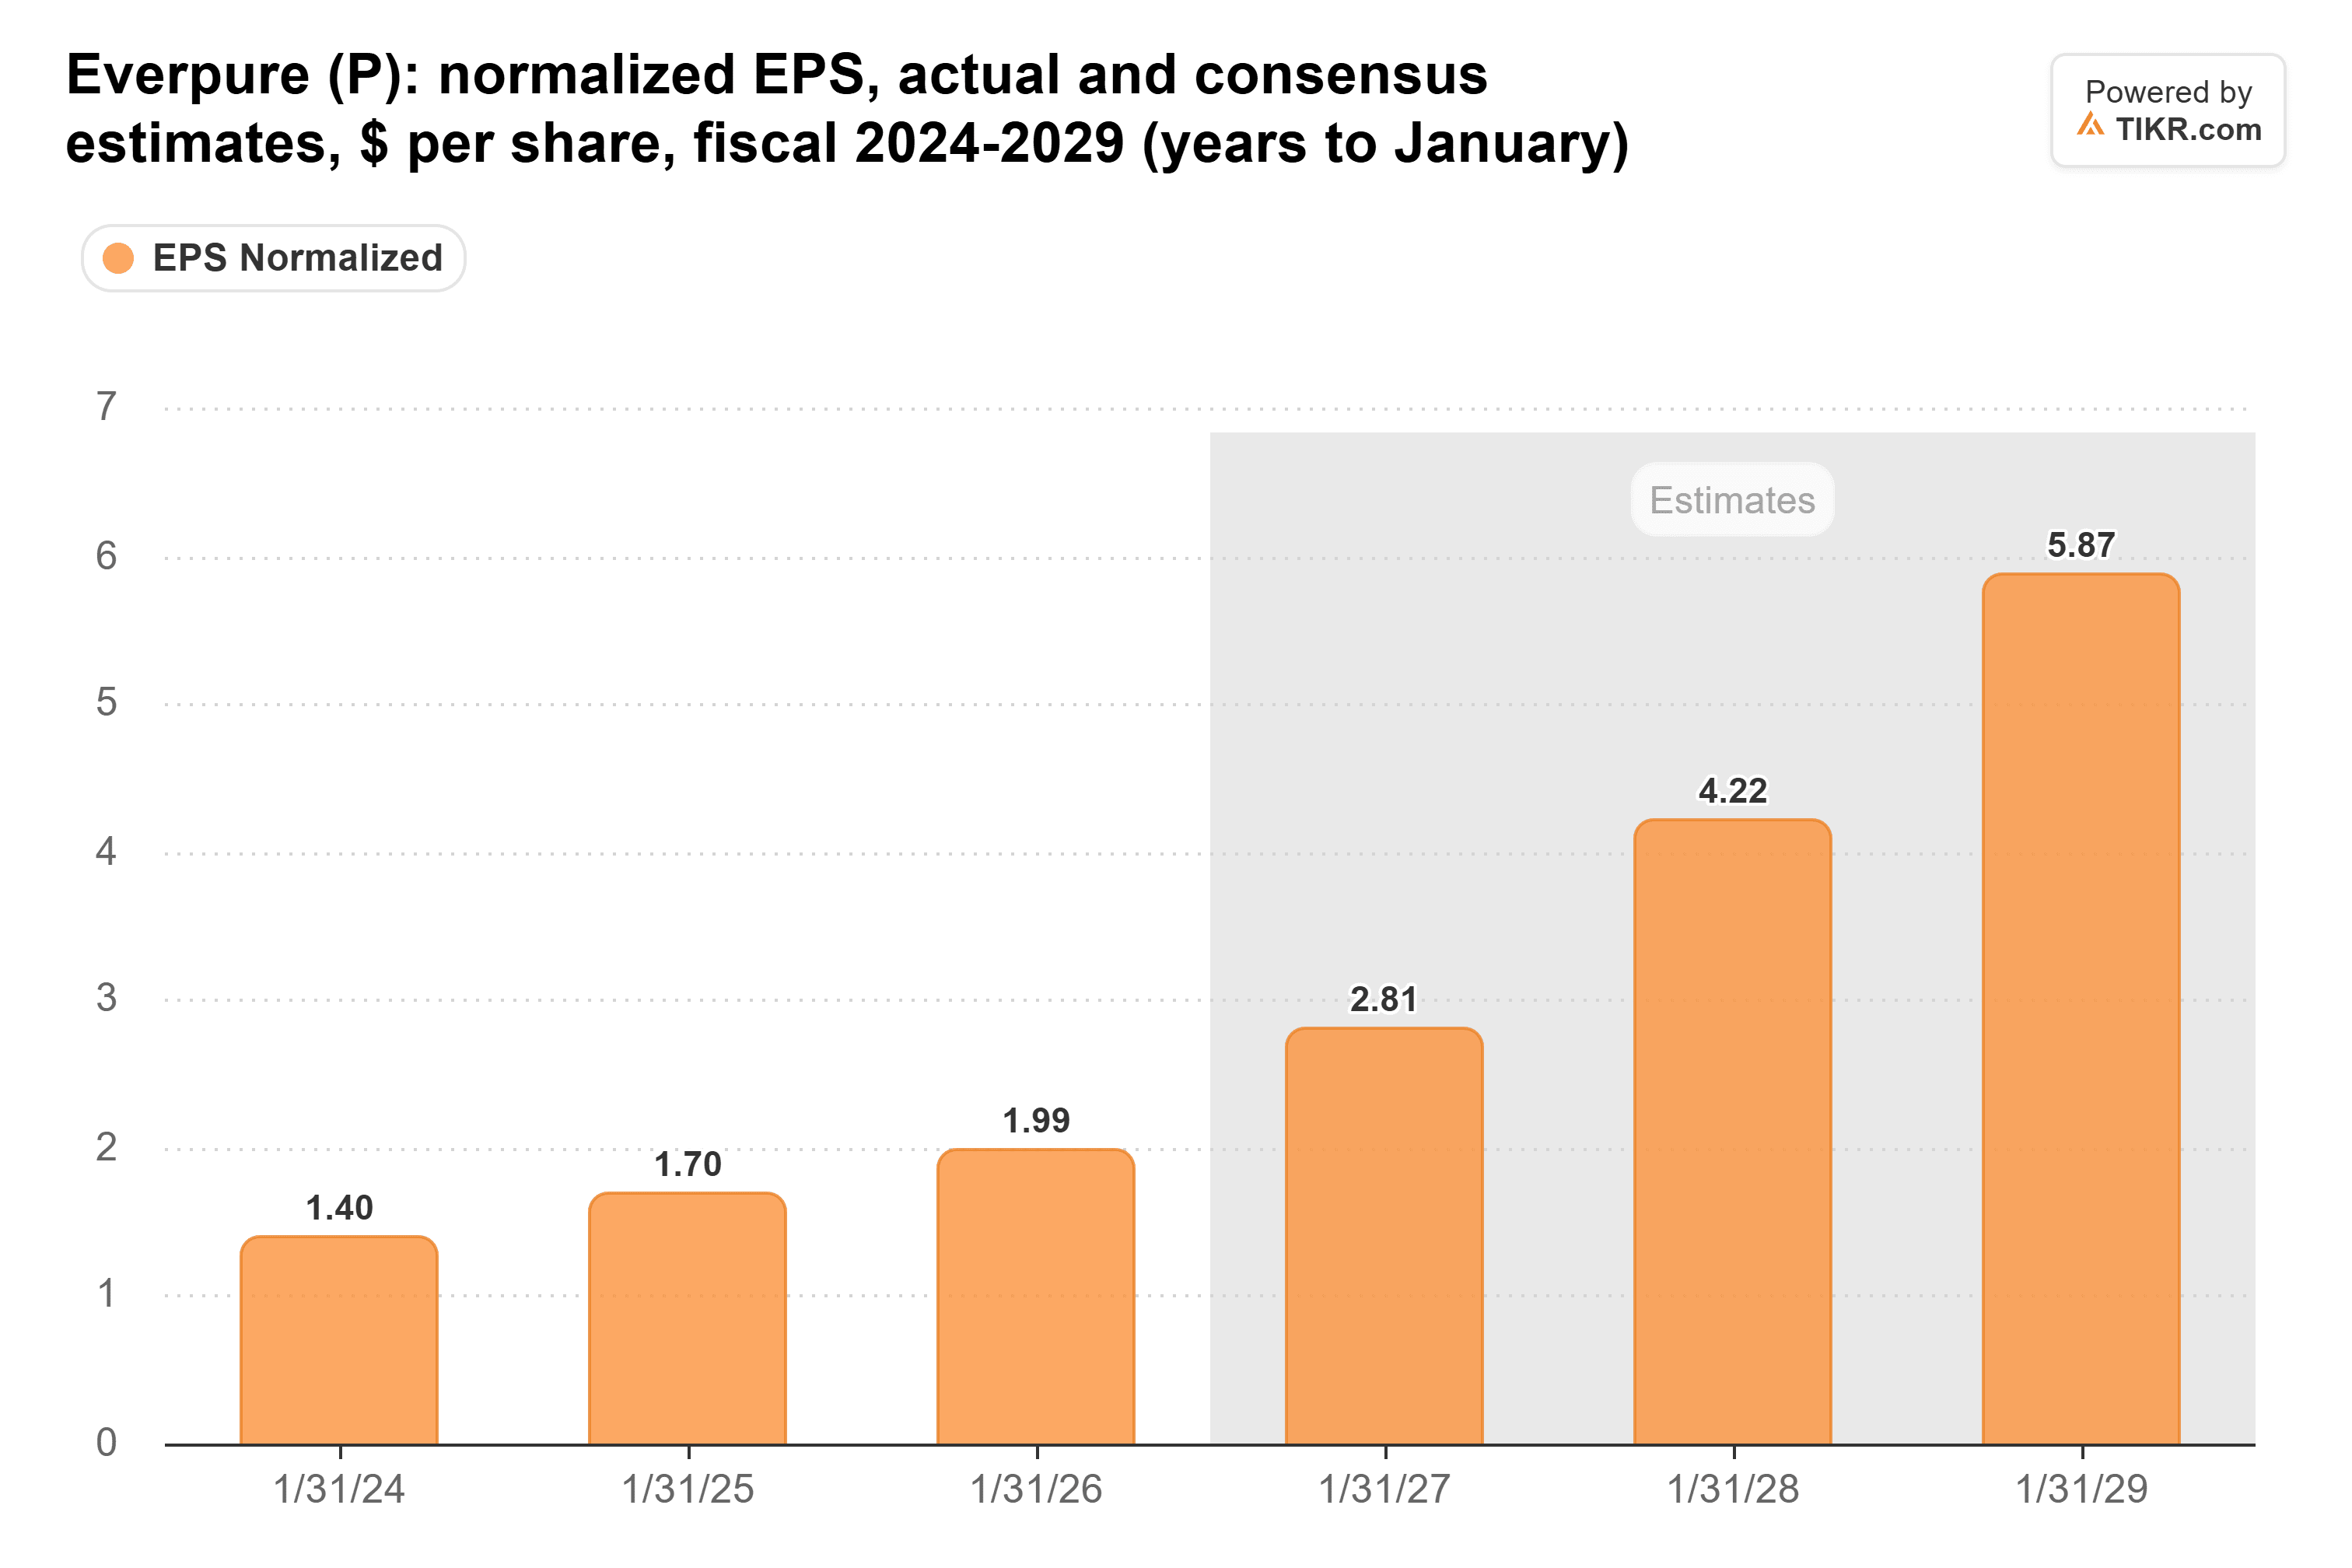
The bigger profit guide should push this year’s figure higher.
The stock still isn’t expensive against its own history. It traded at 28x forward earnings at Wednesday’s close, below its five-year average of 31x:
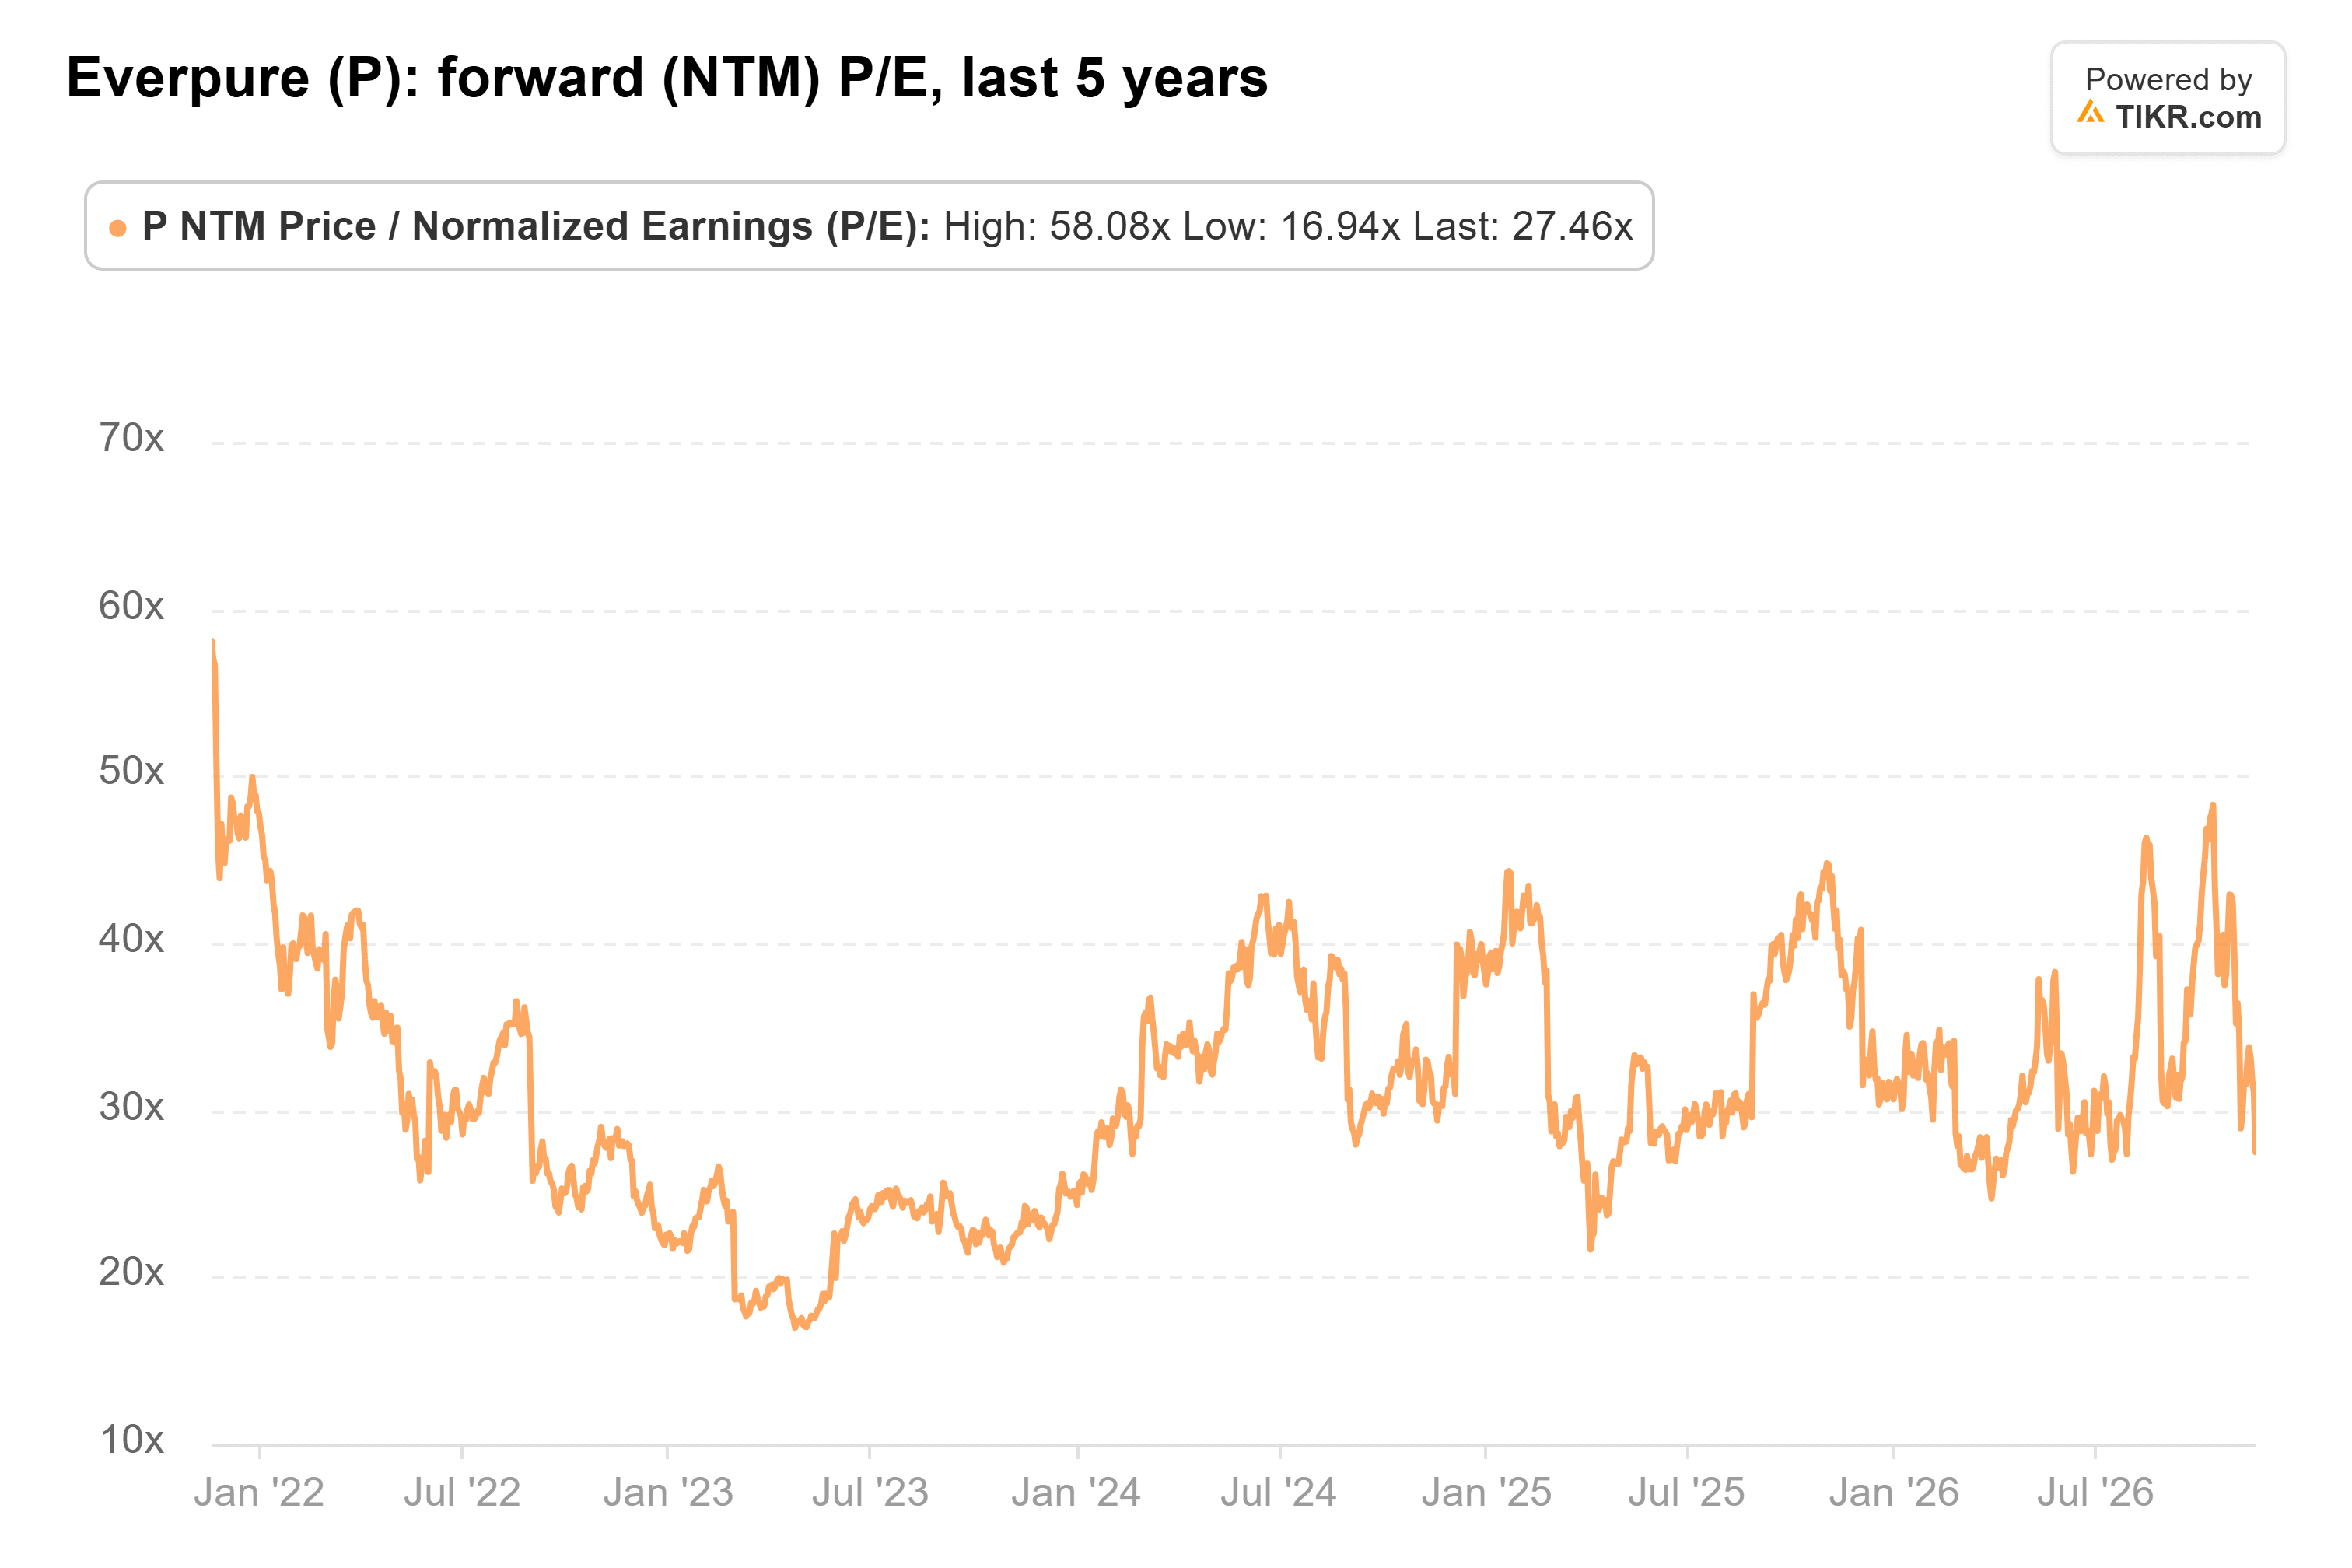
At today’s price, it’s about 30x, still under that average.
TIKR tracks 20 analysts on Everpure. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Everpure, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Everpure’s Analyst Ratings
Gross margin is the price of share
The catch is gross margin, which has slipped for four straight quarters:
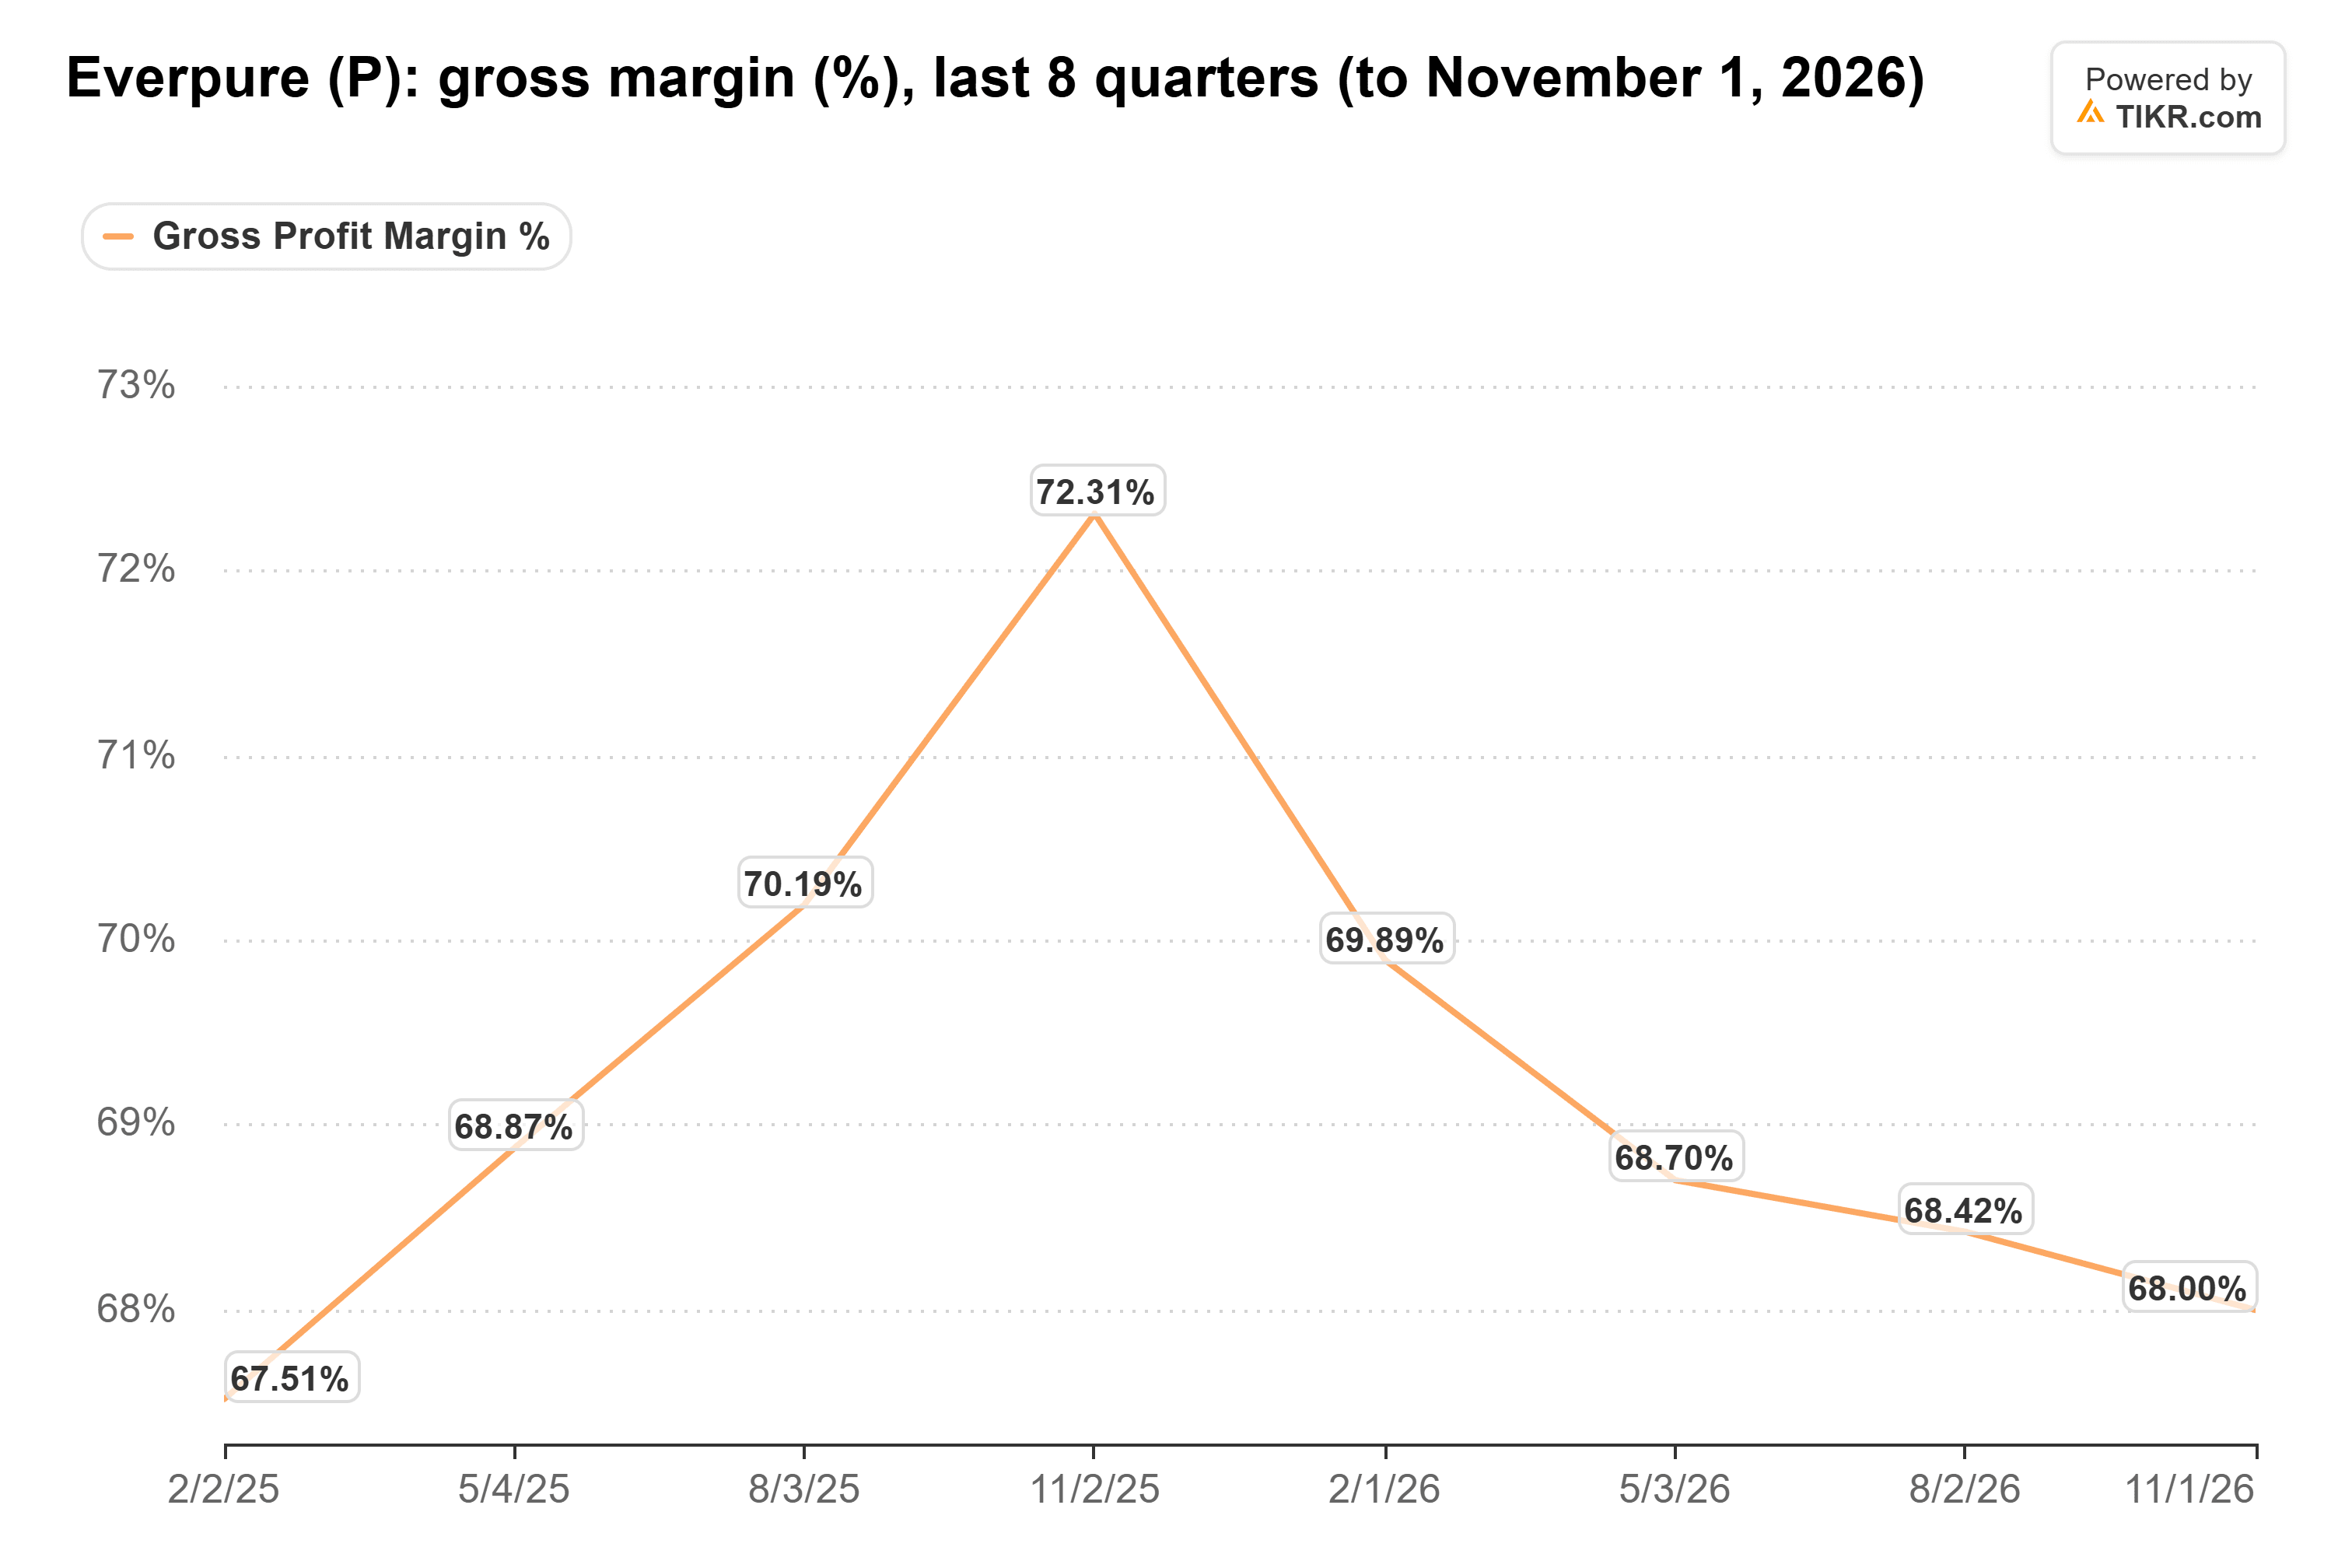
Most of that came from the hardware itself, where gross margin fell to 66.7% from 71.6% a year earlier. Barclays cut its price target this morning, citing pricing concerns.
NetApp is holding up so far: its all-flash array revenue jumped 47% to $1.3 billion in its July quarter. But it guided October-quarter non-GAAP gross margin to 67%-68%, down from 70.6%. Does it land inside that range when it reports in early December?
HPE looks more exposed. Its storage revenue grew just 10% to $1.3 billion in its July quarter, and it reports next week. If its growth keeps trailing Everpure’s by that much, Everpure is taking share from HPE.
A trade worth making
Four points of gross margin for 51% growth and a rising operating margin is a trade I’d happily make. The next check comes with fourth-quarter results early next year. Revenue of at least $1.50 billion and non-GAAP operating income of at least $350 million, the low end of the guide, would show it still works.
So what is Everpure stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Everpure could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!