

Key Takeaways
- Altria Group yields 5.7% and raised its dividend 4.7% in August 2026, and BP yields 4.6%.
- BP’s dividend took 31% of its free cash flow over its latest reported twelve months, against 78% for Altria’s.
- BP’s free cash flow swings widely, and it paid $0.33 a share in fiscal 2025, against $0.40 in fiscal 2015.
- BP CEO Meg O’Neill presents her long-term strategy in December, the next sign of how fast BP’s dividend can grow.
Altria Group (MO) raised its quarterly dividend 4.7% to $1.11 a share in August, its 57th increase in 61 years. That leaves it yielding 5.7%.
BP (BP) has spent the fall selling assets and paying down debt. CEO Meg O’Neill said on its third-quarter call that “the dividend is the first call on capital.” BP yields a lower 4.6%, but its dividend uses far less of its cash.
Both companies are selling less of their core product: fewer cigarettes at Altria, and softer fuel demand at BP’s retail sites. So if you could buy only one and collect for the next 20 years, which should it be?
| Metric | Altria Group (MO) | BP (BP) |
|---|---|---|
| Dividend yield | 5.7% | 4.6% |
| Dividend growth, fiscal 2020-2025 | 4.1% a year | 0.6% a year |
| Dividend growth, fiscal 2015-2025 | 6.3% a year | -1.9% a year |
| Cash dividend payout ratio (TTM) | 78% | 31% |
| Net debt/EBITDA | 1.7x | 0.5x |
| Interest coverage | 10.9x | 6.0x |
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Altria pays out most of its cash, and has for years
Altria is shipping fewer cigarettes, but it’s still growing earnings. Management raised its 2026 guidance to adjusted EPS of $5.66 to $5.74, growth of 4.5% to 6.0% from $5.42 in 2025, with nicotine pouches as its growth business.
The cash behind the dividend is steady. Free cash flow was $8.15 billion in fiscal 2020 and $9.07 billion in fiscal 2025, and it has topped dividends paid every fiscal year since 2018:
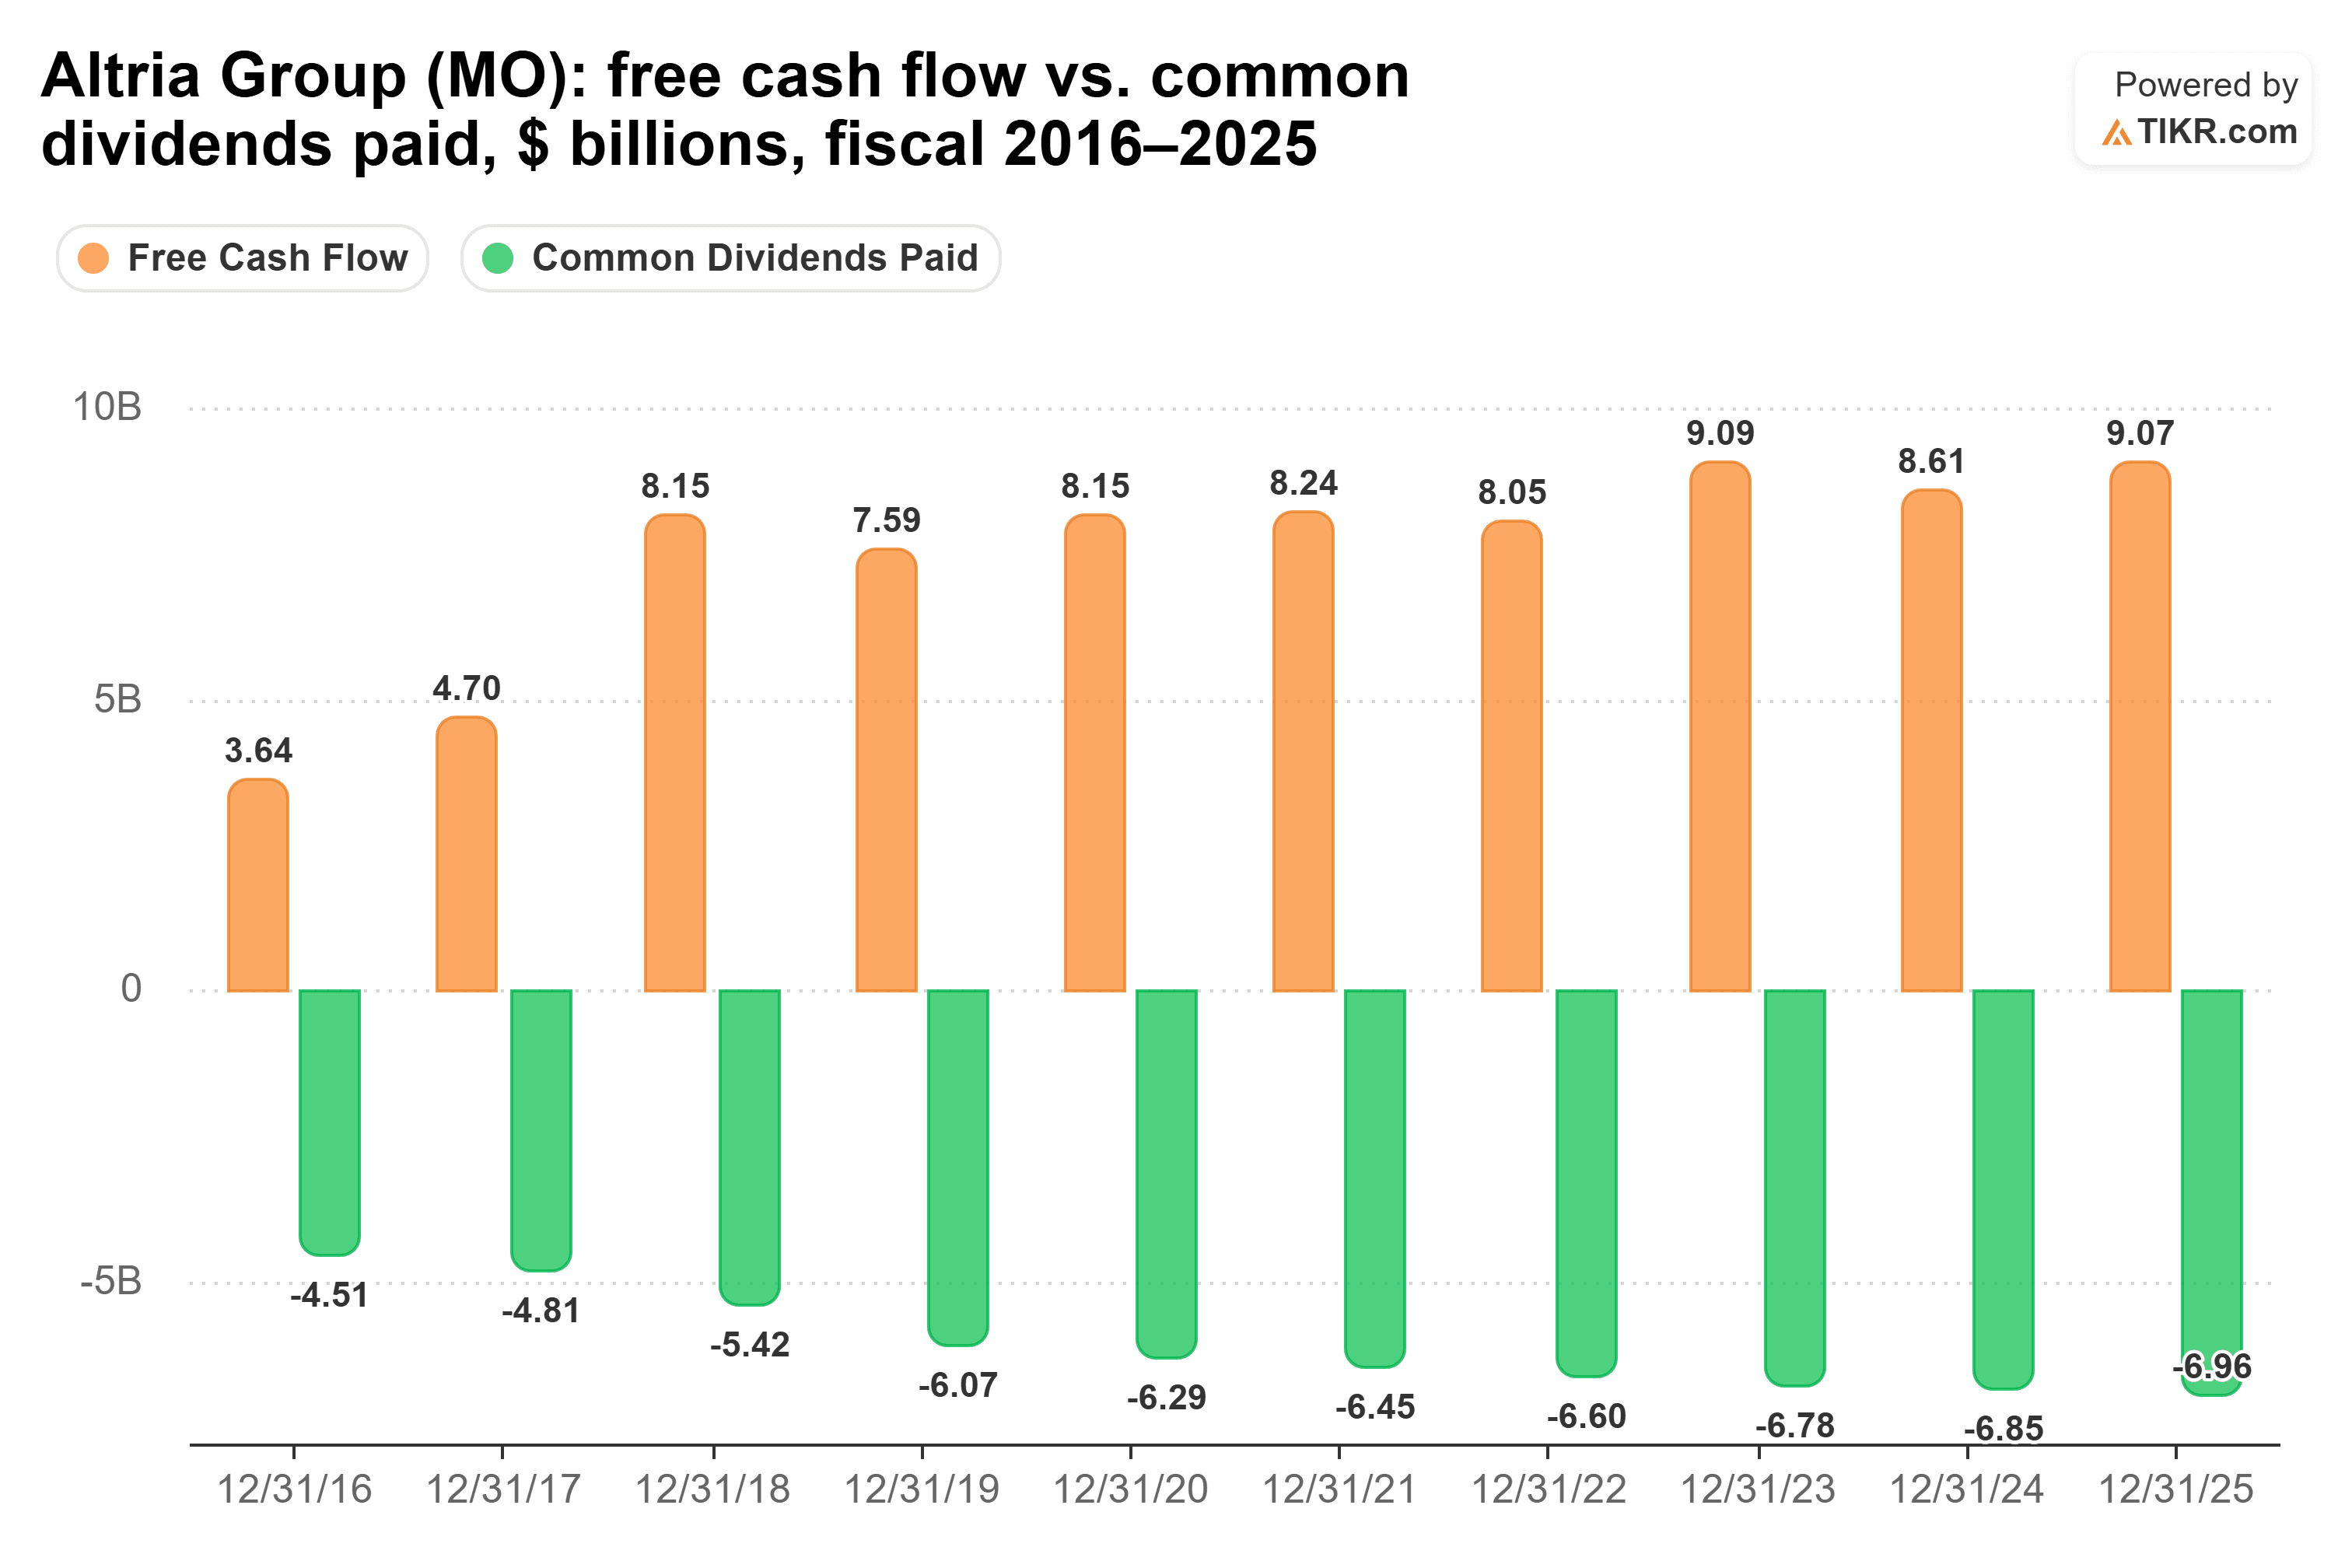
(It fell short in fiscal 2016 and 2017.)
Altria’s cash dividend payout ratio was 78% over the twelve months to Sept. 30, 2026, and it ranged from 75% to 82% in every fiscal year from 2021 to 2025: high but steady. Management targets “mid-single digits dividend per share growth annually through 2028,” which leaves free cash flow to do the growing.
At its 4.1% 5-year rate, $10,000 in Altria pays $570 a year now and about $1,227 in year 20, a 12.3% yield on the original $10,000. The risk is a cigarette decline that outruns Marlboro’s pricing and the pouches.
BP has the bigger cushion, on a cash flow that swings
BP comes at it from the other direction. Its latest quarter was strong: underlying replacement cost profit was $8.5 billion in the third quarter of 2026, against $5.7 billion in the second, and net debt fell from $22.3 billion to $13.87 billion.
BP’s cash dividend payout ratio was a comfortable 31% over the twelve months to June 30, 2026. But free cash flow went negative in fiscal 2016 and fiscal 2020, and it went from $28.9 billion in fiscal 2022 to $11.3 billion in fiscal 2025:
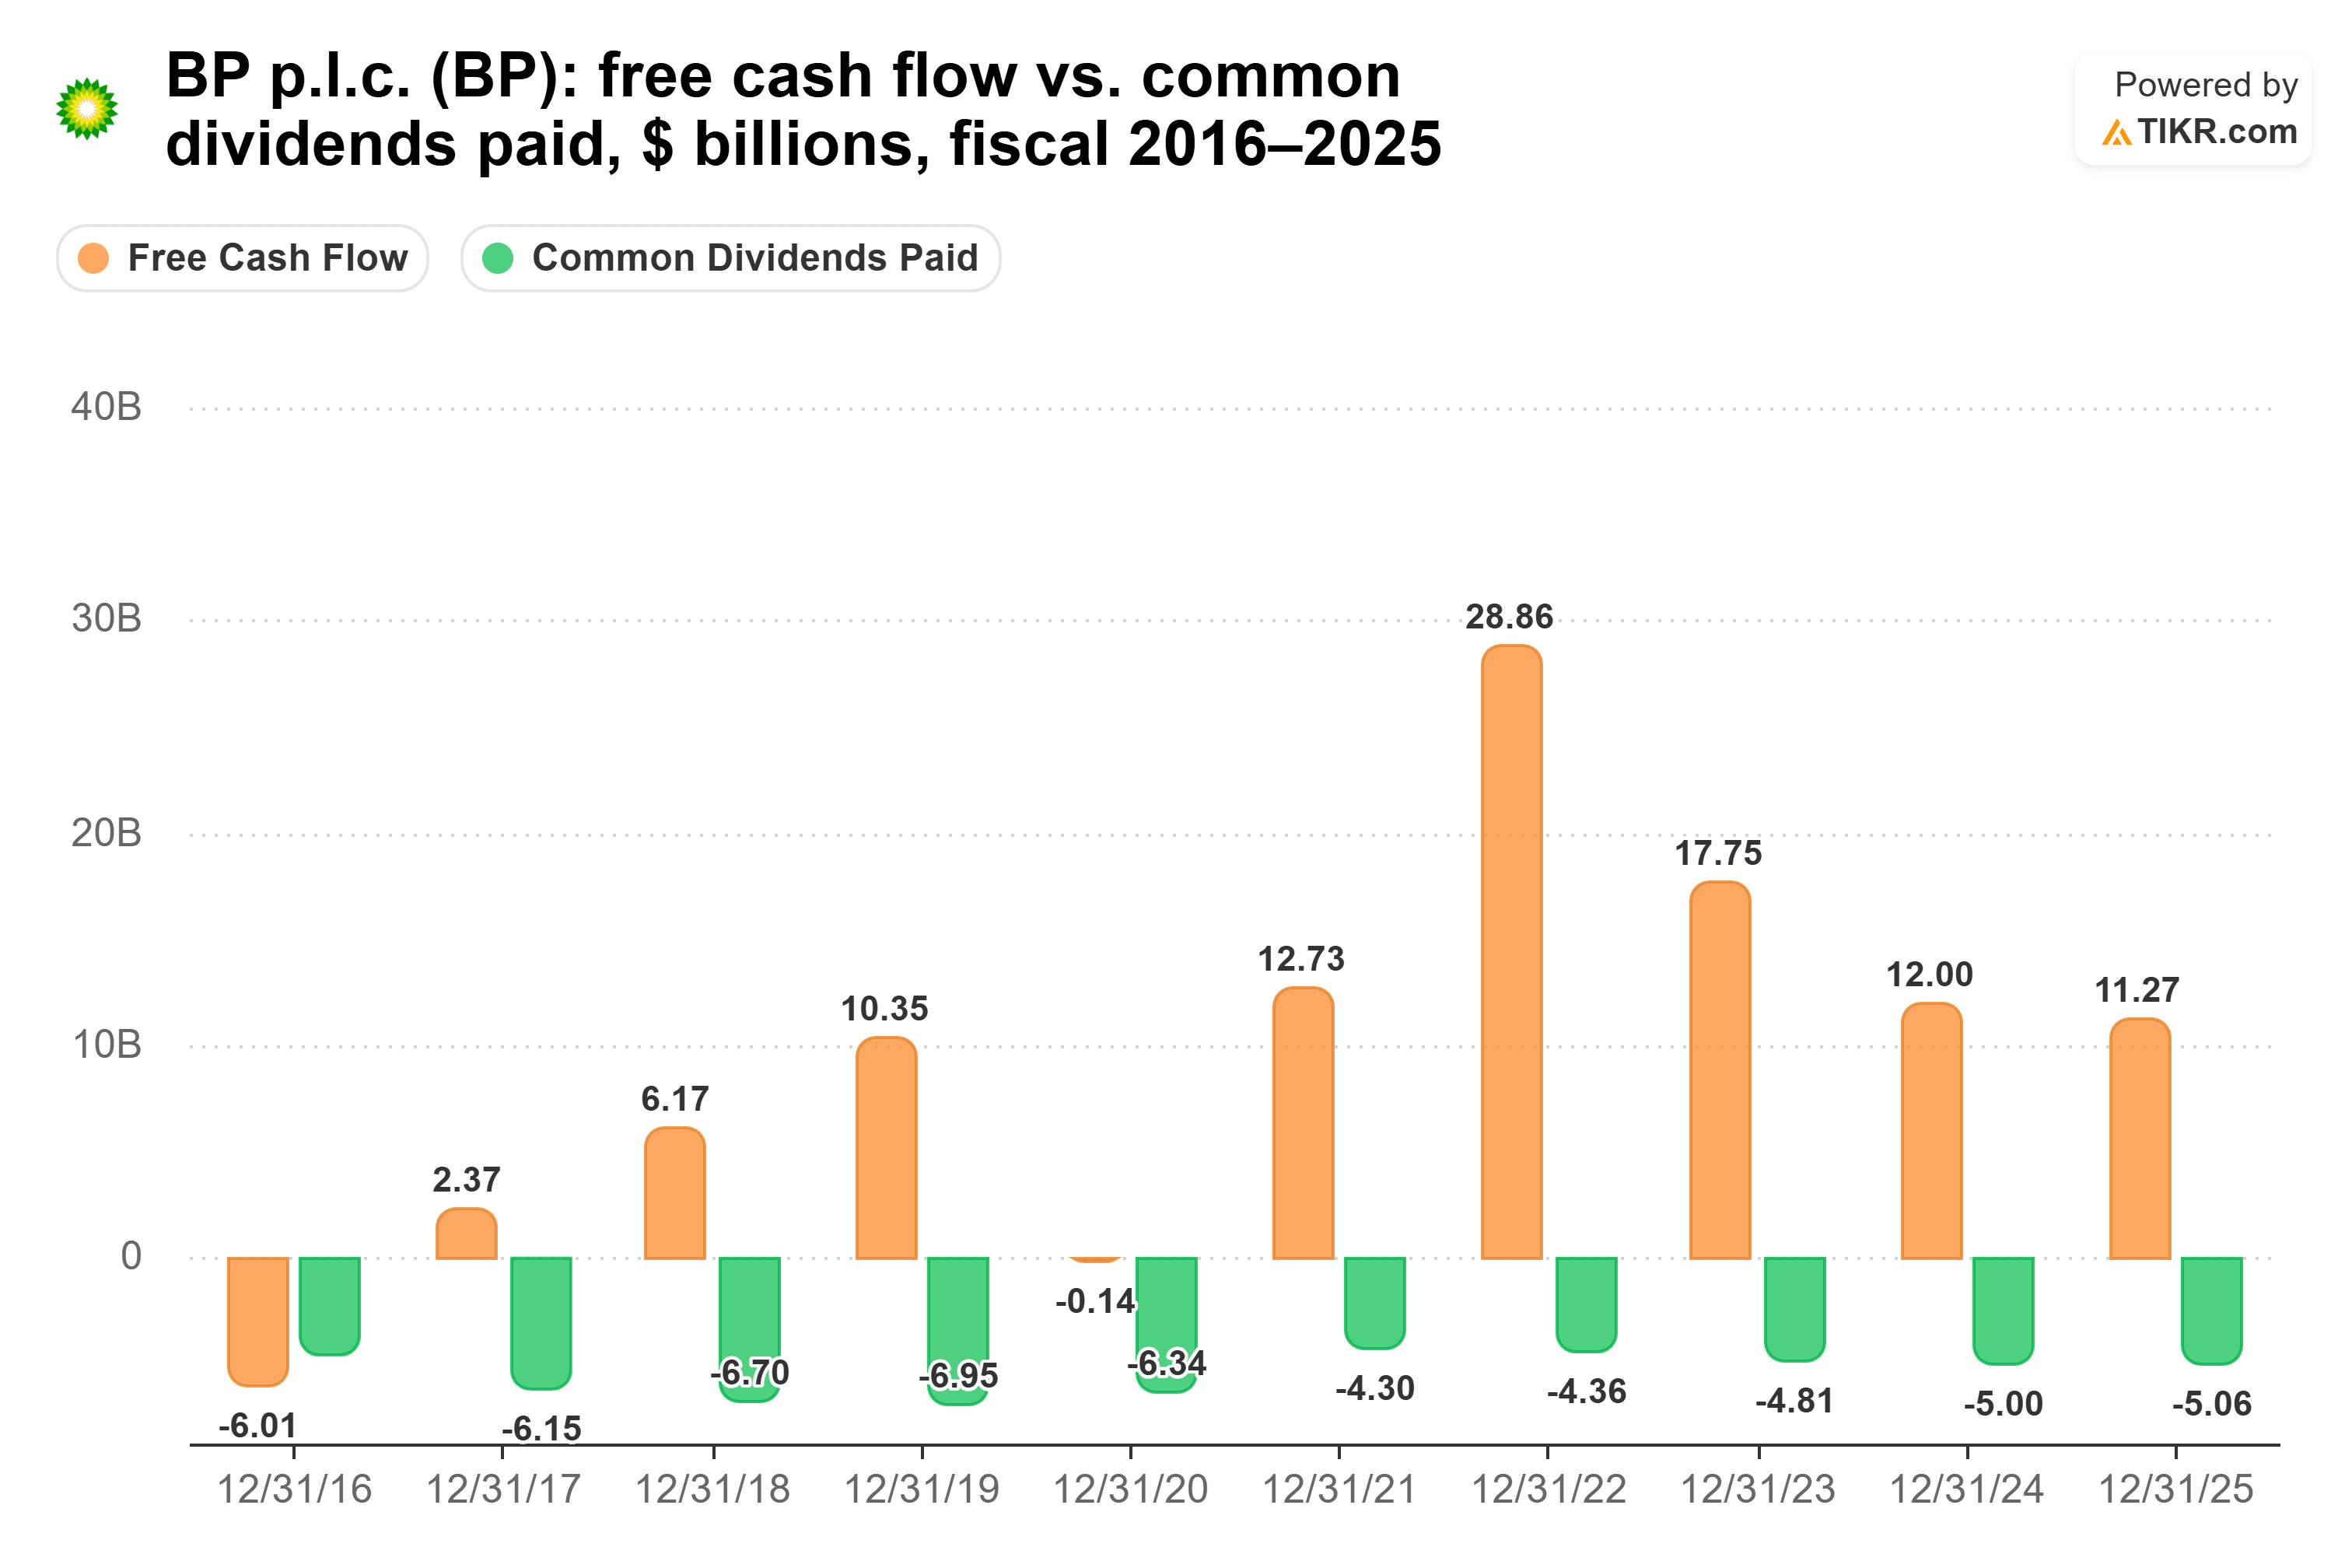
Dividends paid went from $6.34 billion in fiscal 2020 to $4.30 billion in fiscal 2021. BP paid 8.66 cents a share for the third quarter of 2026, the same as for the second, and extra cash is going to past liabilities first. As O’Neill put it, “Our intention now is to prioritize the use of excess cash flow to address our remaining Deepwater Horizon liabilities in full.”
At its 0.6% 5-year rate, $10,000 in BP pays $460 a year now and about $517 in year 20. The risk is the next oil price slump.
So which dividend wins?
Altria gets my dividend dollars for the next 20 years.
Over that long, the steadiness of the cash matters more to me than the size of today’s cushion. At each company’s 5-year rate, $10,000 in Altria pays about $17,182 over 20 years, against about $9,760 for BP. BP’s best case is its 6.5% raise in fiscal 2025, against Altria’s 4.0%: at those rates, BP’s income would pass Altria’s in about 2036. But that’s one year’s raise, after a decade in which BP’s dividend fell.
That doesn’t make BP’s dividend unsafe: it uses less than a third of BP’s free cash flow, on far less debt. Still, Altria’s cash flow barely wobbles, and BP pays less a share than it did a decade ago.
Of course, O’Neill will lay out BP’s long-term strategy in December, and a clear plan to grow its dividend would make this a much closer call.
Forget Altria Group: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Altria Group isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





