Key Takeaways
- Of the 460 big funds that have filed 13Fs for the quarter ended Sept. 30, 28 bought Oracle and 12 sold. David Tepper’s Appaloosa was among the buyers, and Pentwater Capital built a $1.61 billion stake.
- Four of the sellers bought Meta Platforms in the same quarter. Meta is another heavy AI spender, with a fast-growing ad business behind it.
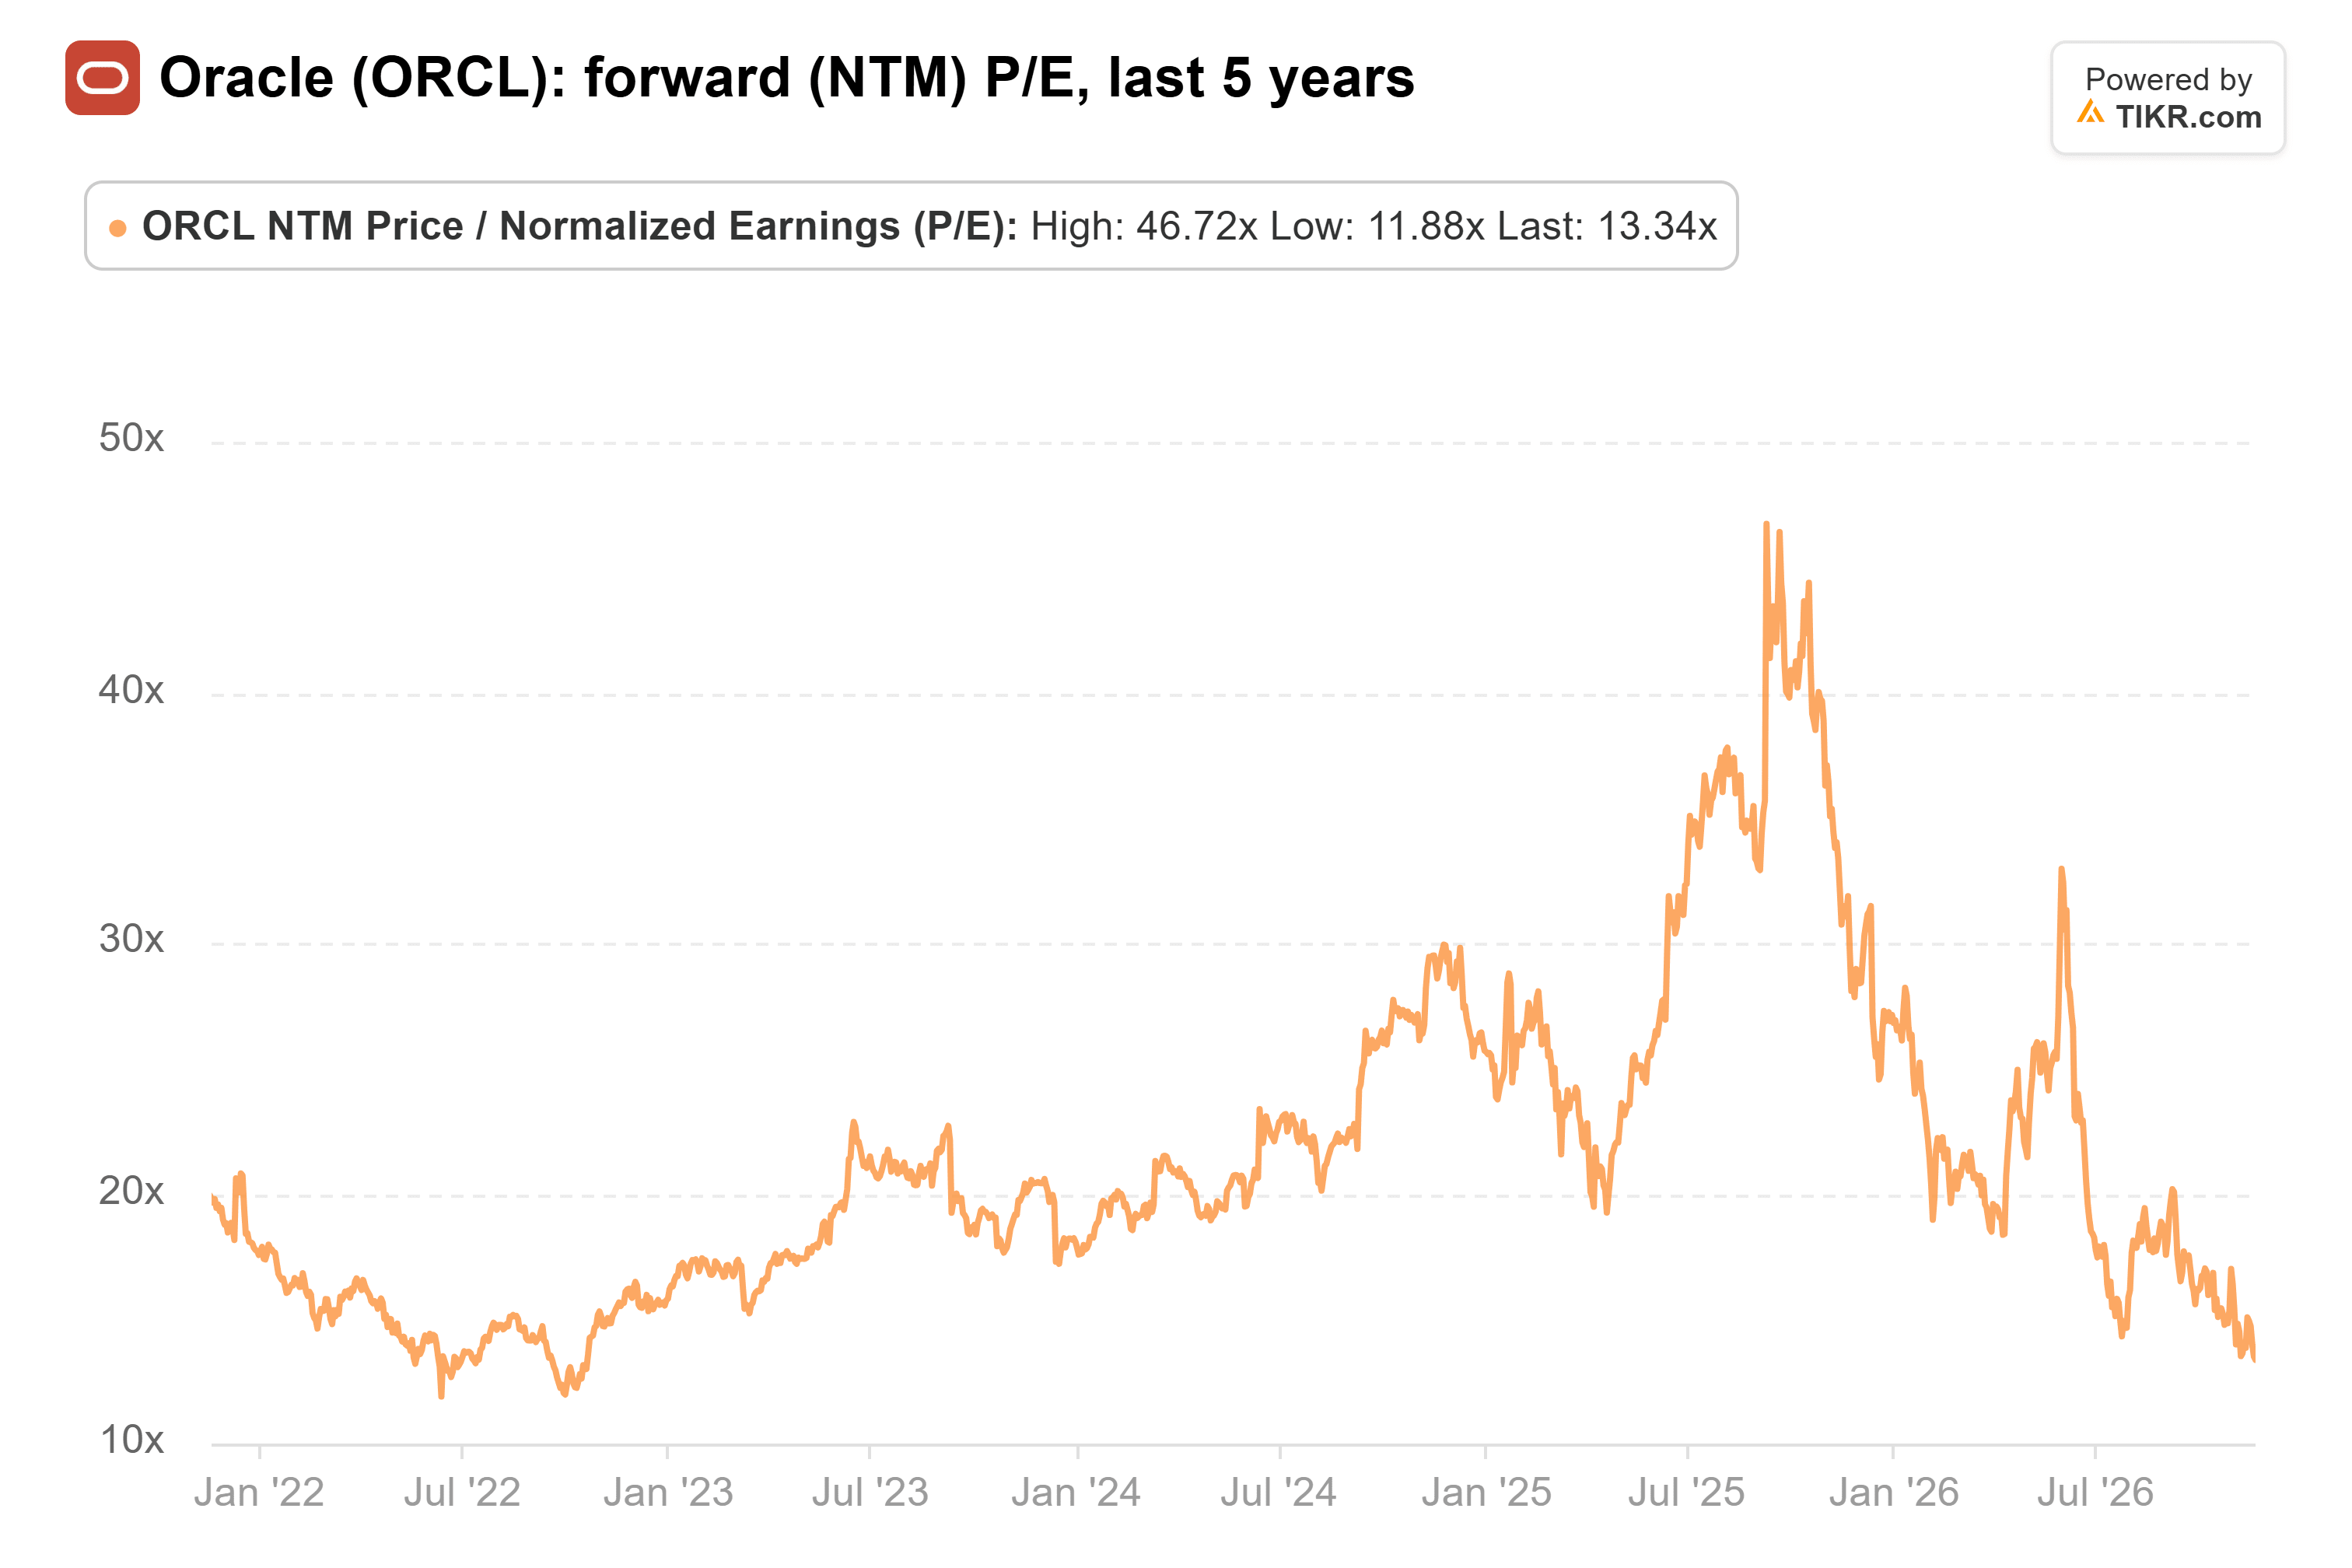
- Oracle trades at 13x forward earnings against a five-year average of 21x, and analysts expect its earnings to climb through fiscal 2028.
- The numbers favor the buyers. But Oracle is funding its AI build with debt, as CoreWeave is, and S&P puts OpenAI at about half of Oracle’s backlog.
Oracle (ORCL) is 54% below its 52-week high, and the big funds can’t agree on what that means.
Of the 460 big funds that have filed 13Fs for the quarter ended Sept. 30, 28 bought Oracle by opening a position or adding 20% or more to one. Twelve sold out or cut 20% or more, and 74 held it at the quarter’s end. The counts cover funds readers know by name and funds with $1 billion or more of US stocks in their 13Fs. Quant and index funds are left out.
TIKR tracks 42 analysts on Oracle. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Oracle, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Oracle’s Analyst Ratings
Tepper has company, and Pentwater went biggest
David Tepper’s Appaloosa opened a position of 1.25 million shares, worth $172 million at Sept. 30. That’s from its 13F for the quarter, filed Nov. 16. The stake is 2.3% of its 13F stocks and its 13th-largest holding.
The biggest buy by far came from Pentwater Capital Management, which manages $19 billion. Its 13F, filed the same day, shows its stake growing from 90,000 shares to 11.75 million. Those shares were worth $1.61 billion, or 12.3% of its 13F stocks, making Oracle its second-largest position. Pentwater also reported put options with a notional value of $656 million and call options with a notional value of $323 million. Its 13F doesn’t show how the shares and options fit together.
GQG Partners, which manages $164 billion, opened a position of 2.49 million shares worth $341 million, though that’s just 0.6% of its 13F stocks. Larry Robbins’ Glenview Capital and Jeremy Grantham’s GMO opened smaller positions, worth about $74 million and $26 million at quarter-end prices.
Parnassus and Polen did most of the selling
None of the sellers is a famous name. Parnassus Investments, which manages $41 billion, cut its stake 79%, from 2.08 million shares to 439,170. That’s about $225 million of stock at quarter-end prices. Polen Capital, which manages $24 billion, sold about $145 million in a 29% cut. Its remaining 2.52 million shares, worth $346 million, are still 3.8% of its 13F stocks. Blue Sparrow, whose 13F holds $8.3 billion of US stocks, cut its stake 94%.
Four of the 12 sellers bought Meta Platforms (META) in the same quarter. Meta is spending heavily on AI too: its third-quarter capex of $34.91 billion was more than its $32.79 billion of operating cash flow. But its ad-driven revenue grew 26% to $64.60 billion, and it ended September with $82.45 billion of cash and marketable securities. Oracle’s total debt, leases included, was $169.1 billion at Aug. 31.
Priced like a slow grower
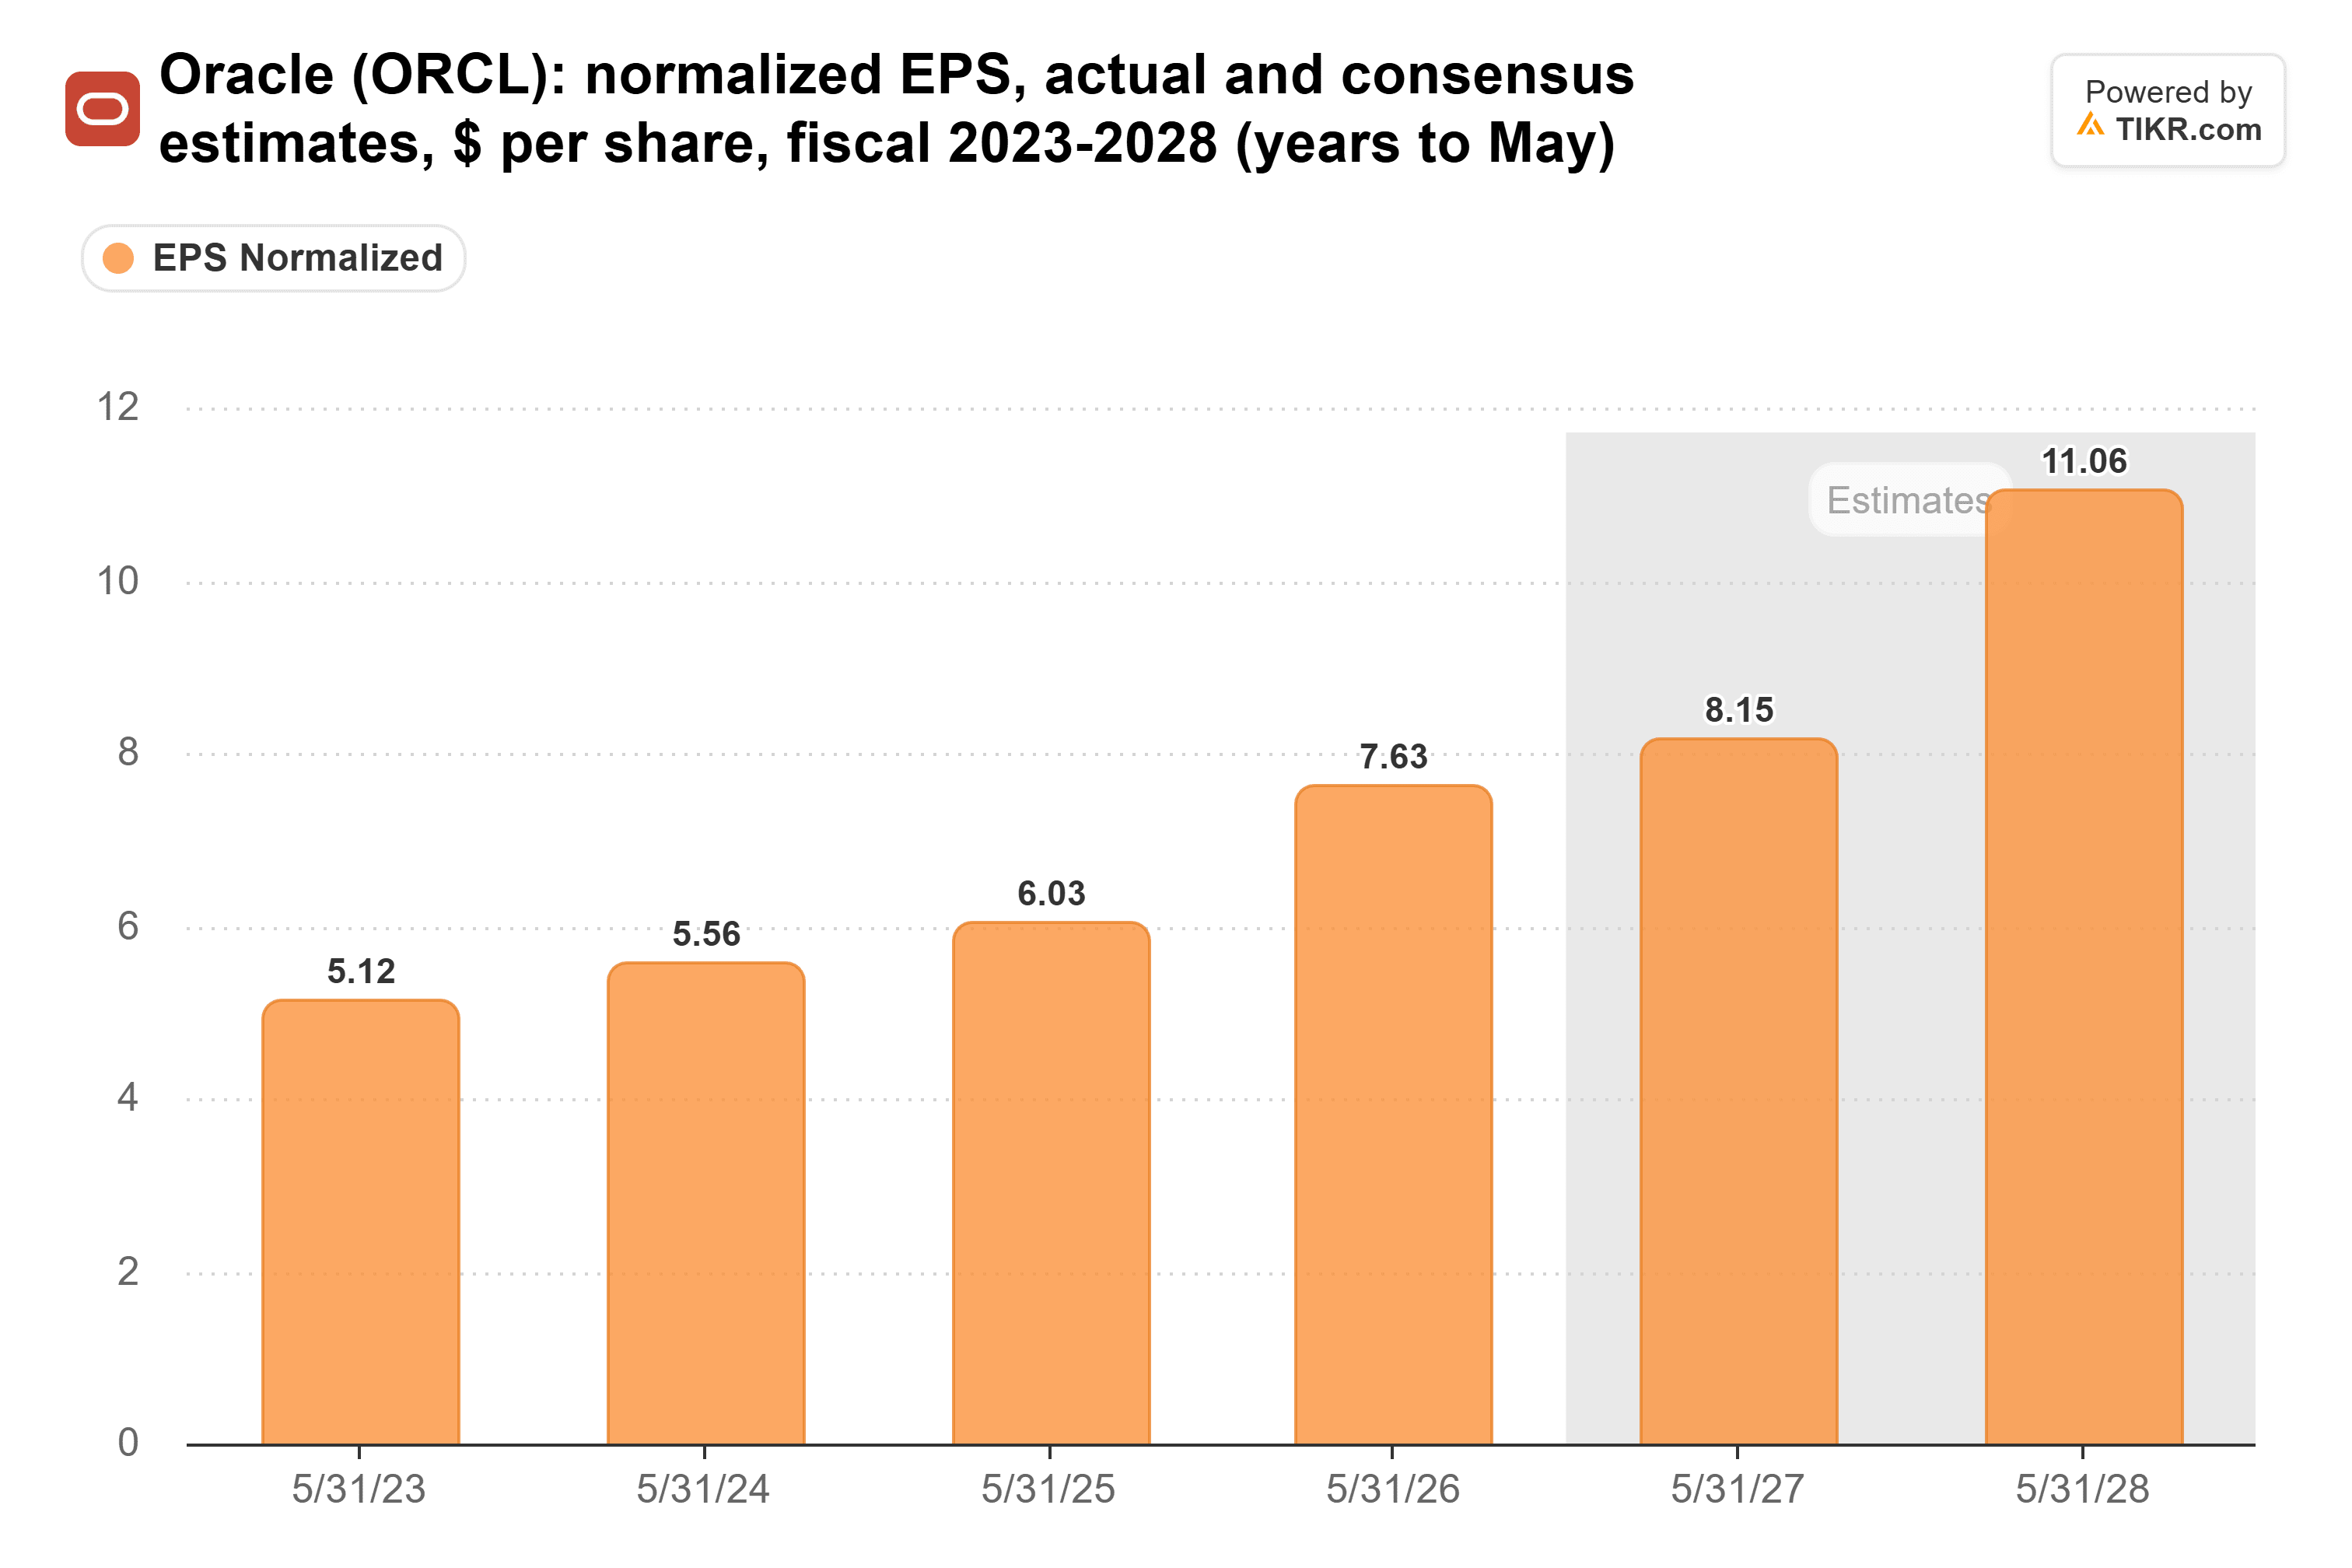
On price alone, the sellers are ahead so far: Oracle is down 17% since Sept. 30, the date the filings use to value every stake. The business looks better than the stock, though. Analysts expect Oracle’s normalized EPS to climb from $7.63 in fiscal 2026 (the year to May) to $11.06 in fiscal 2028. That fiscal 2028 estimate has edged up from $10.90 over the past 90 days:
Even so, Oracle trades at 13x forward earnings. That’s near the bottom of its five-year range and far below its 21x average:
Analysts have cut their targets over the past year, though not as far as the stock has fallen. The consensus target from 42 analysts is $236, down from $347 a year ago, and it’s still 107% above the last close:
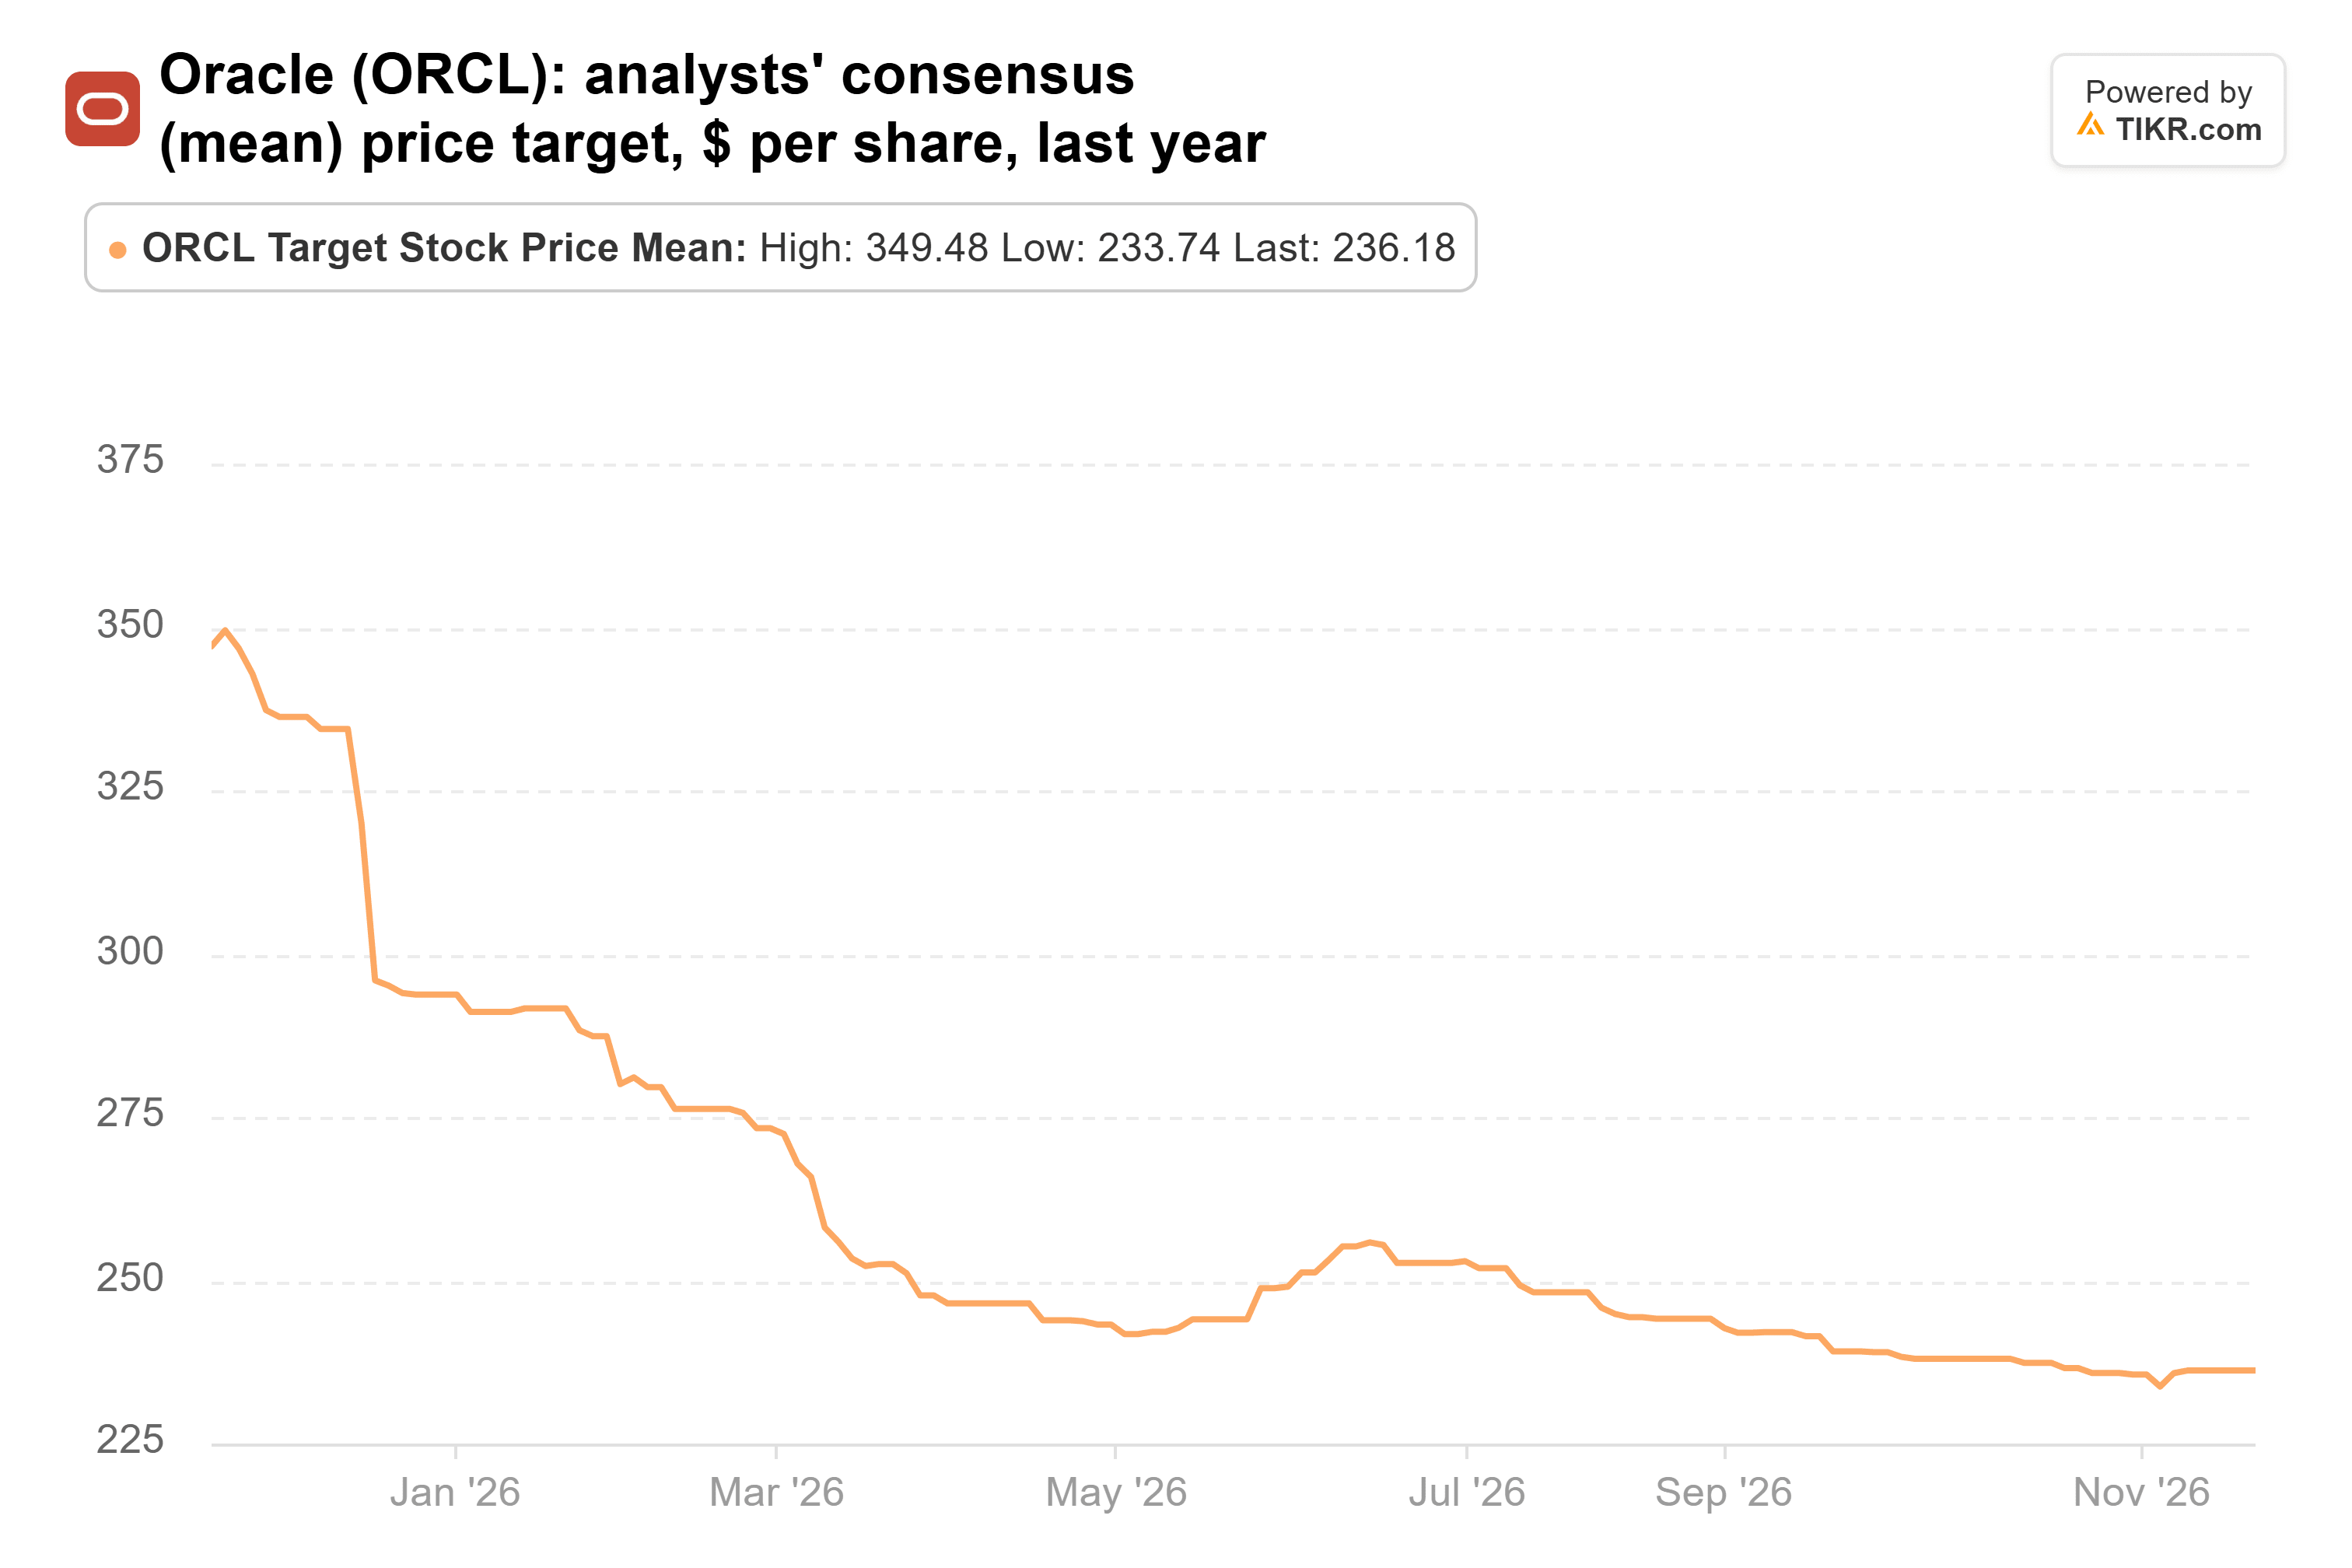
On fiscal 2028 estimates, $236 works out to about 21x, in line with Oracle’s five-year average. So to reach the Street’s target, the estimates only have to hold at Oracle’s usual multiple.
The buyers have the numbers, if OpenAI pays
The catch is how Oracle pays for its build. Analysts expect its free cash flow to stay negative through fiscal 2028, even though CFO Hilary Maxson promised more than $30 billion of it in fiscal 2029. S&P puts OpenAI at about half of Oracle’s backlog. Meanwhile, OpenAI’s latest funding round has reached $15 billion, half its original $30 billion target, CNBC reported. CoreWeave (CRWV), which also counts OpenAI as a customer, is carrying the same kind of build. Its third-quarter interest expense of $846 million was more than four times its $207 million of GAAP operating income.
Still, I’m with the buyers. At 13x, Oracle’s stock already reflects a lot of that risk, and analysts keep raising what they expect it to earn. If I’m wrong, it’ll be because OpenAI can’t raise the money to pay for the capacity Oracle is building for it.
Oracle reports in December. Two things would back the buyers: second-quarter non-GAAP EPS within its $1.85 to $1.93 guidance, and a $664 billion backlog that grows with customers other than OpenAI. The funds’ next 13Fs, for the quarter ending Dec. 31, are due by mid-February, and they’ll show who doubled down.
So what is Oracle stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Oracle could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!