


Key Takeaways
- Dan Loeb’s Third Point sold all of its Amazon, Norfolk Southern and Carpenter Technology stock in the third quarter, its latest 13F shows.
- Its two biggest positions at Sept. 30 were both new: Meta Platforms and Unum.
- Norfolk Southern’s remaining upside depends on regulators approving its sale to Union Pacific, and Carpenter’s business has held up far better than its stock.
- Amazon trades well below its usual forward multiple while analysts raise their estimates, which makes it the sale I’d most want to undo.
Dan Loeb’s Third Point just showed what it cleared out. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows it no longer held any Amazon (AMZN), Norfolk Southern (NSC) or Carpenter Technology (CRS). On June 30, those three made up 9.0%, 4.1% and 2.9% of its 13F stocks.
At the top now are two new positions: Meta Platforms (META), its biggest at 10.5% of its 13F stocks, and Unum (UNM), at 9.7%. The firm manages $28.7 billion in all, and its 13F held $4.54 billion of US stocks across 36 positions.
Amazon got cheaper while its estimates went up
Amazon was the biggest exit: 1.75 million shares, worth $417 million at June 30. The stock is up 8% since then, and AWS grew 39% last quarter, its fastest in five years. Analysts’ consensus target has climbed from $293 to $326 over the past year:
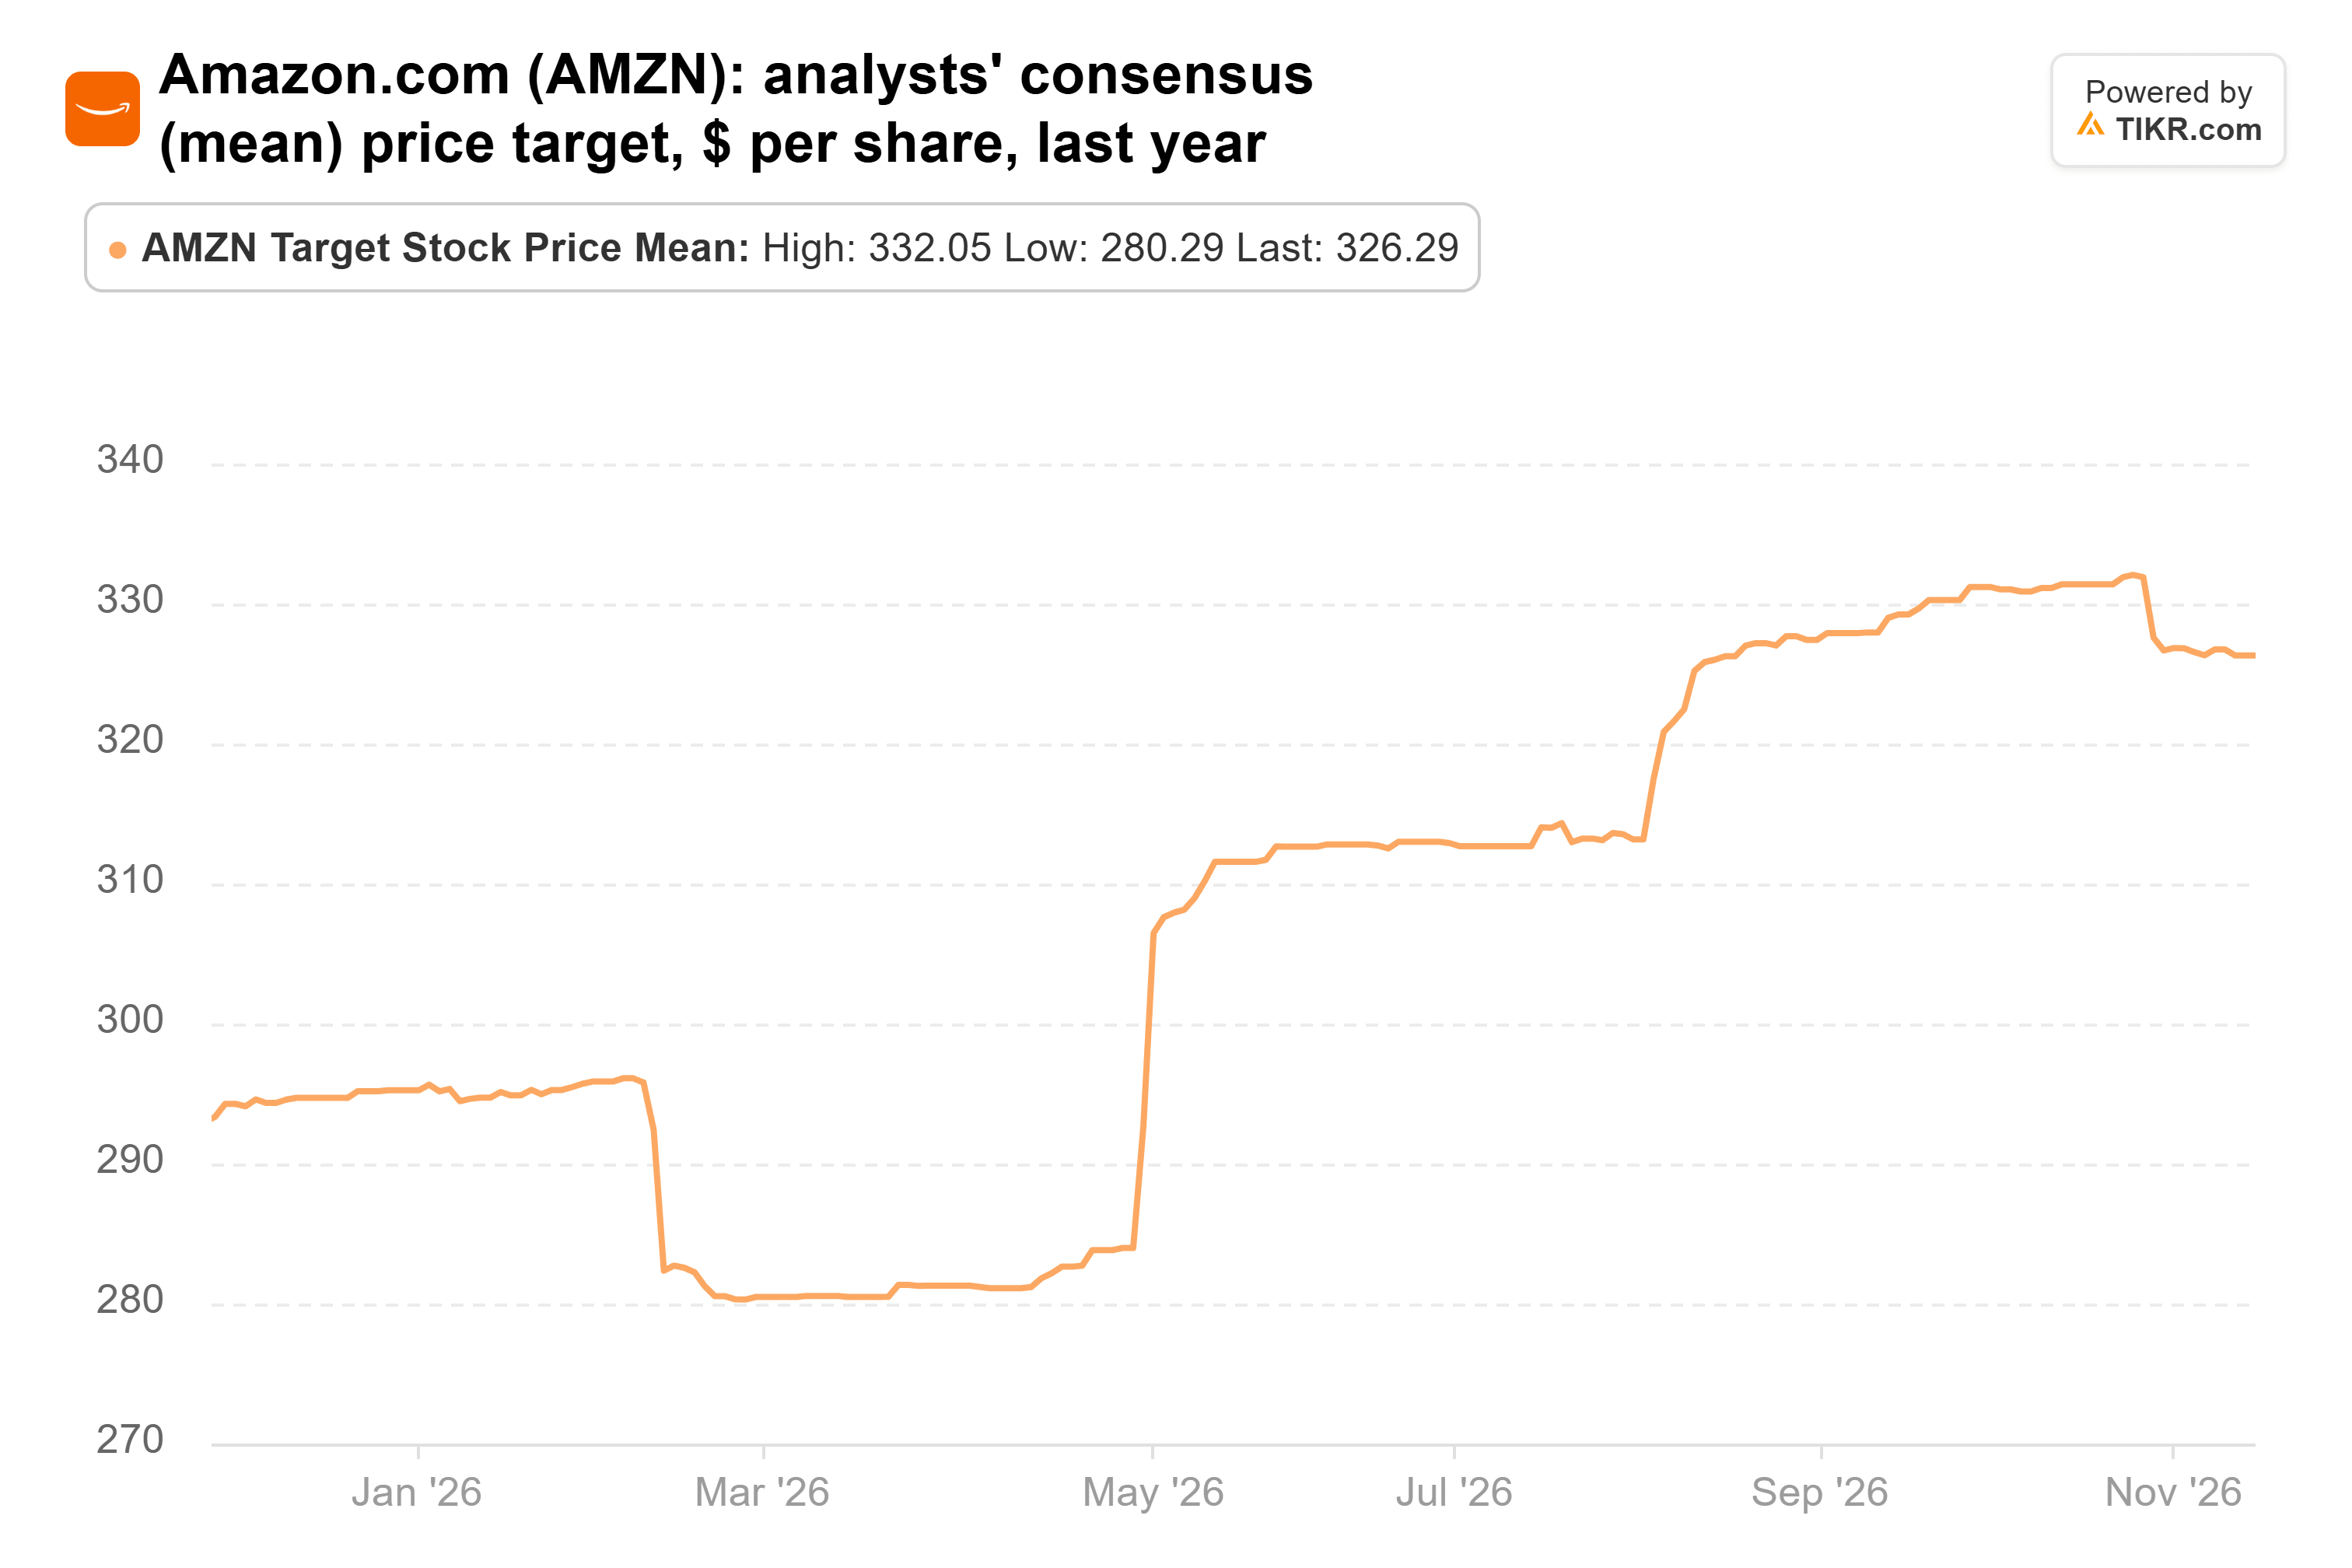
That’s 27% above the last close, and 62 analysts cover the stock. At about 26x forward earnings, Amazon trades well below its 3-year average of 35x, even though analysts raised their 2028 EPS estimate 24% over the past year. The catch is cash: consensus has free cash flow at a $33.9 billion outflow in 2026 and an $8.1 billion outflow in 2027, before a $37.8 billion inflow in 2028.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
Norfolk Southern is a merger bet now
Norfolk Southern was a smaller exit: 600,000 shares worth $189 million at June 30. The stock is up 5% since then. Union Pacific agreed to buy it in July 2025, so the stock now trades largely on that deal, which still needs the Surface Transportation Board’s approval. The board accepted the companies’ revised application in May, comments and protests are due Nov. 18, and it’s the first deal the board will judge under the stricter merger rules it adopted in 2001.
The consensus target has risen from $312 to $357 over the past year:
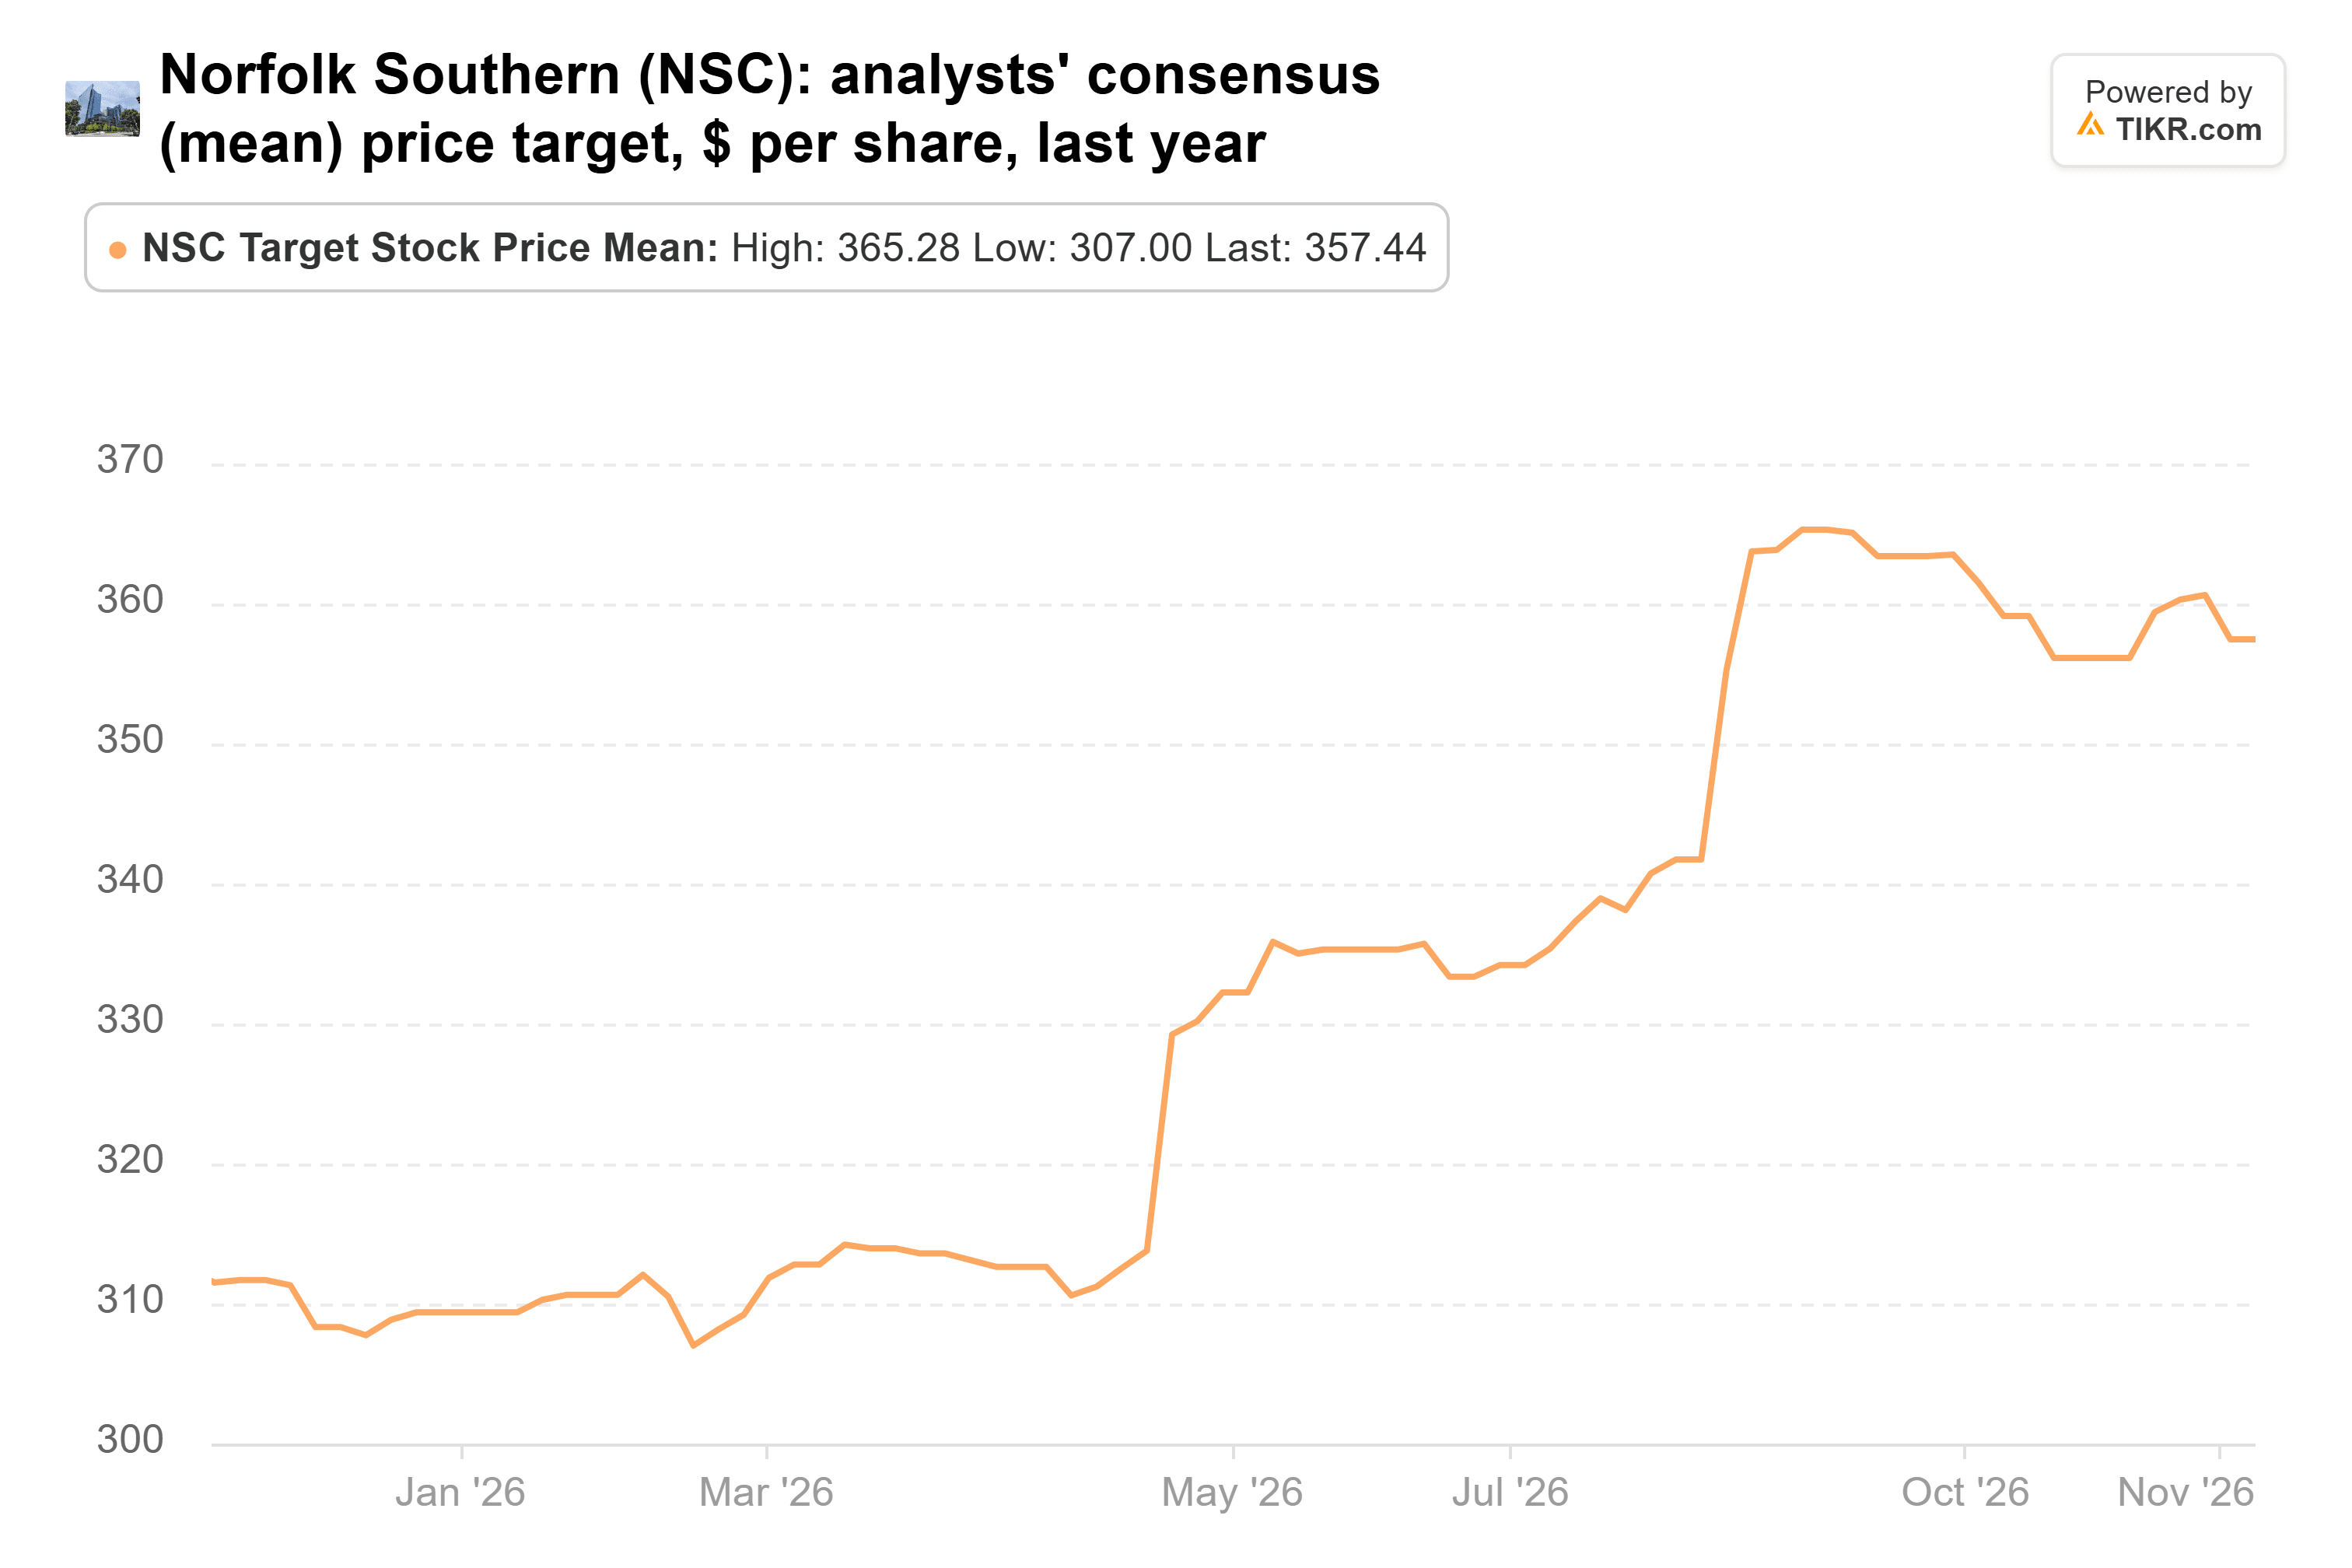
That’s 9% above the last close. Twenty-one analysts cover the stock, and it trades at about 23x forward earnings. With a deal pending, that gap is mostly a bet on regulators.
Carpenter’s business held up far better than its stock
Third Point held 215,000 Carpenter shares worth $133 million at June 30, and the stock has fallen 55% since. Yet Carpenter’s operating income hit a first-quarter record of $196.4 million in the three months to Sept. 30, up 28% from a year earlier, and management kept its fiscal 2027 outlook of $850 million to $880 million of operating income. The stock still sank 22% on the Oct. 22 report after revenue missed. Carpenter itself bought back $133.9 million of its stock in the quarter.
Analysts cut their targets hard, but not as hard as the stock fell. The consensus target peaked at $626 in early August and stood at $438 in late October:
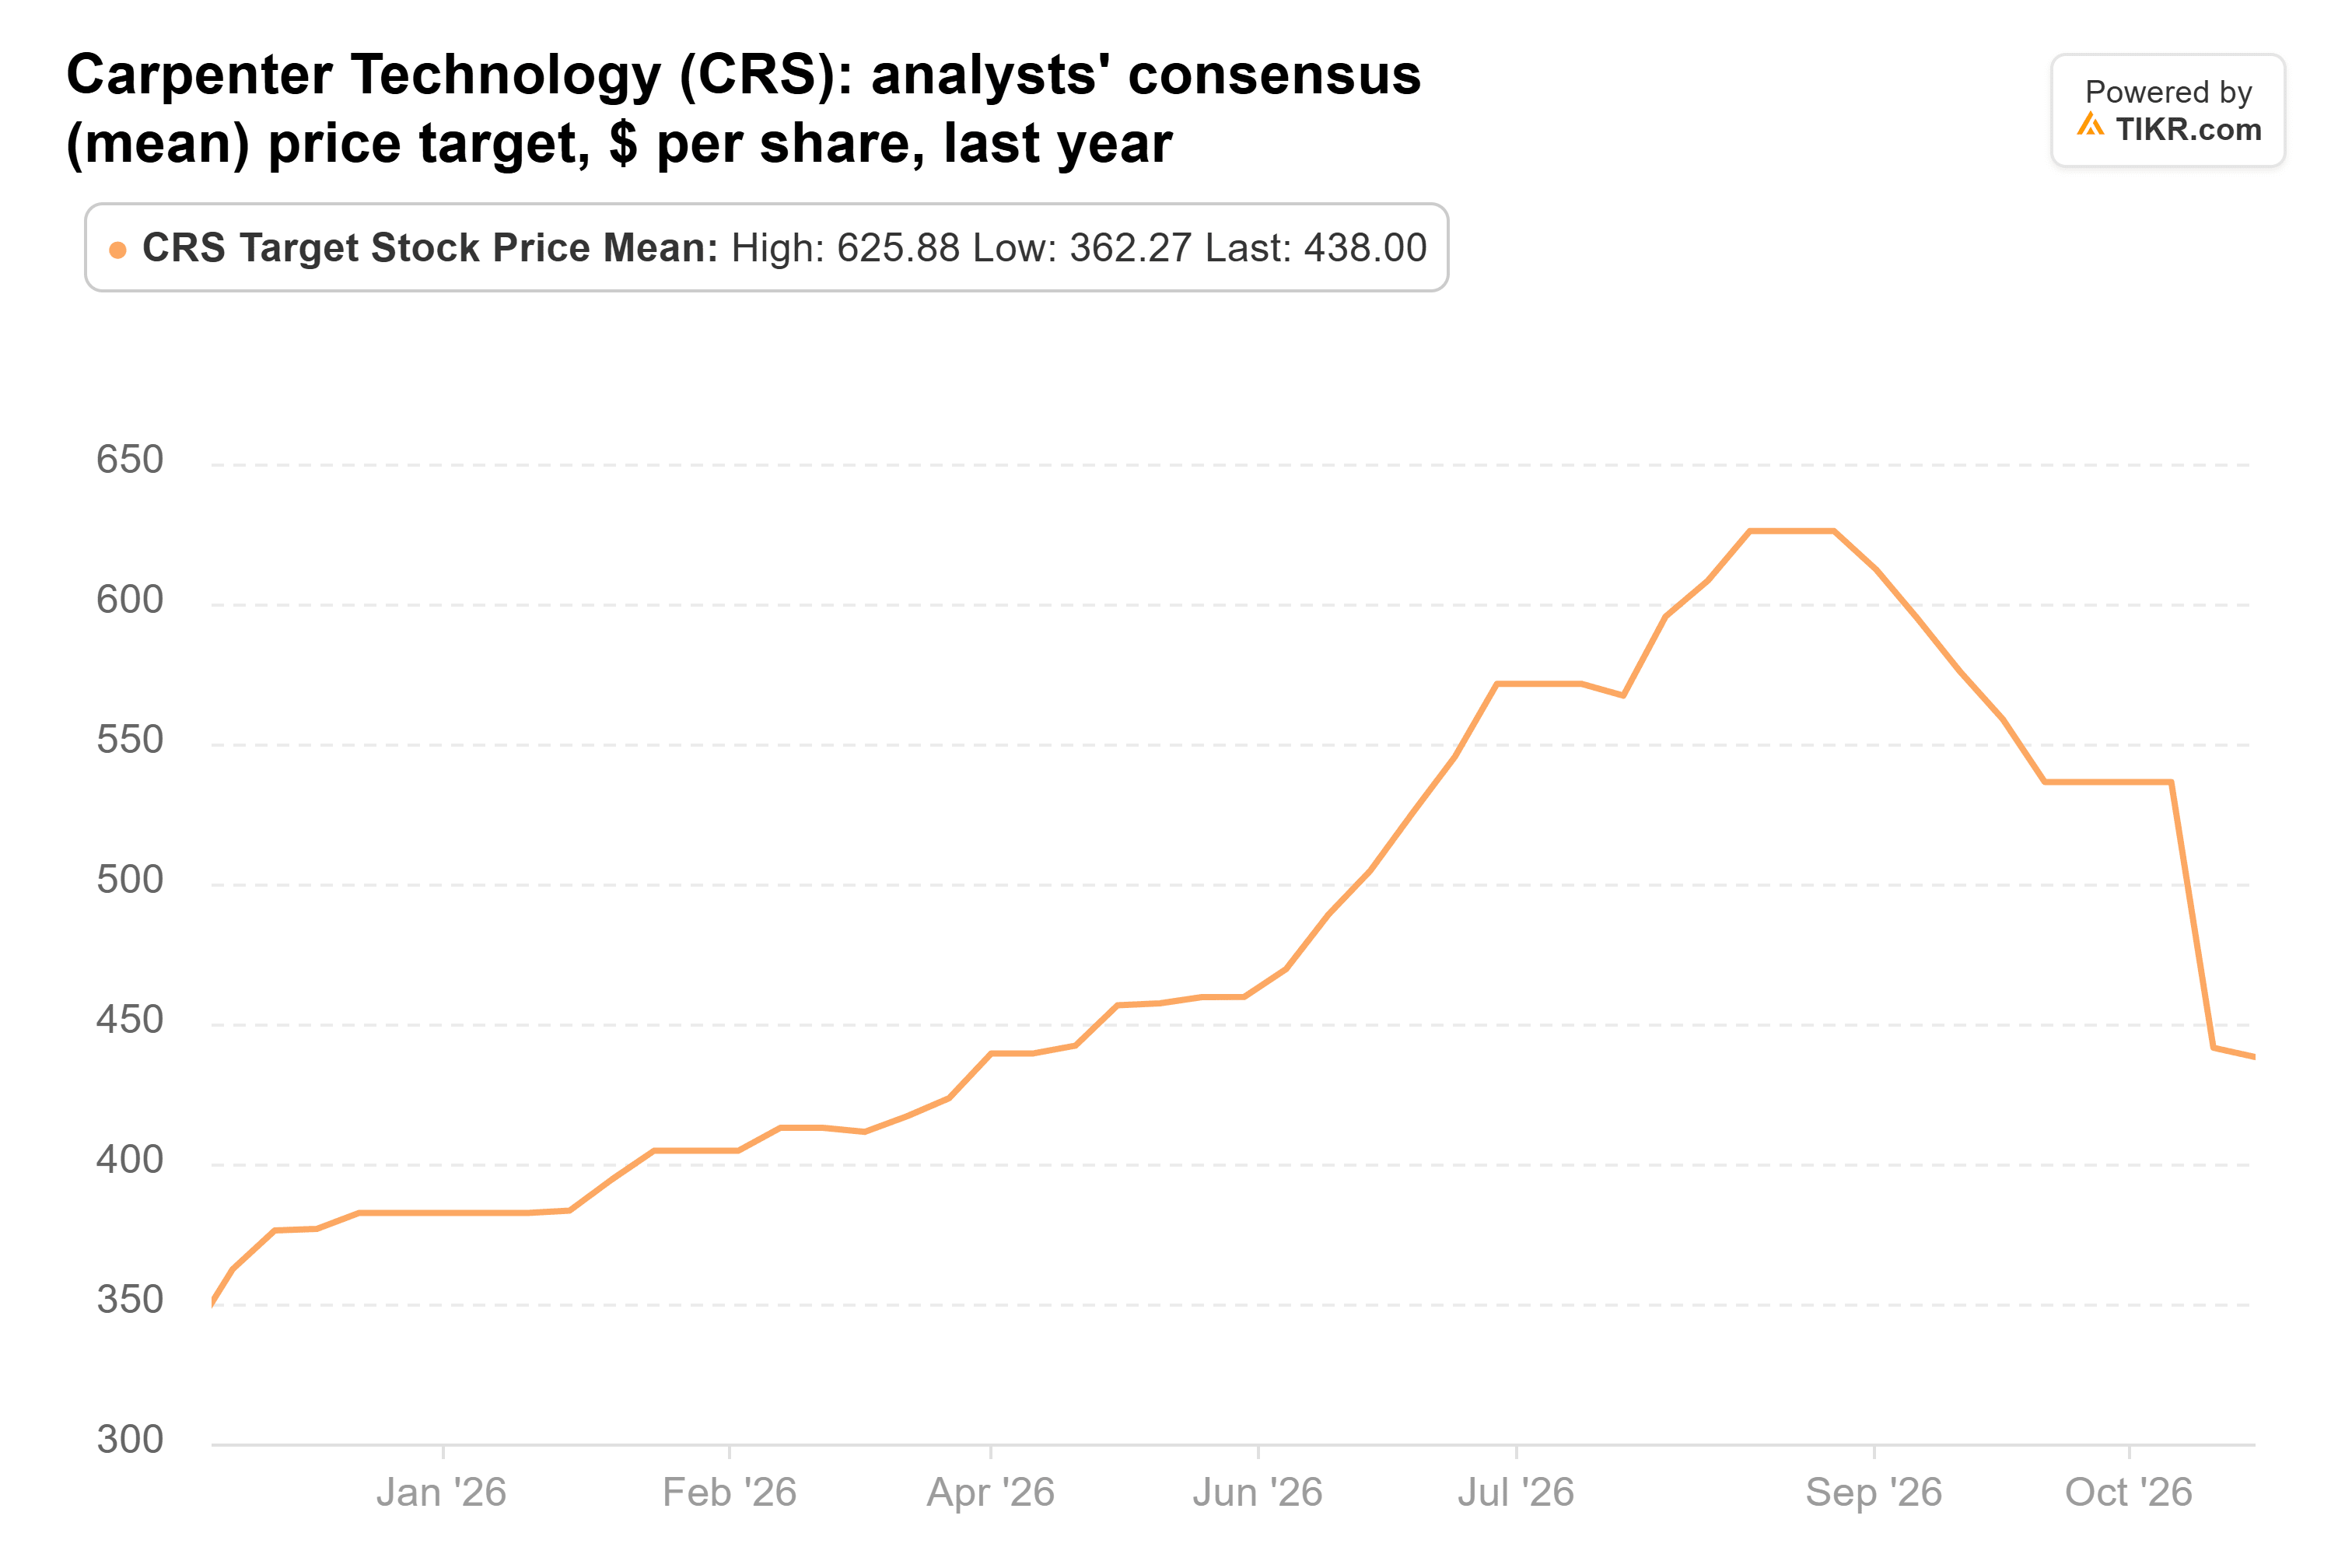
That’s 57% above the last close, and even the lowest of the 8 analysts’ targets, $315, sits above the stock. My read: at about 20x forward earnings, investors are pricing in a slowdown that management’s own guidance doesn’t show yet.
If I could buy one back, it’d be Amazon
Third Point’s two new top positions are both down since Sept. 30: Meta by 14% and Unum by 10%. That’s price only, and it says nothing about what Third Point paid. Meta’s AI bill is also bigger than Amazon’s: consensus has Meta’s free cash flow bottoming at a $48.0 billion outflow in 2027, against Amazon’s $8.1 billion.
Of the three sales, Norfolk Southern’s makes the most sense to me: there’s only about 9% left to the consensus target, and a regulator holds the keys. Carpenter is a closer call, since record profits and an outlook that hasn’t changed suggest the selloff went too far. But if I could buy one back right now, it’d be Amazon. It trades well below its usual multiple while analysts keep raising its estimates.
The risk is that AI spending keeps climbing and pushes Amazon’s cash turn past 2028. We’ll know more when Amazon gives its 2027 capex outlook with fourth-quarter results in early February. And Third Point’s next 13F, due by mid-February, will show whether Loeb went back to any of the three.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





