Key Takeaways
- CrowdStrike (CRWD) stock surged 114% in 2026 through October 30, closing near $250 as accelerating cybersecurity demand and strong financial results supported its rally.
- Palo Alto Networks (PANW) gained approximately 99% over the same period, while Fortinet (FTNT) reported 20% third-quarter revenue growth but raised concerns about slowing services growth.
- CrowdStrike’s net new annual recurring revenue jumped 51% to a record $333 million in the July quarter, exceeding management’s guidance by approximately $47 million.
- CrowdStrike looks overvalued at its October 30 price, making its next earnings report an important test of whether accelerating demand can justify its premium valuation.
What Happened?
CrowdStrike (CRWD) stock surged 114% in 2026 through October 30, closing near $250 as accelerating recurring revenue growth and rising demand for AI cybersecurity helped drive its rally.
CEO George Kurtz described the industry’s turning point as “the Mythos moment,” reflecting growing recognition of the cybersecurity risks created by increasingly powerful artificial intelligence.
In April, Anthropic unveiled Claude Mythos Preview, an advanced AI model capable of discovering and exploiting software vulnerabilities. CrowdStrike and Palo Alto Networks also joined Anthropic’s Project Glasswing initiative, which aims to strengthen cybersecurity defenses using the model’s capabilities.
CrowdStrike’s financial results reinforced that opportunity. The company generated a record $256 million in net new annual recurring revenue (ARR) in the April quarter, representing 32% year-over-year growth.
Momentum accelerated in the July quarter, when net new ARR climbed 51% to a record $333 million, exceeding the upper end of management’s guidance by approximately $47 million.
Management subsequently raised its full-year net new ARR growth outlook to 34% at the midpoint, compared with its original 20% to 25% projection in March.
CrowdStrike also moved its long-term target of reaching $10 billion in ARR forward by one year to fiscal 2030, compared with approximately $5.25 billion recorded at the end of January 2026.
AI security offers another growth opportunity. ARR from CrowdStrike’s AI detection and response products nearly tripled between the April and July quarters as businesses expanded their use of AI-powered applications and agents.
Kurtz emphasized that opportunity in August, saying, “The Mythos moment translated into mass-market acceptance that AI adoption needs security, and that’s CrowdStrike.”
The broader cybersecurity sector has benefited from similar enthusiasm. Palo Alto Networks gained approximately 99% in 2026 through October 30 as investors anticipated stronger security spending.
However, Fortinet’s October 28 earnings report highlighted the sector’s sensitivity to growth expectations. Fortinet generated $2.08 billion in third-quarter revenue, up 20% year over year, while product revenue increased 37% to $765 million.
Despite those results and higher guidance, concerns about slower services growth weighed on Fortinet shares and contributed to selling pressure across cybersecurity stocks.
The central question is whether CrowdStrike can sustain its accelerating growth as investor expectations remain elevated.
Is CrowdStrike Stock Undervalued or Overvalued?
CrowdStrike looks overvalued at its October 30 share price, despite its strong position in the expanding cybersecurity market.
According to TIKR’s October 27 consensus estimates, normalized earnings per share are expected to increase from $0.93 in the year ended January 2026 to approximately $2.12 in the year ending January 2029, supported by recurring revenue expansion and growing AI security demand.
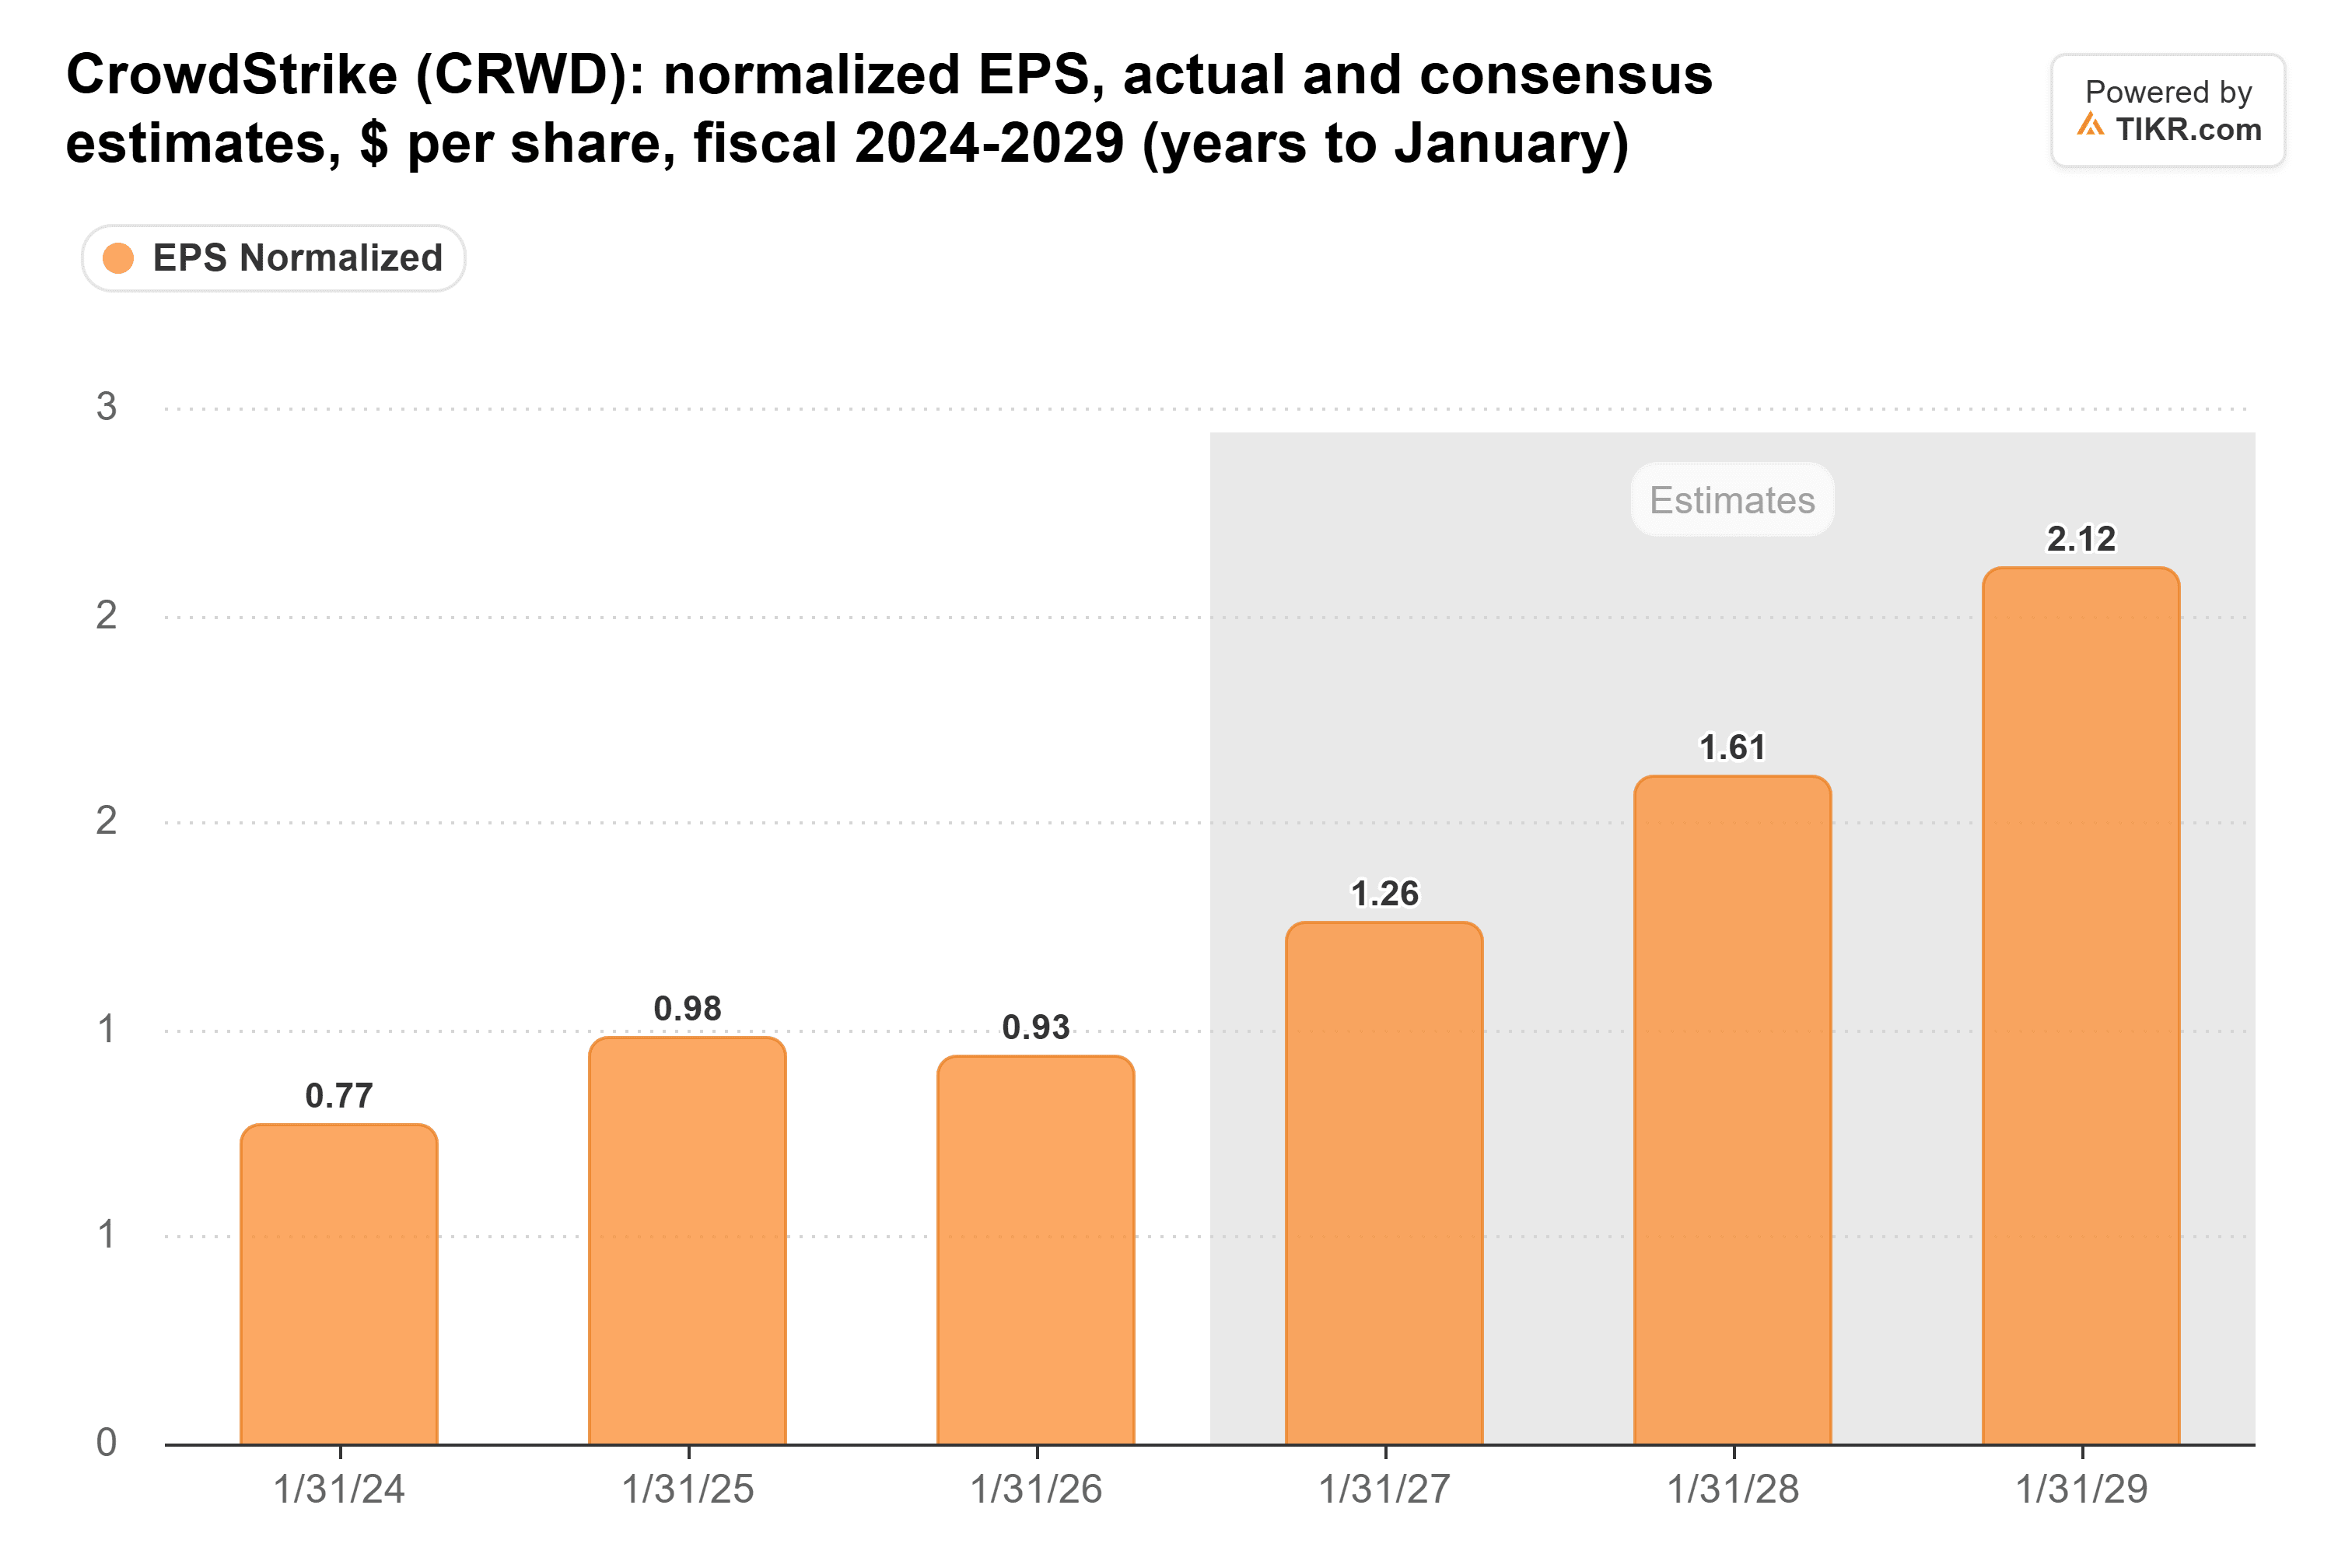
CrowdStrike traded at approximately 168x forward earnings on October 22, substantially above its five-year average of 114x, suggesting investors have already priced in considerable future growth.
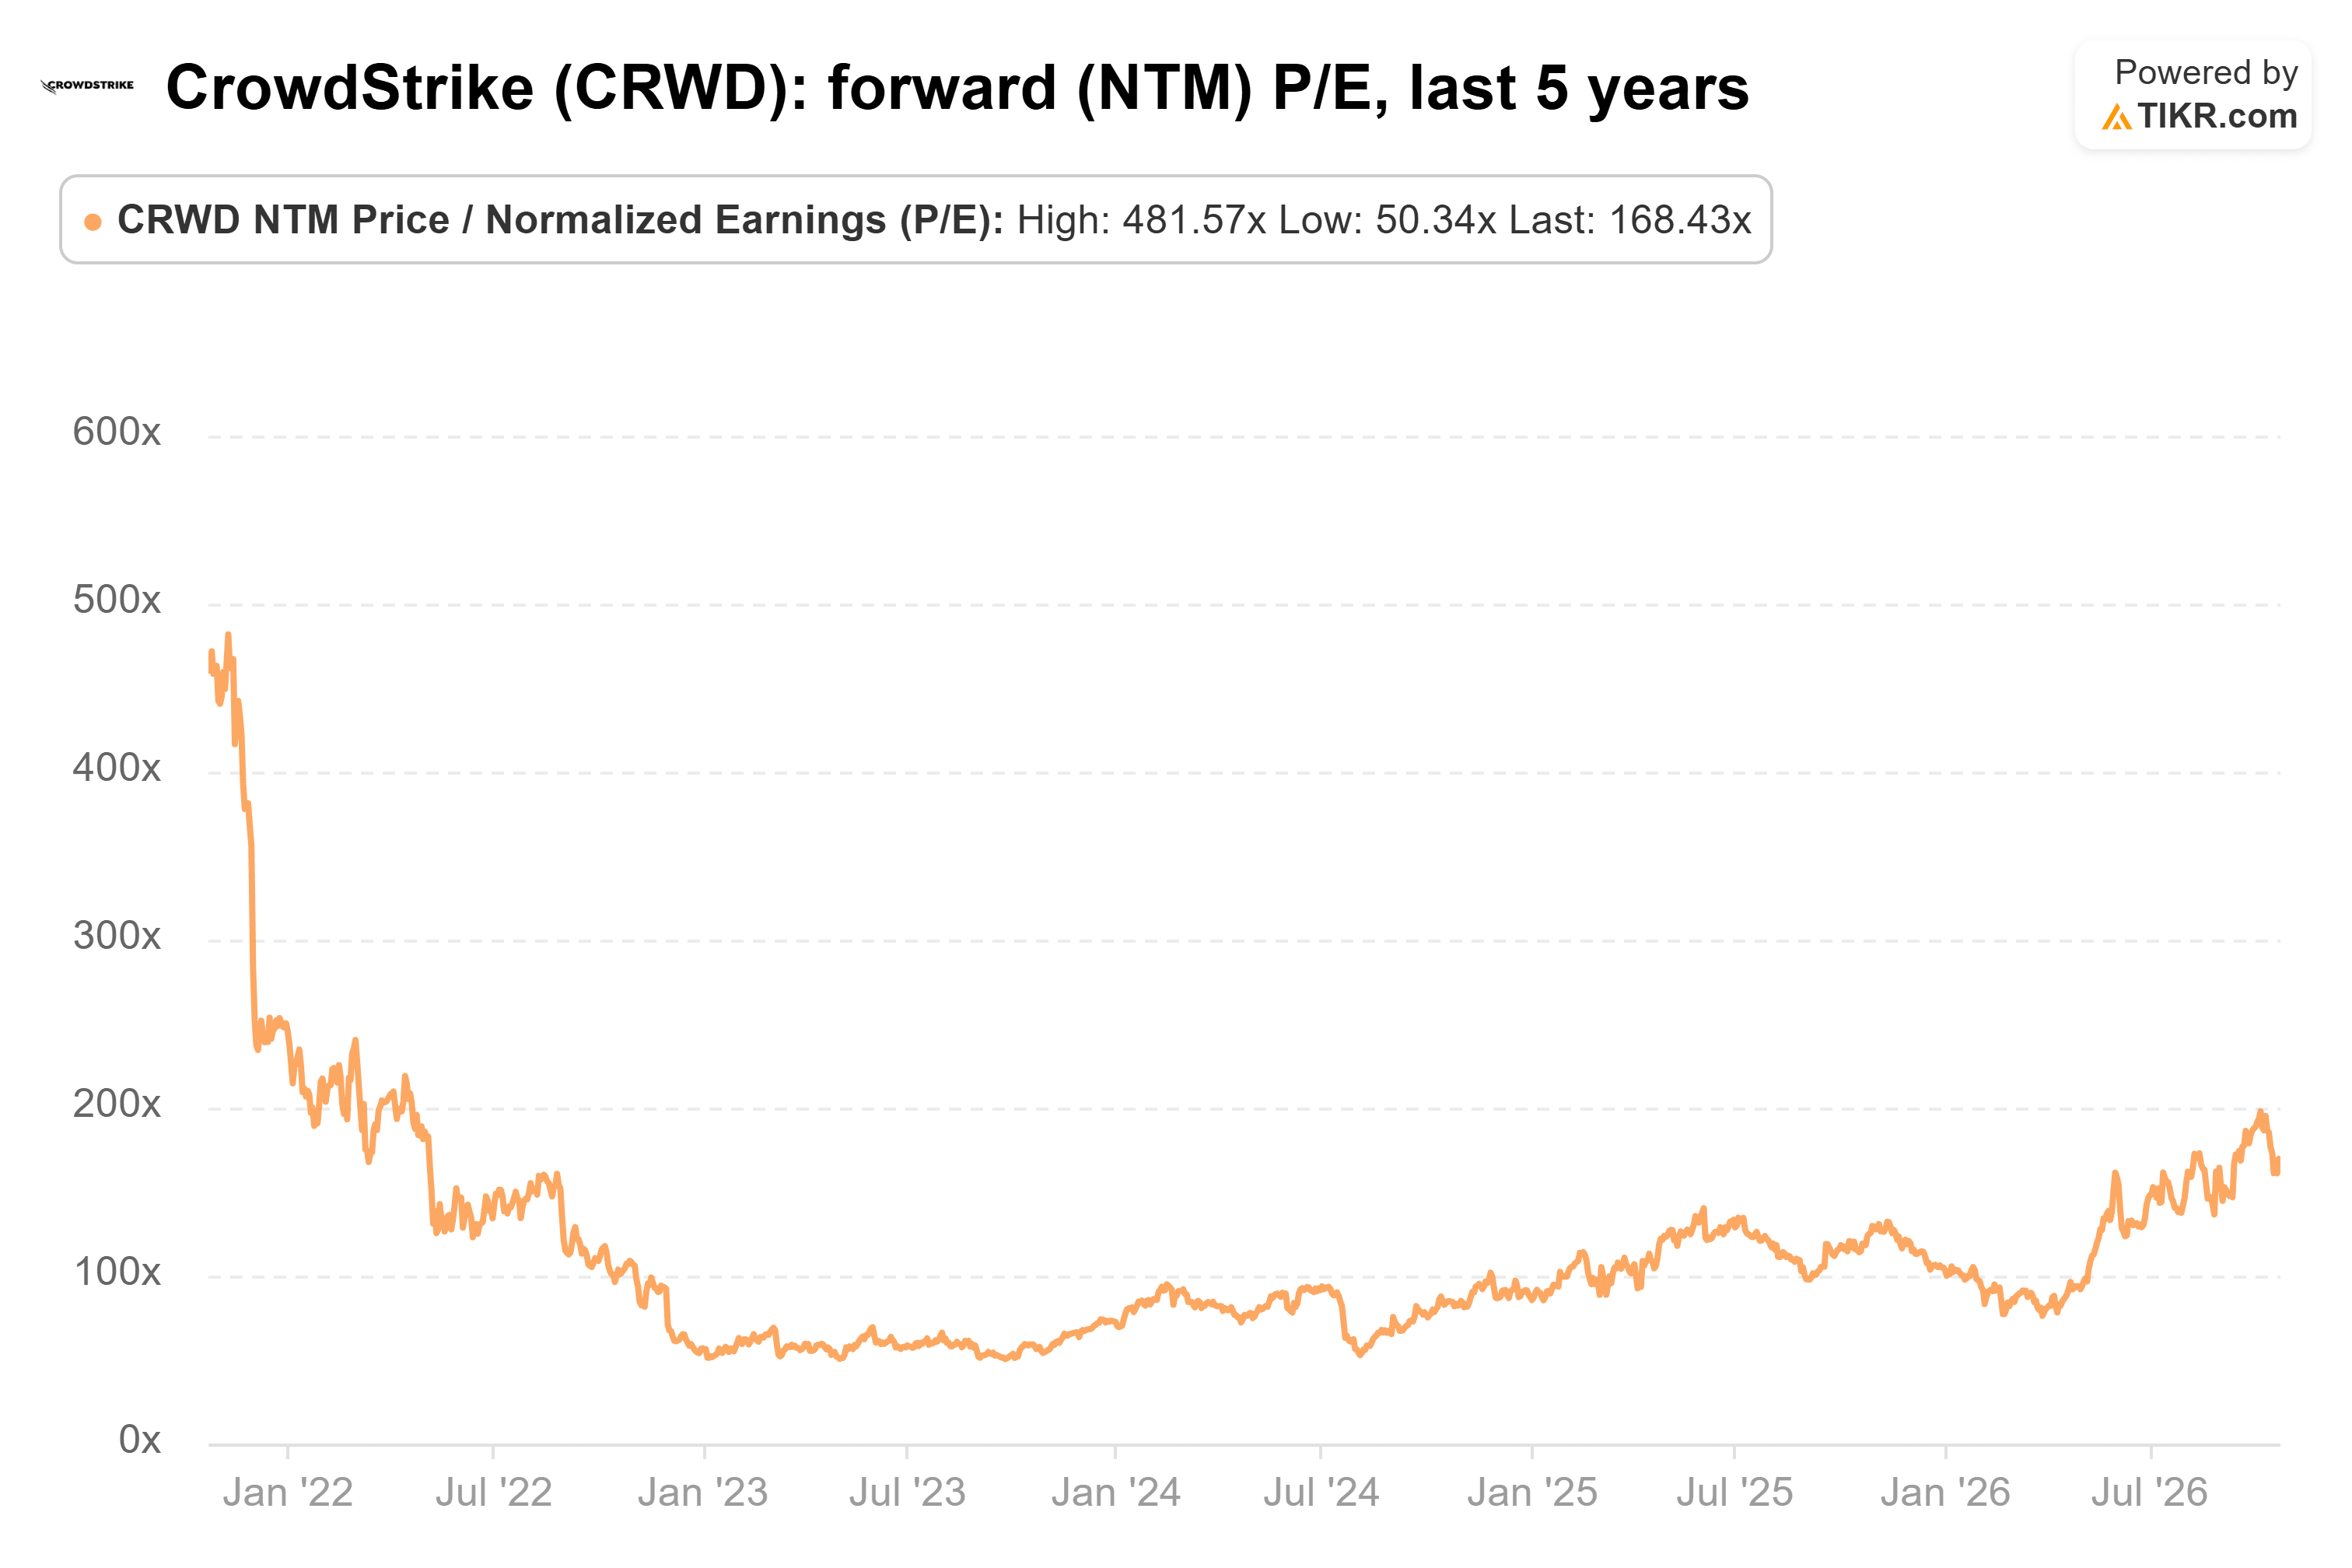
At its October 30 closing price of approximately $250, CrowdStrike also traded slightly above Wall Street’s average price target of roughly $247. Even using the projected $2.12 in normalized EPS for the year ending January 2029, shares traded at approximately 118x those future earnings.
Management expects $343 million to $347 million in net new ARR for the October quarter, representing 29% to 31% growth. That would mark a slowdown from July’s 51% growth, although the previous quarter’s approximately $47 million guidance beat suggests management’s forecast could be conservative.
CrowdStrike’s expanding AI security business and accelerating recurring revenue support its long-term growth prospects, but its 114% rally leaves limited room for disappointing results. The stock looks overvalued based on its October 30 price, making it more attractive to wait for the next earnings report to confirm another substantial guidance beat before considering a new position.
So what is CrowdStrike stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CrowdStrike could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!