Key Takeaways
- CoreWeave stock jumped 24.7% on Nov. 11 after its third-quarter report but is still 56% below its May high, and Bank of America kept its Buy rating and $140 price target.
- Bank of America says CoreWeave’s funding needs are manageable, and the quarter’s prepayments, raised guidance and plan to avoid new unsecured debt through 2027 support that.
- The $140 target works out to about 3.3x forward sales, below the stock’s average over the past year, but analysts expect a bigger loss in 2027 than they did 90 days ago.
- Several other bullish firms cut their targets to between $90 and $115 after the report, and that range is a likelier landing over the next year than $140.
CoreWeave (CRWV) jumped 24.7% to $60.77 on Wednesday, Nov. 11, after a third quarter that beat its own guidance, and the stock is still 56% below its May high. Bank of America’s Tal Liani reiterated his Buy rating and $140 price target the same day, 130% above that close.
Debt sank the stock
The slide has been about funding. CoreWeave’s 9.625% notes due 2032 fell below 80 cents on the dollar on Oct. 14, a yield near 15%. On Nov. 9, MoffettNathanson’s Nick Del Deo said its unsecured debt yields about 16% and that CoreWeave is largely shut out of that market. And analysts now expect CoreWeave to lose $4.70 a share in 2027, against $3.90 90 days ago.
Bank of America says the funding plan holds up
“CoreWeave’s funding needs are manageable, in our view, supported by a diversified set of financing options,” Liani wrote after the report, pointing to customer prepayments, vendor financing and contract-backed loans. CoreWeave gave him plenty to work with. Revenue of $3.66 billion was up 168% from a year earlier, adjusted operating income of $379 million beat the $200 million to $260 million it had guided, and the company raised its 2026 revenue outlook to $13.0 billion to $13.3 billion. It also expects about $9 billion of prepayments and deposits in the next three months. Management said it won’t sell unsecured debt at today’s yields and expects to raise less than $5 billion at the parent company through 2027.
TIKR tracks 42 analysts on CoreWeave. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on CoreWeave, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See CoreWeave’s Analyst Ratings
Does $140 add up?
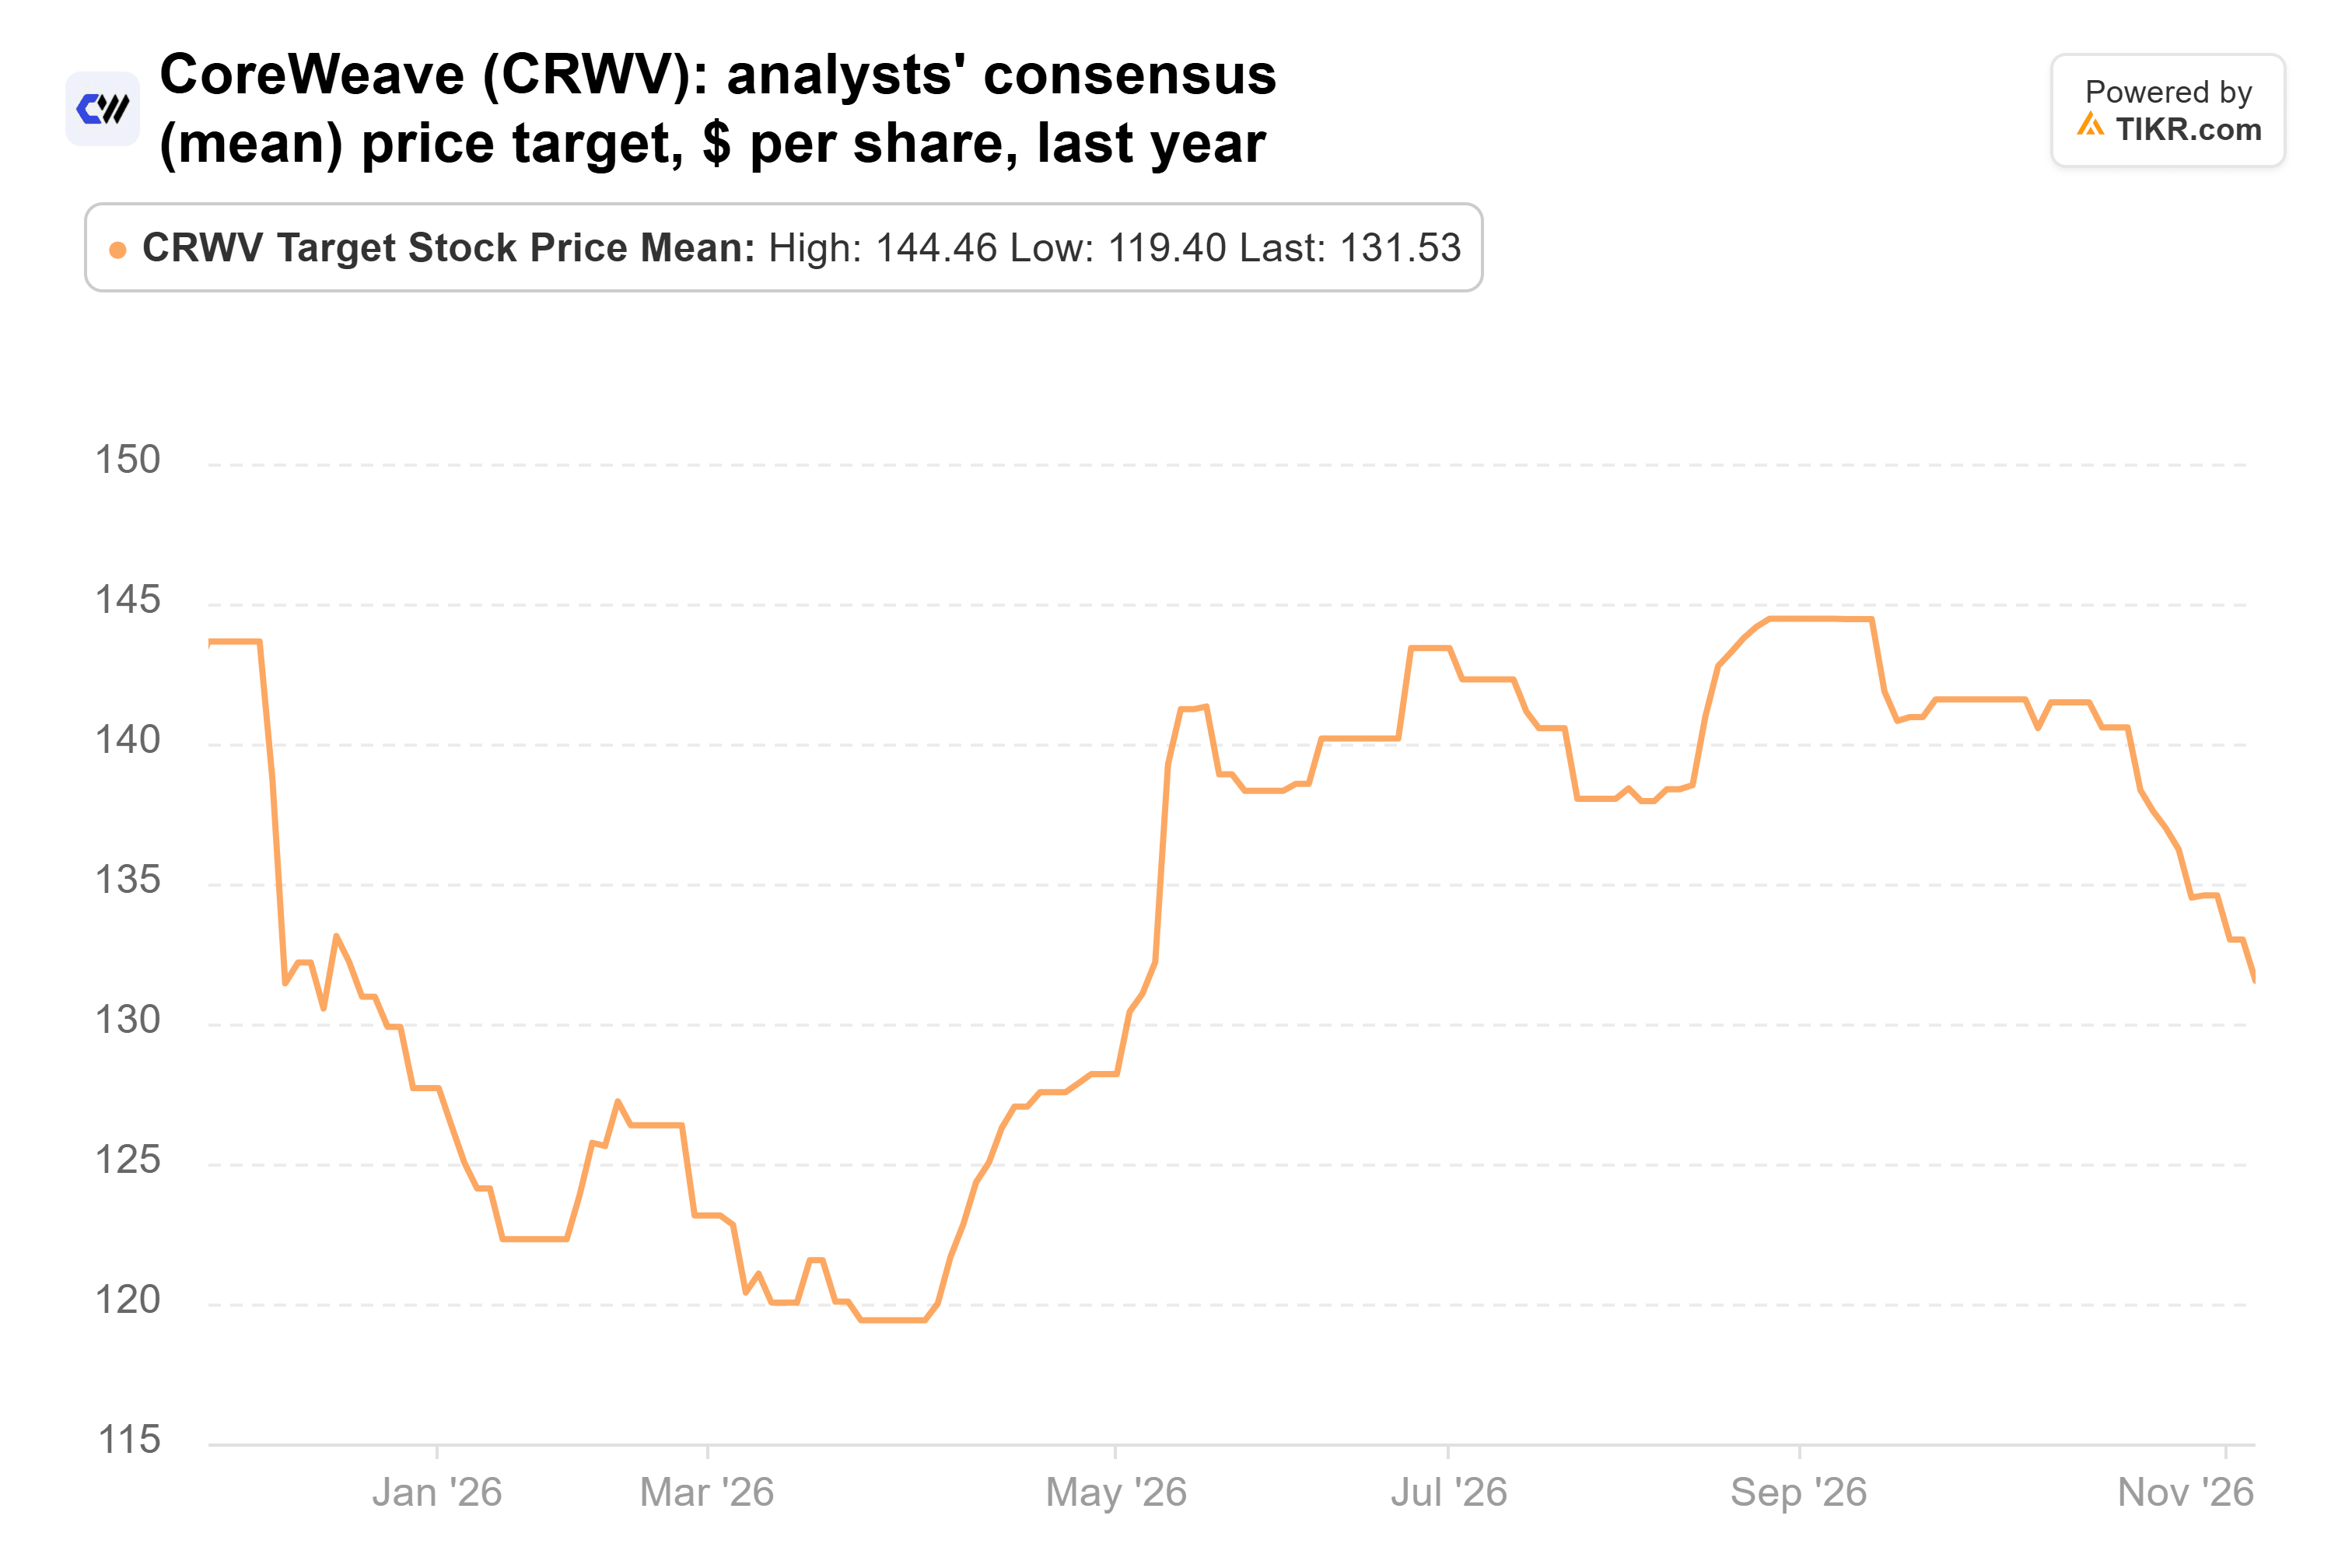
Bank of America isn’t far out on a limb. The consensus target of the 42 analysts covering CoreWeave is $132, 116% above the price, though it has slipped from $144 a year ago:
Revenue estimates keep climbing. Analysts expect sales to more than double to $26.5 billion in 2027:

And investors still pay little for that revenue. Even after Wednesday’s jump, CoreWeave trades at about 1.4x forward sales, near the past year’s low of 1.2x and well under the 3.5x average:
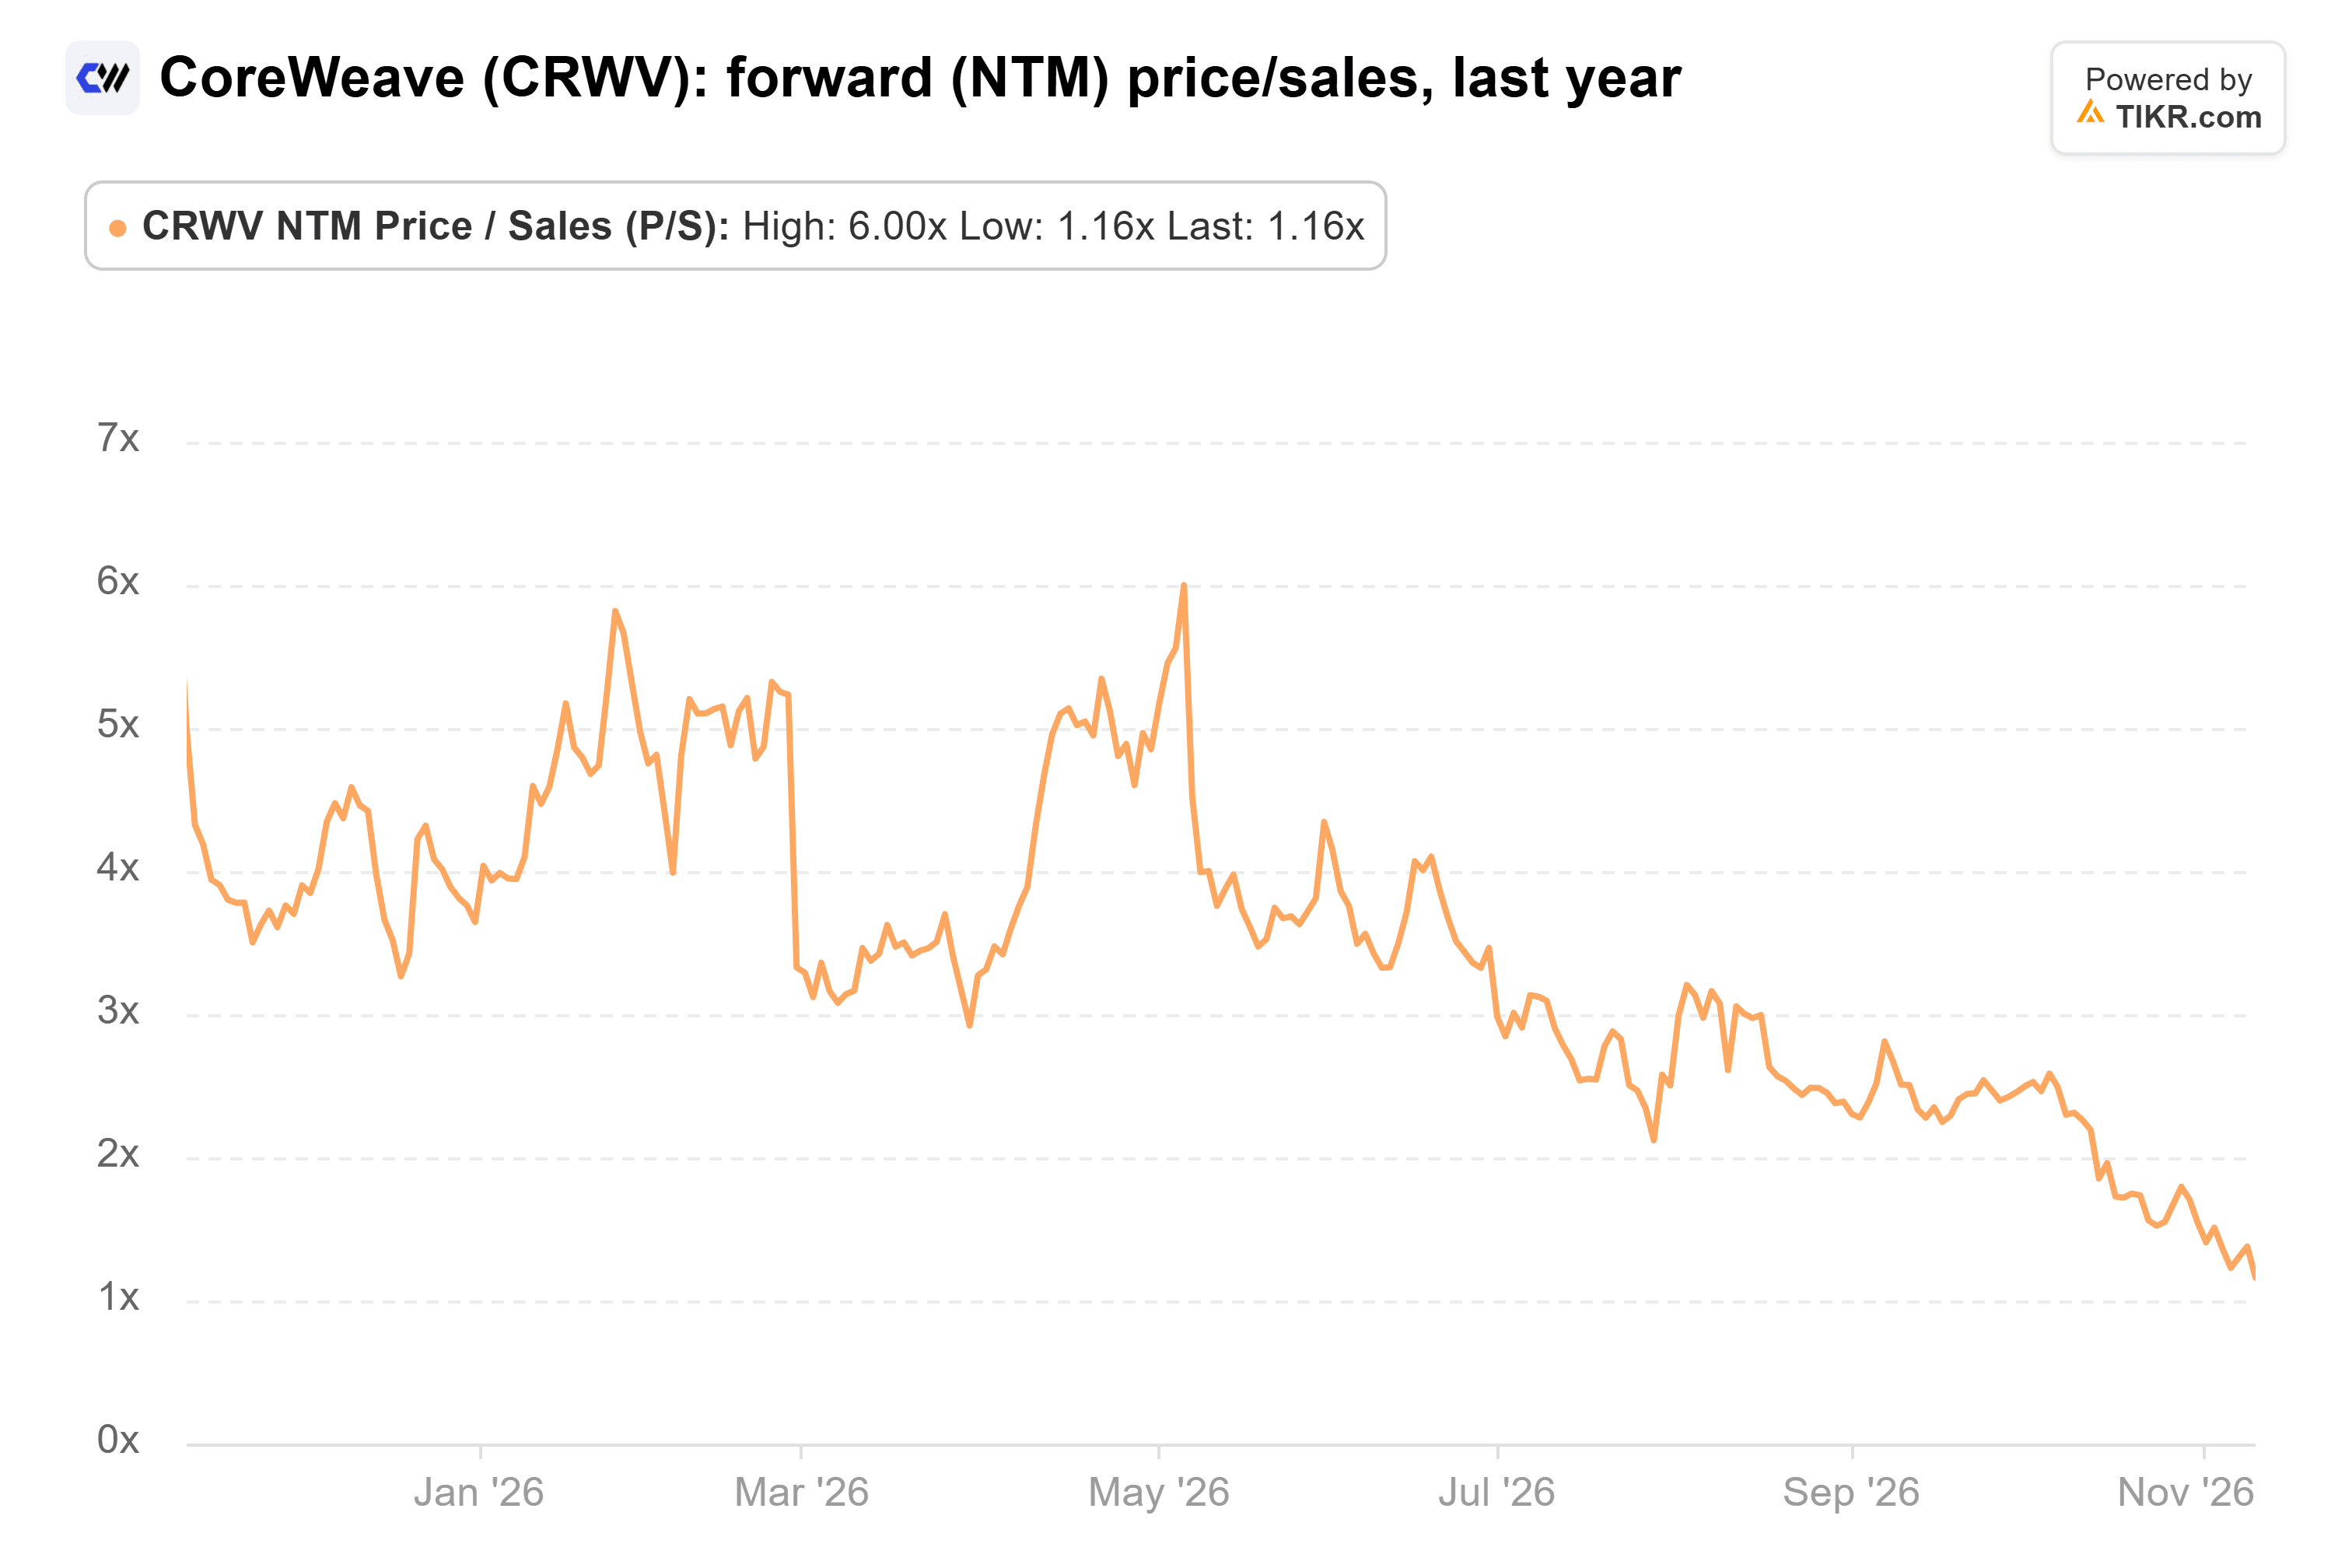
The $140 target works out to about 3.3x forward sales, so Liani isn’t asking for a peak multiple. On the bank’s own measure, though, the target rests on 26 times 2027 EV/EBIT, well above the 14x to 19x it uses for cloud data center peers.
Aim lower than $140
But loss estimates are getting bigger while sales estimates rise, and the difference is interest. Bank of America itself cut its 2027 forecast to a loss of $1.60 a share from 90 cents. Third-quarter interest of $846 million was more than double adjusted operating income, and CoreWeave guides $1.05 billion to $1.15 billion for the fourth quarter. Add an at-the-market program for up to 35 million shares and $4.2 billion of new convertible notes, and more of that revenue goes to lenders and new shareholders before it reaches today’s owners.
Bank of America is right that the stock looks too cheap for a business growing this fast. But Liani’s $140 dates to May, before October’s jump in borrowing costs. Jefferies, Baird, Cantor Fitzgerald and Truist kept bullish ratings after the report but cut their targets to between $90 and $115, and that range looks like the likelier landing over the next year. CoreWeave expects to launch its next contract-backed loan in the coming weeks at a yield of 7% to 7.5%, and a deal at that price would make the higher targets easier to believe.
So what is CoreWeave stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CoreWeave could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!