Key Takeaways
- Anthropic opened 34% above its $83 IPO price in its Nasdaq debut today, and Melius Research initiated coverage at Buy with a two-year $155 target, 63% above today’s price.
- Melius is betting on margins, and it pitches Anthropic as a hedge, since a computing slowdown would hurt chipmakers like Broadcom and lower Anthropic’s costs.
- Analysts expect Anthropic’s revenue to reach $145 billion in 2027 alongside a loss per share, and some of that growth has to come from enterprise budgets Salesforce is chasing too.
- Melius may be right about the margins, but $155 is an early bet on a company with a 2027 loss ahead and nearly $900 billion of computing commitments to pay for.
Anthropic (ANT) opened at $111.50 in its Nasdaq debut today, 34% above its $83 IPO price. Melius Research’s Ben Reitzes initiated coverage at Buy with a two-year target of $155, 63% above today’s price of $95.19.
Reitzes even pitches Anthropic as a hedge within AI: a slowdown in computing demand would hurt chipmakers like Broadcom (AVGO) and lower Anthropic’s costs. But the revenue Melius is counting on has to come partly from the corporate budgets Salesforce (CRM) is chasing with its own AI agents.
Melius is betting on margins
Melius values Anthropic at 6x the roughly $430 billion of revenue it projects for 2029. Reitzes points to Anthropic’s cost to serve customers, which Melius puts at 14 cents per dollar of revenue, down from about $2 in 2024. “We see $5+ in long-term earnings power with the ability for operating margins to top 30%, delivering significant EPS leverage by CY29/30,” he wrote.
That hedge has a flip side for Broadcom. Hock Tan said on Broadcom’s fiscal third-quarter call in September that “Anthropic is on track to become our largest XPU customer in 2027 and sustain that in 2028.” So a slowdown that helps Anthropic’s margins would hit Broadcom’s biggest custom-chip customer, and Broadcom’s Dec. 9 report is the next read on Anthropic’s orders.
See analyst ratings on Anthropic (it’s free):
See the full breakdown of Buy, Hold, and Sell ratings on Anthropic, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Anthropic’s Analyst Ratings
Does $155 add up?
Analysts’ revenue estimates show how fast Anthropic is expected to grow:
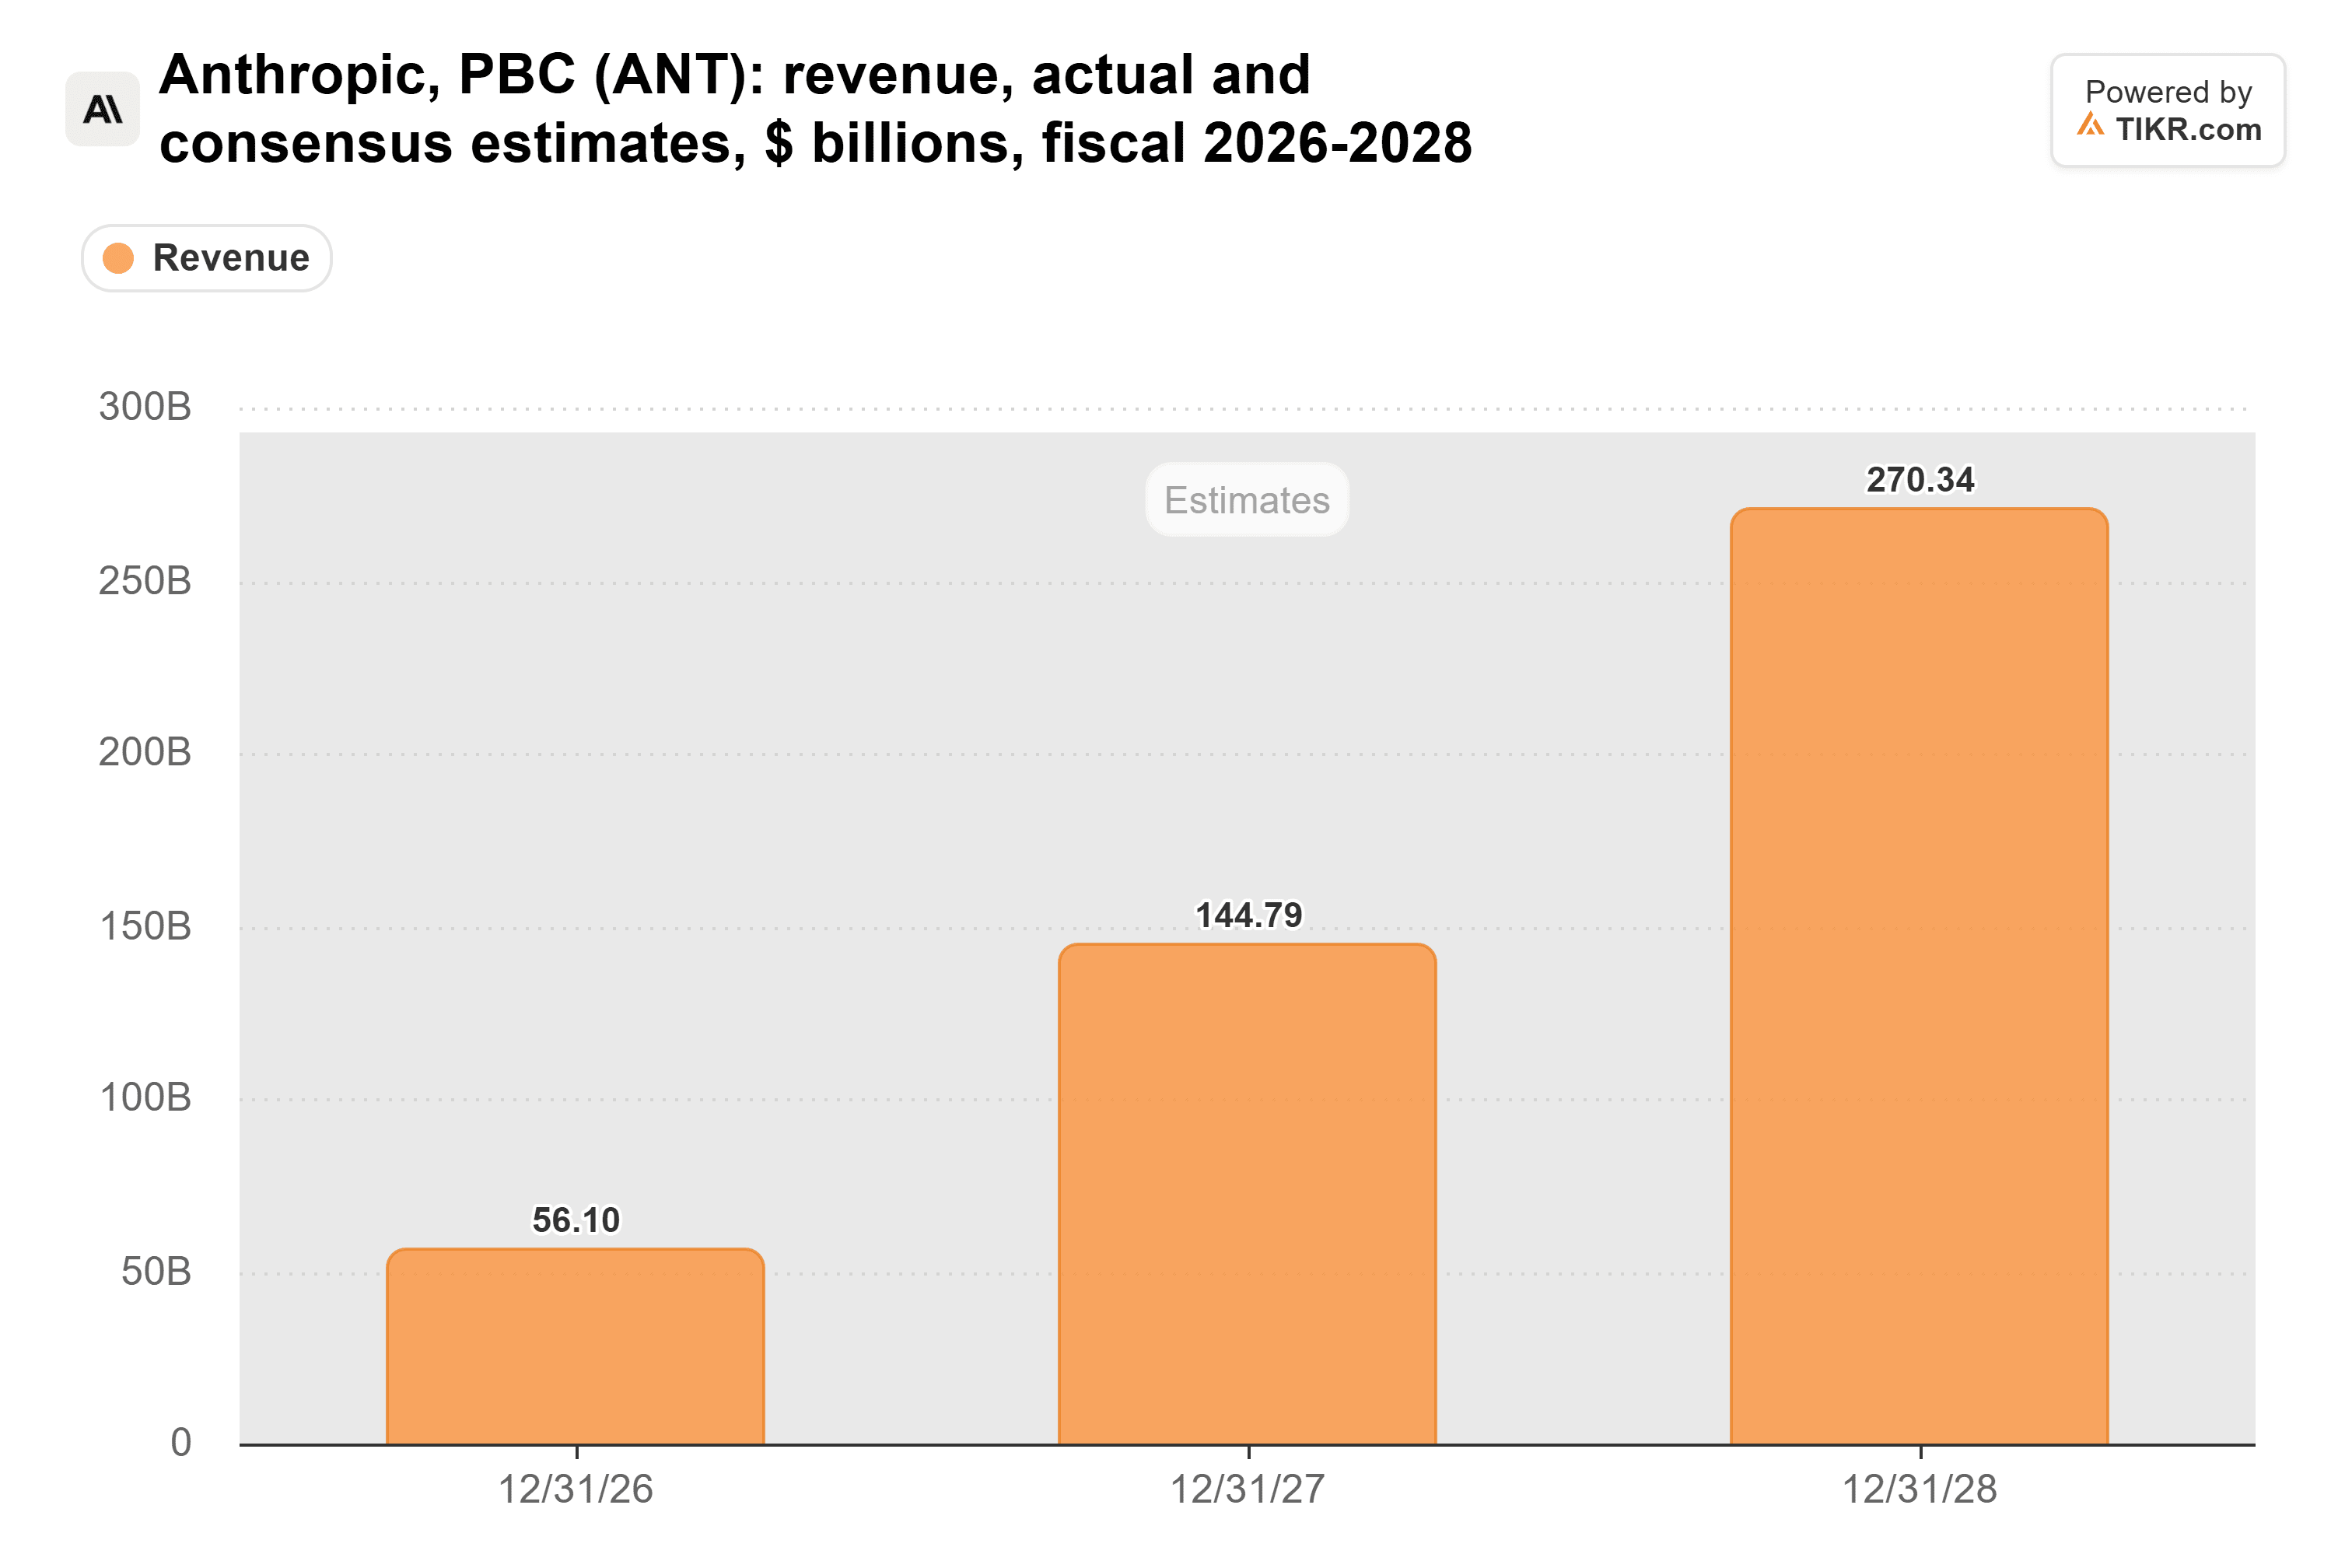
Melius’s $430 billion for 2029 is well above even the $270 billion consensus has for 2028. And the two analysts with published earnings estimates expect Anthropic to lose $0.12 a share in 2027, so there’s no profit yet to put a multiple on. Two years from now, $155 needs investors to believe in 2029’s revenue and 30%-plus margins at once.
A lot has to go right first
The bill is the main risk. Anthropic has nearly $900 billion of computing commitments with partners including Amazon and Google, against the record $107.3 billion its offering is set to raise.
The revenue has to come from somewhere, too. Salesforce’s Agentforce annual recurring revenue passed $1.5 billion in its quarter ended July 31, up more than 240%, and its Dec. 2 report will show whether enterprise AI budgets look big enough for both companies.
Bottom line: Melius may be right about where Anthropic’s margins end up, but $155 is too early a bet. Anthropic’s first full-year report as a public company, likely early next year, needs to show 2026 revenue near the $56.1 billion consensus and a gross margin near the 85% Melius cites before I’d pay up for 2029.
So what is Anthropic stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Anthropic could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!