Key Takeaways
- Dorsal Capital Management, which manages $6.64 billion, sold all of its Home Depot and Nexstar Media shares in the third quarter, according to its latest 13F.
- The same filing shows bigger stakes in Meta and US Foods, which are now two of the fund’s six largest positions.
- Home Depot’s consensus price target and earnings estimates have fallen over the past year, and management trimmed its full-year outlook on Nov. 17.
- Nexstar trades at about 8x forward earnings after a record quarter, and of the two it’s the one I’d rather own today.
Dorsal Capital Management just got out of two dividend payers. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows no shares left in Home Depot (HD) or Nexstar Media (NXST). It held both at June 30.
Two exits, two bigger bets
Dorsal manages $6.64 billion in all, and its 13F listed $2.86 billion of US stocks across 20 positions at Sept. 30. Home Depot had been a big position: 600,000 shares worth $212 million at June 30, or 7.6% of its 13F stocks. Nexstar was smaller, at 250,000 shares worth $45 million, or 1.6%.
The same filing shows the fund putting more money into two other stocks. It added 27% to its Meta Platforms (META) stake. That’s now 280,000 shares and its No. 4 position, at 7.1% of its 13F stocks. It also raised its US Foods (USFD) share count 533% to 1.90 million, its No. 6 position at 6.1%. Since Sept. 30, Meta has fallen 15% and US Foods has gained 17%.
TIKR tracks 36 analysts on Home Depot. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Home Depot, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Home Depot’s Analyst Ratings
Home Depot’s estimates keep coming down
Home Depot is down 4% since Sept. 30, and its third-quarter report on Nov. 17 was a mixed bag. Sales rose 4.9% to $43.4 billion. US comparable sales grew 2.2%, up from 1.3% in the second quarter. Adjusted EPS of $3.86 edged past the $3.84 analysts expected.
But the outlook got worse. Management narrowed its fiscal 2026 guidance for comparable sales growth to about 1.4%, from flat to 2%. It narrowed adjusted EPS growth to about 2%, from flat to 4%. Operating margin slipped to 12.6% from 12.9% a year earlier. And it cut the organic growth outlook for SRS to low single digits from mid-single digits after two weak storm seasons. SRS is the biggest piece of the $24.2 billion Home Depot has spent on wholesale distributors to win Pro contractors.
Dorsal had company on the way out: Lone Pine Capital sold its entire Home Depot stake in the third quarter, too. Home Depot also named CFO Richard McPhail its next CEO, effective Nov. 23, so a new team will set next year’s plan.
Analysts have been cutting their targets all year. The consensus target has slid from $420 a year ago to $377.
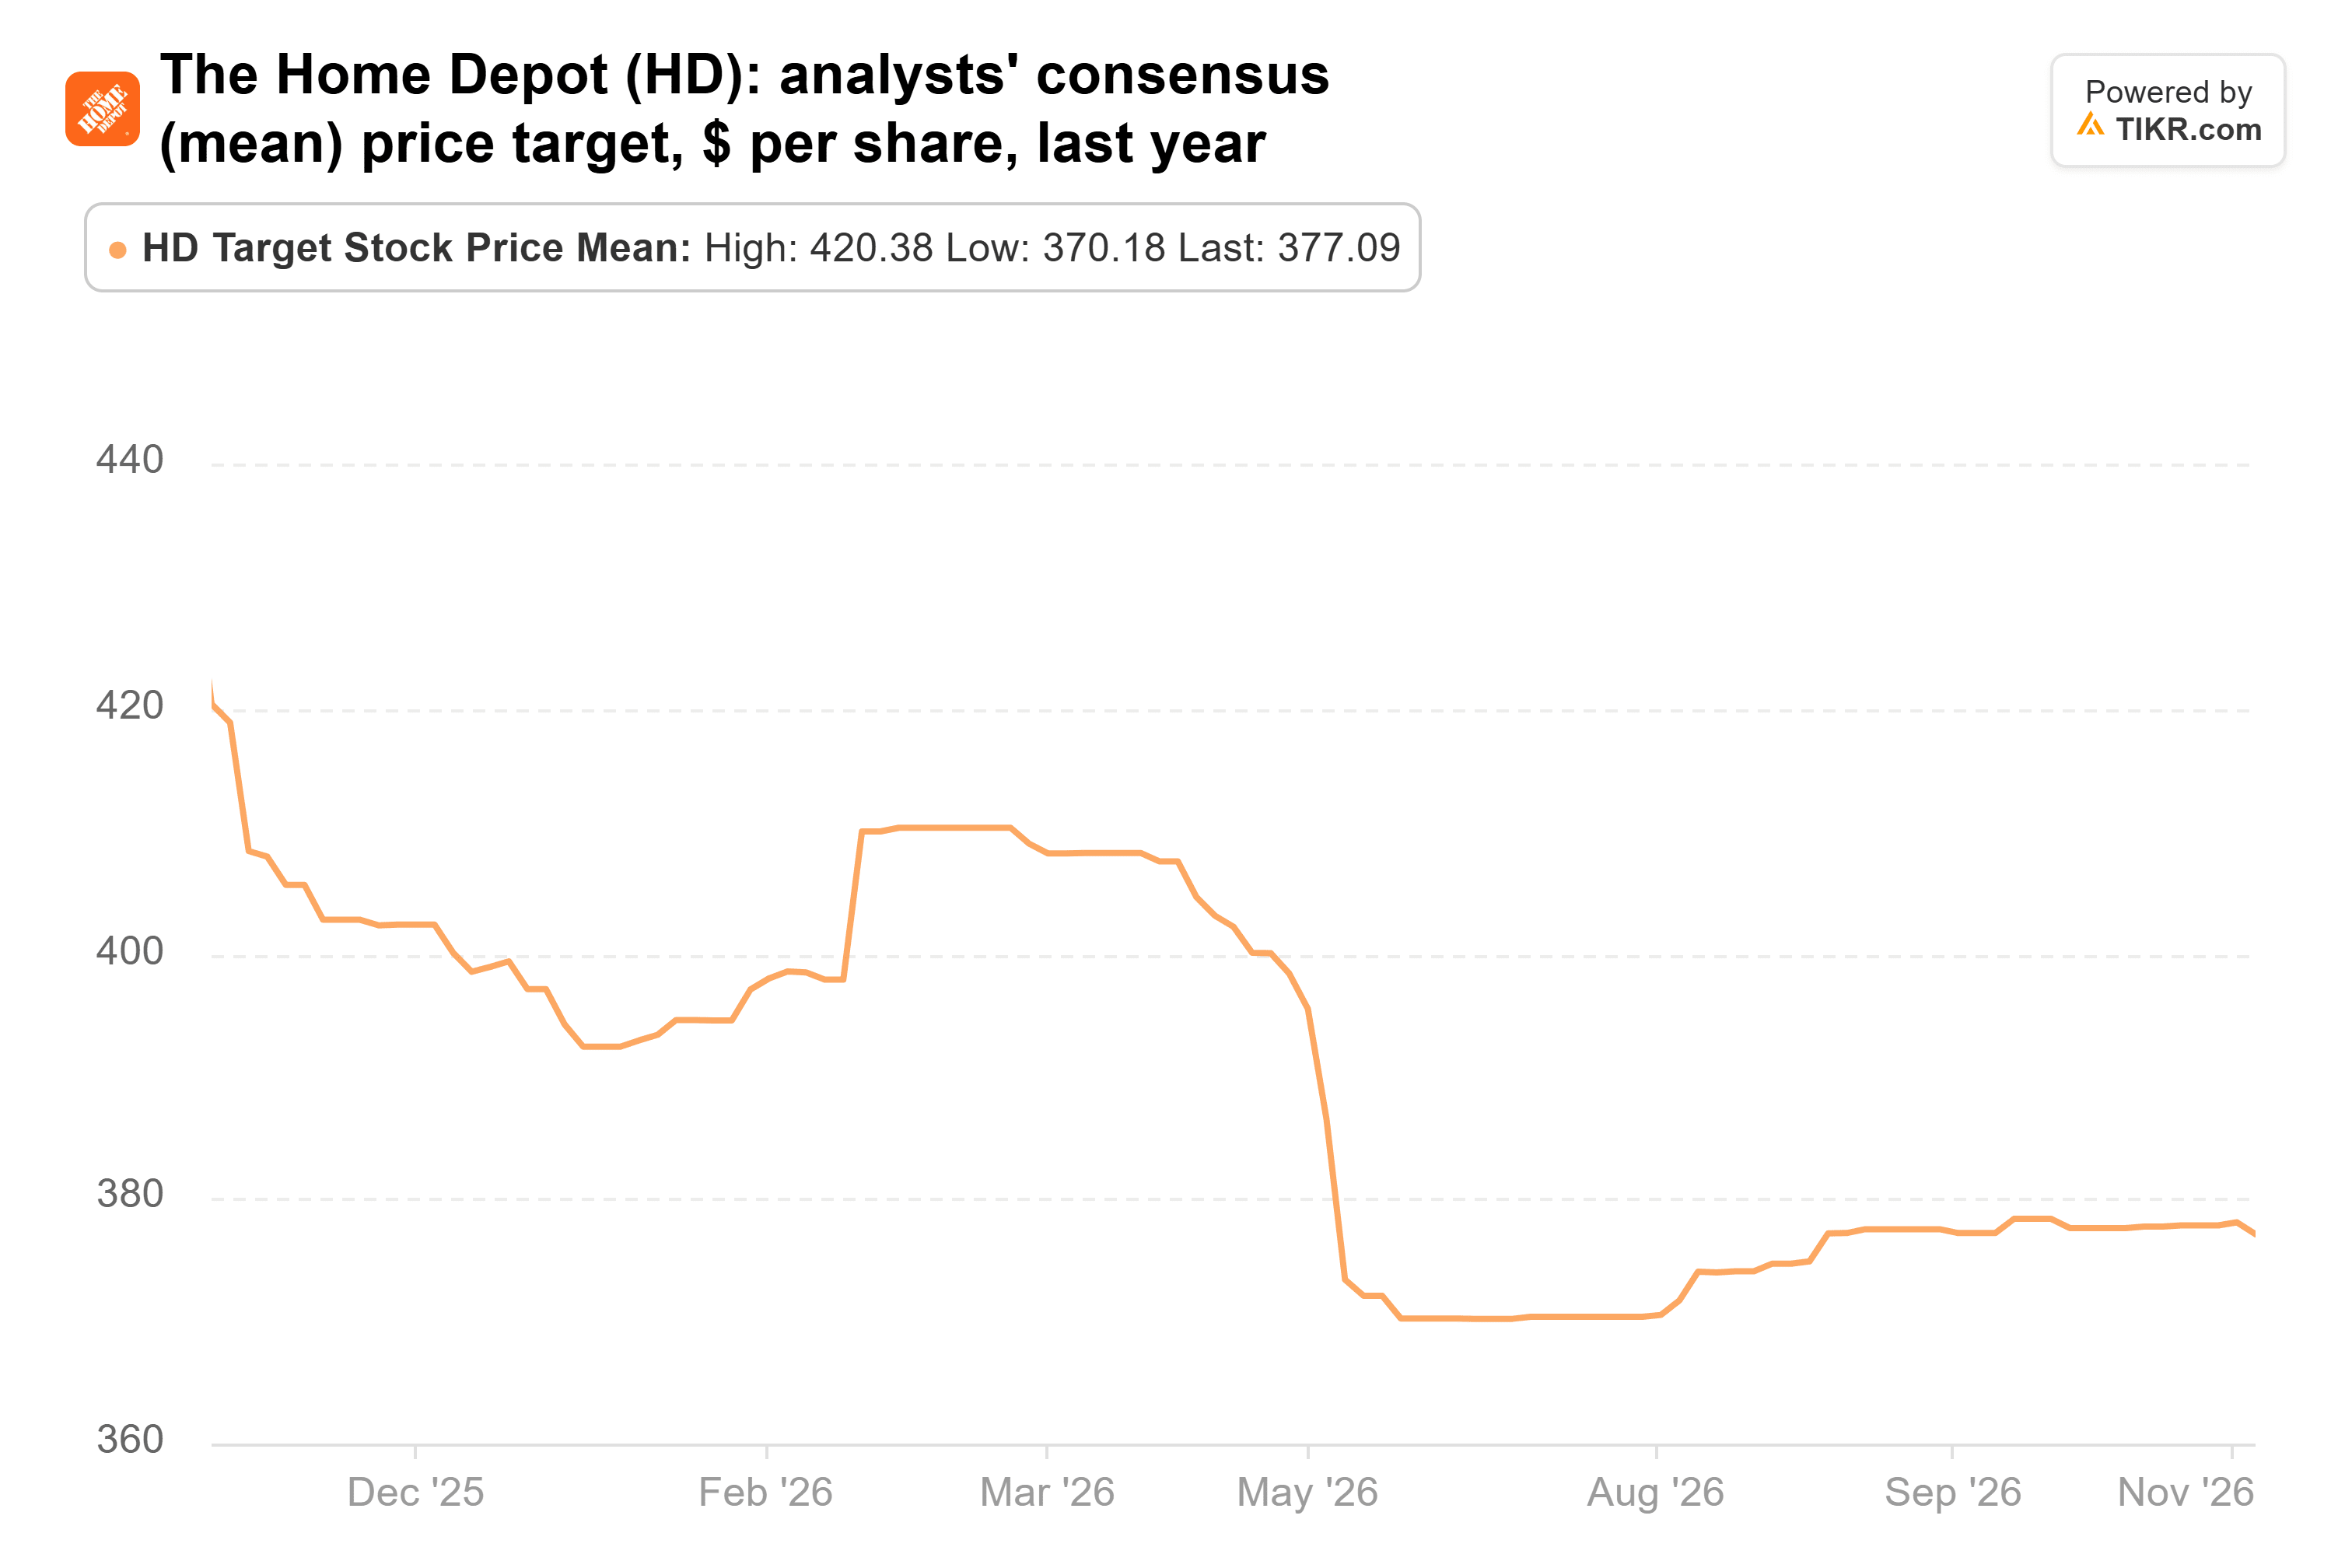
That’s still 12% above the last close of $337.64, but the estimates behind it keep falling. Consensus for fiscal 2027, the year ending January 2028, was down to $15.90 a share from $17.74 at the end of September 2025, and that was before the trimmed guidance. At about 22x forward earnings, the stock trades right around its 21.4x average since 2014.
So you’re paying Home Depot’s usual multiple for earnings that keep getting revised lower, with a 2.8% yield while you wait.
Nexstar just put up a record quarter
Nexstar has gone the other way and is up 15% since Sept. 30. In its third-quarter release on Nov. 5, net revenue rose 78% to a record $2.13 billion. Two things drove it: Tegna, the station group Nexstar bought for $6.2 billion in March, and $317 million of political ads, a third-quarter record in a midterm year. Distribution revenue, the fees pay-TV and streaming services pay to carry its stations, rose 53.9% to $1.09 billion. Tegna added $352 million of that. Adjusted EBITDA more than doubled to $756 million.
Analysts have been raising their targets. The consensus target has climbed from $232 to $245 over the past year, though it’s still below its $271.50 high from March.
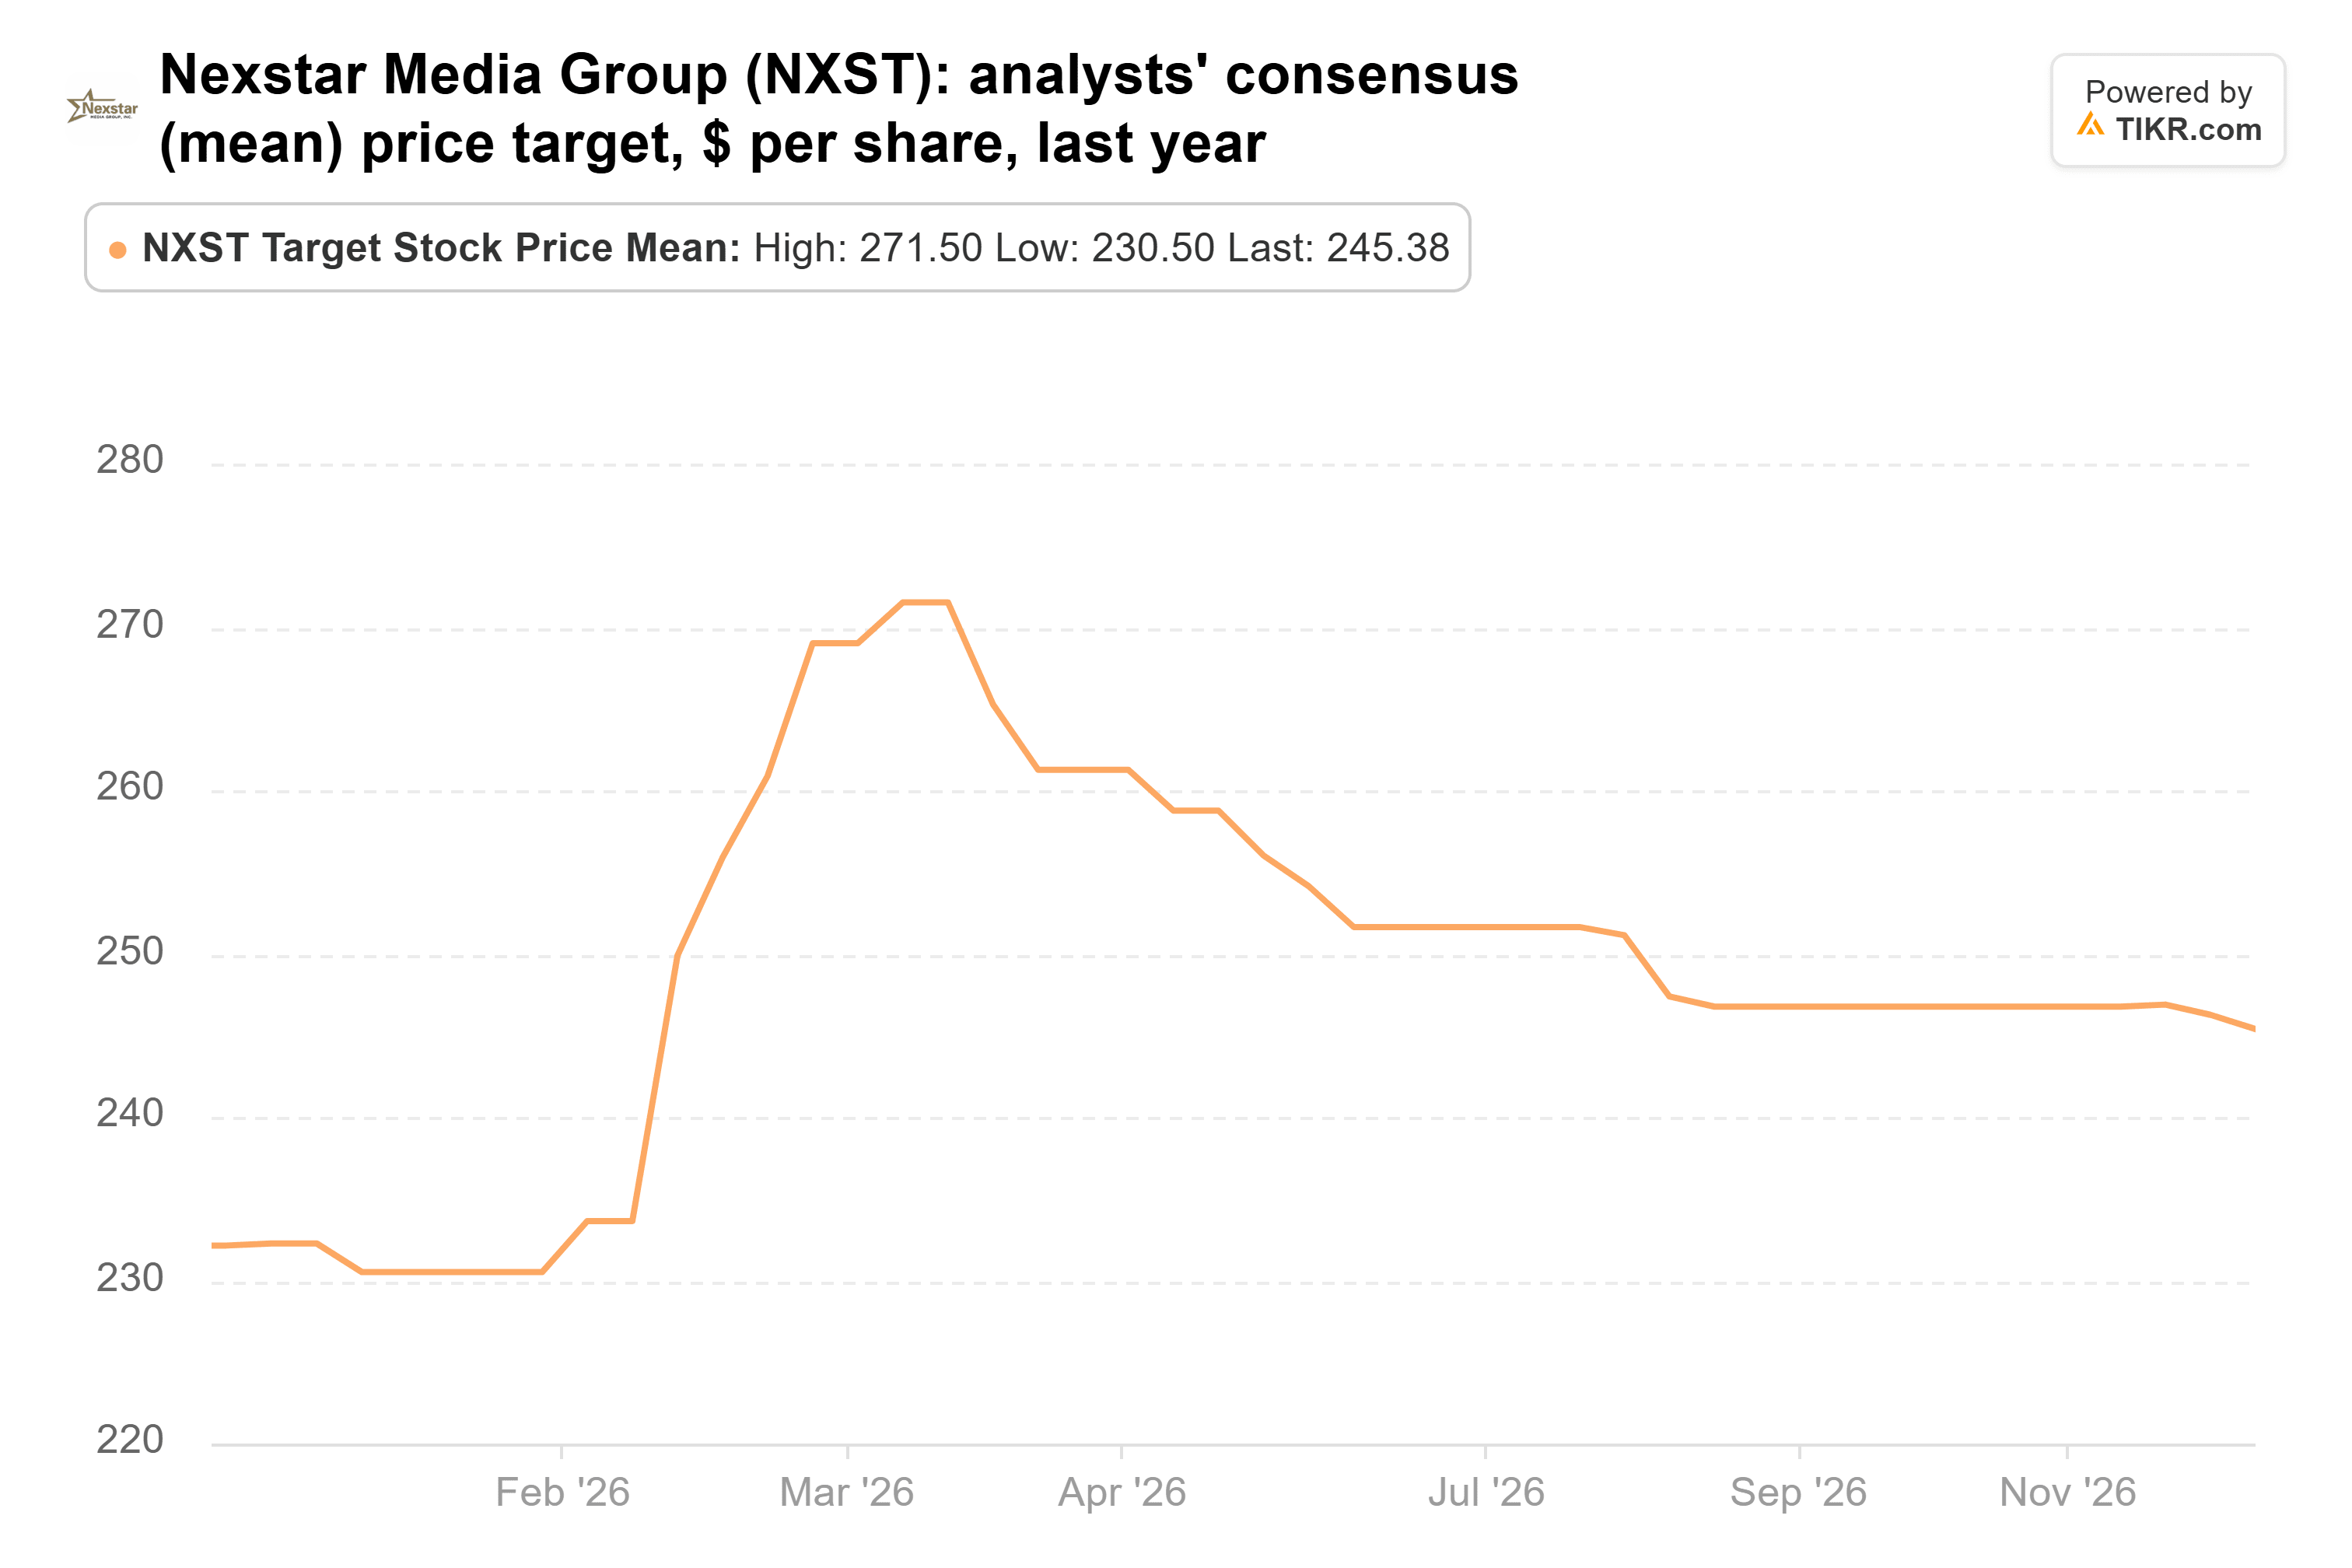
That’s 20% above the last close, and the stock trades at about 8x forward earnings with a 3.6% yield.
Next year has no midterms, so the political money behind this quarter’s record won’t come back at that size. Pay-TV subscriber losses also still weigh on distribution revenue. And eight state attorneys general and DirecTV sued to block the Tegna deal the day it closed. Even so, I think investors paying 8x are already braced for a quieter 2027.
Who’s right?
On Home Depot, the numbers side with Dorsal. The stock trades at its usual multiple while estimates keep falling, and the new CEO has yet to give his first full-year outlook. On Nexstar, I think the fund is wrong to walk away: a record quarter, a rising consensus target and a single-digit multiple make a strong case for owning it.
If I could only buy one of the two right now, it’d be Nexstar. It’s cheaper, it pays more, and analysts are still raising their targets.
Home Depot’s fourth-quarter report in February will bring McPhail’s first fiscal 2027 outlook. If he guides above the $15.90 consensus, Dorsal’s exit will look premature. Nexstar’s fourth-quarter report early next year should give the first read on a year without much political ad money. And Dorsal’s next 13F, due by mid-February, will show whether it came back to either one.
So what is Home Depot stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Home Depot could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!