Key Takeaways
- Coinbase stock fell 13% in the past month (through Monday’s close). The S&P 500 rose less than 1% over the same stretch, and other crypto stocks fell with Coinbase.
- The month’s worst day was a 4.9% drop on Oct. 14, after Coinbase told Bitcoin’s developers to start preparing for quantum computers.
- Analysts expect a normalized loss of $1.87 a share for 2026, and the stock trades at about 169x forward earnings against a five-year average of 28.2x.
- Coinbase reports third-quarter results after the close on Oct. 29, and that report needs to show estimates turning up before the stock is worth loading up on.
Coinbase Global (COIN) stock is down 13.3% in the past month (through Monday’s close), while the S&P 500 rose 0.6%.
The count starts near a high point. On Sept. 18, the stock jumped 12% as Bitcoin climbed back above $80,000. That pop didn’t last, and the rest of crypto faded with it: Circle Internet Group (CRCL) lost 11.3% over the same month, and other crypto stocks fell too.
The four biggest sessions nearly canceled each other out, so most of the damage was a slow bleed.
Coinbase’s own warning landed on the worst day
Crypto was already jumpy about its math. On Oct. 7, Dragonfly’s Haseeb Qureshi posted on X about the problem Bitcoin’s signatures rest on:
“To be clear, if the discrete log problem turns out to be breakable by classical computers, it’s pretty much over.”
A week later, on Oct. 14, Coinbase had its worst day of the month. The stock fell 4.9% after the company told Bitcoin’s developers to start building defenses against quantum computers now. Coinbase says it holds about 5% of all Bitcoin for its customers, and it warned that upgrading the network could take years.
Coinbase never claimed today’s quantum computers can break Bitcoin. But when the custodian of that much Bitcoin says the fix takes years, it sounds like a threat to the asset its business runs on. I think that’s a real long-term question and a weak reason to sell this month.
TIKR tracks 38 analysts on Coinbase. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coinbase, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coinbase’s Analyst Ratings
The deals kept coming
On Sept. 28, Citigroup (C) expanded its partnership with Coinbase so Citi’s institutional clients can accept stablecoin payments. The same day, the CFTC approved Coinbase’s own clearing house. Coinbase also opened IPO allocations to US retail traders and signed stablecoin deals for payment cards and a mobile wallet.
None of it held the stock up. Coinbase fell 5.8% on Oct. 16, the same day as the card deal. Circle issues the USDC those payments run on, and it got no lift either.
Oct. 29 is the real test
Coinbase reports third-quarter results after the close on Thursday, Oct. 29.
The bar is low. Analysts expect revenue near $1.2 billion, down about 37% from a year earlier. That would follow three straight quarterly net losses, the latest $359.5 million in the second quarter. CFO Alesia Haas has also promised that 2026 expenses will look much like 2025’s (excluding USDC rewards), so most of any pickup in trading should go to profit.
There are early signs of that pickup. Barclays rates the stock Underweight, but on Oct. 7 it raised its target to $149 from $95 on better third-quarter volumes. Citi lifted its target to $230 on Oct. 13.
Is Coinbase a buy at this price?
The trouble is earnings. Normalized EPS was $9.48 in 2024 and $4.45 in 2025, and the consensus now calls for a $1.87 loss in 2026.
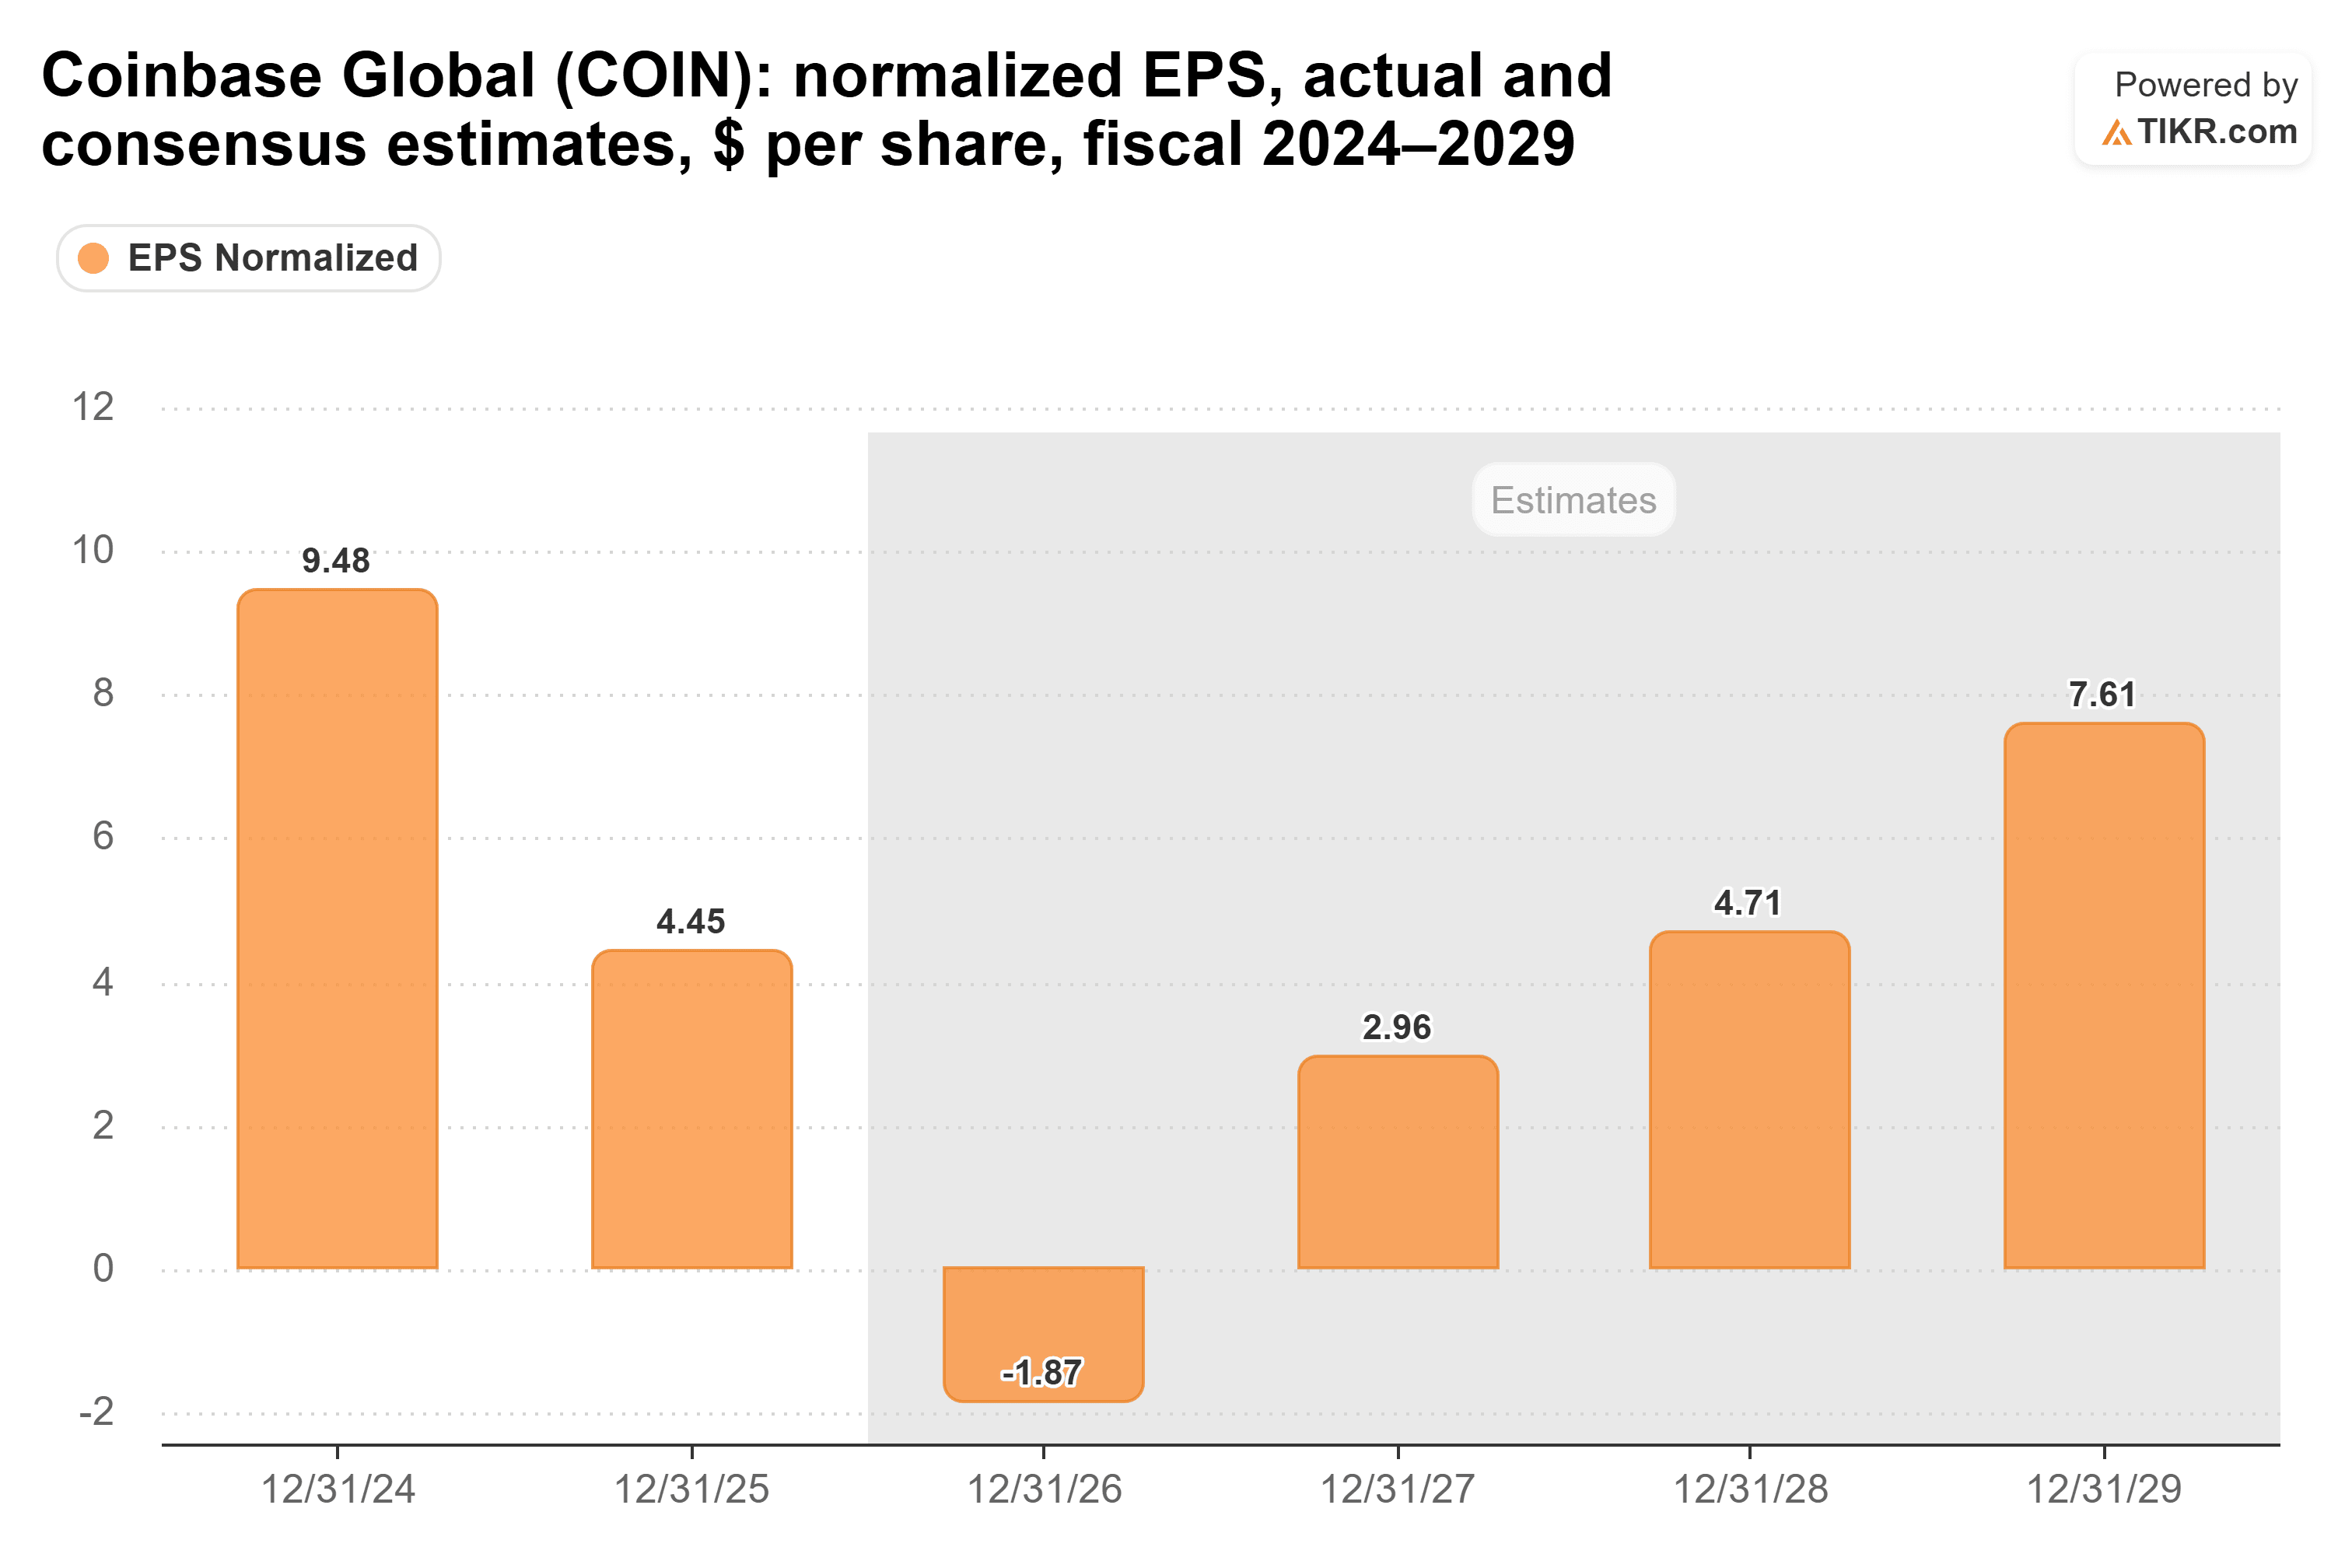
Even the $4.71 analysts expect for 2028 is about half of 2024’s.
That leaves the stock pricey against its own history.
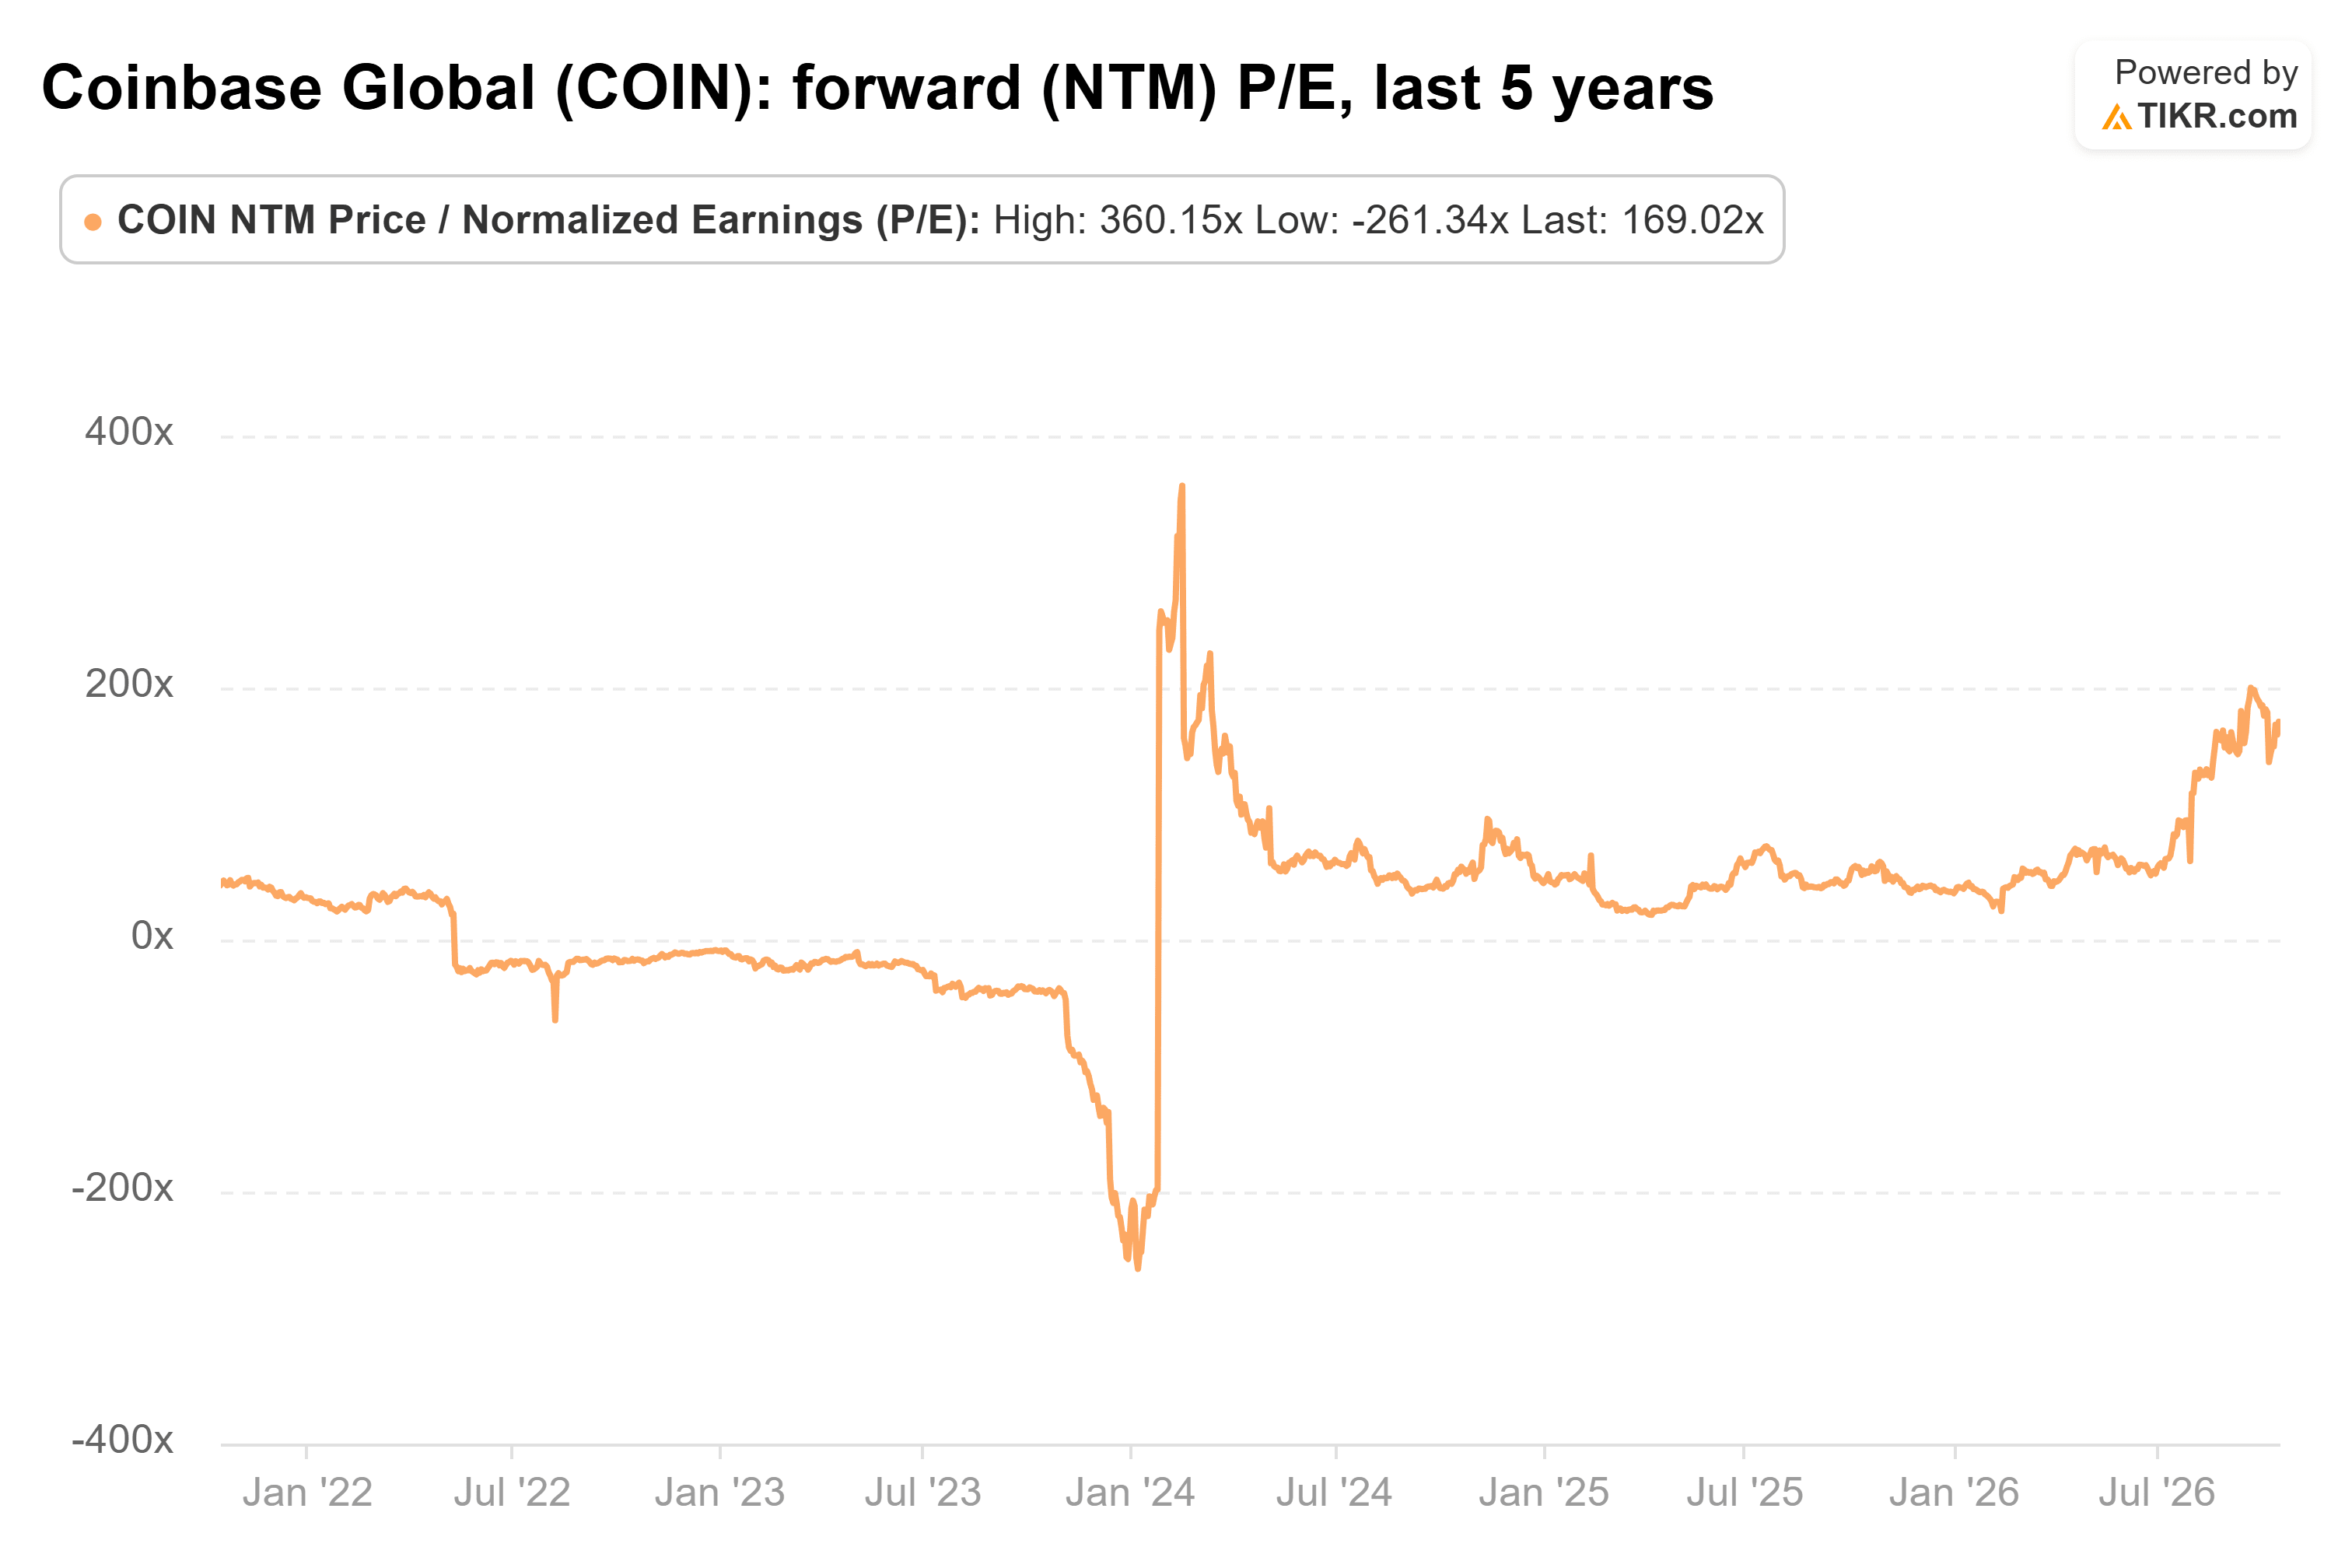
Coinbase traded at 169x forward earnings on Friday, against a five-year average of 28.2x. (It peaked at 360x, in February 2024.)
The Street is kinder. The consensus target has fallen from about $382 to $212 in a year, and it’s still about 26% above Monday’s close.
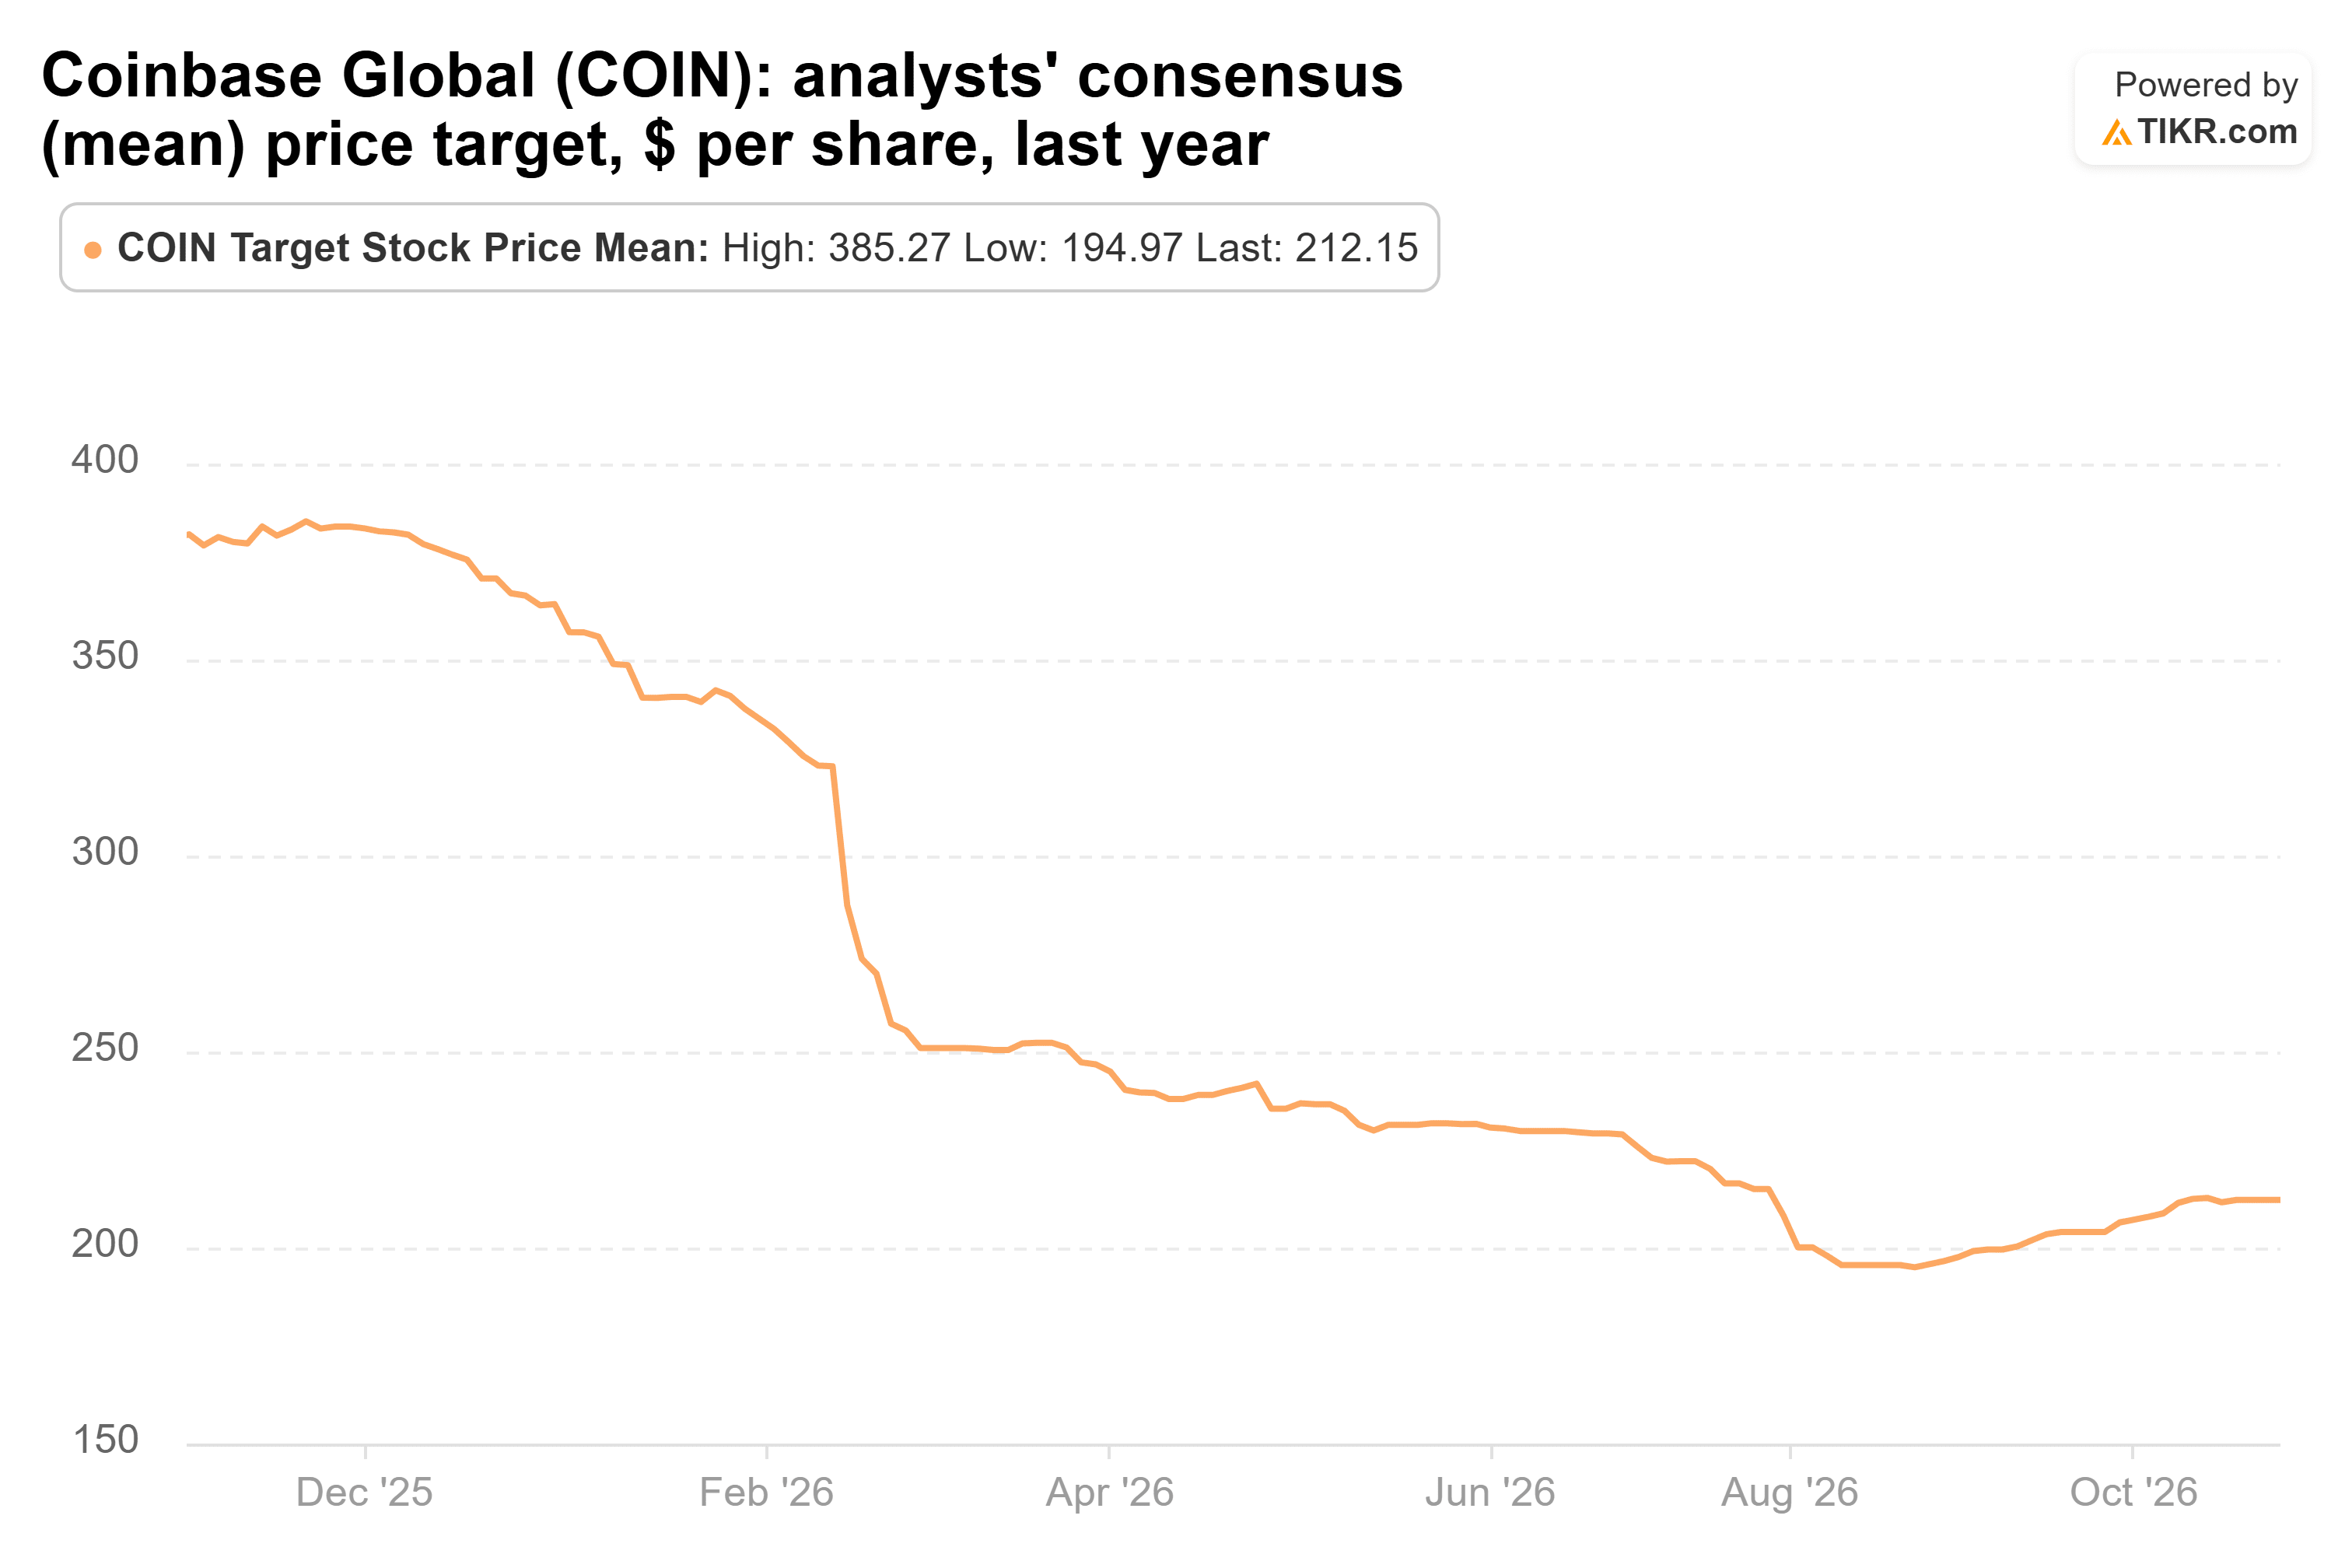
My take: The stock is down 55% from its 52-week high, and I wouldn’t sell here. But I wouldn’t load up either until Oct. 29 shows estimates turning up.
Of course, crypto moves faster than earnings estimates, and a Bitcoin rally could lift the stock well before the numbers catch up.
So what is Coinbase stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coinbase could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!