Key Takeaways
- Coinbase reports third-quarter results after the close on Thursday, Oct. 29, with its stock down 31% this year.
- CEO Brian Armstrong’s push into AI agents, stablecoins and tokenized stocks is still too small in dollars to move the quarter’s revenue.
- Analysts expect $5.30 billion of revenue for 2026, about 26% below 2025’s $7.18 billion, so revenue has to hold up for those estimates to stand.
- The numbers to watch are revenue, subscription and services revenue against the $500 million to $580 million guide, and adjusted expenses against the $980 million to $1.08 billion guide.
Coinbase (COIN) stock is down 31% this year, and CEO Brian Armstrong has spent the days before the company’s third-quarter report talking up AI agents, stablecoins and tokenized stocks.
The report comes out after the close on Thursday, Oct. 29. It’s the first real check on whether that pitch can steady a business that still rises and falls with crypto trading.
TIKR tracks 38 analysts on Coinbase. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coinbase, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coinbase’s Analyst Ratings
A busy week for the pitch
The announcements have come fast…
- On Oct. 22, Coinbase launched a Coinbase for Agents page that shows users how to connect ChatGPT, Grok, Muse or another agent to research, manage a portfolio, and trade crypto and stocks.
- Armstrong followed up the same day: “We’re building Coinbase to be the most AI-enabled financial account.”
- Aave is bringing lending and borrowing to Coinbase’s tokenized stocks on Base. Deposits on Aave V4 reached $10.1 million, about 53% of the $18.9 million across DeFi venues, according to Token Terminal.
- Coinbase also added fixed-rate Bitcoin-backed loans through Morpho on Sept. 22.
Big pitch, small dollars
Next to the rest of the business, those figures are tiny. The $18.9 million deposited across DeFi venues compares with $245.9 billion of assets on Coinbase’s platform at June 30.
Trading and stablecoins still drive the results. In the second quarter of 2026, consumer transaction revenue fell 31% from a year earlier to $451.7 million, as consumer spot volume fell 38%. Subscription and services revenue, the part meant to steady things in a slump, slipped to $555.1 million. That was below management’s own $565 million to $645 million guide.
Revenue has to hold up
Wall Street expects 2026 revenue of $5.30 billion, about 26% below 2025’s $7.18 billion.
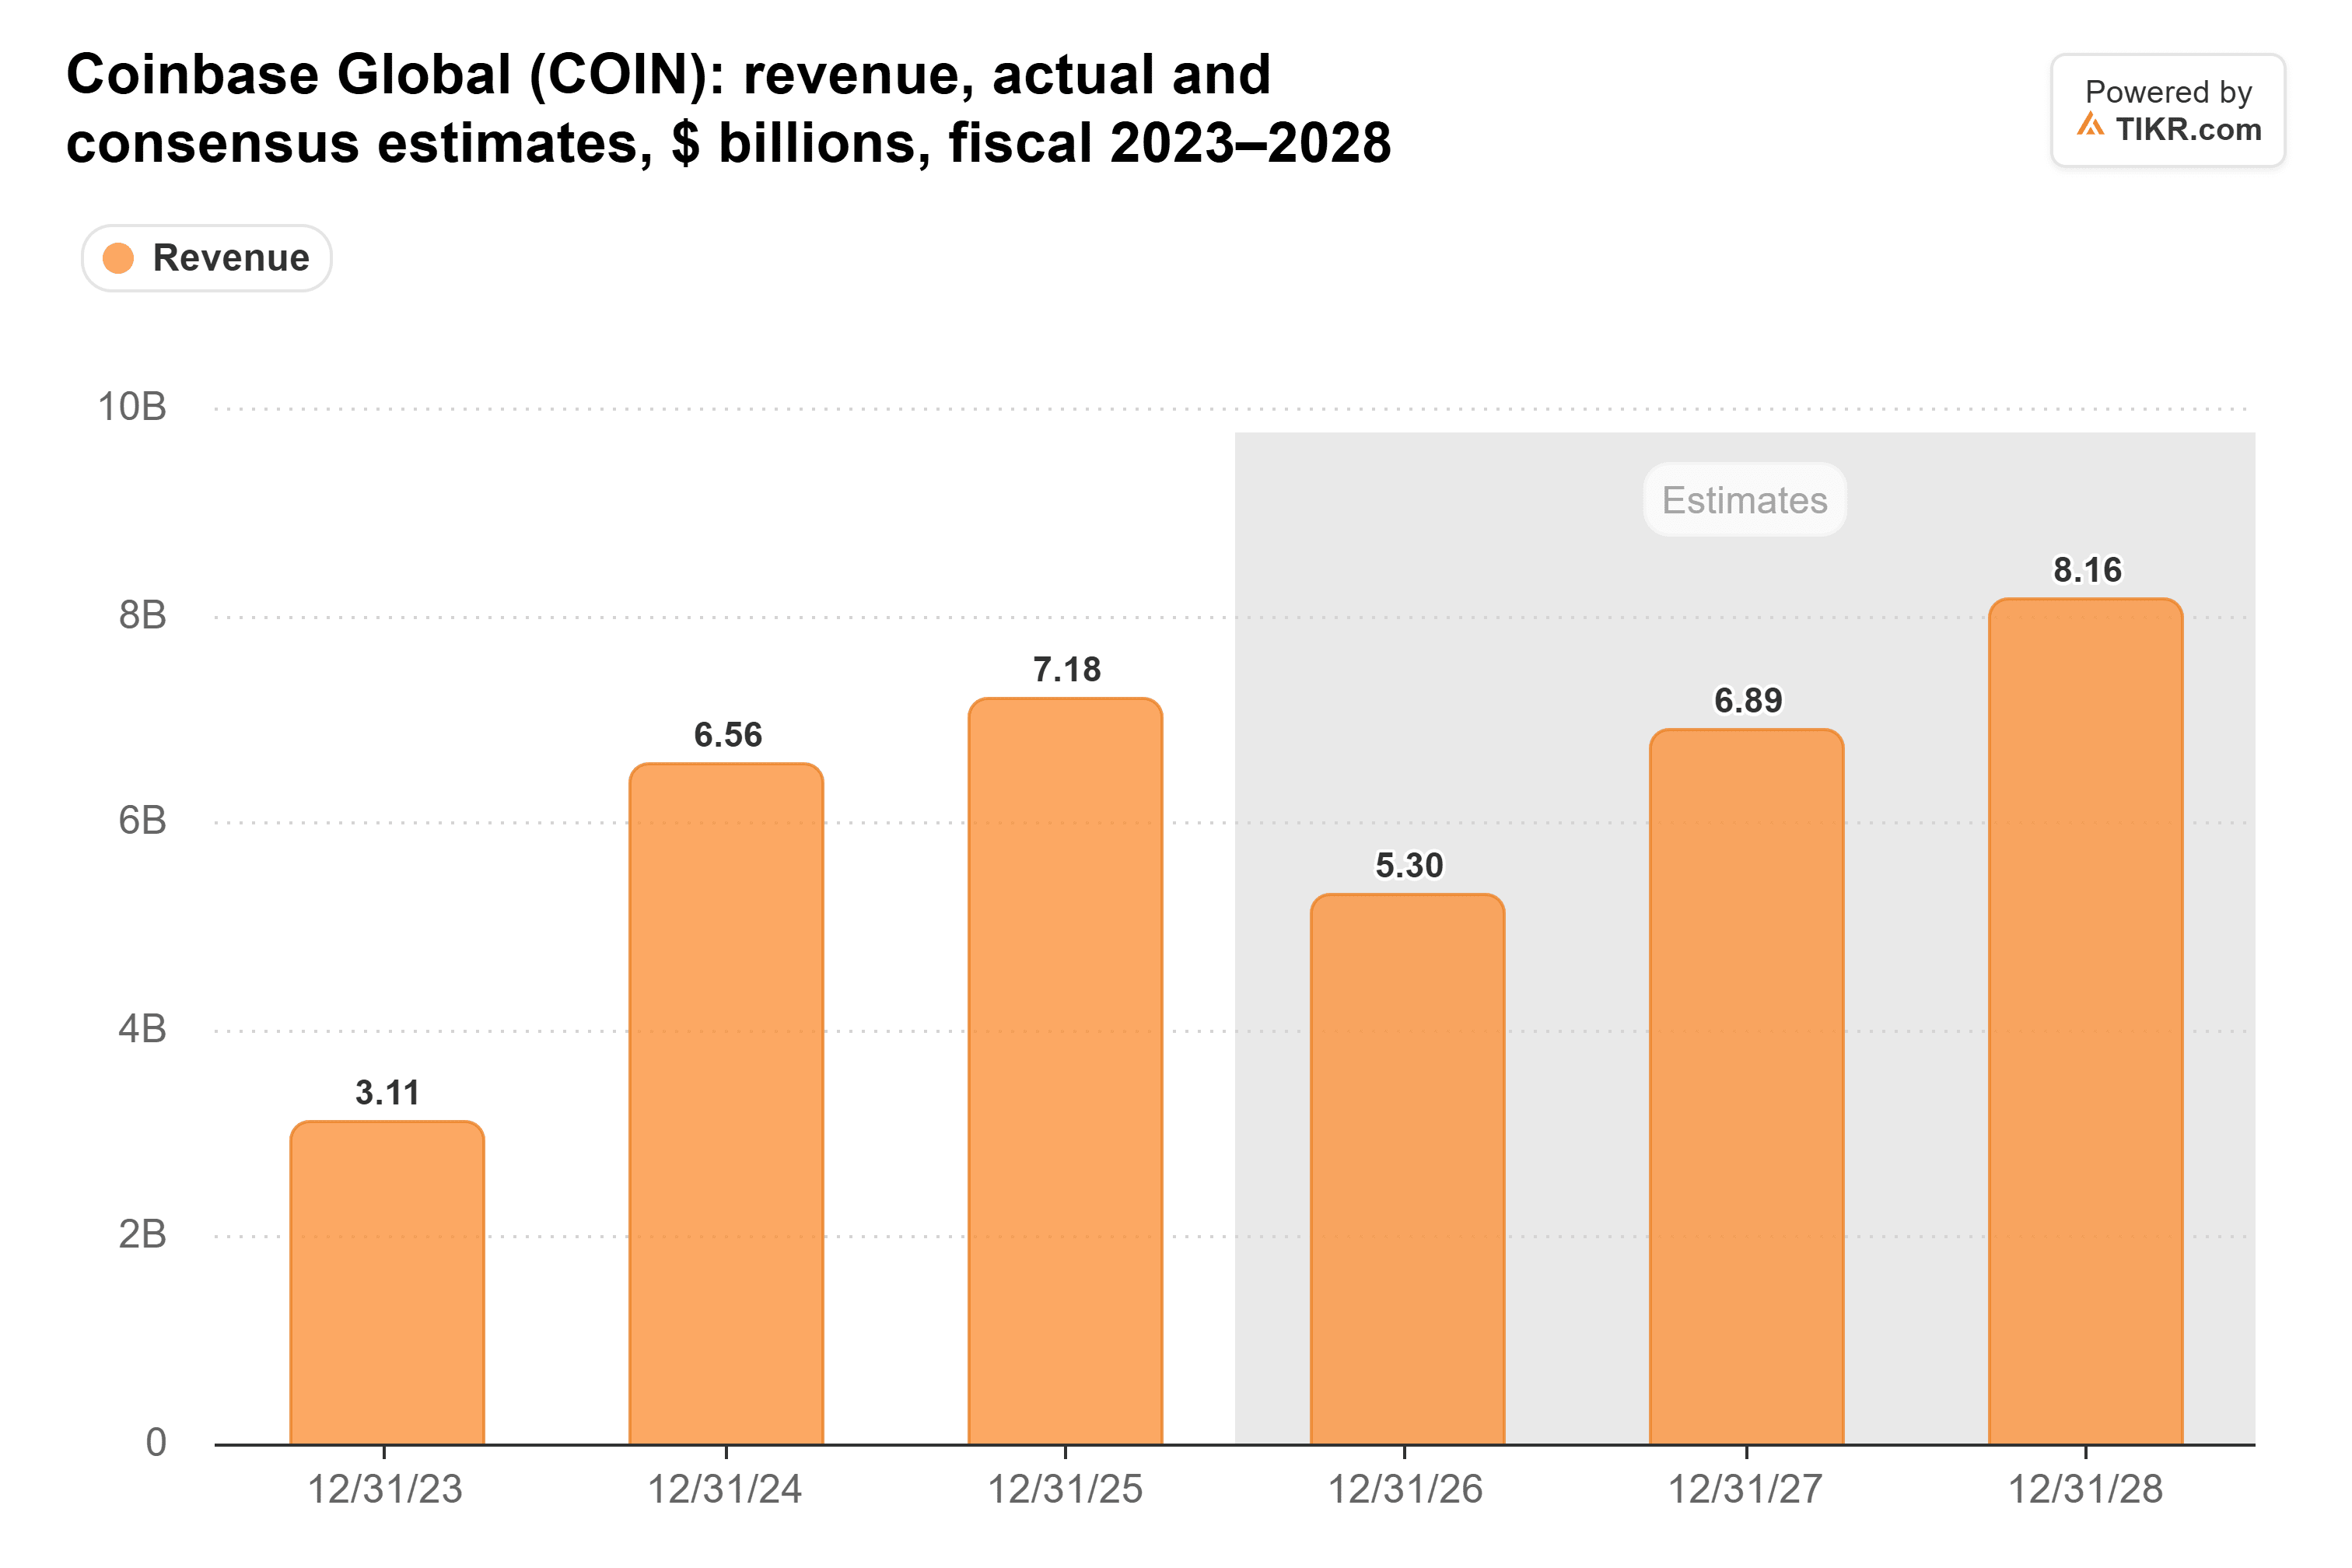
Even the $6.89 billion analysts expect for 2027 falls short of last year.
Coinbase booked $2.63 billion in the first half. To reach the consensus, it needs about $1.3 billion a quarter in the second half, more than the $1.22 billion it reported in the second quarter. The third quarter started slowly, too: Coinbase said transaction revenue was about $130 million through July 26, against roughly $200 million a month in the second quarter.
So Thursday’s bar is a quarter near $1.3 billion, with subscription and services revenue inside the new $500 million to $580 million guide. If revenue falls well short, the 2026 estimates will likely come down again.
Costs are the lever Coinbase controls
Coinbase’s EBITDA margin has swung with every crypto cycle. It went from 42.6% in 2021 to -81.3% in 2022, back up to 34.4% in 2024 and down to 24.3% in 2025.
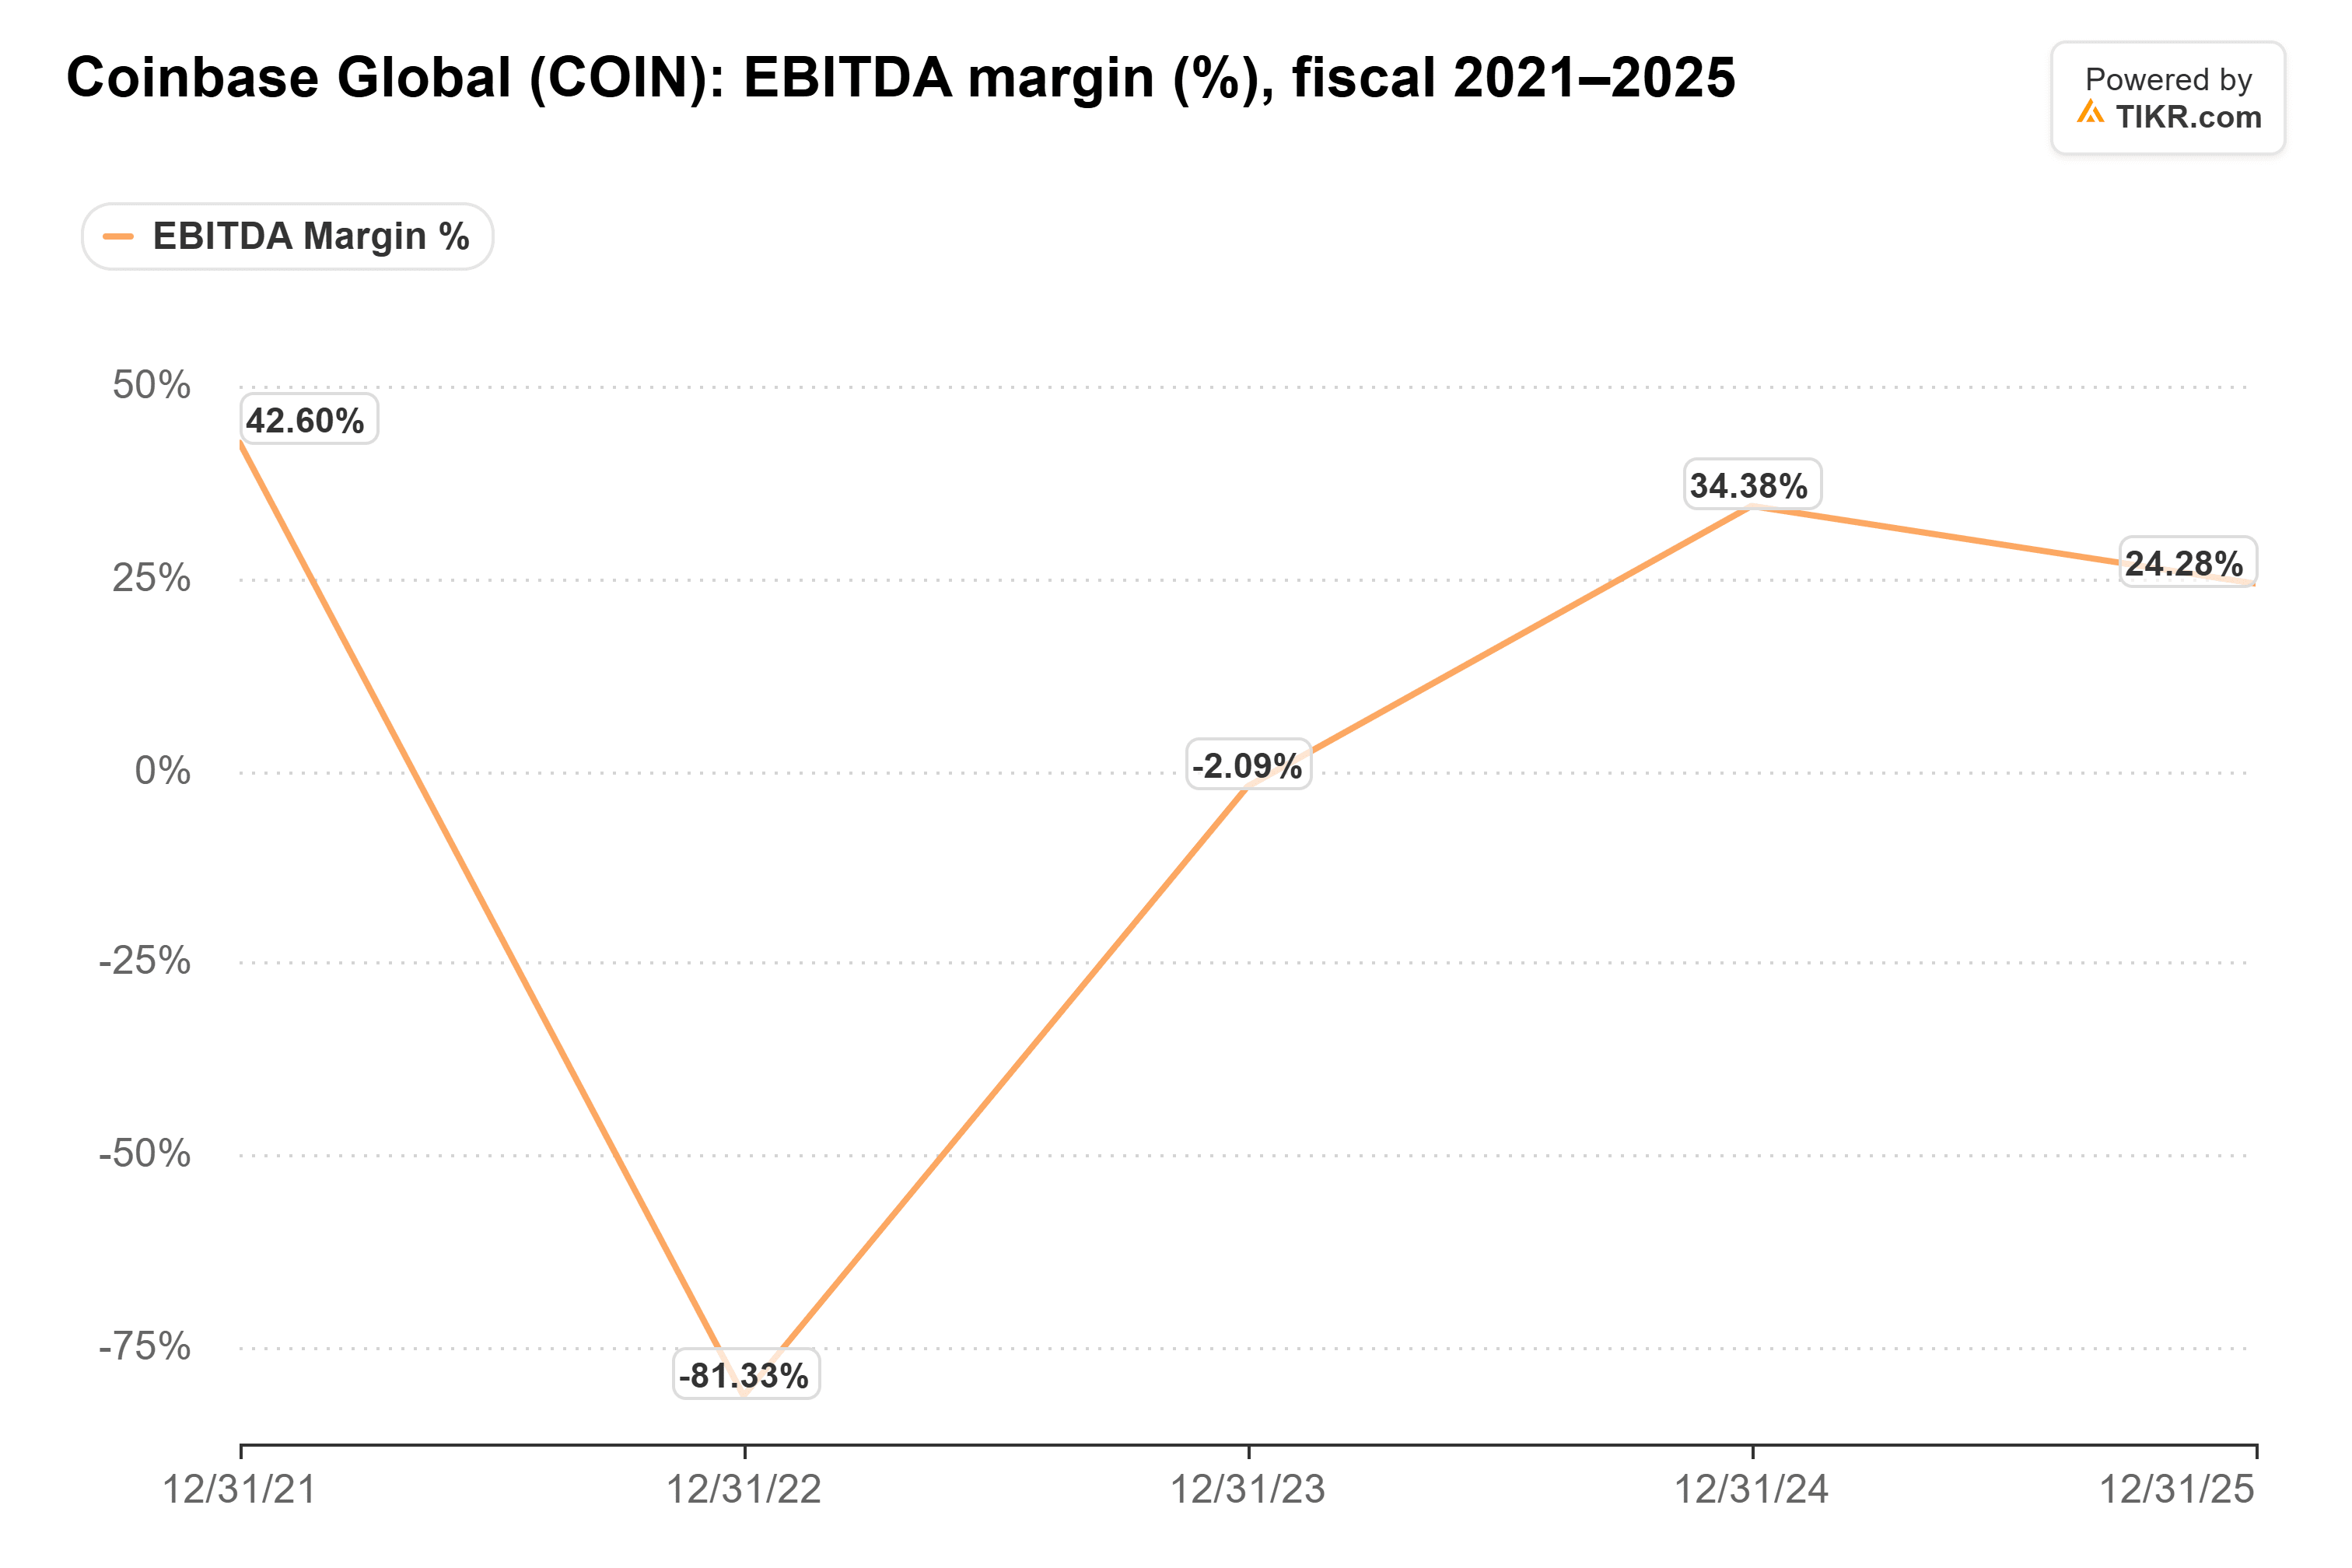
This year has been harder: Coinbase posted GAAP operating losses in both the first and second quarters of 2026.
After cutting about 700 jobs in May, management guides third-quarter adjusted expenses of $980 million to $1.08 billion. For all of 2026 it guides $4.2 billion to $4.45 billion, against $4.28 billion in 2025. This is the first full quarter since the cuts, so a figure at or below the midpoint would show that margins can hold up in a slow year.
The stock is already priced for a rebound
At about 108x forward earnings, the market is paying for a recovery. Analysts expect $1.20 a share of normalized earnings over the next twelve months, against an average of $3.45 over the past year.
My take: the agent and tokenized-stock pitch could matter in a few years, but Thursday’s quarter will still come down to trading, stablecoins and costs. If revenue lands well short of $1.3 billion, I’d expect estimates to fall again, and at 108x forward earnings the stock has little room for that.
Of course, one quarter won’t settle the cost question. The bigger test of whether the cuts hold is management’s 2027 expense outlook. This year’s outlook came with first-quarter results.
So what is Coinbase stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coinbase could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!