Key Takeaways
- Coinbase won final approval to run a national trust bank, joining Circle, and PNC launched a stablecoin payments pilot powered by Coinbase the same day.
- Third-quarter transaction revenue fell 44% to $590 million, while a $715 million crypto gain drove most of the $719 million net profit.
- Morgan Stanley cut Coinbase to underweight with a $120 target after roughly $165 million of fourth-quarter transaction revenue through October 25.
- The fourth-quarter report, expected in February, will test guidance of $550 million to $630 million in subscription and services revenue.
Coinbase Global (COIN) now has final approval from the Office of the Comptroller of the Currency to run a national trust bank. The charter took effect on November 6, and Coinbase announced it on Monday.
That puts it alongside Circle Internet Group (CRCL), the USDC issuer, which already holds a trust charter of its own. PNC Financial Services (PNC) launched a pilot the same day that lets corporate clients accept USDC payments, with Coinbase powering it.
Good news, then. Yet the stock had already lost about 22% in the month before Morgan Stanley downgraded it on November 2.
Trading revenue is the problem, and the charter does nothing to fix it quickly.
A charter lands mid-slump
The charter mainly moves custody under one federal regulator. Coinbase plans to shift its New York custody business into the new bank over three years. However, the bank can’t take ordinary deposits or make commercial loans.
Meanwhile, the October 29 report showed how hard trading has fallen:
- Total revenue fell 35% to $1.22 billion.
- Transaction revenue dropped 44% to $590 million as consumer spot volume fell 59%.
- Net income rose to $719 million, but $715 million of it came from gains on crypto Coinbase holds.
Put the two revenue engines side by side, and the shift is obvious.
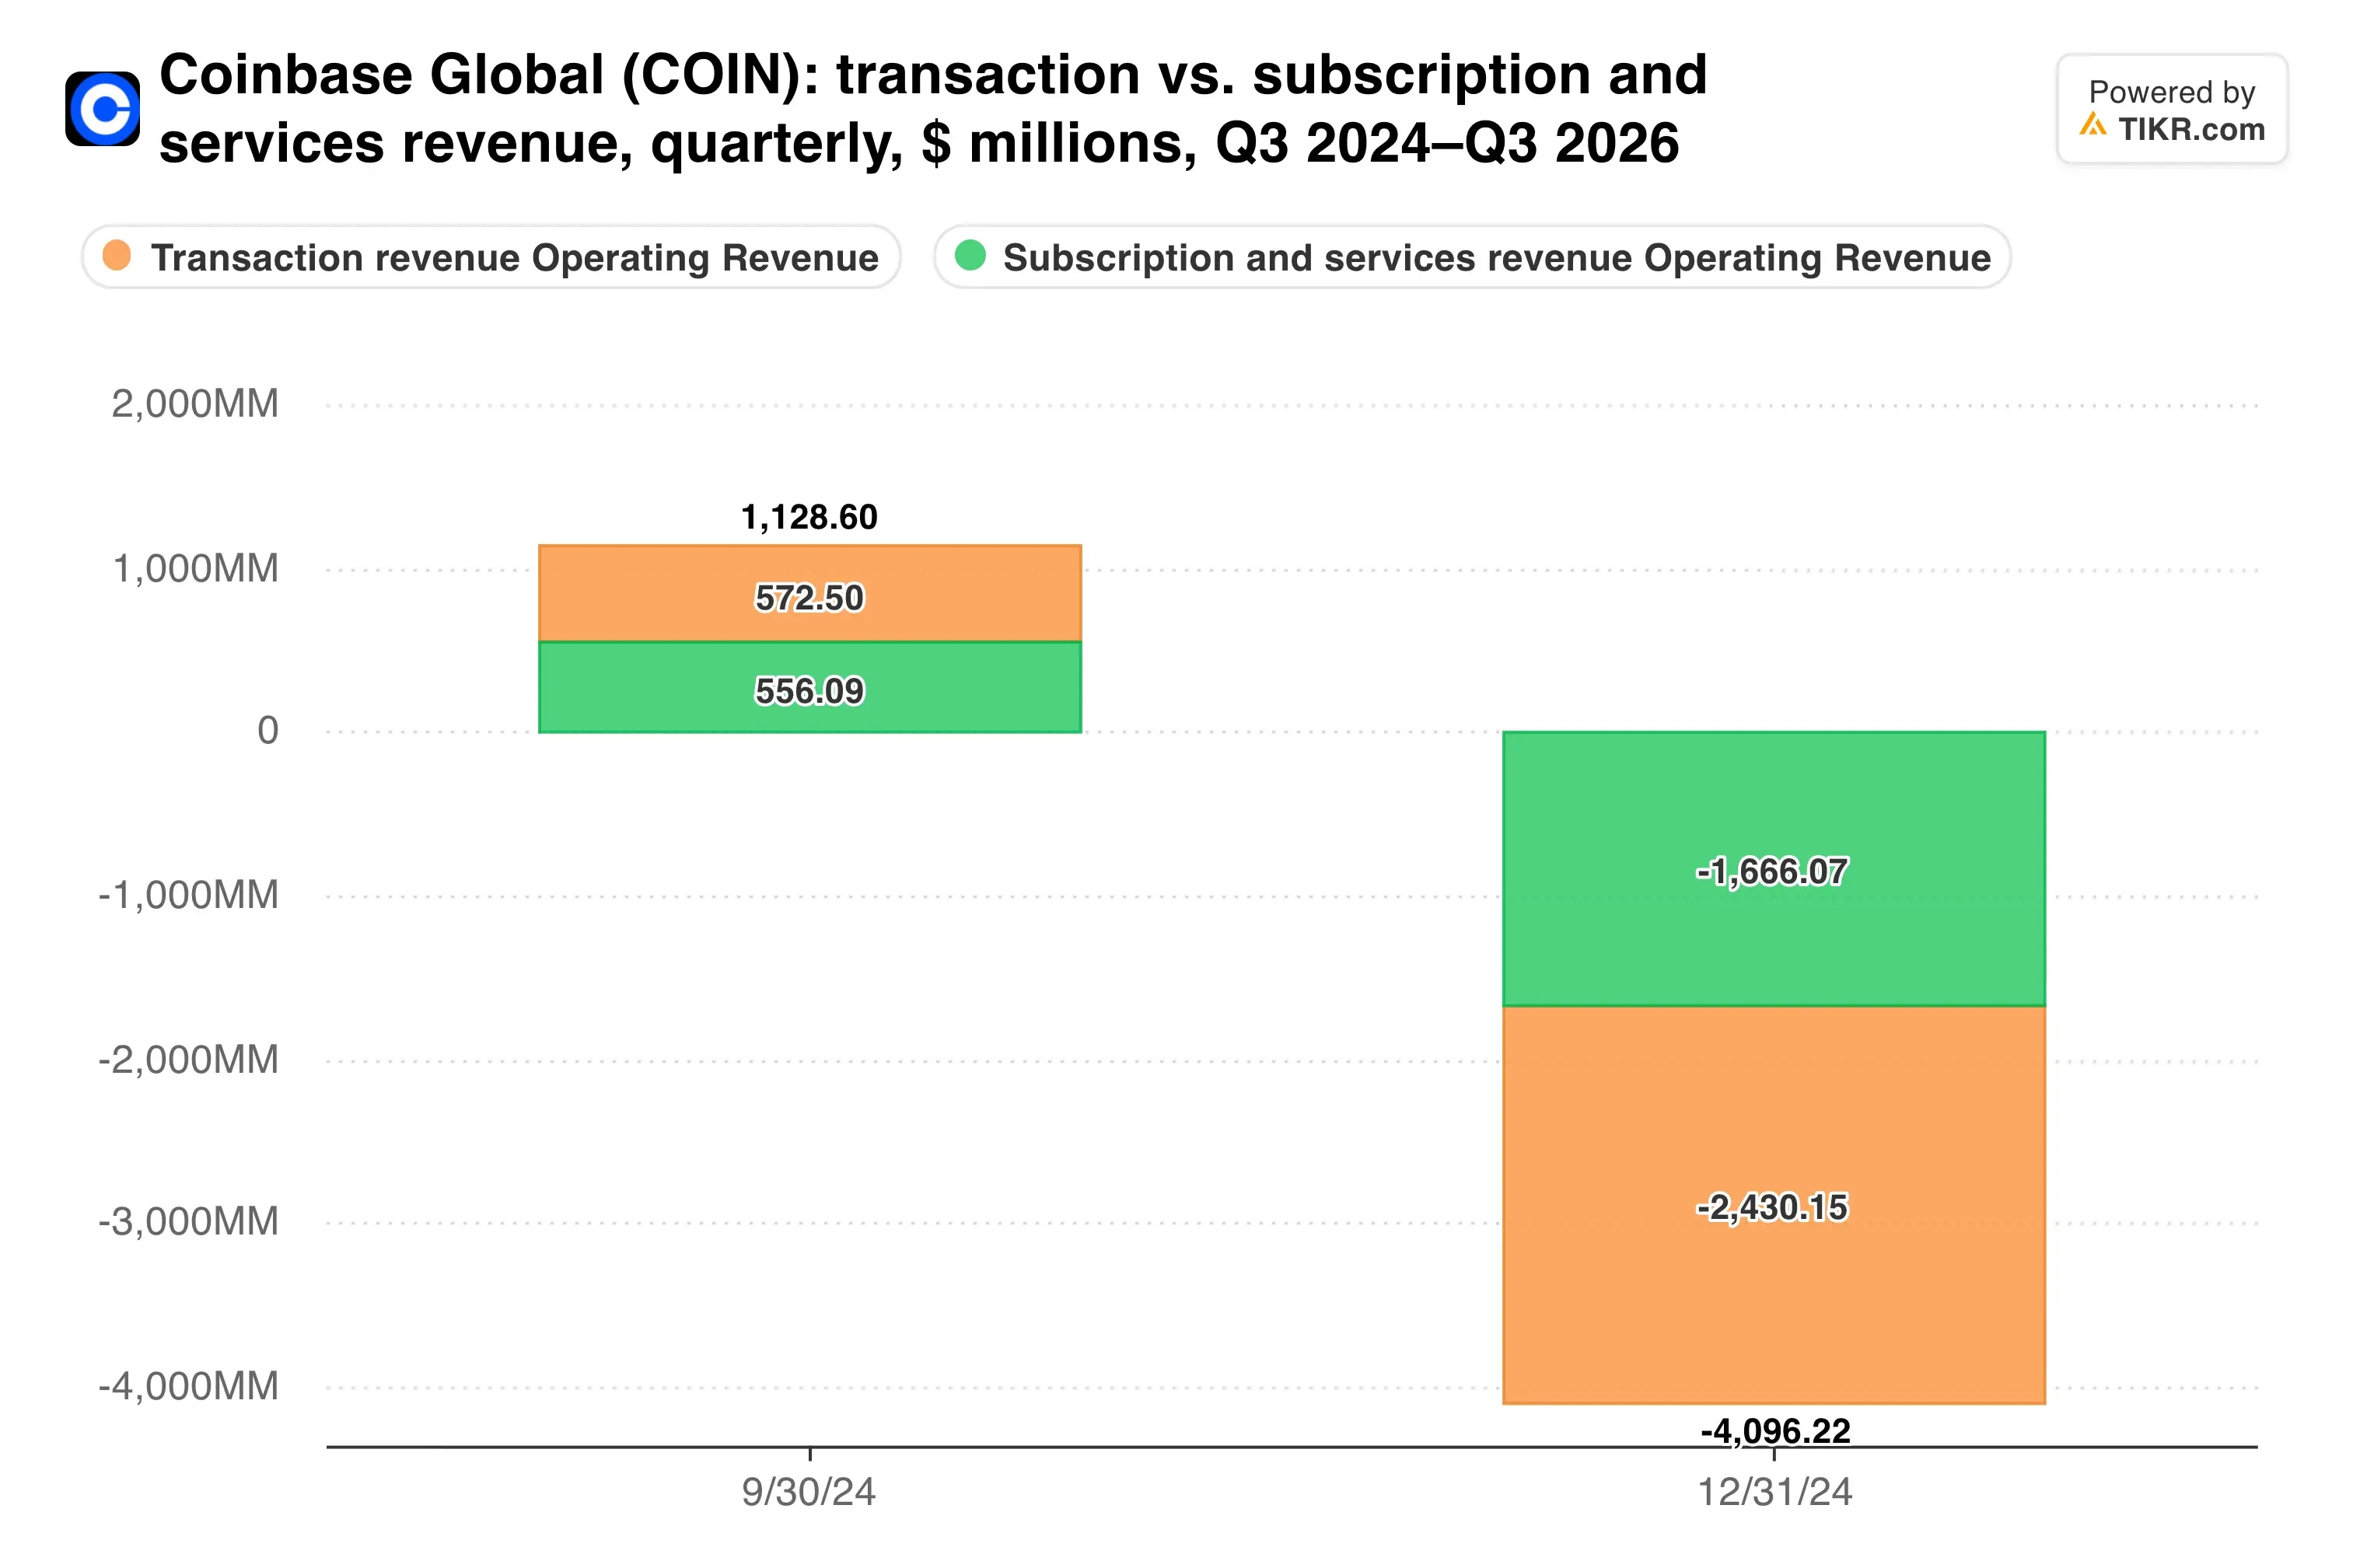
Subscription and services revenue reached $570 million, almost level with trading, so that half of the business now carries real weight.
Custody and stablecoins do the steadying
Stablecoin revenue came in at $307 million, down just 5% from a year earlier. Higher USDC balances added $85 million, while lower interest rates took away $53 million. Coinbase also renewed its USDC revenue arrangement with Circle on the same terms.
That is where a federal charter could matter most. Large institutions care about who regulates their custodian, especially since the roughly $6 billion Binance hack in late October.
For comparison, Coinbase held $376.6 billion of customer assets at the end of September. That figure was down 27% from a year earlier, mostly because bitcoin prices fell.
Can these steadier lines pull total revenue back up?
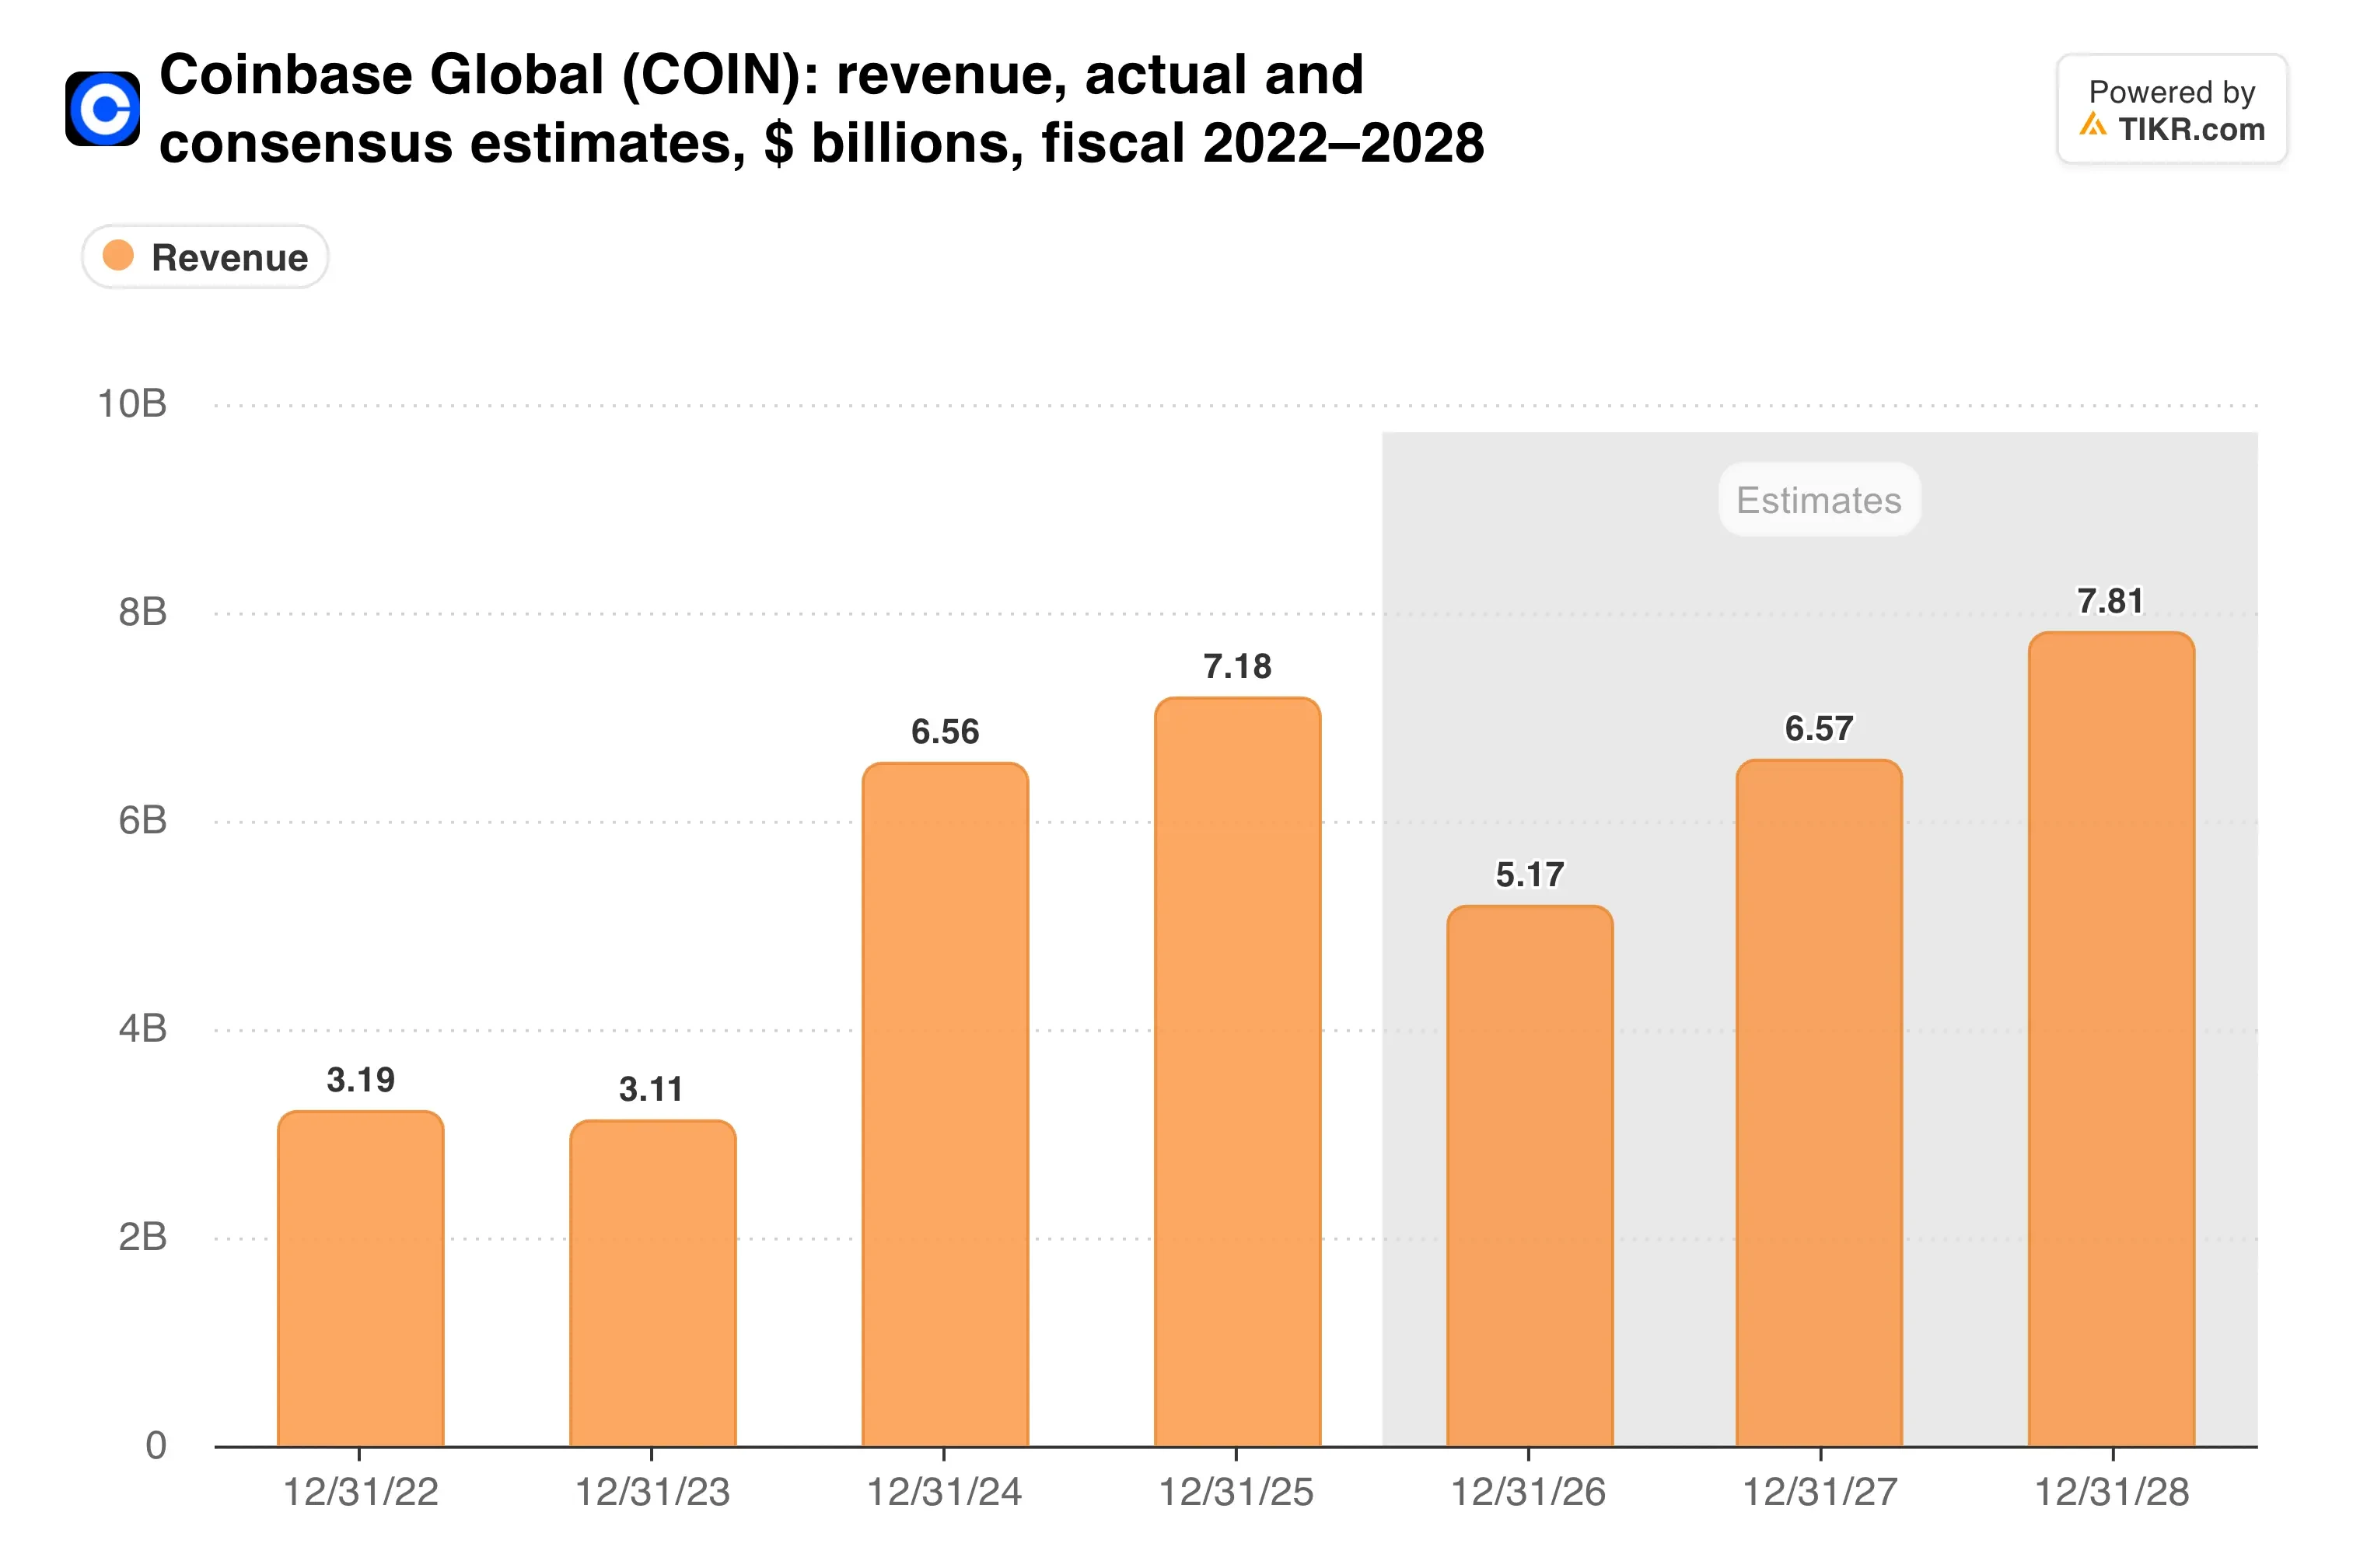
Analysts expect a recovery, but those forecasts still lean on crypto prices cooperating.
TIKR tracks 38 analysts on Coinbase. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Coinbase, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Coinbase’s Analyst Ratings
Trading still decides the profit
Operating income shows the strain. It fell to $61.7 million from $480.5 million a year earlier, even after a May restructuring cut about 700 jobs.
And the fourth quarter has started slowly. Coinbase booked roughly $165 million of transaction revenue through October 25, against $590 million for all of the third quarter. Morgan Stanley used that weak start to cut the stock to underweight, lowering its target to $120 from $258. The firm also flagged the Binance hack as a risk to crypto trading.
Here’s what thinner trading has done to margins…
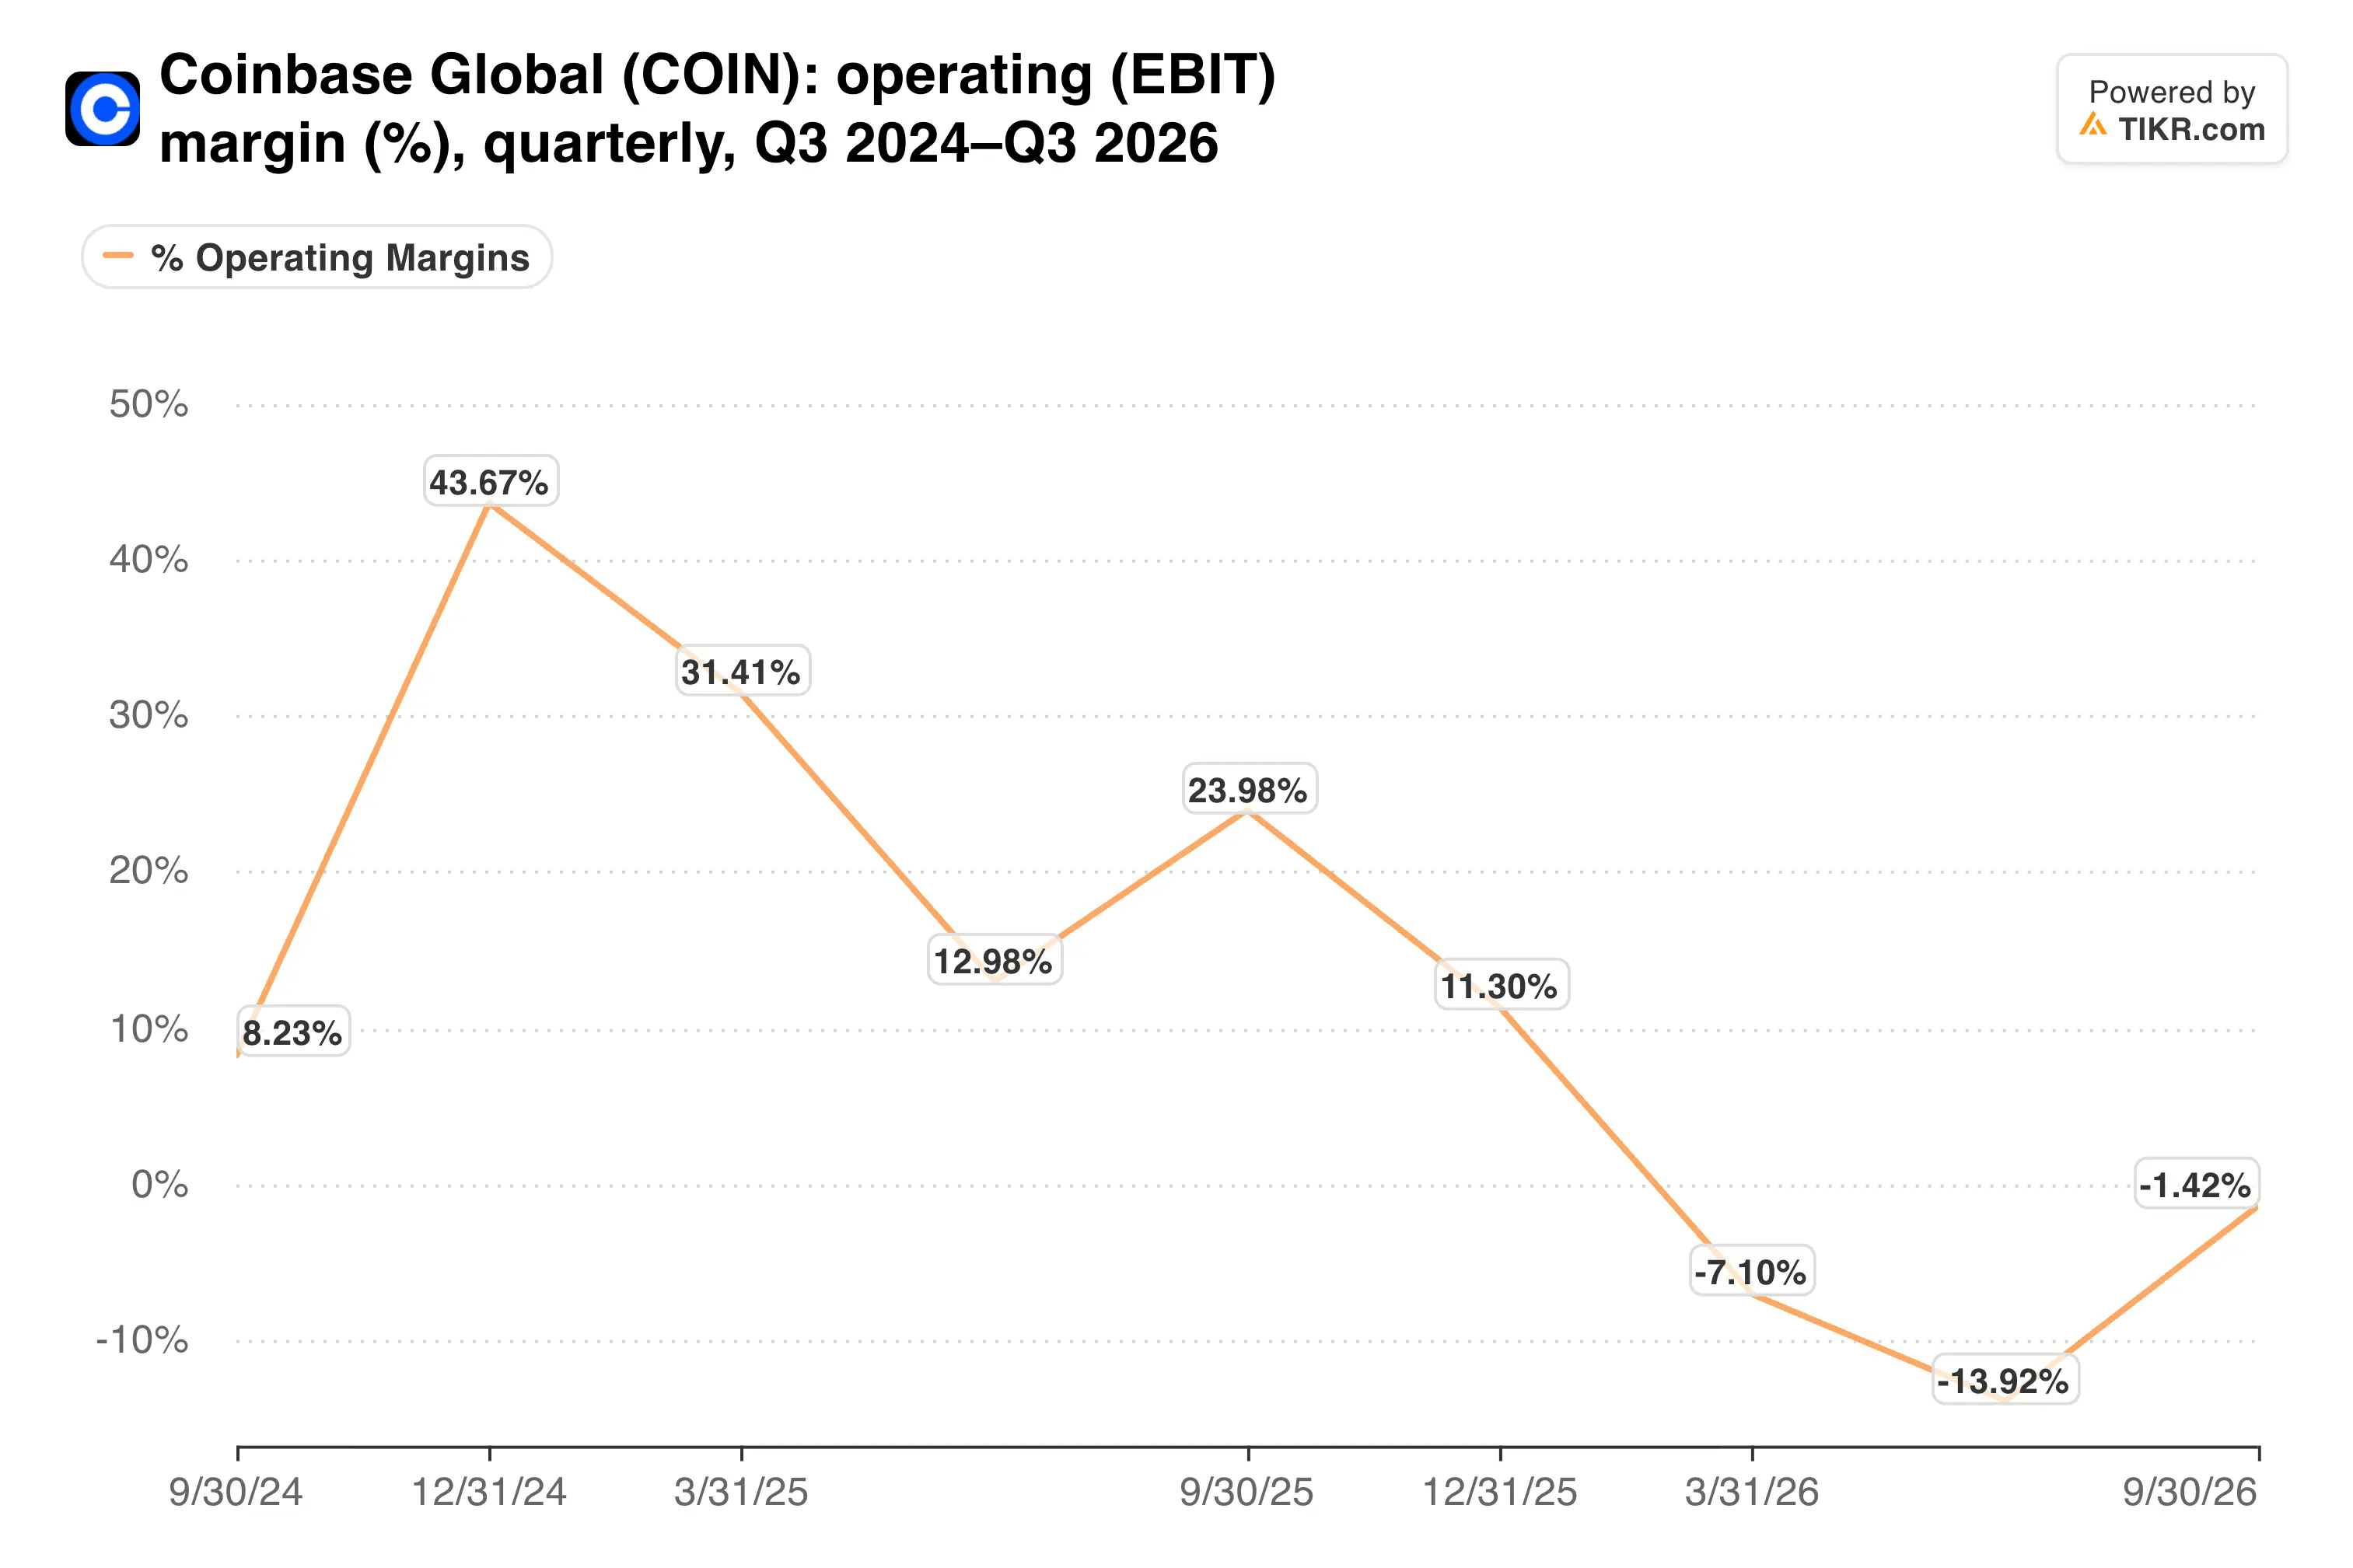
Costs came down about 17% from a year earlier, yet revenue fell faster.
Insider selling could add supply, too. Chief Executive Brian Armstrong’s trading plan allows sales of up to 8.2 million shares from November 16, if the stock clears preset price levels.
My take: The charter is a genuine long-term asset because it strengthens the half of Coinbase that doesn’t depend on trading. Still, I wouldn’t chase the stock on this news. Profits swing with crypto prices, and the fourth quarter is tracking well behind the third. I’d wait for proof that volumes have bottomed.
The fourth-quarter report, expected in February, is that proof point. It will show whether subscription and services revenue lands within the $550 million to $630 million guidance, and whether trading has stopped shrinking.
So what is Coinbase stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Coinbase could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!