


Key Takeaways
- Cisco raised its fiscal 2027 non-GAAP EPS outlook to $5.47 to $5.53, up from $5.05 to $5.11, yet the stock fell 6.24% to $95.64 on Friday.
- Cisco’s forward P/E has dropped to 17.2x from 27.7x at its June peak, but it still sits about 10% above its five-year average of 15.7x.
- The guide implies a second-half non-GAAP operating margin of about 35%, against 37.8% in the first quarter, as hardware mix and memory costs weigh on gross margin.
- Analysts expect EPS growth to slow from about 27% this year to about 9% in fiscal 2028, and Cisco’s February 10, 2027 report is the next test.
Cisco Systems (CSCO) stock fell 6.24% to $95.64 on Friday, a day after the networking giant reported record quarterly revenue and raised its fiscal 2027 earnings outlook by about 8%. The drop erased roughly $25 billion of market value, against the roughly $1.7 billion of annual non-GAAP profit that the higher EPS guide implies.
Investors didn’t dispute the earnings. They cut what they’ll pay for them. Cisco now trades at 17.2x forward earnings, down from 27.7x at its June peak, and the company’s own guidance shows why.
Cisco Beat the Quarter and Raised the Year
Fiscal first-quarter revenue rose 24% to $18.5 billion, and non-GAAP EPS jumped 40% to $1.40, ahead of the $1.33 consensus estimate. On the Q1 2027 earnings call, CEO Chuck Robbins called them Cisco’s “strongest top and bottom line growth rates in over 15 years.”
The full-year outlook moved up across the board:
- Revenue of $74.8 billion to $75.8 billion, about 19% growth.
- Non-GAAP EPS of $5.47 to $5.53, up from $5.05 to $5.11 (and above FactSet’s $5.10 consensus, per CNBC).
- Hyperscaler AI revenue of $9 billion, up from $7.5 billion, or about 12% of sales (from 6% in fiscal 2026).
Cisco’s Estimates Went Up. Its Multiple Went Down.
Analysts have already moved to the new guide. Consensus EPS sits at $5.50 for fiscal 2027, $6.01 for 2028, and $6.51 for 2029.
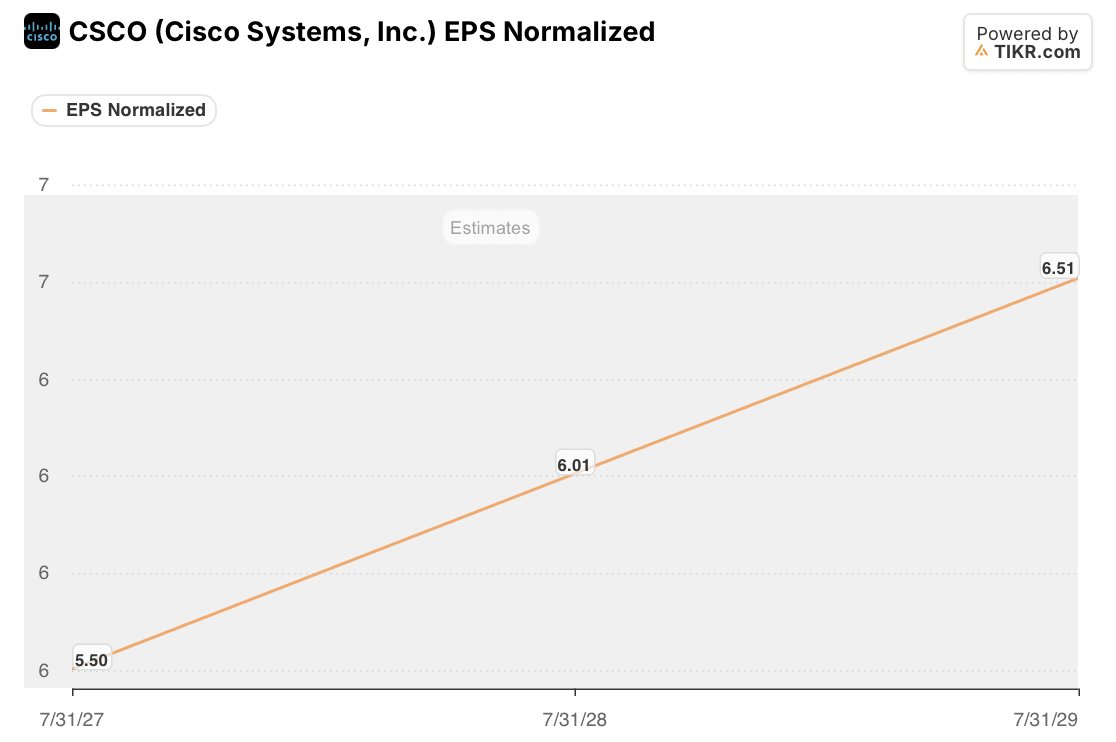
EPS grows about 27% this year, then about 9% and 8%. Buyers paying 27.7x in June were paying for far more than 9% growth.
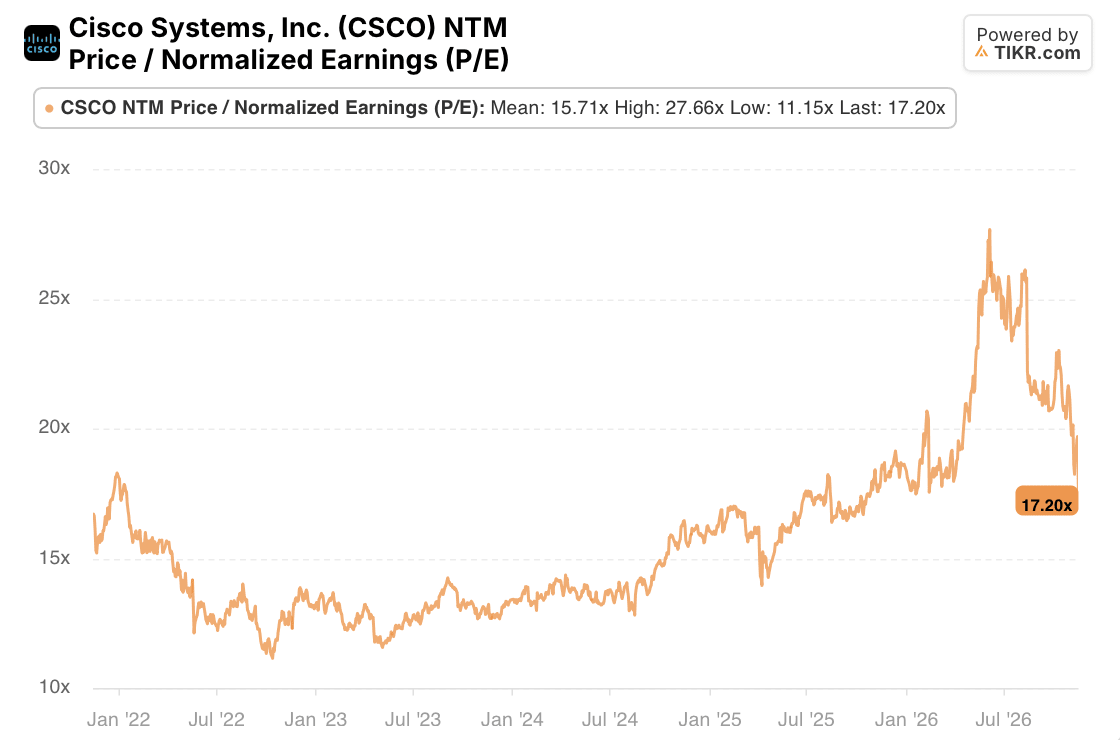
Cisco traded at about 21.8x forward earnings in late August. It’s now at 17.2x, about 10% above its five-year average of 15.7x. The selloff didn’t make Cisco cheap. It repriced Cisco closer to the high-single-digit earnings grower the Street now models.
TIKR Tracks 28 Analysts on Cisco. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cisco, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cisco’s Analyst Ratings
Why Cisco’s Guide Didn’t Earn a Higher Multiple
The doubt sits in the back half. Second-quarter revenue guidance of $18.0 billion to $18.2 billion is below the $18.5 billion Cisco just reported. To hit the full-year midpoint, second-half revenue has to average about $19.3 billion a quarter, 4.5% above the first quarter, while second-half EPS averages about $1.38, below the first quarter’s $1.40. More revenue, less profit per dollar of it. The full-year guide implies a non-GAAP operating margin of about 35% in the second half, against 37.8% in the first quarter, as hardware mix and memory costs pressure gross margin, already down 2.5 points to 65.6%. The full-year margin still rises to 36% from 34.8%.
CFO Mark Patterson said the second half carries “tougher compares and a little bit less visibility.” Cisco also stopped reporting hyperscaler AI orders, moving “to the revenue side so that it’s just cleaner,” Robbins said. Barclays’ Tim Long estimated those orders were “likely down meaningfully Q/Q.” Cisco estimates price increases add about 5 percentage points to this year’s revenue growth, and Morgan Stanley warned on November 5 that early ordering ahead of those increases could weaken later demand.
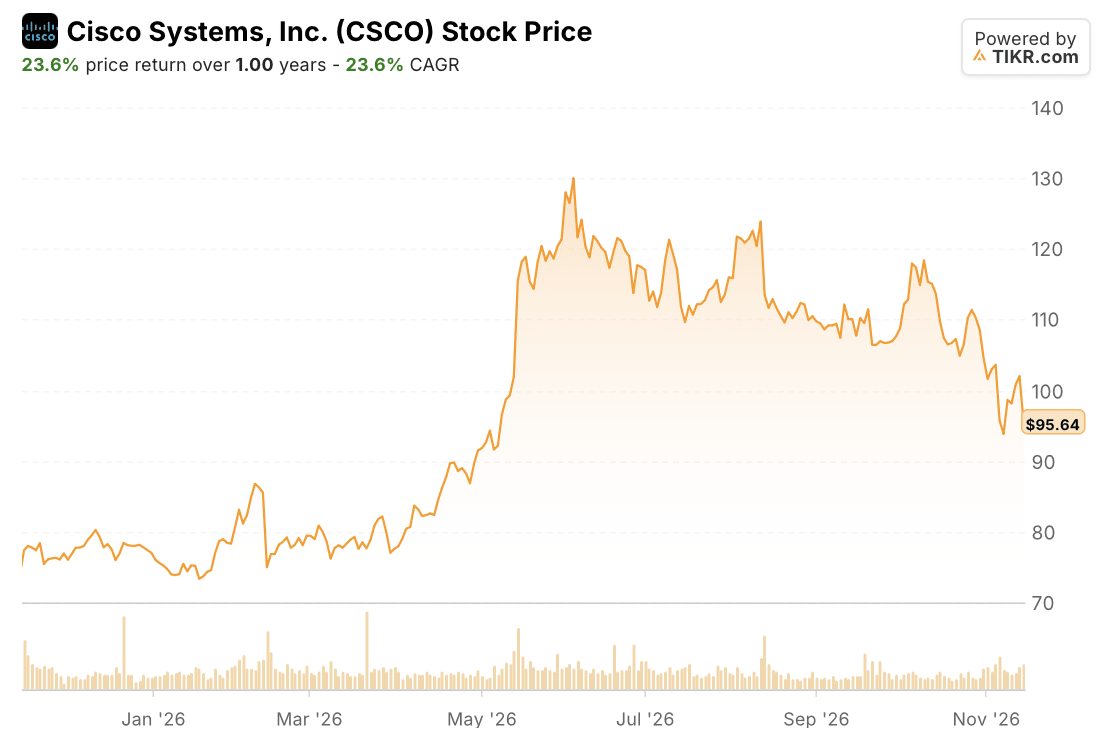
That makes Friday the third post-earnings drop in four reports, after roughly 13% in February and 9% in August.
Conclusion
Nothing in the quarter says demand is cracking: product orders grew 21%, and 14% outside the hyperscalers. But the selloff stripped out most of Cisco’s premium. If the multiple holds near 17.2x, gains from $95.64 should roughly track the 8% to 9% annual EPS growth analysts expect for fiscal 2028 and 2029, plus a 1.8% dividend yield. A re-rating needs proof that the hyperscale revenue arrives without more margin loss. The first check comes on February 10, 2027, when Cisco has to land near $18.1 billion in revenue with gross margin inside 65% to 66%.
So What Is Cisco Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what CSCO stock could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Cisco Systems, Inc. for free→
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





