Key Takeaways
- Cipher Digital rose 4% after Morgan Stanley cut its price target to $27.50 from $51.50 but kept its Overweight rating.
- Riot Platforms, CleanSpark, TeraWulf and Core Scientific also rose as Morgan Stanley called powered shell stocks a buying opportunity.
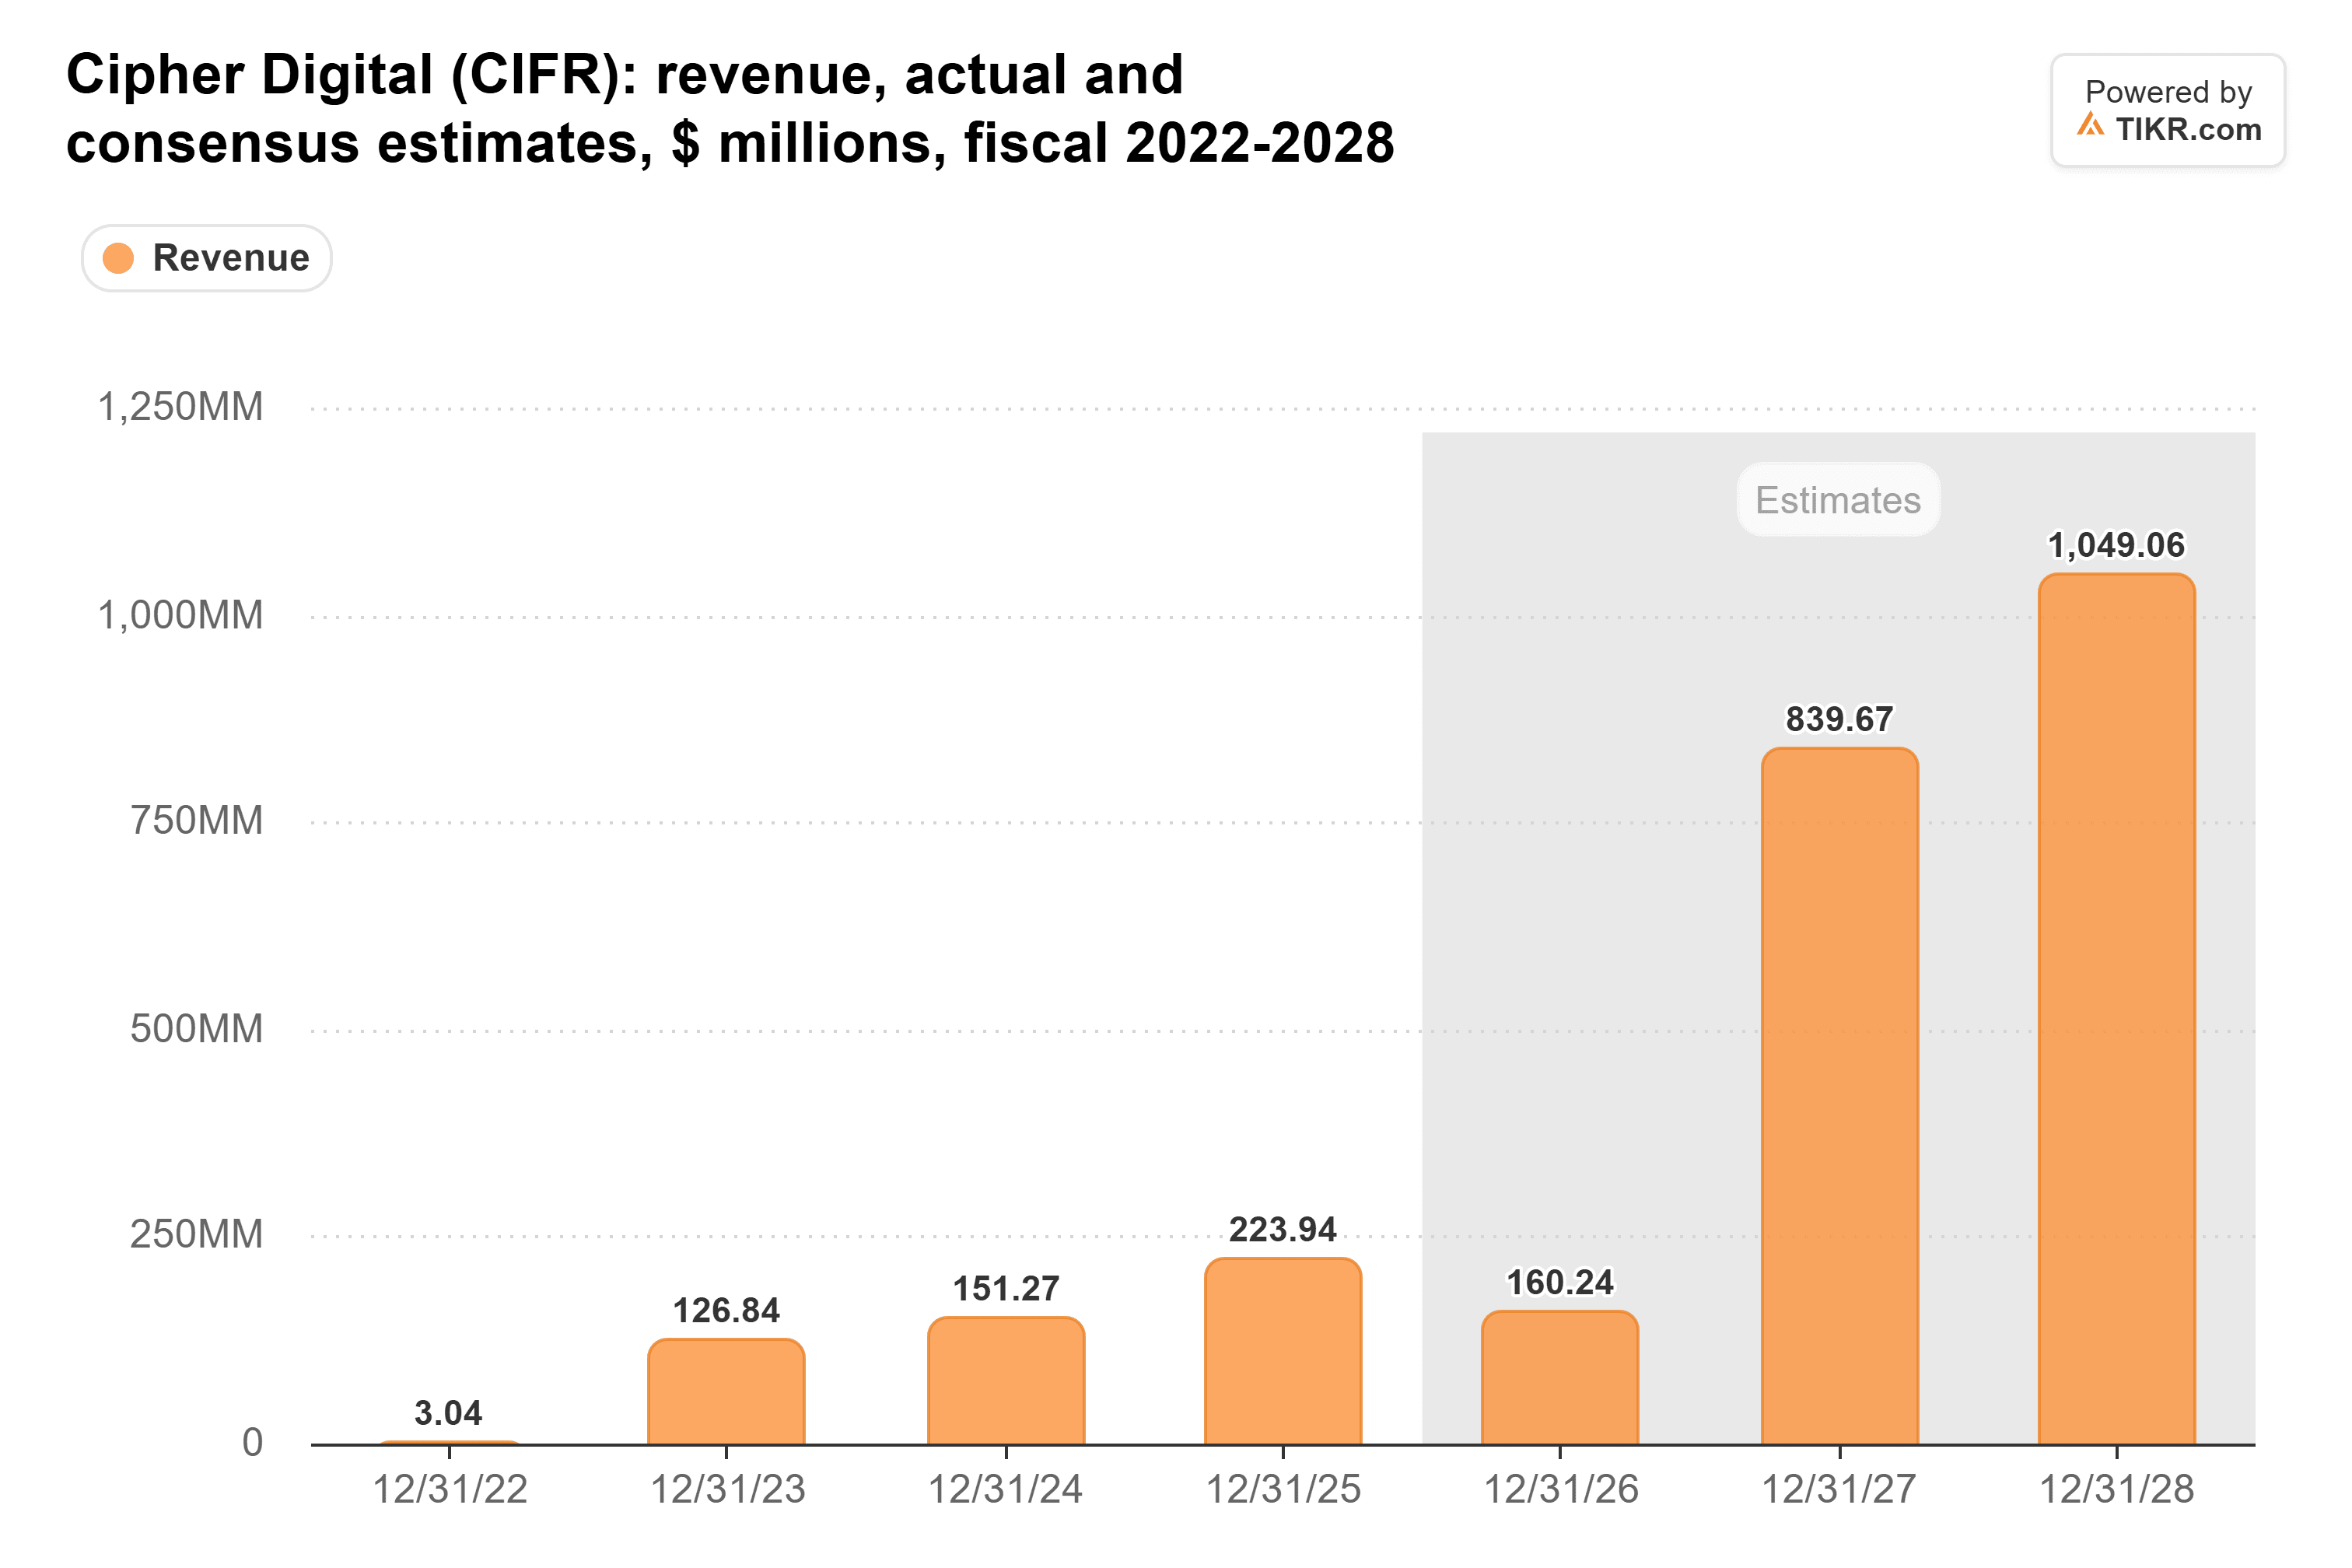
- Analysts expect Cipher’s revenue to jump more than fivefold in 2027 as its leases start paying.
- Cipher pays for more of its builds than Riot, so watch how it funds its next lease.
Cipher Digital (CIFR) is up 4% today, even though Morgan Stanley’s Stephen Byrd nearly halved his price target before the open, to $27.50 from $51.50, keeping his Overweight rating. Late this morning, the bank called Riot Platforms (RIOT) and other powered shell providers a buying opportunity.
Morgan Stanley also raised its Riot target to $41 from $35.50, and Riot is up 6%. CleanSpark (CLSK) is up 12%. TeraWulf (WULF) and Core Scientific (CORZ) are up 9% and 8% in a broad market rally.
TIKR tracks 22 analysts on Cipher Digital. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Cipher Digital, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Cipher Digital’s Analyst Ratings
Even the lower target is a big call
Morgan Stanley’s $27.50 is still about four times where Cipher closed on Friday. The bank is betting on rent. Analysts expect its revenue to fall to $160 million this year as mining shrinks, then jump to $840 million in 2027:
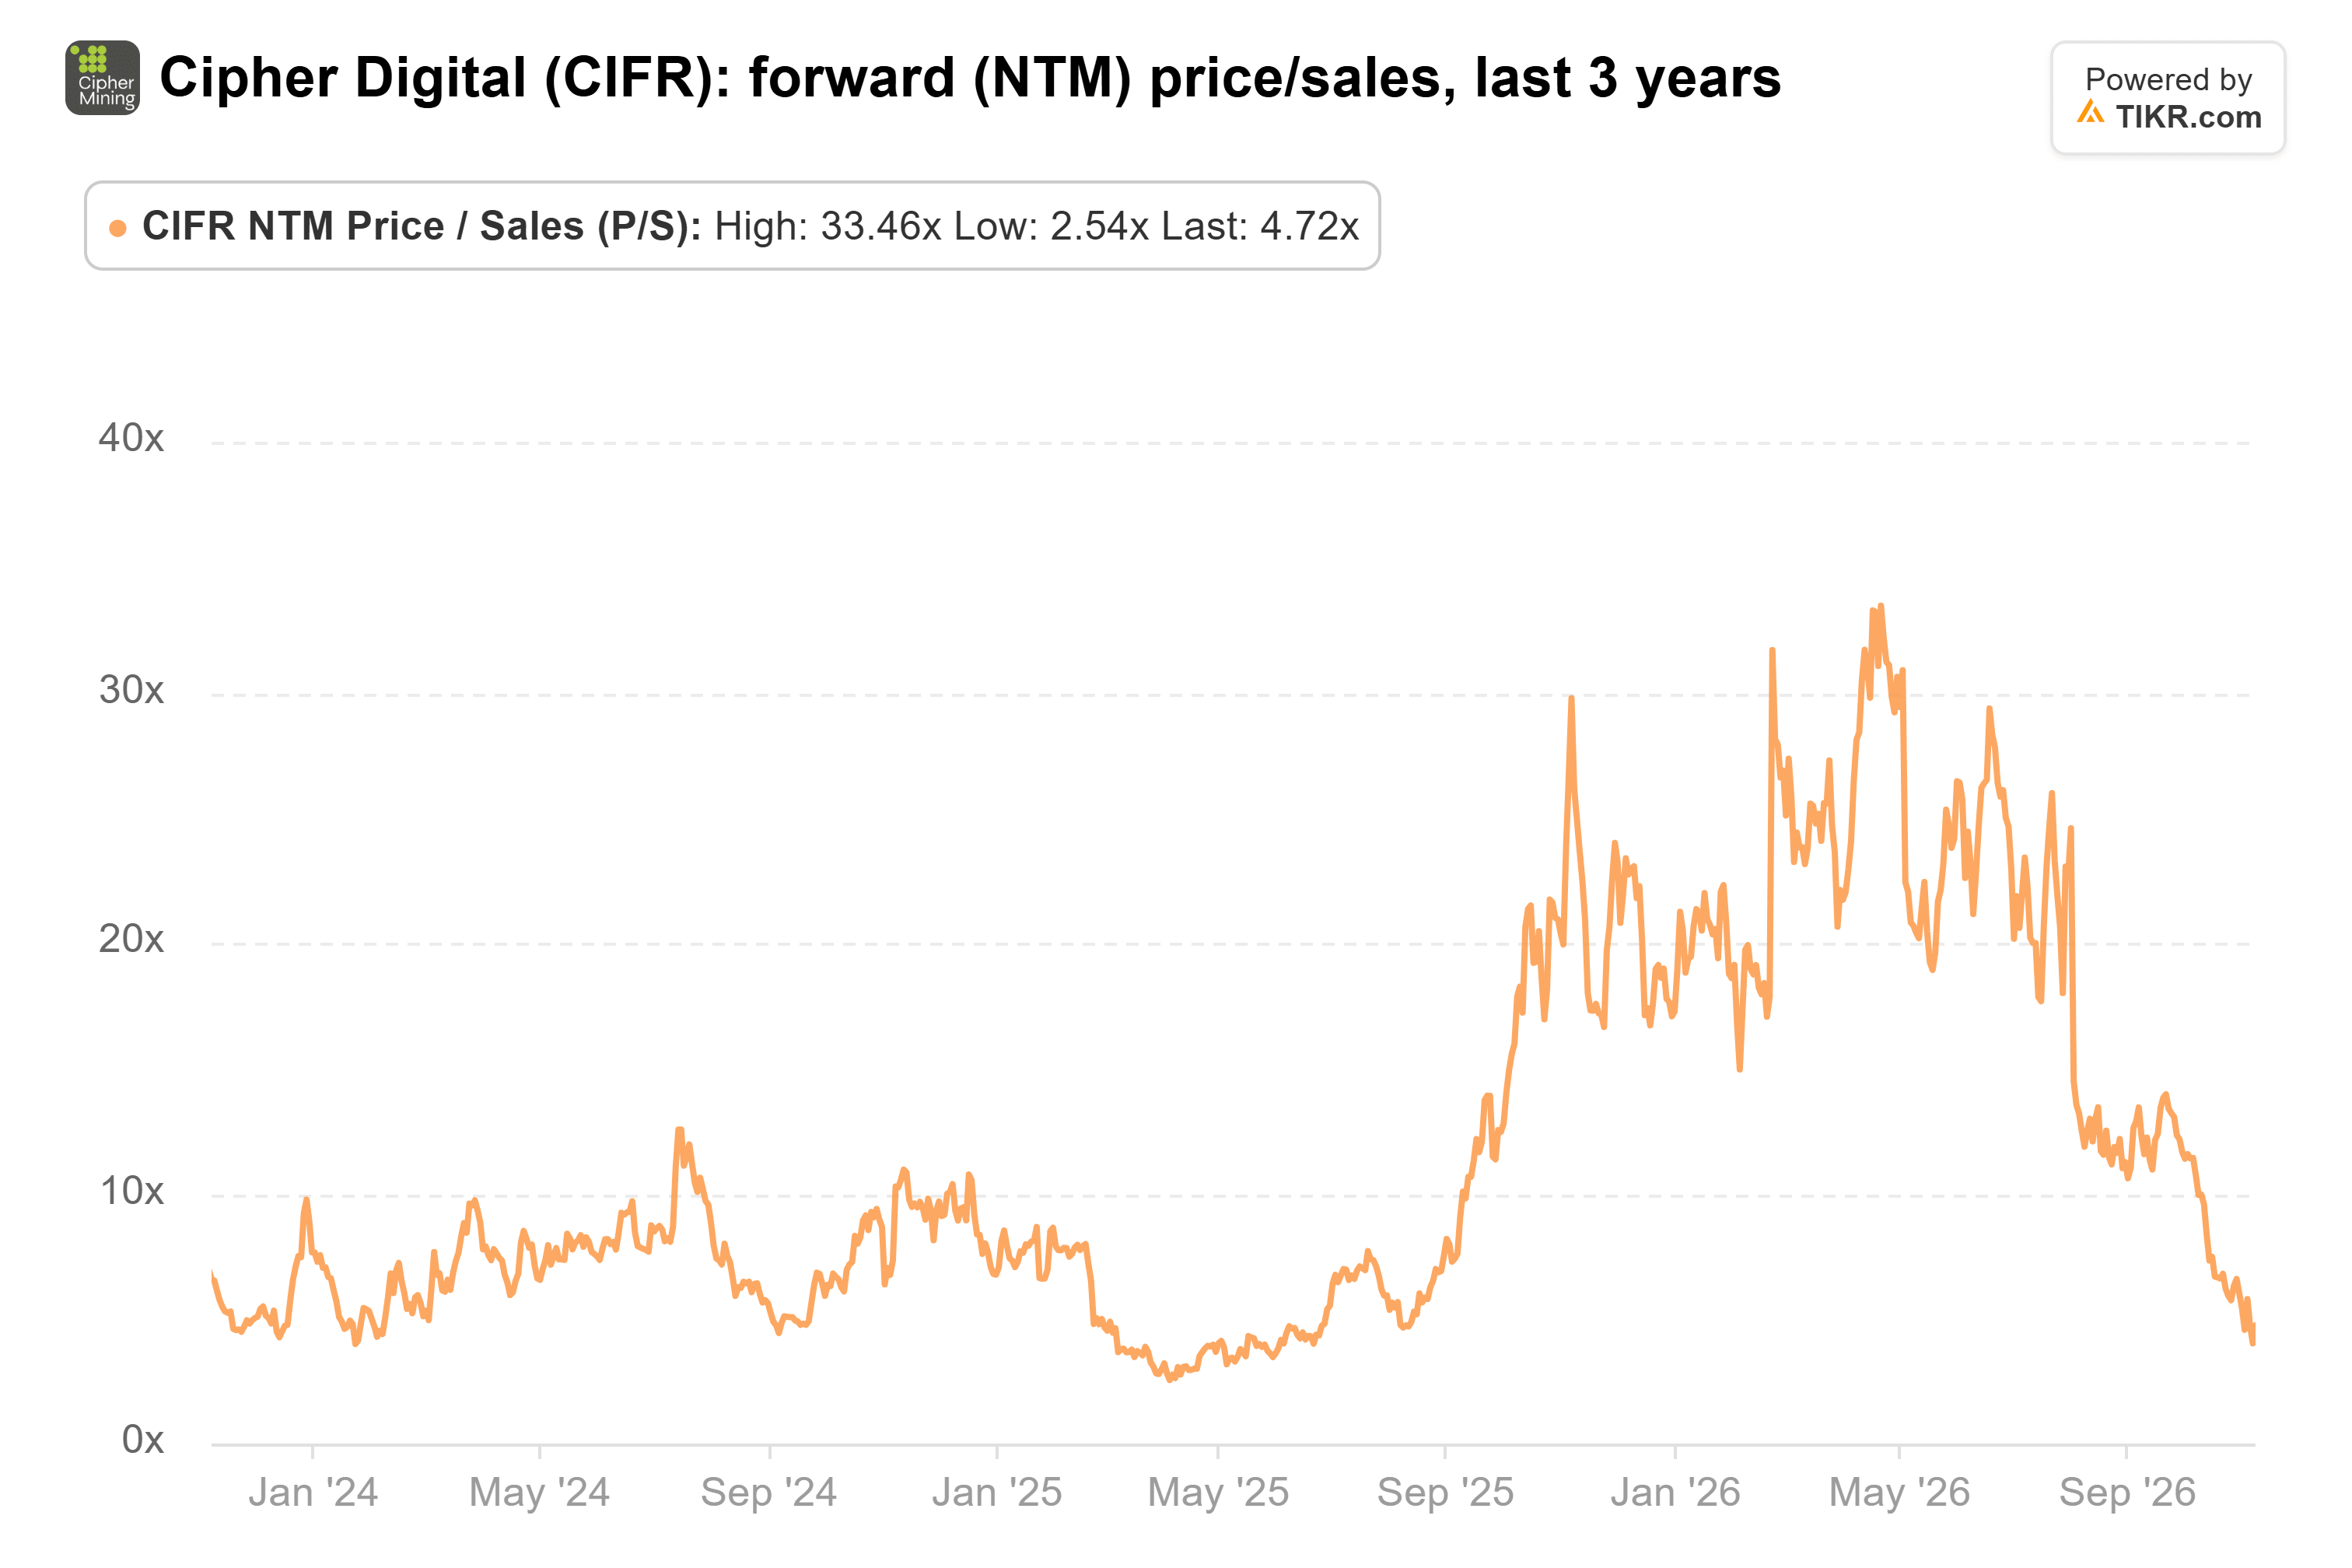
Investors aren’t paying for that yet. Cipher traded at 4.7x forward sales at Friday’s close, against a 3-year average of 11.4x:
Riot’s tenant pays for more of the build
On Nov. 4, Riot leased its whole 910-megawatt Corsicana campus to a frontier AI lab for about $28 billion over 15 years.
My read: Morgan Stanley split its calls based on who pays for the build. Riot puts Corsicana’s cost at about $6 million per IT megawatt, pays only $2 million of that up front, and doesn’t expect to sell stock. Cipher puts its builds at $9 million to $11 million per critical IT megawatt. In October, Cipher sold $850 million of convertible notes to fund more of Barber Lake.
Cipher’s peers are on either side of it. CleanSpark has signed a 20-year, $6.6 billion lease at Sandersville, but mining still brings in its revenue. At TeraWulf, lease revenue was 83% of third-quarter revenue. Core Scientific’s colocation revenue hit $215.4 million in the quarter, about what Cipher’s 2027 estimate works out to per quarter.
I’d wait for Cipher’s next lease
For Morgan Stanley’s target to work, Barber Lake’s tenant has to start paying rent, and Cipher has to fund its next builds without selling much more stock at these prices. I’d wait to see both before buying the bounce. A fourth lease funded mostly with project debt would change my mind fast.
So what is Cipher Digital stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Cipher Digital could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!