Key Takeaways
- Chevron and Southern Company yield 3.4% and 3.3%, but Chevron’s dividend has grown nearly twice as fast over the past five years.
- Chevron’s dividend took 41% of its free cash flow over the twelve months to September, and the company carries very little net debt.
- Southern Company’s dividend took 68% of its 2025 earnings, and data center demand just lifted its 2026 guidance, but it relies on new debt and stock to fund its growth.
- Chevron’s reported deal for Beacon Offshore Energy and Southern Company’s February update to its outlook are the next things to watch.
Anyone buying a dividend stock to hold for 20 years needs a check that keeps growing through recessions, price crashes and rate hikes. Chevron (CVX) and Southern Company (SO) both just turned in quarters that make the case for theirs.
Chevron’s free cash flow came to $12.0 billion in the third quarter of 2026, up from $4.9 billion a year earlier. Southern raised its 2026 adjusted EPS guidance to $4.70 on Nov. 5, with data center usage on its system 59% higher in the quarter.
With yields of 3.4% and 3.3%, the two pay about the same today. So which one would I hold for the next two decades?
| Metric | Chevron (CVX) | Southern Company (SO) |
|---|---|---|
| Dividend yield | 3.4% | 3.3% |
| Annual dividend | $7.12 | $3.04 |
| Dividend growth, fiscal 2020-2025 | 5.8% a year | 3.0% a year |
| Consecutive years of dividend raises | 39 | 25 |
| Coverage | Cash dividend payout ratio: 41% (TTM to Sept. 30, 2026) | Payout ratio of normalized EPS: 68.4% (fiscal 2025) |
| Net debt/EBITDA (LTM) | 0.4x | 4.9x |
| Interest coverage (LTM) | 25.1x | 2.6x |
Source: TIKR and StockAnalysis; raise records from each company’s third-quarter call.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
Chevron puts the dividend first
Chevron’s U.S. refineries ran a record 1.09 million barrels of crude a day in the third quarter. The company paid $13.92 billion of dividends over the twelve months to Sept. 30, 2026. That’s a well-covered 41% of its $34.07 billion of free cash flow, down from a heavier 76.9% in fiscal 2025.
Its free cash flow swings with oil and gas prices, and it fell short of the dividend in fiscal 2016, 2017 and 2020.
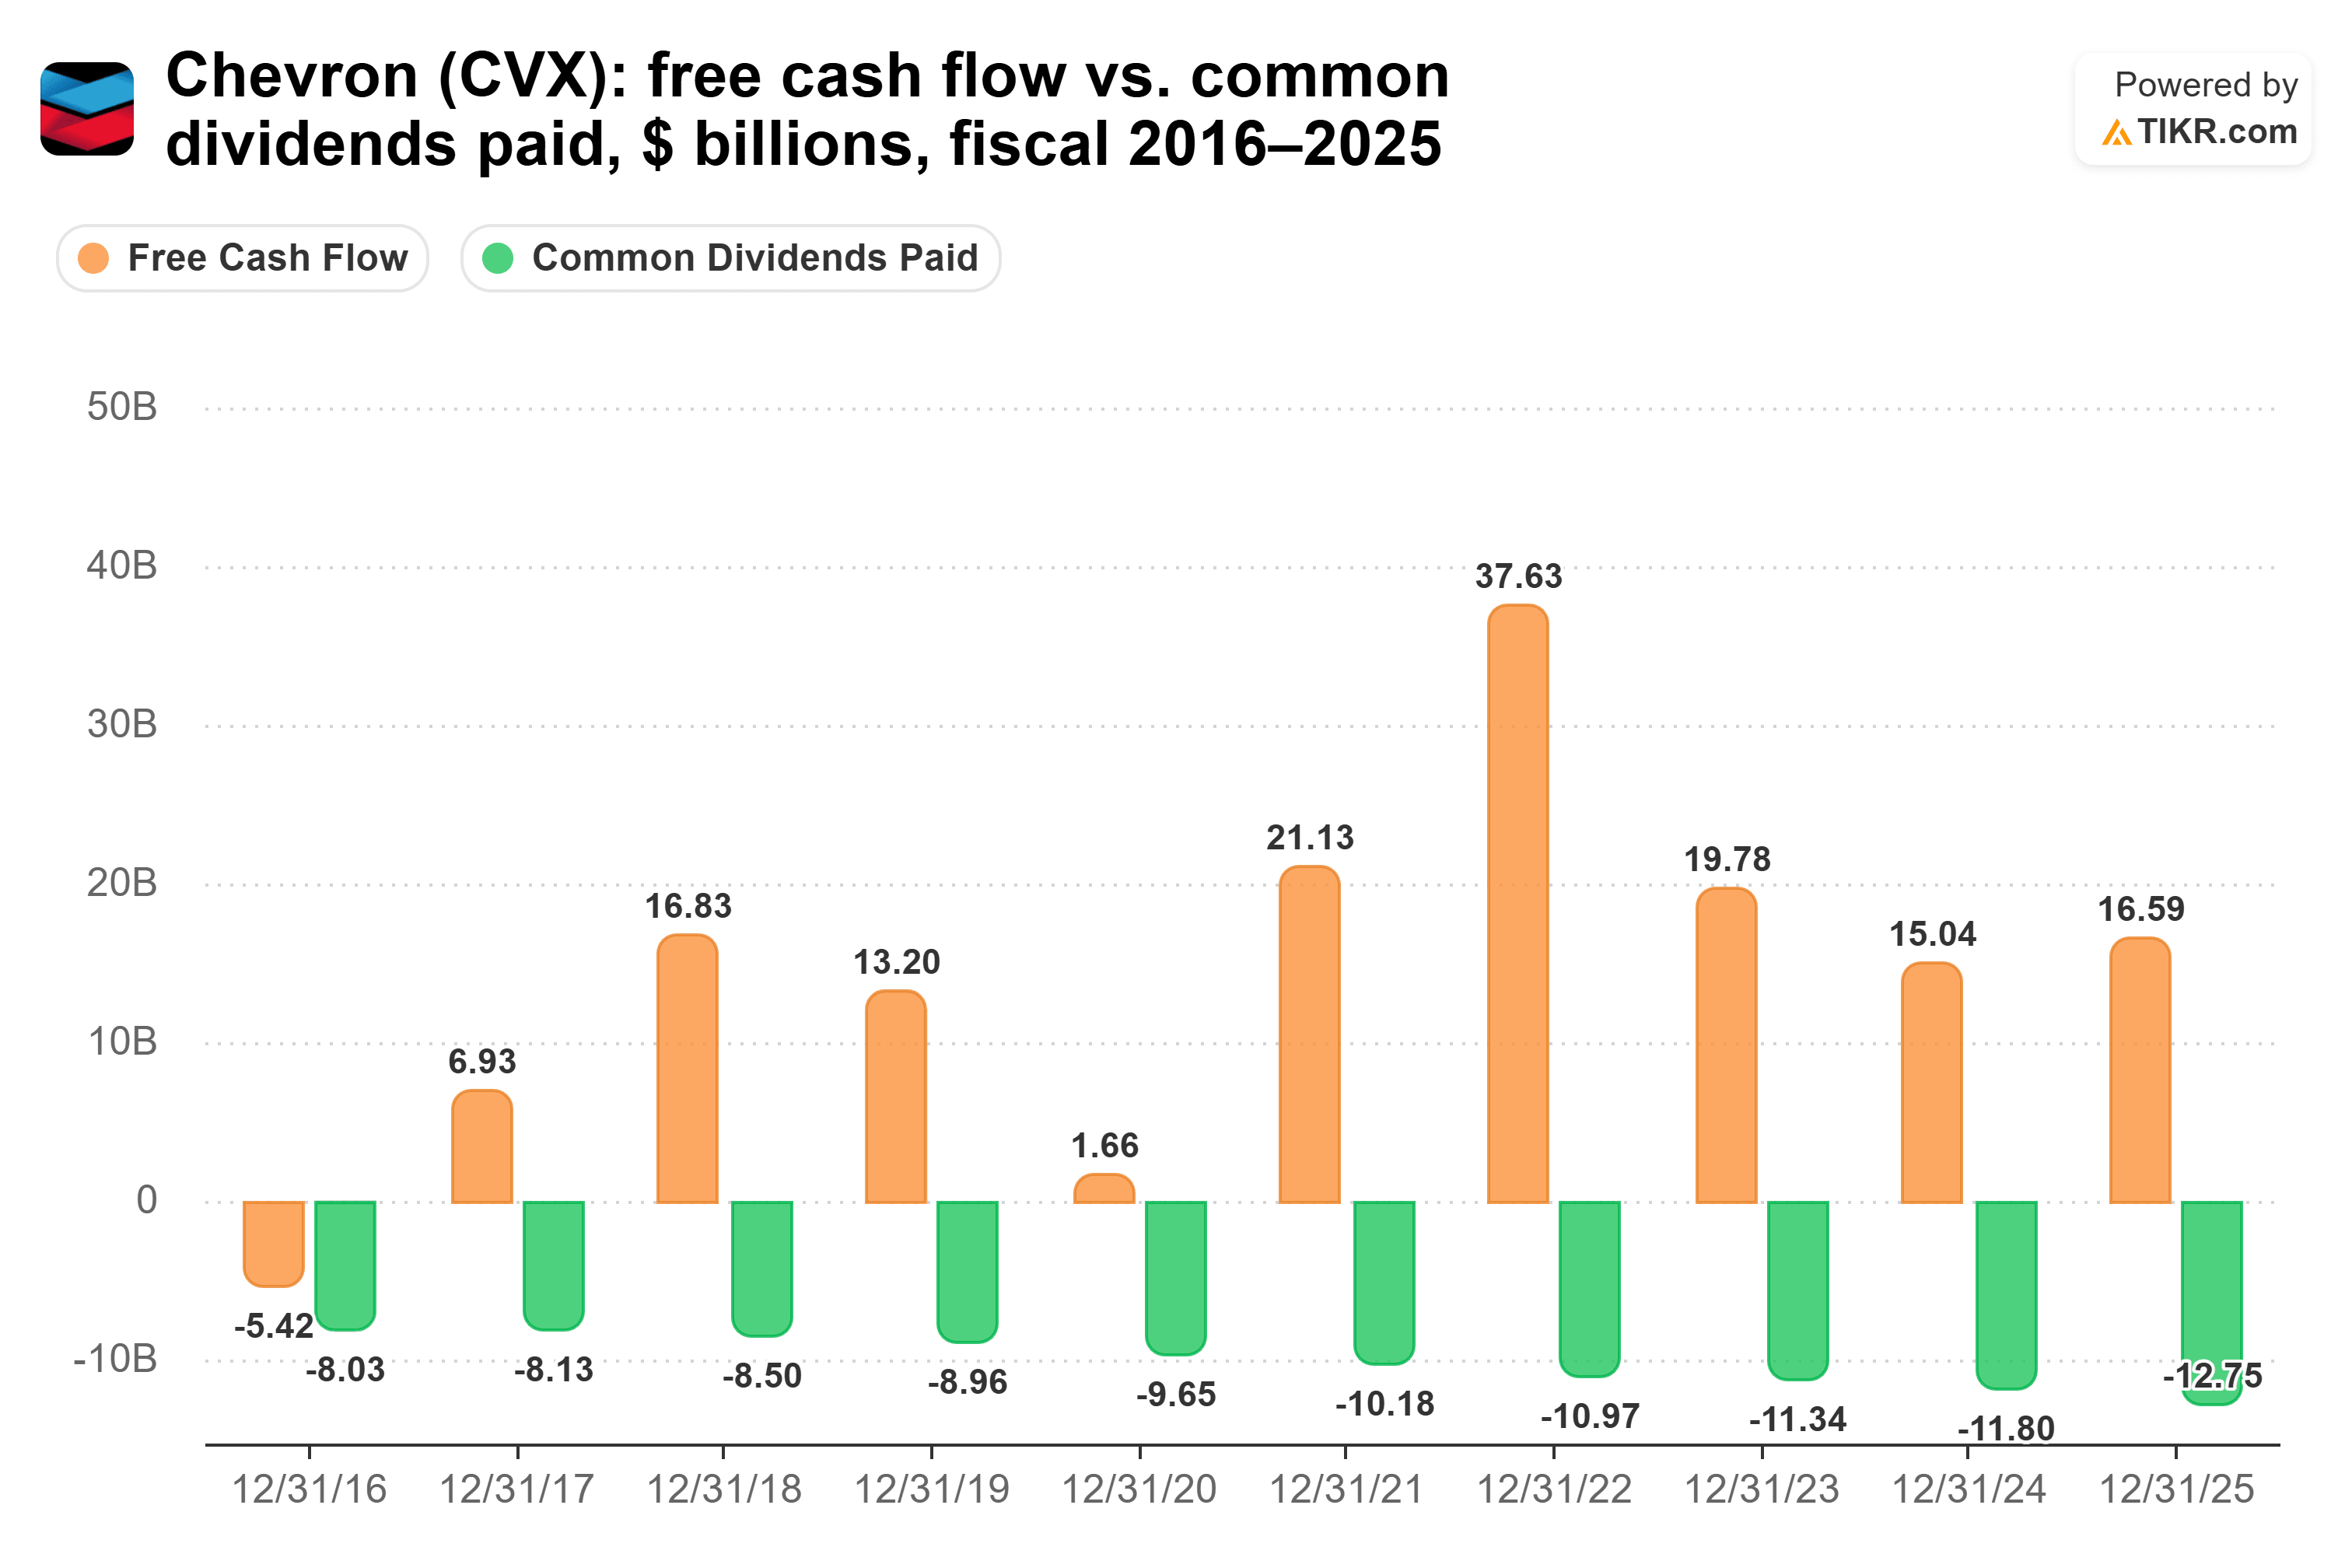
Dividends paid still rose every year, from $8.03 billion in fiscal 2016 to $12.8 billion in fiscal 2025. When CFO Eimear Bonner laid out Chevron’s capital priorities on the third-quarter call, she said “the first priority within that is to grow the dividend consistently.” Chevron has raised its dividend for 39 consecutive years. Oil prices are the main risk to watch.
Southern pays for its growth with debt and new stock
Chevron’s cash swings with commodity prices, but Southern’s earnings have climbed every year for a decade. Its normalized EPS rose from $2.89 a share in fiscal 2016 to $4.30 in fiscal 2025, faster than its dividend grew.
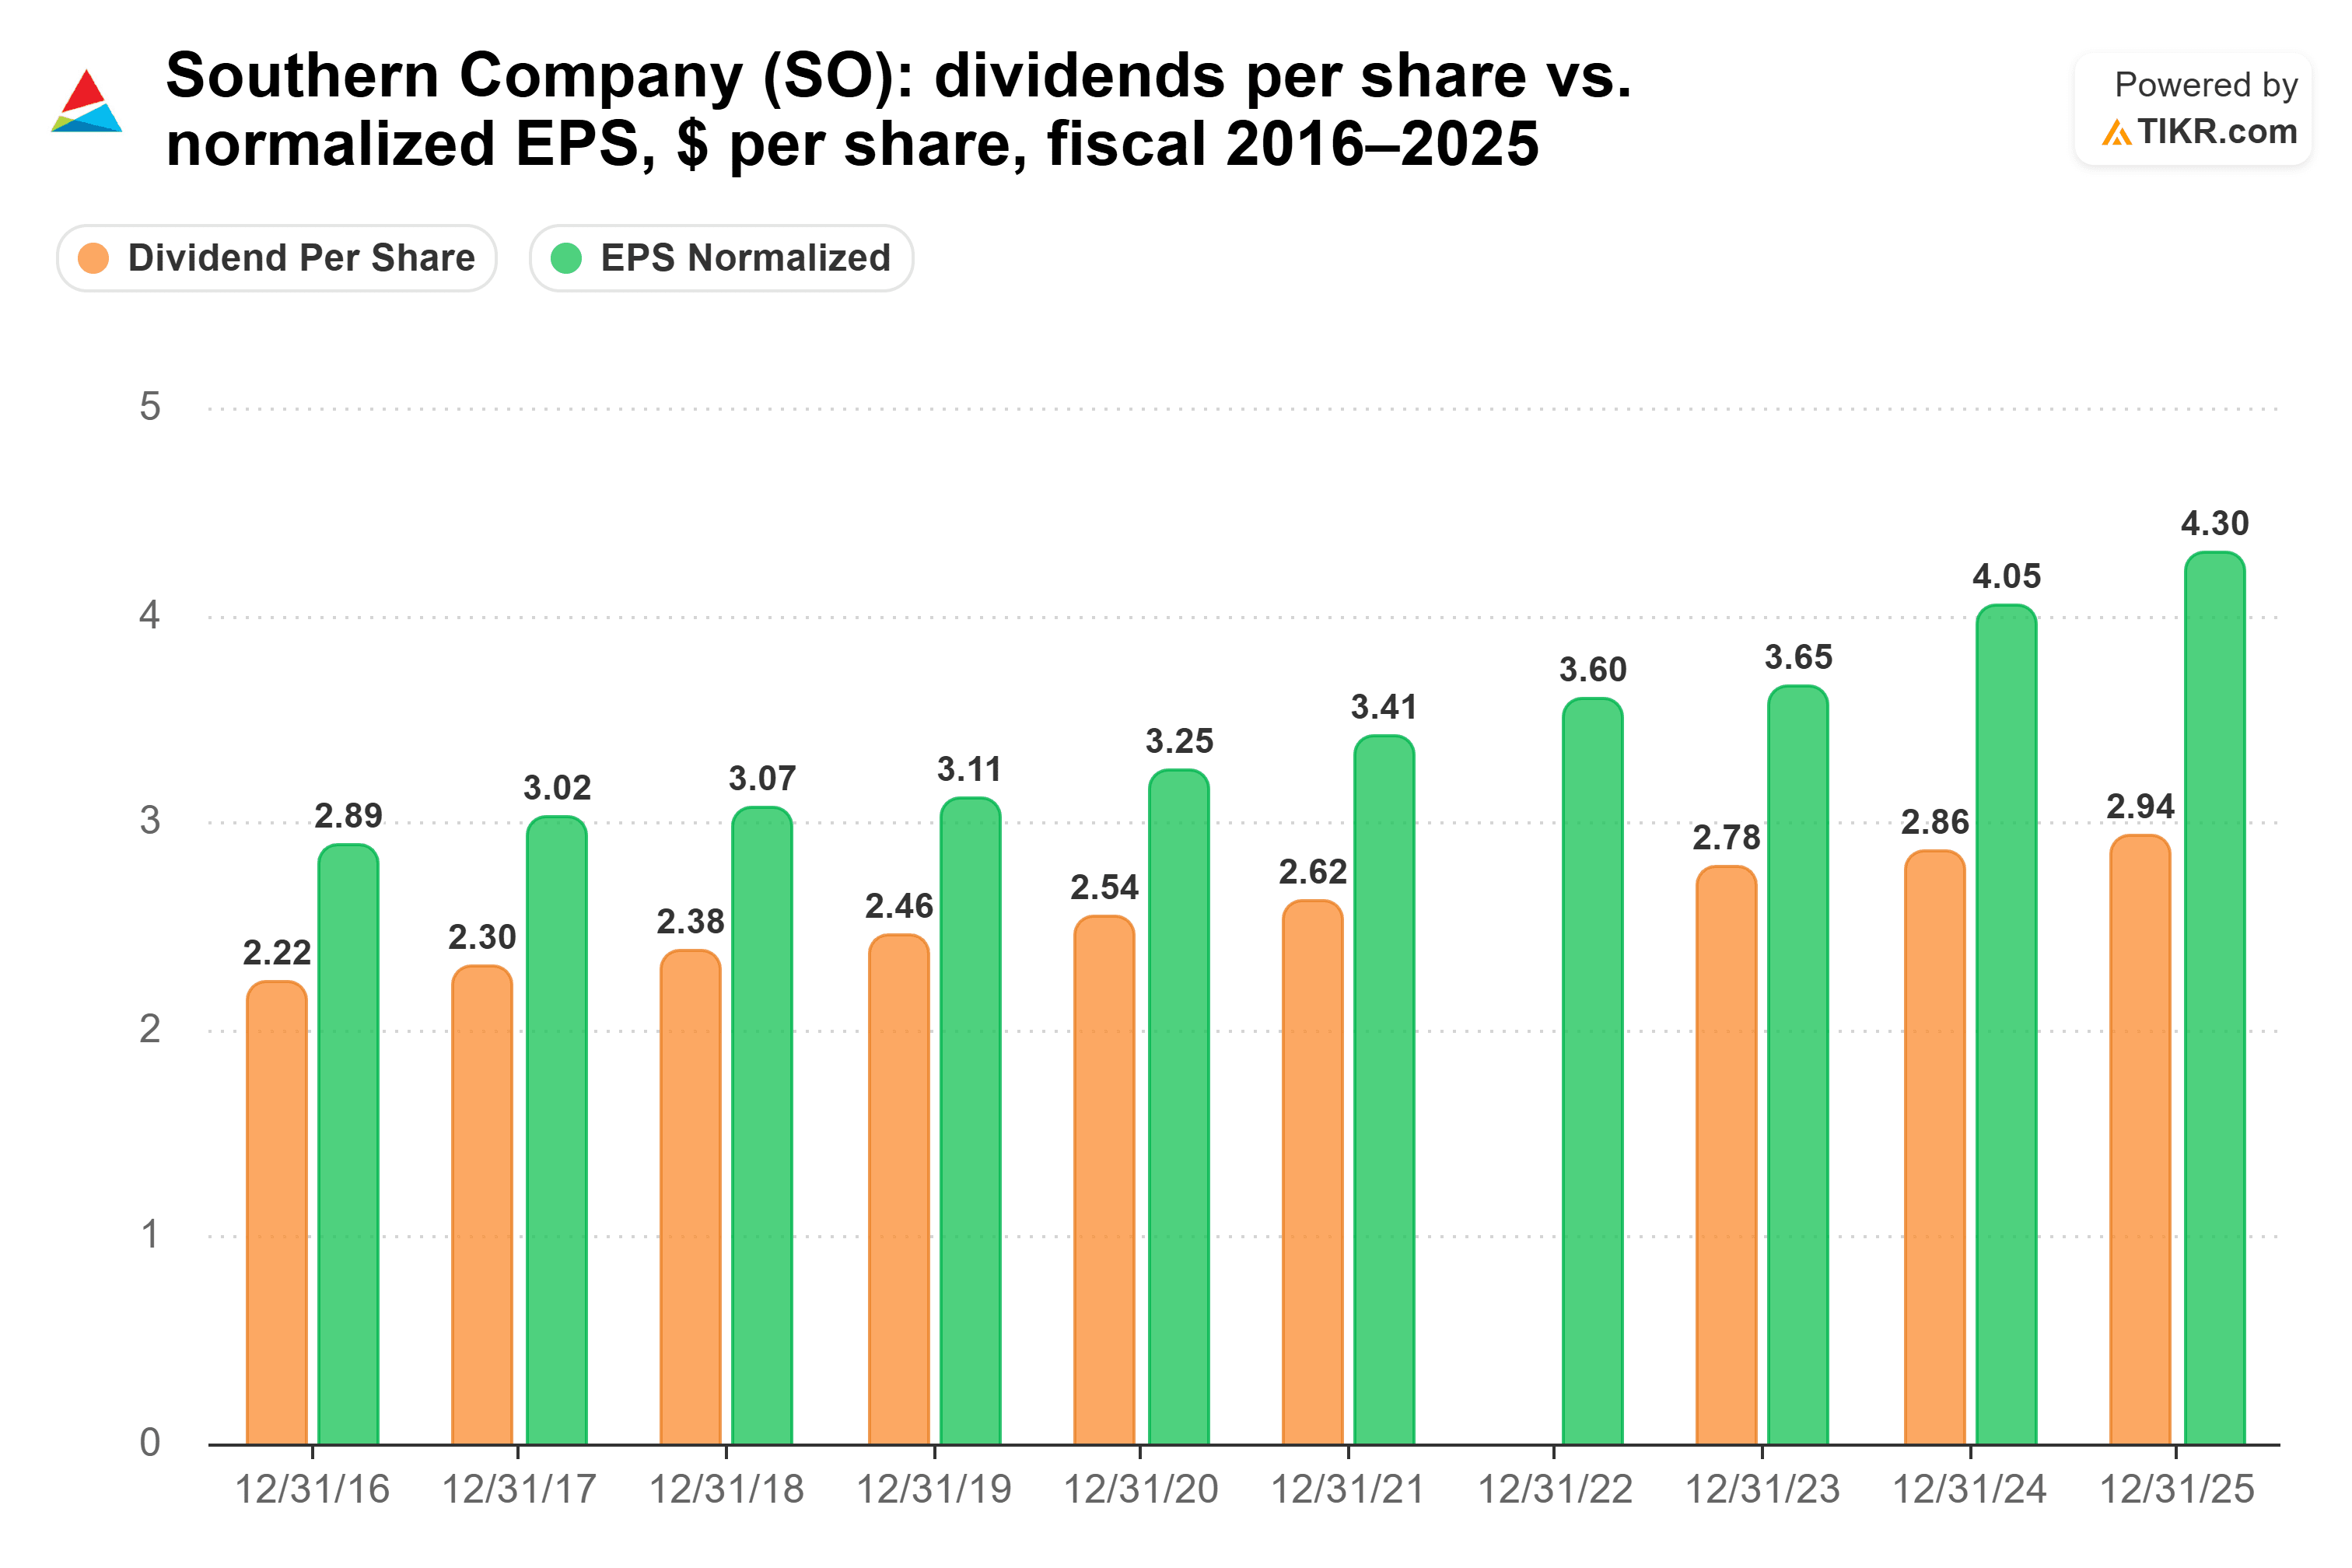
That took its payout ratio of normalized EPS from 79.1% in fiscal 2019 down to a comfortable 68.4% in fiscal 2025. Southern has signed large-load contracts for 21 gigawatts, and its new guidance works out to 9% adjusted earnings growth in 2026. On the third-quarter call, management pointed to “25 consecutive years of dividend increases, more than 3/4 of a century having never reduced our dividend.”
But Southern can’t fund all that growth from its own cash. It says its capital plan could approach $100 billion over five years, funded with about 40% equity or equity equivalents. Net debt stands at a heavy 4.9x EBITDA, and interest coverage is a thin 2.6x. Georgia is the risk to watch, with a changed Public Service Commission and an upcoming rate case.
So which dividend wins?
I’d hold Chevron for the next 20 years.
Over two decades, what matters most is whether a dividend survives the bad years, and Chevron has already shown that it can. When its free cash flow fell short, its net debt rose to 2.9x EBITDA in fiscal 2016 and 3.2x in fiscal 2020, then fell each time.

Today it’s at 0.4x, after Chevron cut net debt by $7.8 billion in the third quarter of 2026 alone. At each company’s five-year rate, $10,000 in Chevron pays about $12,240 over 20 years, against about $8,839 for Southern.
This isn’t to say Southern’s dividend isn’t safe. Its payout ratio is falling, it hasn’t cut in more than 75 years, and data centers are lining up for its power. It’s just that Southern needs new debt and stock to keep growing, while Chevron can raise its dividend through a bad year without either.
Reuters reported on Nov. 16 that Chevron is close to buying a majority stake in Beacon Offshore Energy, in a deal that values the business at about $5 billion. Chevron’s December update on its 2027 capital program will show how the deal fits.
Forget Chevron: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And Chevron isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!