Key Takeaways
- AT&T yields 5.0% and plans to hold its dividend at $1.11 a share, while PPG Industries yields 2.5% and raised its dividend 4.5% in fiscal 2025.
- Both dividends are well covered, with AT&T paying out 44% of its free cash flow over the last twelve months and PPG 50%.
- AT&T carries more debt, at 3.3x EBITDA against PPG’s 2.0x.
- AT&T’s dividend has held flat since its cut, and PPG’s keeps rising, so the 10-year answer comes down to which pace holds.
AT&T (T) raised its 2026 earnings outlook on Oct. 21 and reaffirmed its plan to keep its dividend at $1.11 a share a year. Shares fell 5% to 6% that day anyway, on worries about its rising debt.
PPG Industries (PPG) got a warmer reception a week later. A record third quarter and a higher midpoint for its full-year outlook sent shares up 7% before the open on Oct. 27. Its yield is half of AT&T’s, but its dividend is still growing. So which one actually pays you more over the next 10 years?
| Metric | AT&T (T) | PPG Industries (PPG) |
|---|---|---|
| Dividend yield | 5.0% | 2.5% |
| 5-yr dividend growth (fiscal 2020-2025) | -11.8% a year | 5.8% a year |
| Cash dividend payout ratio (TTM to Sept. 30, 2026) | 44% | 50% |
| Cash dividend payout ratio (fiscal 2026 consensus) | 46% | 50% |
| Net debt/EBITDA (LTM) | 3.3x | 2.0x |
| Interest coverage (LTM) | 3.9x | 8.7x |
Source: TIKR, at today’s prices.
6 safe dividend stocks paying retirees 6%+ yields
There are over 100 stocks paying 6%+ annual dividends today.
But after an extensive investment review leveraging TIKR’s proprietary data, we now believe only six of them are truly safe for retirees.
They’re all yours as part of our new investment report. Learn more about how to get access right here.
AT&T’s flat dividend has room to spare
AT&T’s growth is coming from fiber. Third-quarter 2026 revenue rose 5.3% to $32.3 billion, with a record 769,000 internet net adds. CEO John Stankey said on the third-quarter call that “the most durable customer combination in our industry is a fiber-fed broadband customer with a great wireless service on top of it, bar none.”
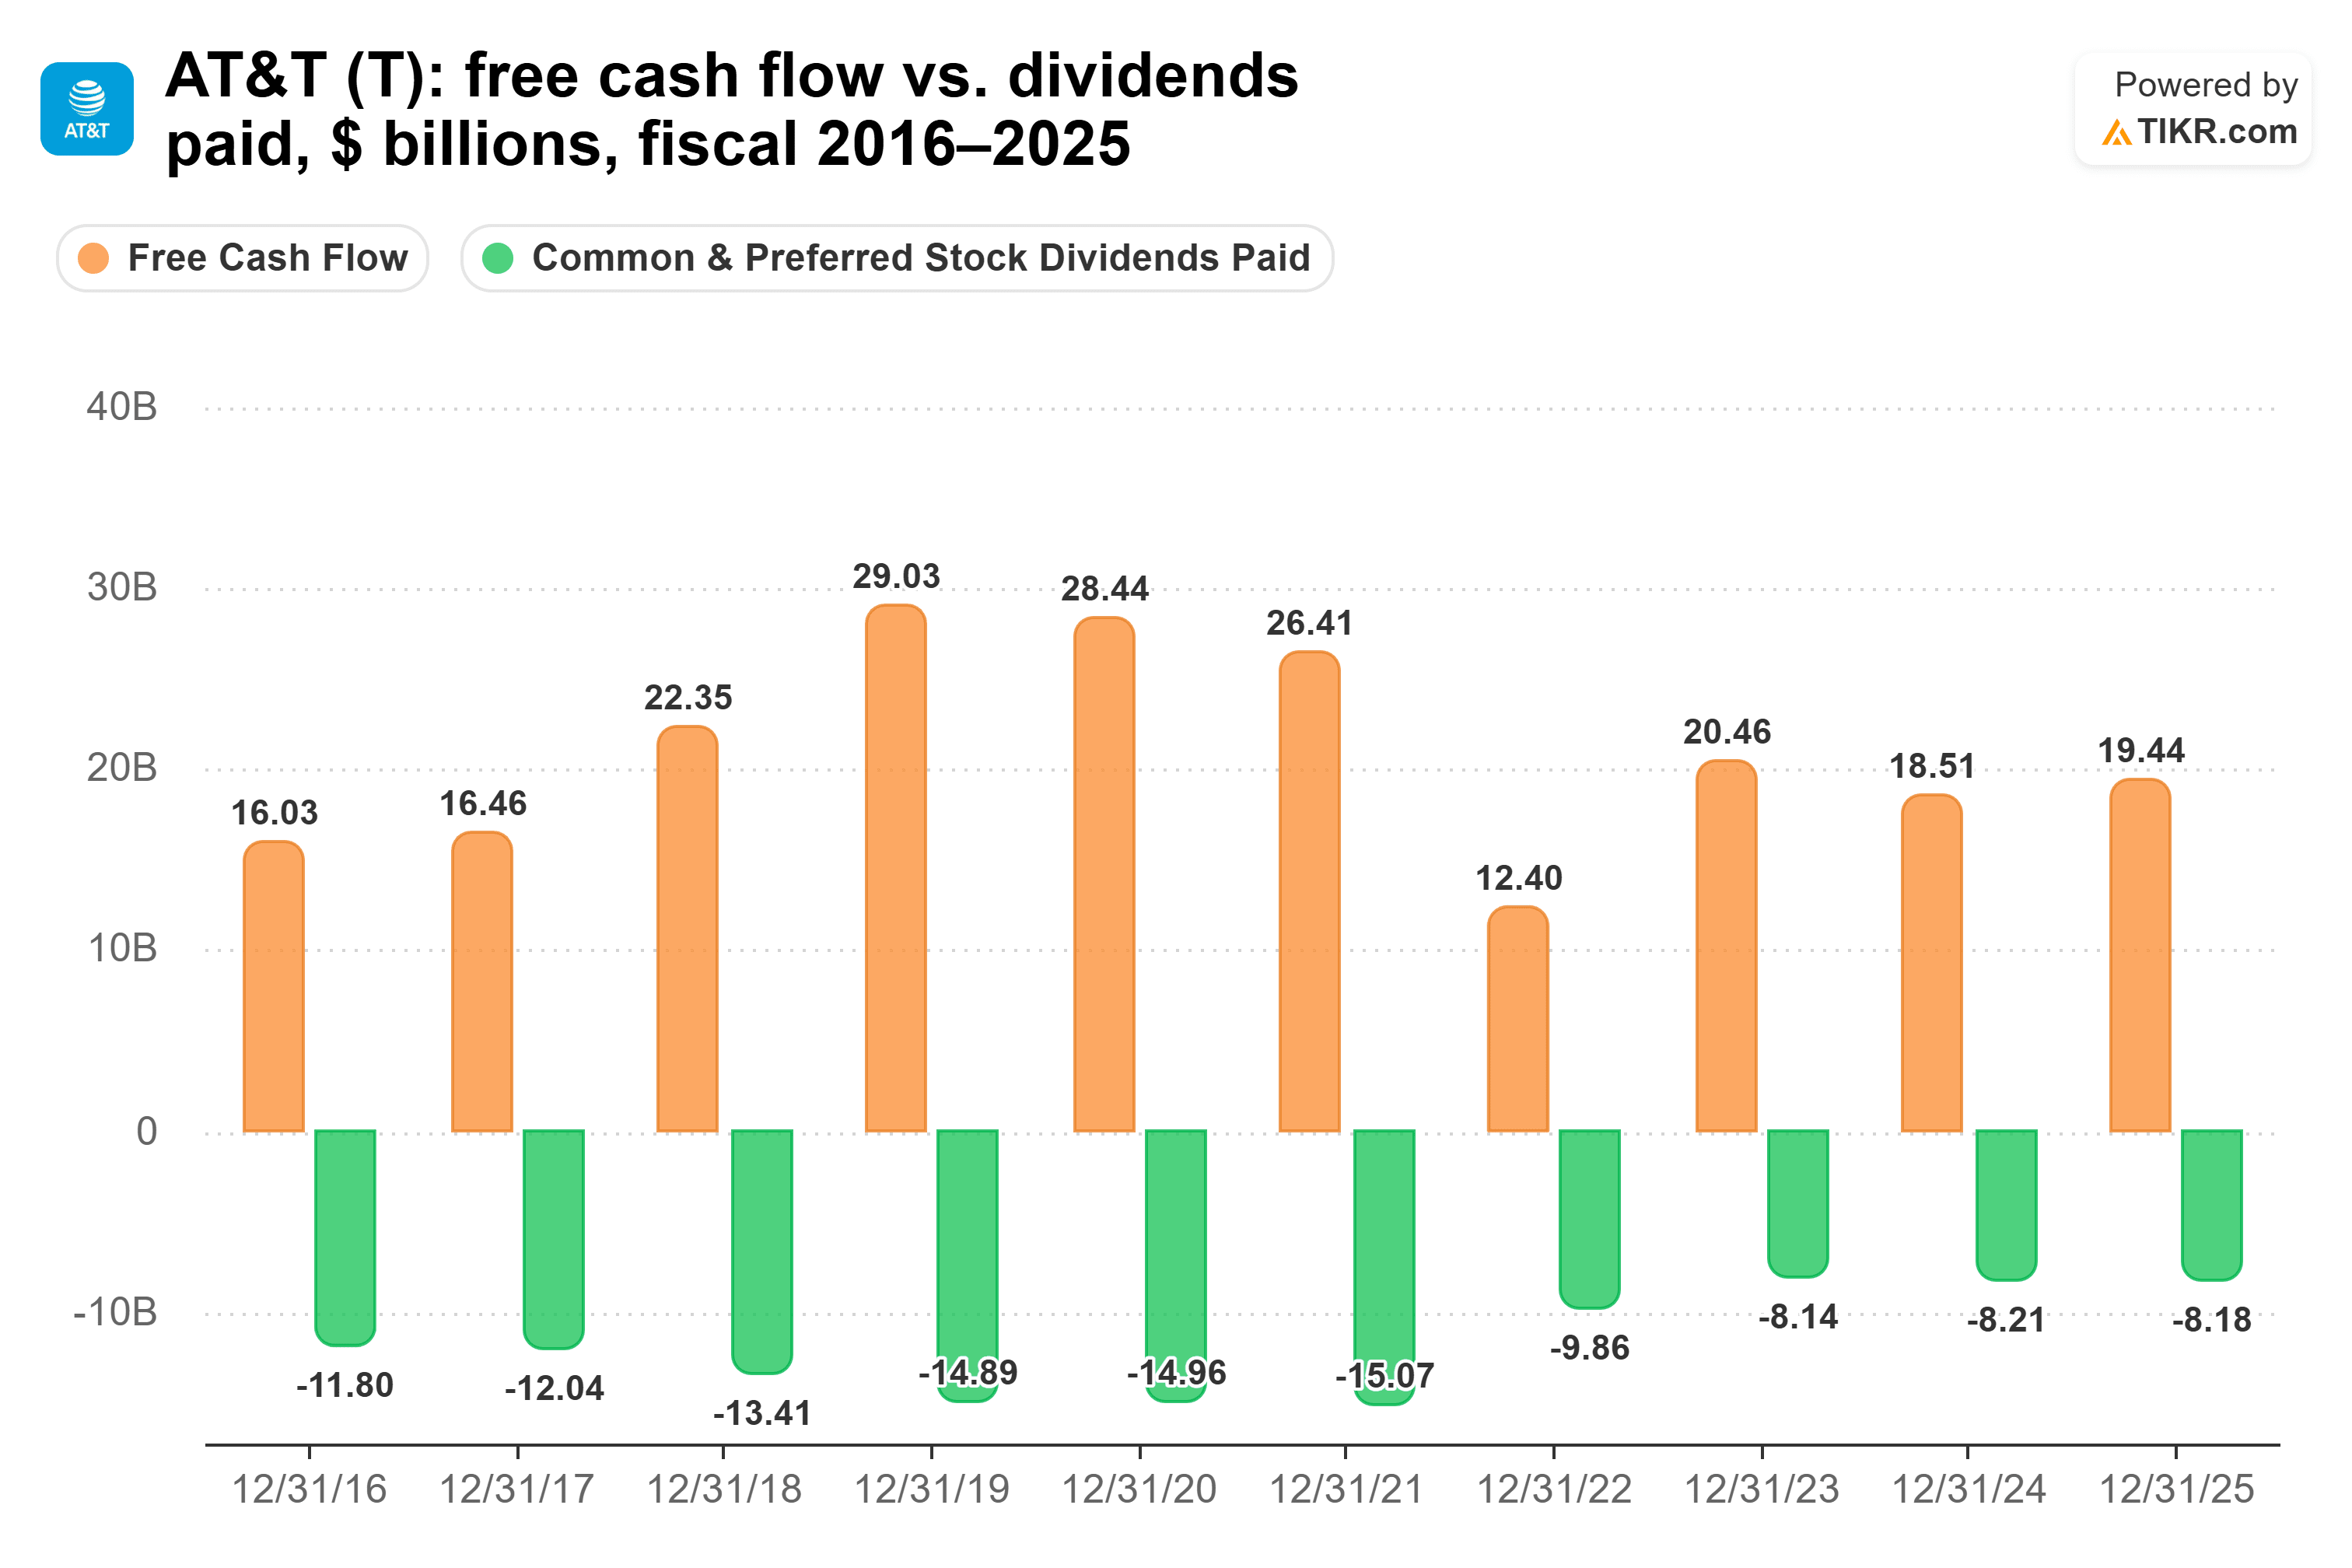
AT&T paid out a comfortable 44% of its free cash flow over the twelve months to Sept. 30, 2026, and consensus has 46% for fiscal 2026. After the cut, dividends paid fell from $15.1 billion in fiscal 2021 to $8.1 billion in fiscal 2023, and free cash flow has run well above them since:
The risk is debt. Net debt is 3.3x EBITDA, and EBIT covers interest just 3.9x. The $2 billion sale of AT&T Mexico, expected to close in the first quarter of 2027, brings in some cash.
PPG keeps raising, but its cash swings more
PPG’s dividend rose 4.5% in fiscal 2025, and 5.8% a year from fiscal 2020 to fiscal 2025, from $2.10 to $2.78 a share. Third-quarter net sales rose 7% to $4.4 billion, and adjusted EPS rose 6% to a record $2.25. Industrial Coatings was the soft spot: its EBITDA margin fell 260 basis points to 14.4% as costs outran pricing.
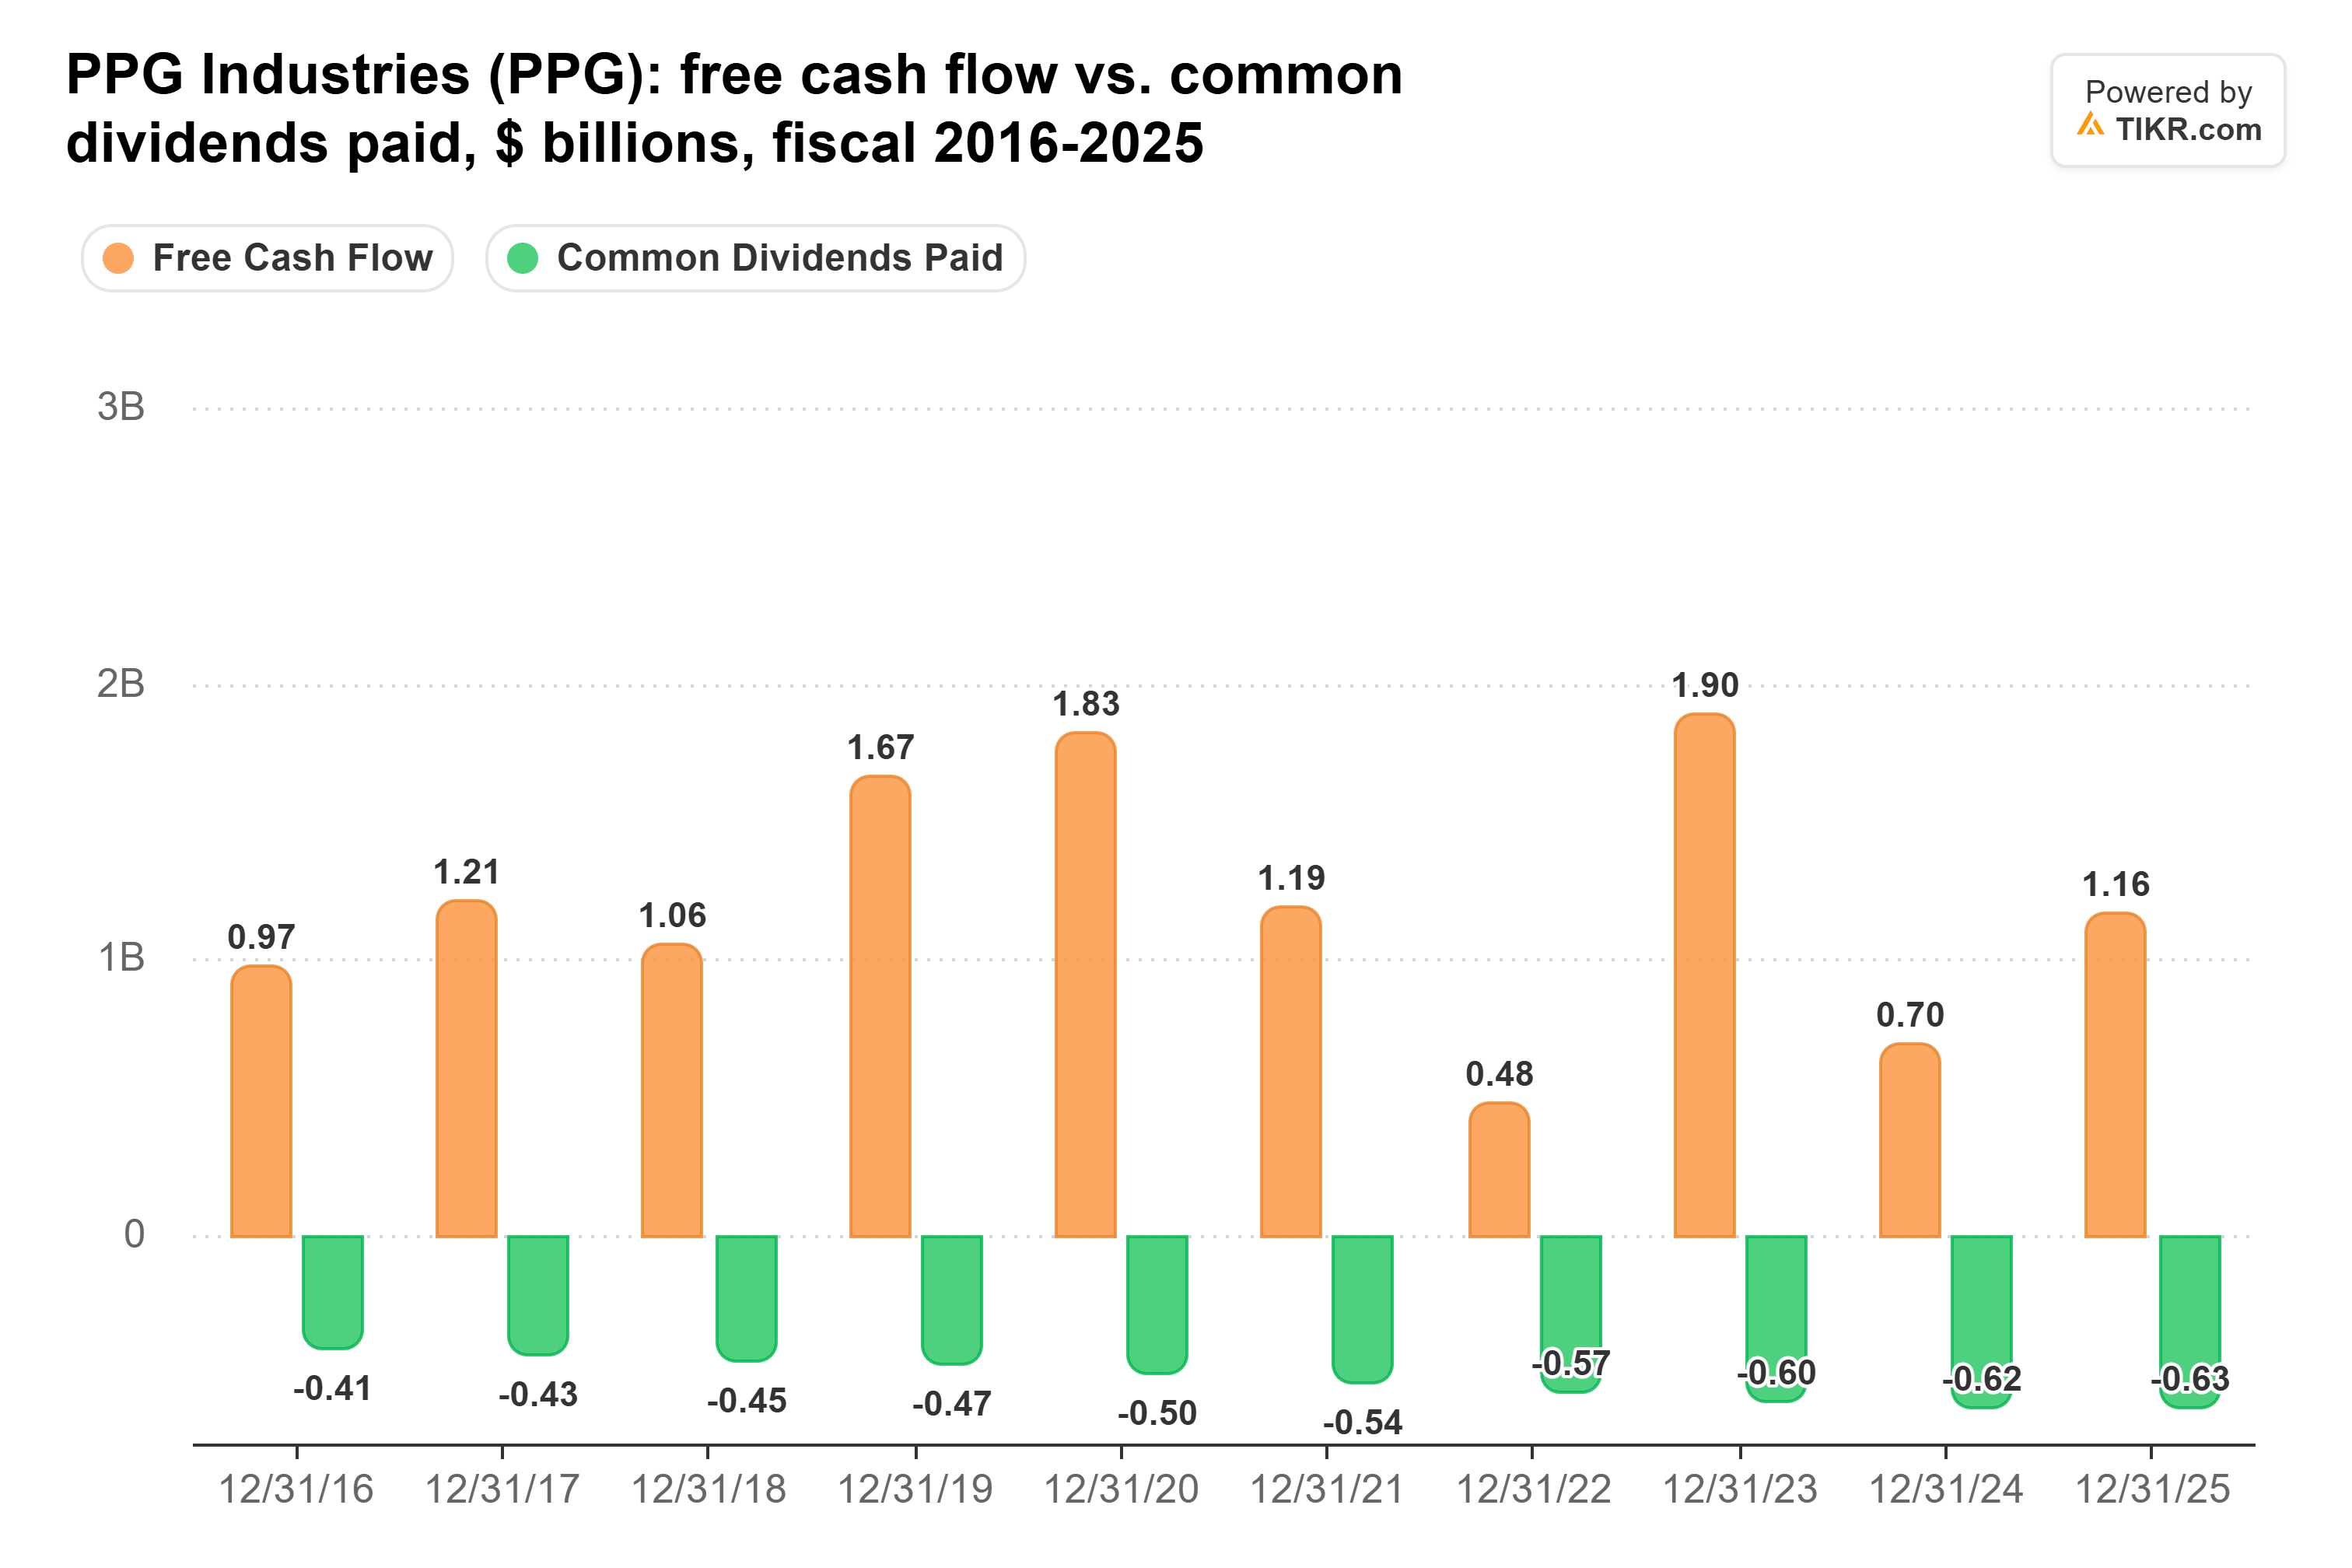
PPG paid out 50% of its free cash flow over the twelve months to Sept. 30, 2026, and consensus has the same 50% for fiscal 2026. Dividends paid rose every year from $410 million in fiscal 2016 to $630 million in fiscal 2025. Free cash flow fell short of them in fiscal 2022, and covered them at a risky 89% in fiscal 2024:
PPG’s net debt of $5.2 billion is down about $200 million from a year earlier.
So which dividend wins?
AT&T pays you more over 10 years, and by a wide margin. At each dividend’s pace now (AT&T’s flat $1.11 and PPG’s 4.5% raise in fiscal 2025), $10,000 in AT&T pays about $5,000 over the decade. The same $10,000 in PPG pays about $3,074, so AT&T comes out about $1,926 ahead. PPG’s income wouldn’t pass AT&T’s until about 2042.
Run each 5-year rate forward instead, and PPG edges ahead by about $230, since AT&T’s $500 a year would shrink to about $161 by year 10. But AT&T’s rate starts from its cut, and the company plans to hold $1.11. Even at its faster 5-year pace, PPG pays about $3,260 over the 10 years, still well short of AT&T’s flat check.
AT&T also has the cash to keep paying. It guides free cash flow to $18 billion+ in 2026, $19 billion+ in 2027 and $21 billion+ in 2028, and analysts are right in line:
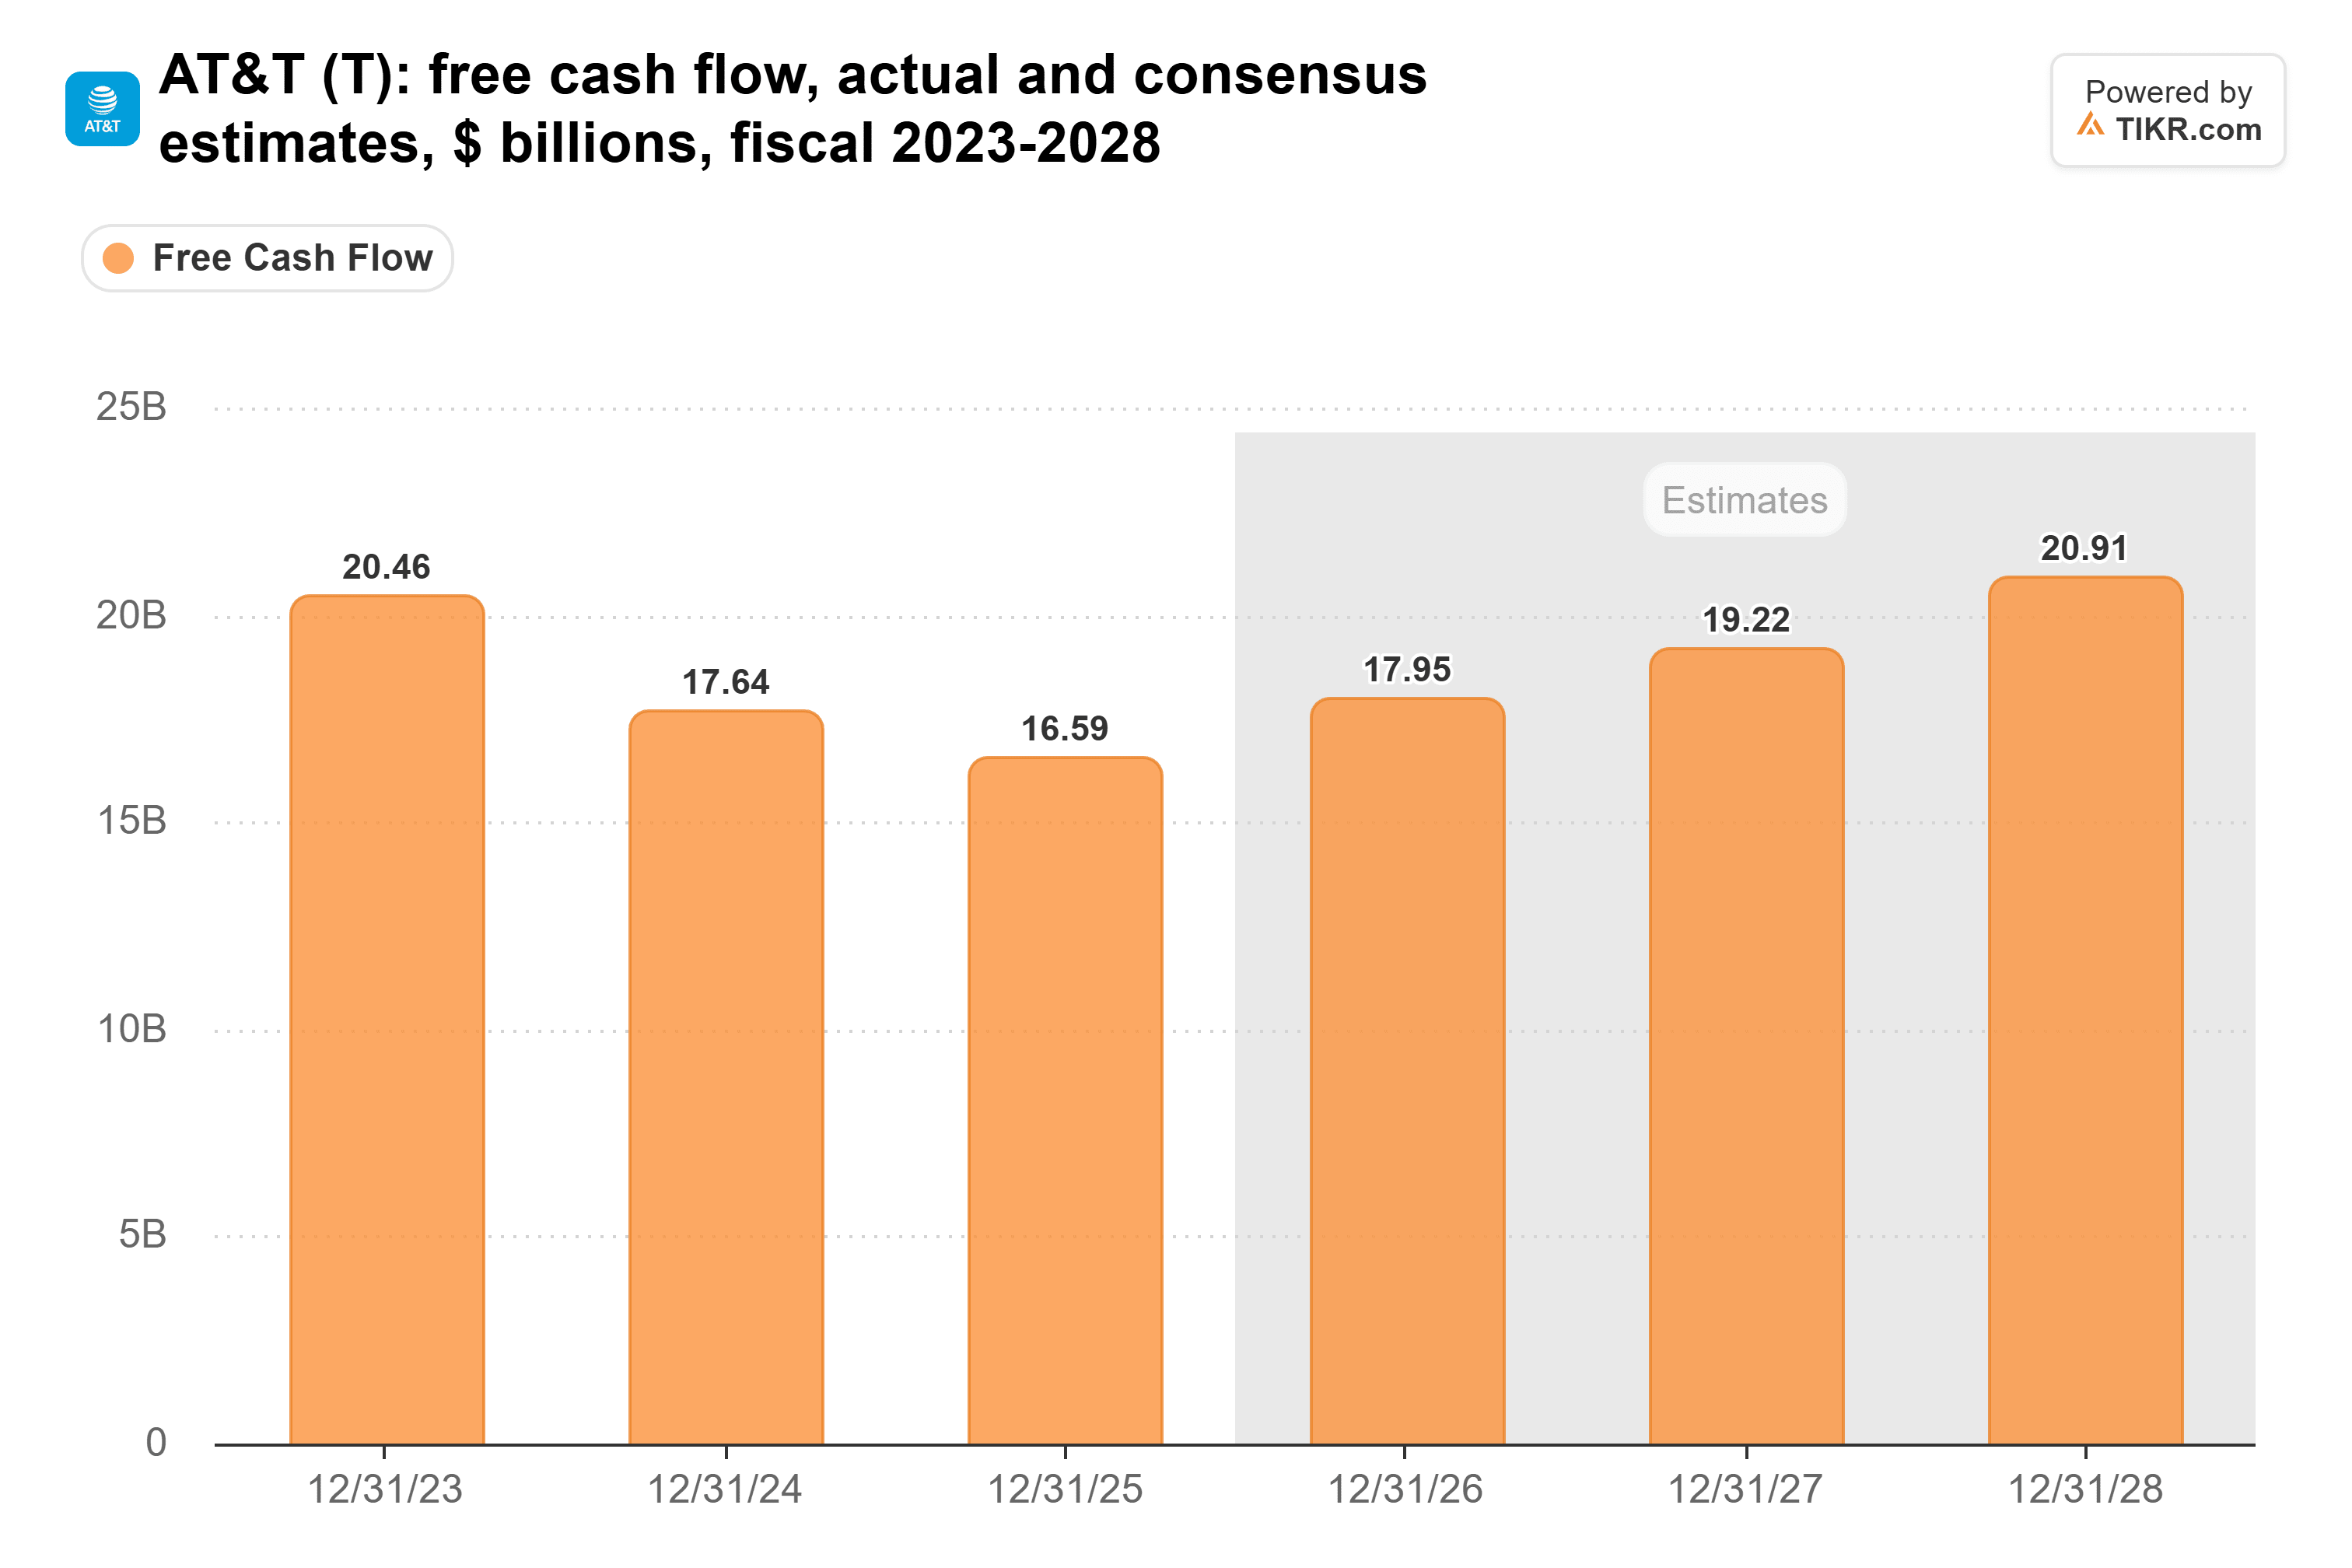
That’s more than twice what the dividend costs each year.
PPG has a strong case of its own. Its dividend grows, its debt is lighter, and it just raised its outlook after a record quarter. Over 10 years, though, AT&T’s 5.0% starting yield is too big a head start, and its coverage is a bit better too.
AT&T only loses this race with another cut, so watch the debt. Management doesn’t expect leverage back to its 2.5x target until 2029, and it also plans $24 billion+ of buybacks.
Forget AT&T: 6 safe 6%+ dividend yields you can buy right now
Dividends can hold the key to enormous wealth. But only if you buy the right ones.
Picking the right high-yield dividend stock can be the difference between a dream retirement…and scraping by every month, waiting for the next Social Security check to clear.
We’ve identified six stocks yielding 6%+ that we believe every retiree should know about right now. (And AT&T isn’t one of them.)
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!