Key Takeaways
- Berkshire Hathaway’s third-quarter operating earnings fell 5.8% to $12.7 billion as underwriting profit across its insurers dropped 43%.
- Geico’s underwriting profit fell to $982 million from $1.77 billion as it cut prices to win back customers, while Progressive improved its combined ratio.
- BNSF earnings rose 19% and Berkshire Hathaway Energy gained 8%, yet CFRA’s Cathy Seifert asked “what about the rest of the franchise.”
- Berkshire bought back $9.6 billion of stock in the quarter, but shares near record highs could slow buybacks before the February report.
Berkshire Hathaway (BRK.B) reported third-quarter operating earnings of $12.7 billion on November 7, down 5.8% from a year earlier. Insurance did the damage, and Geico did most of it.
Yet the stock has rarely looked stronger. Shares hit record highs the week of the report and are up more than 13% in 2026, beating the S&P 500 by over five points.
Meanwhile, the insurance picture looks worse next to Progressive (PGR). Its third-quarter premiums earned rose 5% to $21.9 billion, while Berkshire’s stayed flat at $22.4 billion.
Greg Abel’s answer was to buy back stock. Berkshire repurchased $9.6 billion in the quarter and about $2 billion more in October.
Two businesses moving opposite ways
The headline decline hides a business pulling in two directions. Here’s how the main pieces moved from a year earlier:
- Insurance underwriting profit fell 43% to $1.35 billion.
- Investment income from insurance slid 14% to $2.73 billion.
- BNSF earnings jumped 19% to $1.73 billion, and Berkshire Hathaway Energy rose 8% to $1.61 billion.
Manufacturing, service and retailing added $4.04 billion, up 12%. So outside insurance, the quarter held up well. Revenue climbed 11% to $105.65 billion, the second straight quarter of double-digit growth…
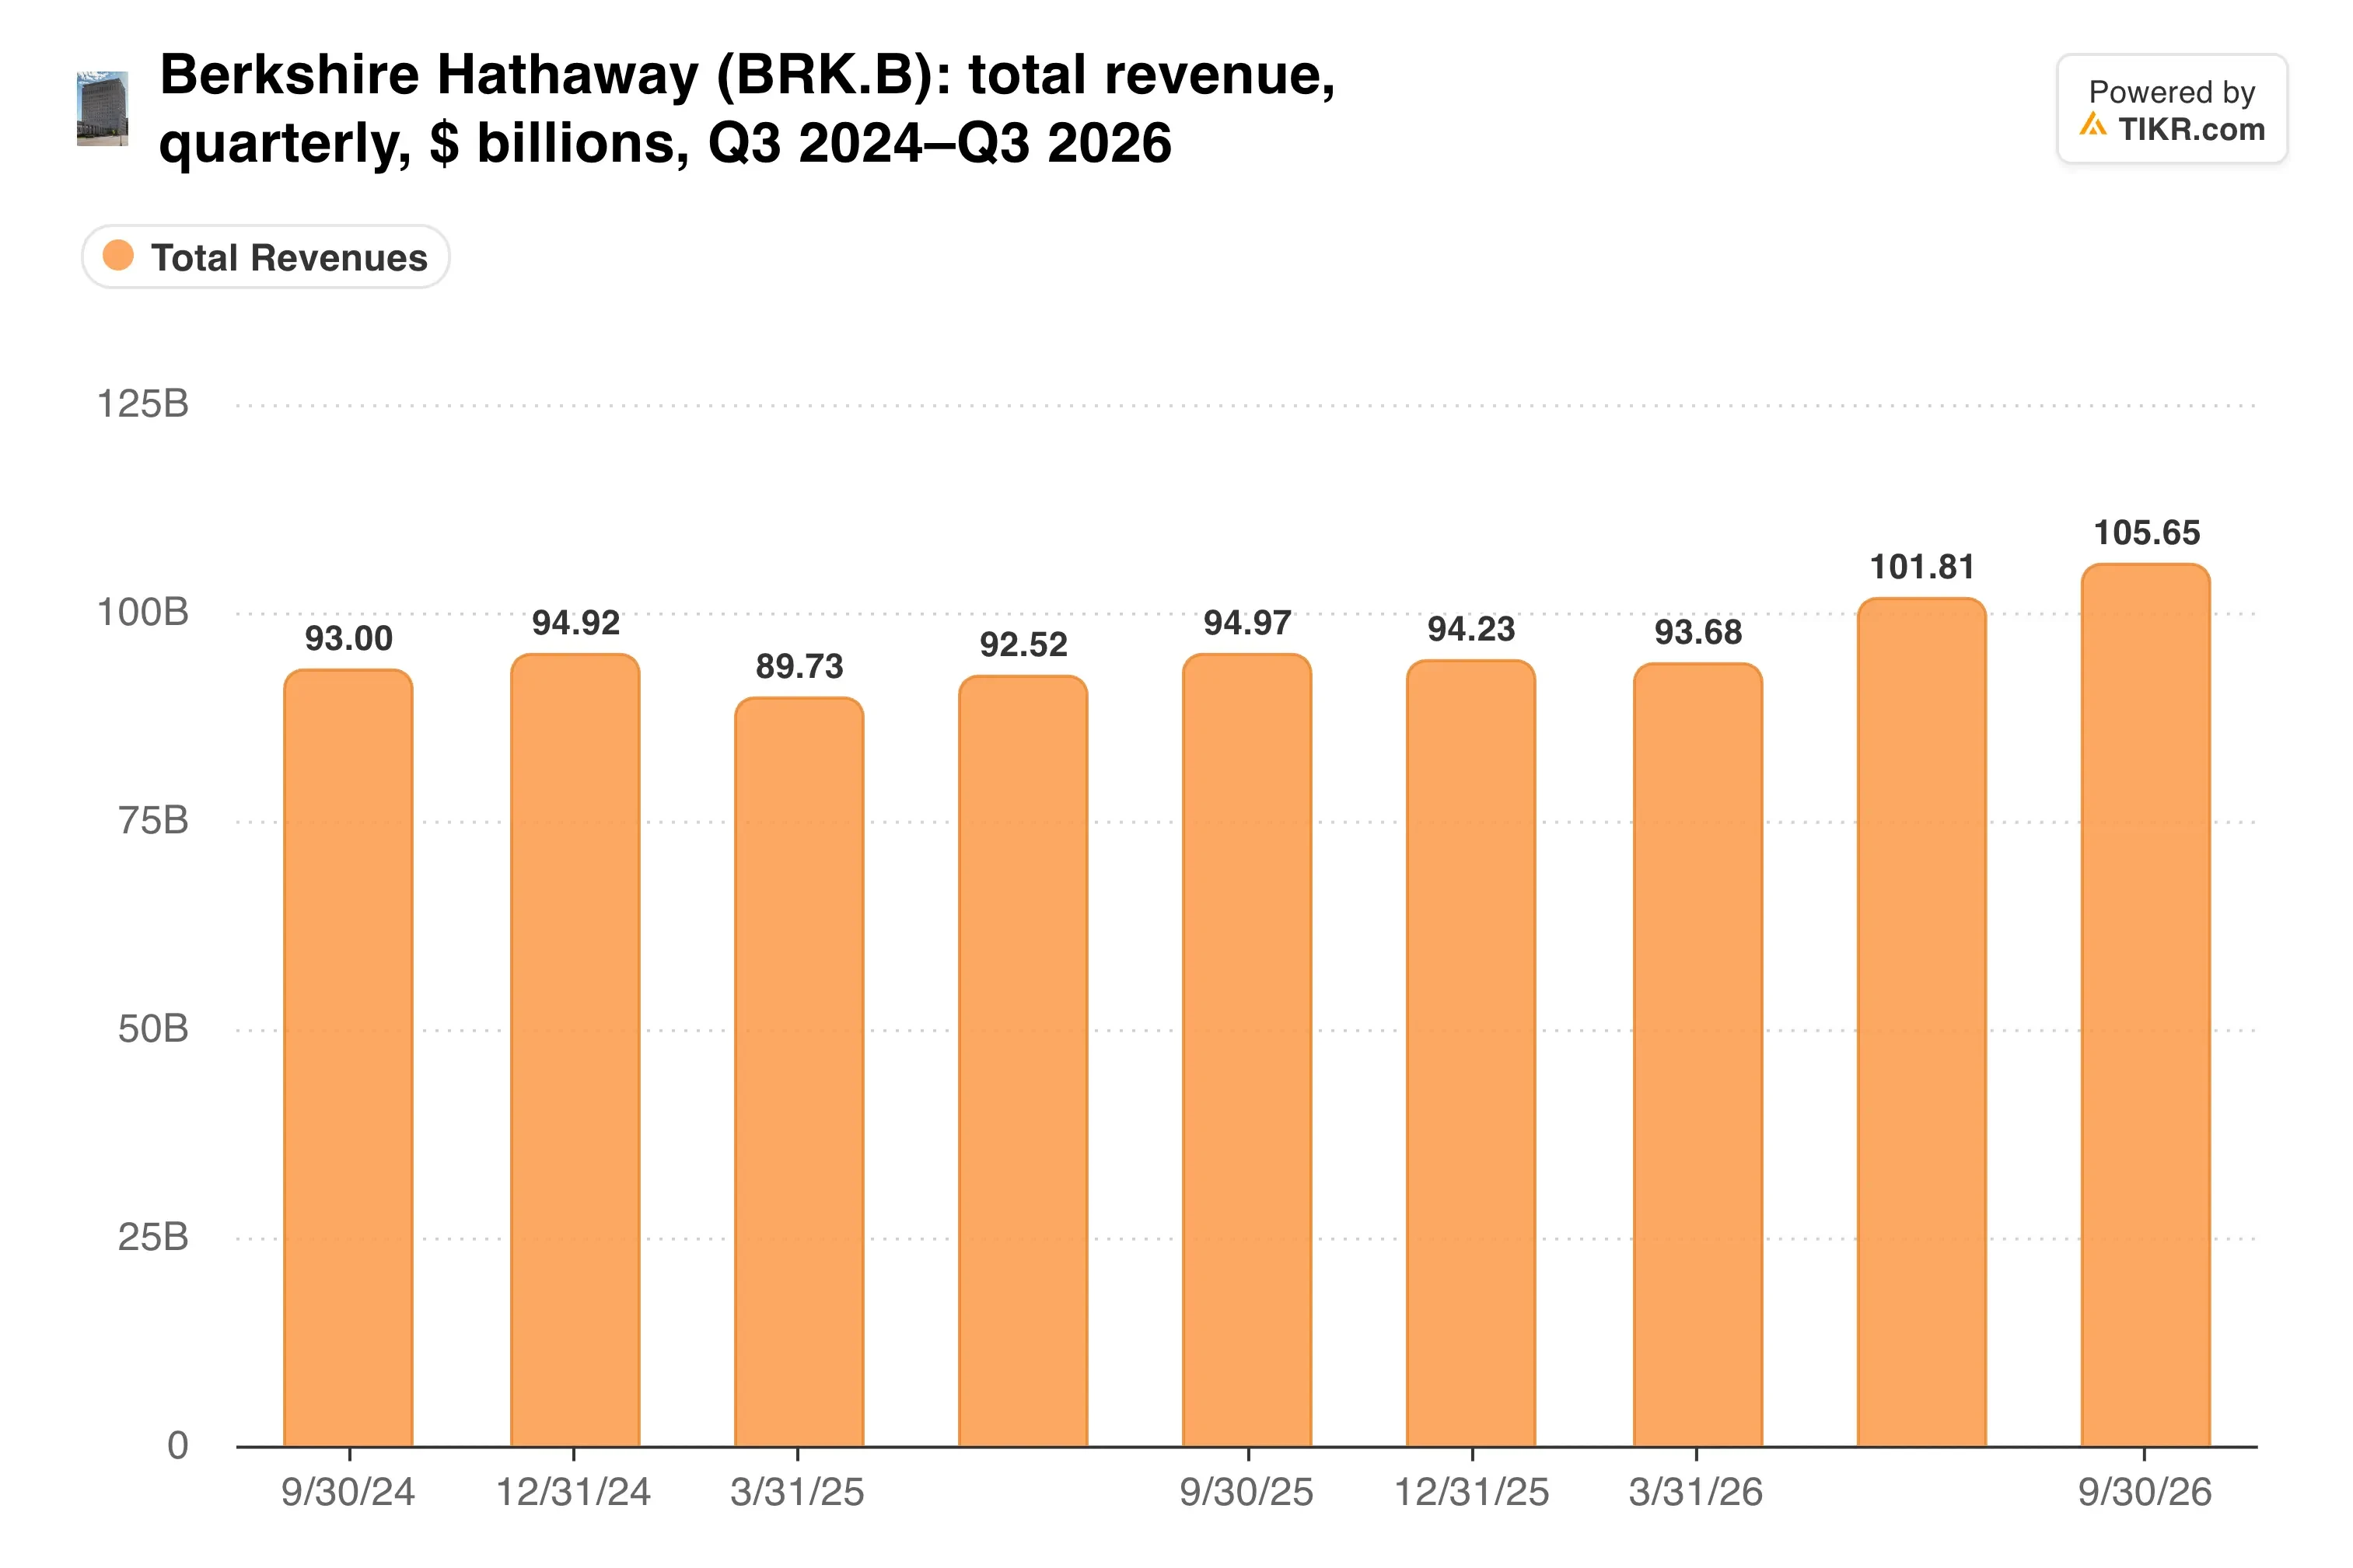
That growth came even as consumer brands such as Fruit of the Loom and Forest River RVs declined. Berkshire also warned that some retailers face sluggish demand because of tariff and geopolitical uncertainty.
Geico is buying back customers
Geico’s pretax underwriting profit fell to $982 million from $1.77 billion. Accident losses pushed its loss ratio to 76.6% from 71.5%, and advertising costs climbed too.
Part of that squeeze is deliberate. Geico is accepting lower premiums to win back customers it lost during a long effort to tighten underwriting and cut overhead.
So how far has the claims pressure spread across Berkshire’s insurers?

Claims also grew at Berkshire’s other insurance and reinsurance businesses, so the pressure reaches beyond Geico.
Progressive, by comparison, kept growing while improving its margin. Its combined ratio fell to 88.7 from 89.5, and net premiums written rose 4% to $22.3 billion.
Cathy Seifert, a CFRA Research analyst who rates Berkshire hold, said the businesses playing to Abel’s strengths are doing well. “But the question is what about the rest of the franchise,” she told the Associated Press.
BNSF and the utilities help cover the gap. Together they earned $3.34 billion in the quarter, against $1.35 billion from underwriting.
TIKR tracks 4 analysts on Berkshire Hathaway. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Berkshire Hathaway, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Berkshire Hathaway’s Analyst Ratings
Buybacks meet a record price
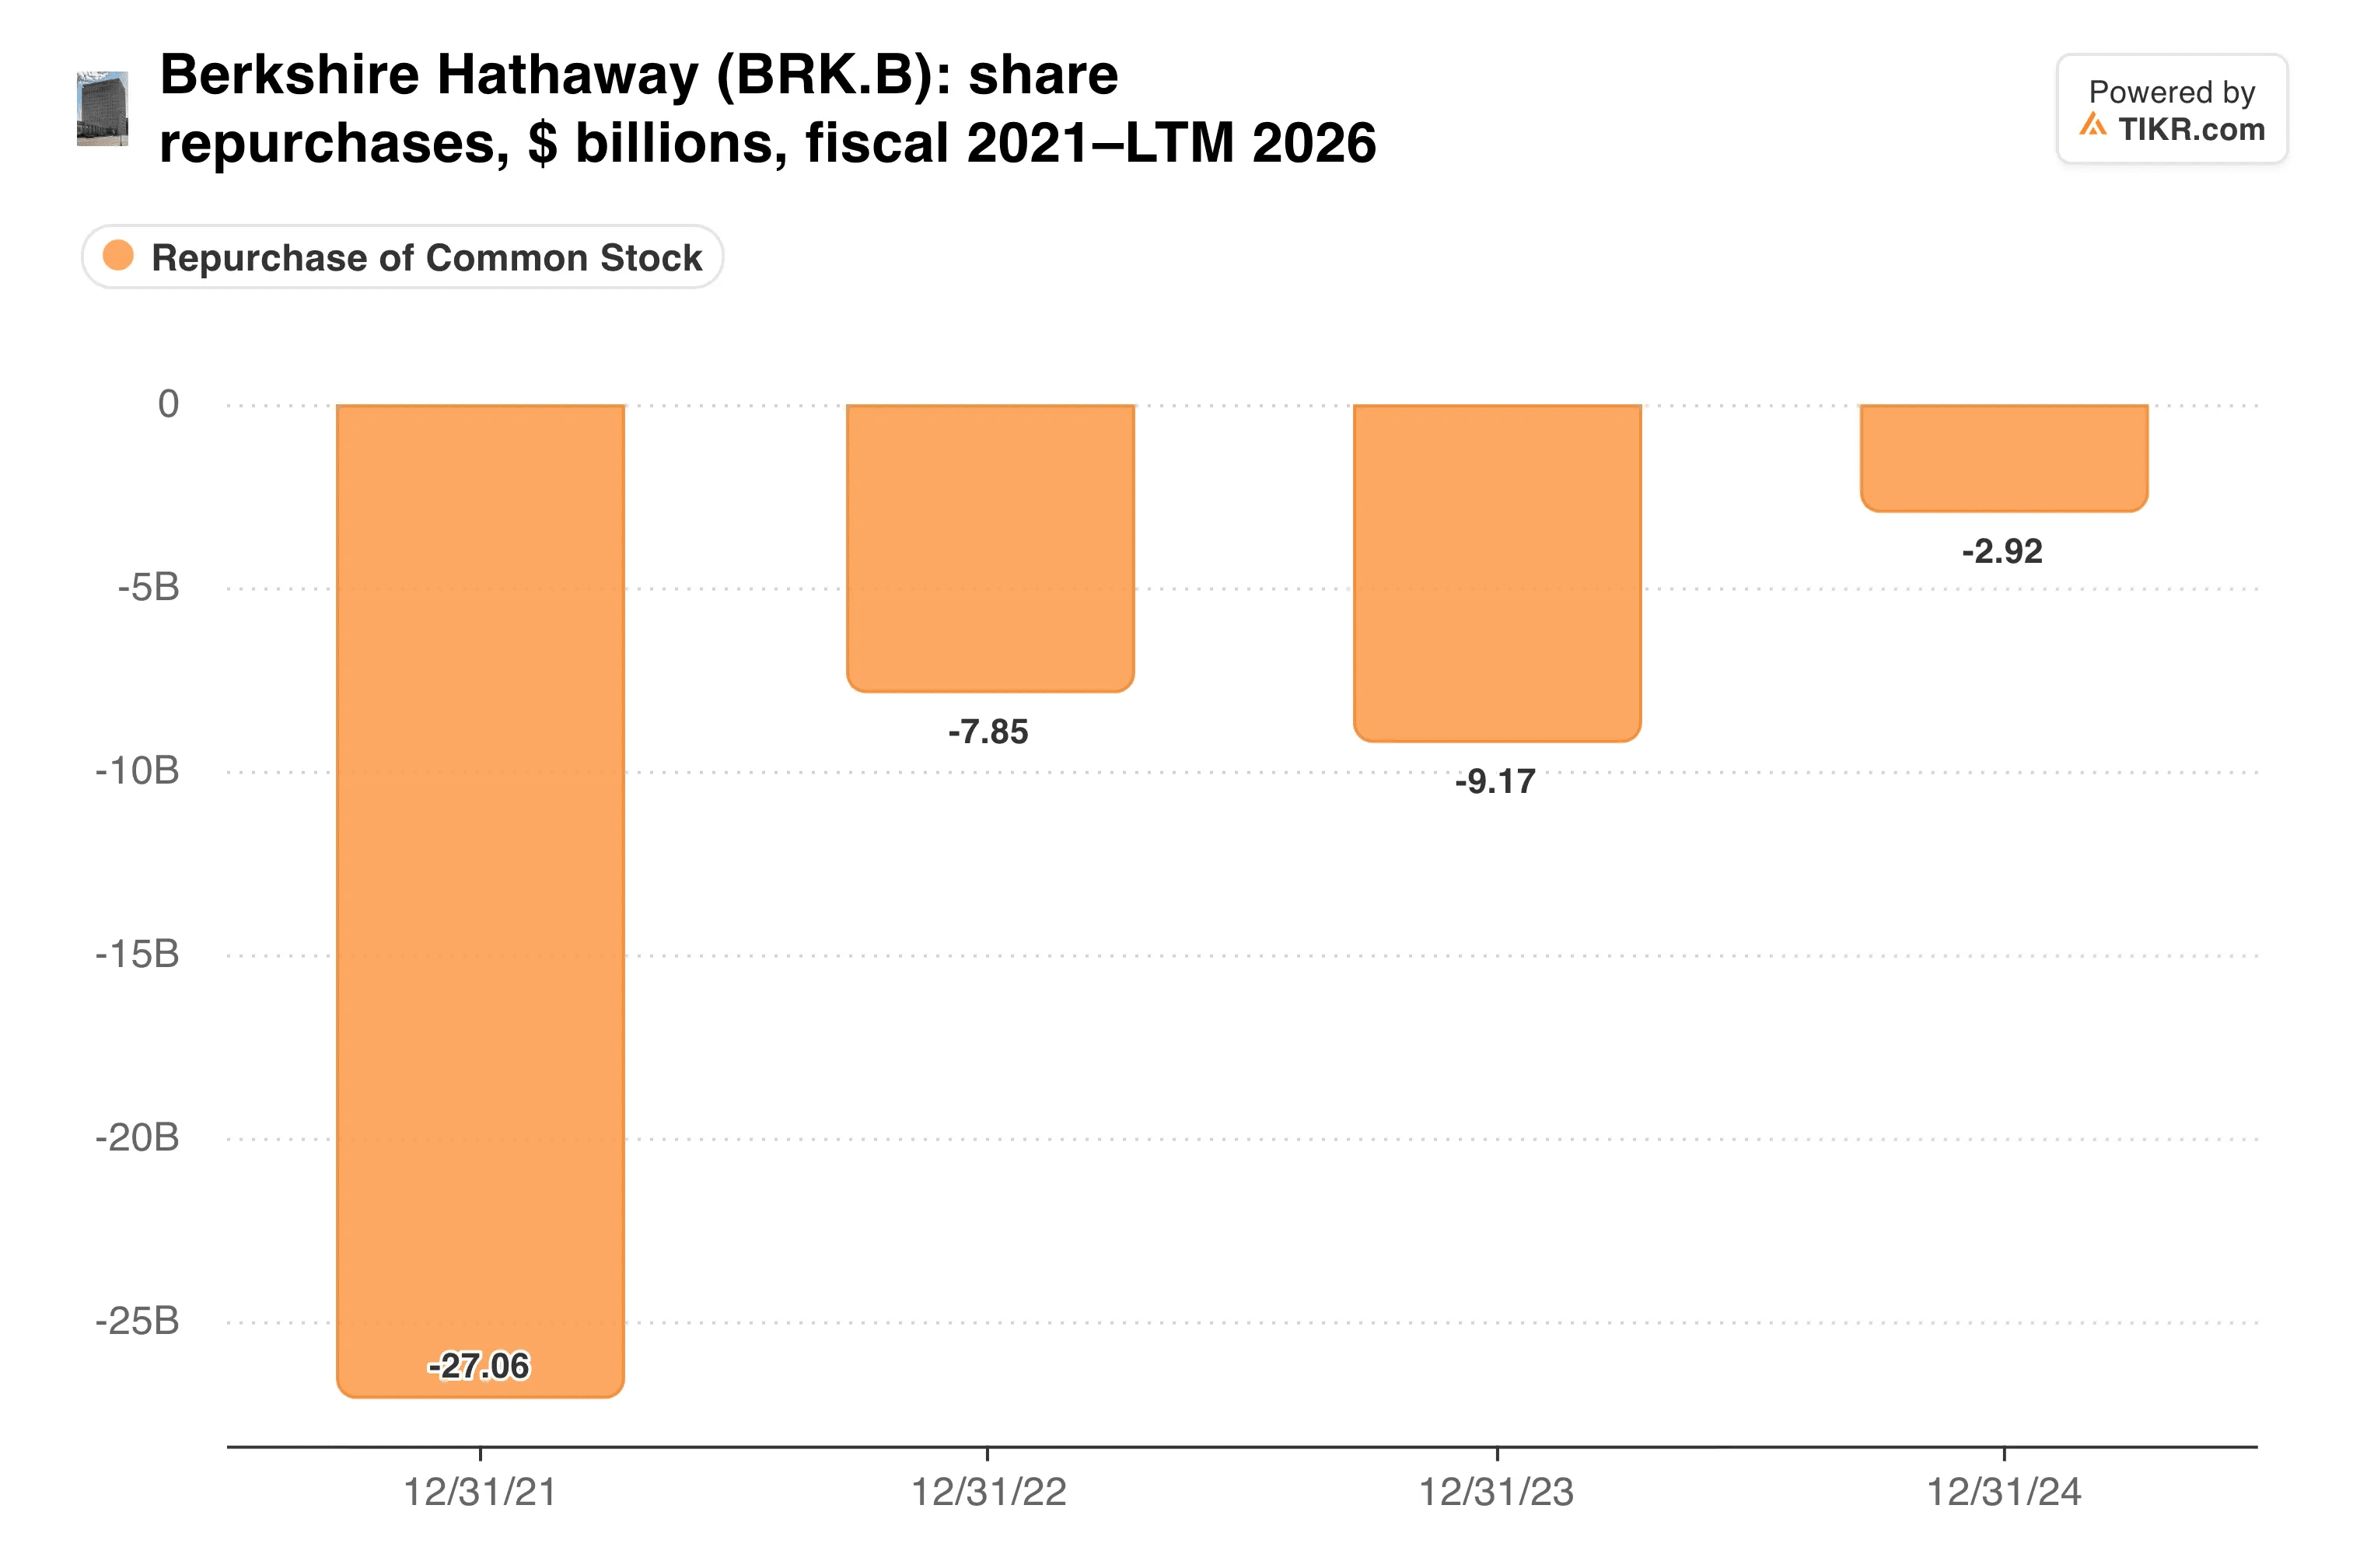
Buybacks now total roughly $16.4 billion this year through October. That still trails 2021, Berkshire’s record year at $27 billion. However, it marks a clear break from Buffett’s final years, when he struggled to find anything worth buying.
The buyback line tells the story of that shift.
Even after the spending, Berkshire ended September with $356.9 billion of cash and equivalents.
The catch is price. Berkshire repurchases stock only when it believes shares trade below intrinsic value, and the stock now sits near record highs. As a result, October’s $2 billion could be the last large batch for a while.
My take: Abel is running Berkshire more decisively than Buffett did at the end, and the railroad and utilities are pulling their weight. Still, Geico is trading margin for growth while Progressive grows and improves margins at the same time. At record highs, I’d hold here rather than add, because much of the good news already looks priced in.
The next checkpoint is the fourth-quarter report and Abel’s second annual letter, expected in late February. Both should show whether Geico’s lower prices are actually winning back customers.
So what is Berkshire Hathaway stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Berkshire Hathaway could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!