Key Takeaways
- AMD shares fell 17% on November 5, then recovered after Alphabet’s Google Cloud picked its EPYC chips and Oppenheimer upgraded the stock.
- Third-quarter revenue rose 45% to $13.4 billion, while Intel forecast its fourth-quarter chip revenue to fall in the mid-20% range.
- Lisa Su expects 2027 revenue to grow more than 80%, but adjusted gross margin is slipping and PC shipments are set to shrink.
- The fourth-quarter report, expected in early February, will show whether Helios and Venice delivered roughly $17 billion in revenue.
Lisa Su did not sound worried. On November 5, the day Advanced Micro Devices (AMD) stock fell 17%, she brushed off the selloff on Yahoo Finance’s Sozzi Unleashed. “I think the market can sometimes be a little bit short-sighted,” she said.
The timing stung. Two days earlier, AMD had posted a record quarter and guided 2027 revenue growth above 80%. Yet a broad chip rout dragged the stock down anyway.
Then sentiment flipped. On Monday, AMD said its fifth-generation EPYC processors will host Alphabet (GOOGL)’s new Google Cloud TPU 8tx system. Oppenheimer upgraded the shares to Outperform with a $600 target that morning. The stock jumped about 13%.
Meanwhile, the gap with Intel (INTC) keeps widening. Intel forecast its fourth-quarter chip revenue to fall in the mid-20% range, while AMD expects roughly 66% growth.
A record quarter, then a rout
AMD beat on every headline number in its third quarter:
- Revenue rose 45% to $13.4 billion, ahead of the $13.09 billion analysts expected.
- Adjusted EPS climbed 74% to $2.09, above the $1.95 consensus.
- Fourth-quarter guidance calls for about $17 billion, plus or minus 3%, above the $16.23 billion Street estimate.
Data Center did nearly all the heavy lifting, and the mix now looks lopsided…

Data Center revenue jumped 97% to $8.5 billion, close to two-thirds of sales. Client and Gaming slipped 8% to $3.7 billion because gaming fell 40%. Embedded added $1.1 billion, up 29%, so the weak spot sits squarely in consoles and graphics.
Google hands EPYC a new job
Monday’s Google news matters because of where it places AMD. TPU 8tx pairs Google’s own accelerators with EPYC host CPUs. It is also the first cloud TPU system with hardware-enforced confidential computing. So even Google’s in-house AI hardware now leans on AMD for its host processors.
That fits Su’s pitch. On the earnings call, she said data center chips will “drive the majority of our revenue and earnings growth” next year. She expects that business to make up about 80% of 2027 sales. Server revenue should double, and data center AI should more than double.
Helios carries the other half of the plan. The rack combines MI455X accelerators with Venice CPUs to take on Nvidia’s rack-scale systems. Anthropic, Meta, Microsoft, OpenAI and Oracle already run workloads on the first units. Production scales sharply this quarter.
How much could all that add to the top line?

Su’s 2027 growth call landed above what analysts had modeled, so estimates may still be catching up.
TIKR tracks 55 analysts on AMD. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AMD, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AMD’s Analyst Ratings
Margins and PCs keep it honest
The quarter still had soft spots. AMD guided adjusted gross margin to about 55% for the fourth quarter, in line with estimates but down from 56%. It also expects PC unit shipments to fall by a double-digit percentage next year. Su says AMD will outperform that market, though.
On top of that, a global memory shortage keeps high-bandwidth memory scarce for every AI chipmaker.
Even so, profits are scaling faster than sales.
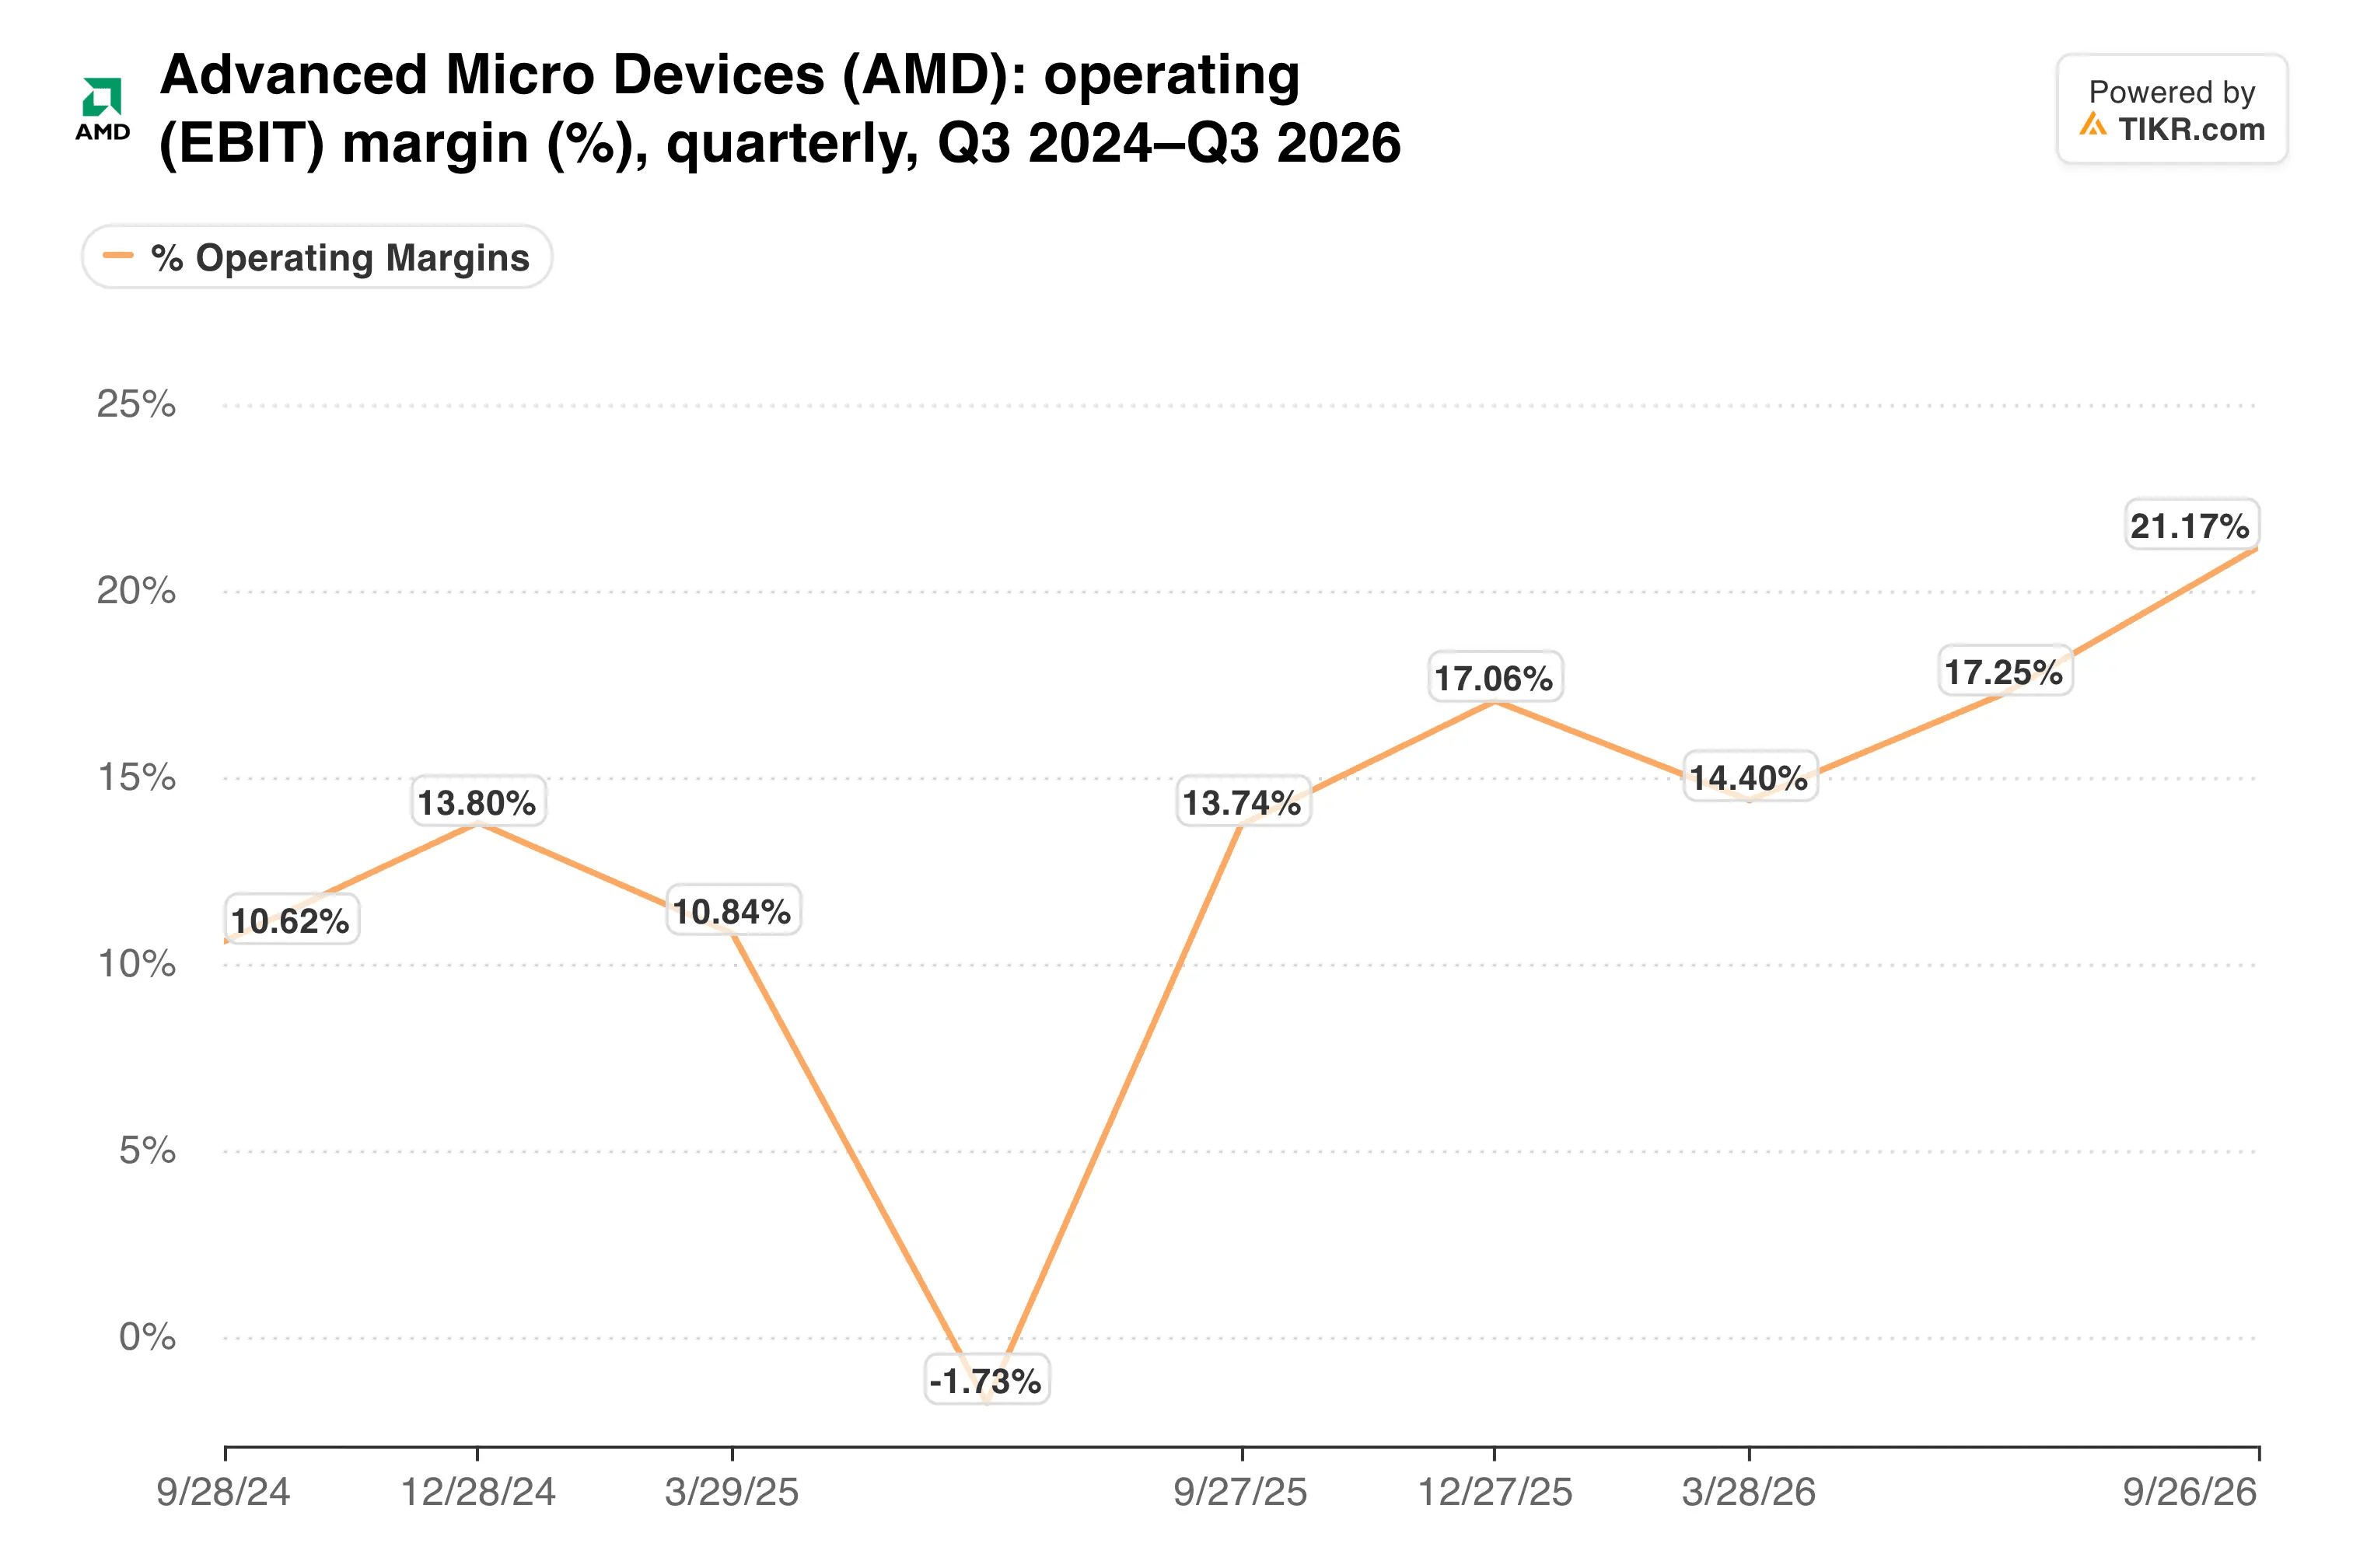
GAAP operating margin reached 21%, up from 14% a year earlier.
My take: I think Su had a point. A 17% drop after 97% Data Center growth looked like the market dumping AI exposure wholesale. Monday’s rebound showed how quickly that mood can reverse. Still, the stock carries a premium multiple, so a Helios delay or a weaker margin could spark another violent day.
The next checkpoint is the fourth-quarter report, expected in early February. It will show whether Helios and Venice delivered about $17 billion in revenue. It will also show whether Su still stands behind 80% growth for 2027.
So what is Advanced Micro Devices stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Advanced Micro Devices could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!