


Key Takeaways
- Cathie Wood’s ARK Invest and 14 other big funds bought Broadcom stock in the third quarter, according to their 13F filings.
- Broadcom trades at 19x forward earnings, well below its five-year average of 24x, while analysts expect its earnings per share to more than quadruple from fiscal 2025 to fiscal 2028.
- The main risk is Anthropic and OpenAI, which carry most of Broadcom’s growth outlook and lean on its balance sheet for financing.
- Broadcom looks like a bargain at today’s price, and its report in early December is the next test.
Cathie Wood’s ARK Invest owned 92% more Broadcom (AVGO) shares on Sept. 30 than on June 30, and 14 other big funds opened or added to positions too. Most of them also hold NVIDIA (NVDA), and Broadcom has held up far better since: it’s down 5% since Sept. 30, against 32% for NVIDIA.
Those figures come from the 13Fs the funds filed between Nov. 3 and Nov. 16 for the quarter ended Sept. 30. Broadcom closed at $333.40, 33% below its June 2 high of $481.57, so most of that fall came before the quarter ended.
GQG made the biggest add
ARK’s 782,119 shares were worth $275 million at the end of September. That’s 1.6% of its 13F stocks, at a firm that manages $17.37 billion. GQG Partners, which manages $163.9 billion, went further: it raised its stake more than fivefold, to 2.09 million shares worth $732 million. Farallon Capital Management added 21%, to 1.40 million shares worth $490 million. Comgest Global Investors nearly quadrupled its position, and two smaller funds, Mane Global Capital Management and Patient Capital Management, bought Broadcom for the first time.
For a few funds it’s a big bet. Broadcom is 8.6% of Tensor Edge Capital’s 13F stocks and 6.4% of RDST Capital’s. Fernbridge Capital Management added 53% to its Broadcom stake and sold all 193,818 of its NVIDIA shares. A 13F shows only what a fund held on the quarter’s last day, so none of this tells us what the funds paid.
TIKR tracks 51 analysts on Broadcom. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Broadcom, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Broadcom’s Analyst Ratings
Wall Street expects a lot more earnings
Analysts expect Broadcom’s normalized earnings per share to more than quadruple, from $6.82 in fiscal 2025 to $30.53 in fiscal 2028:
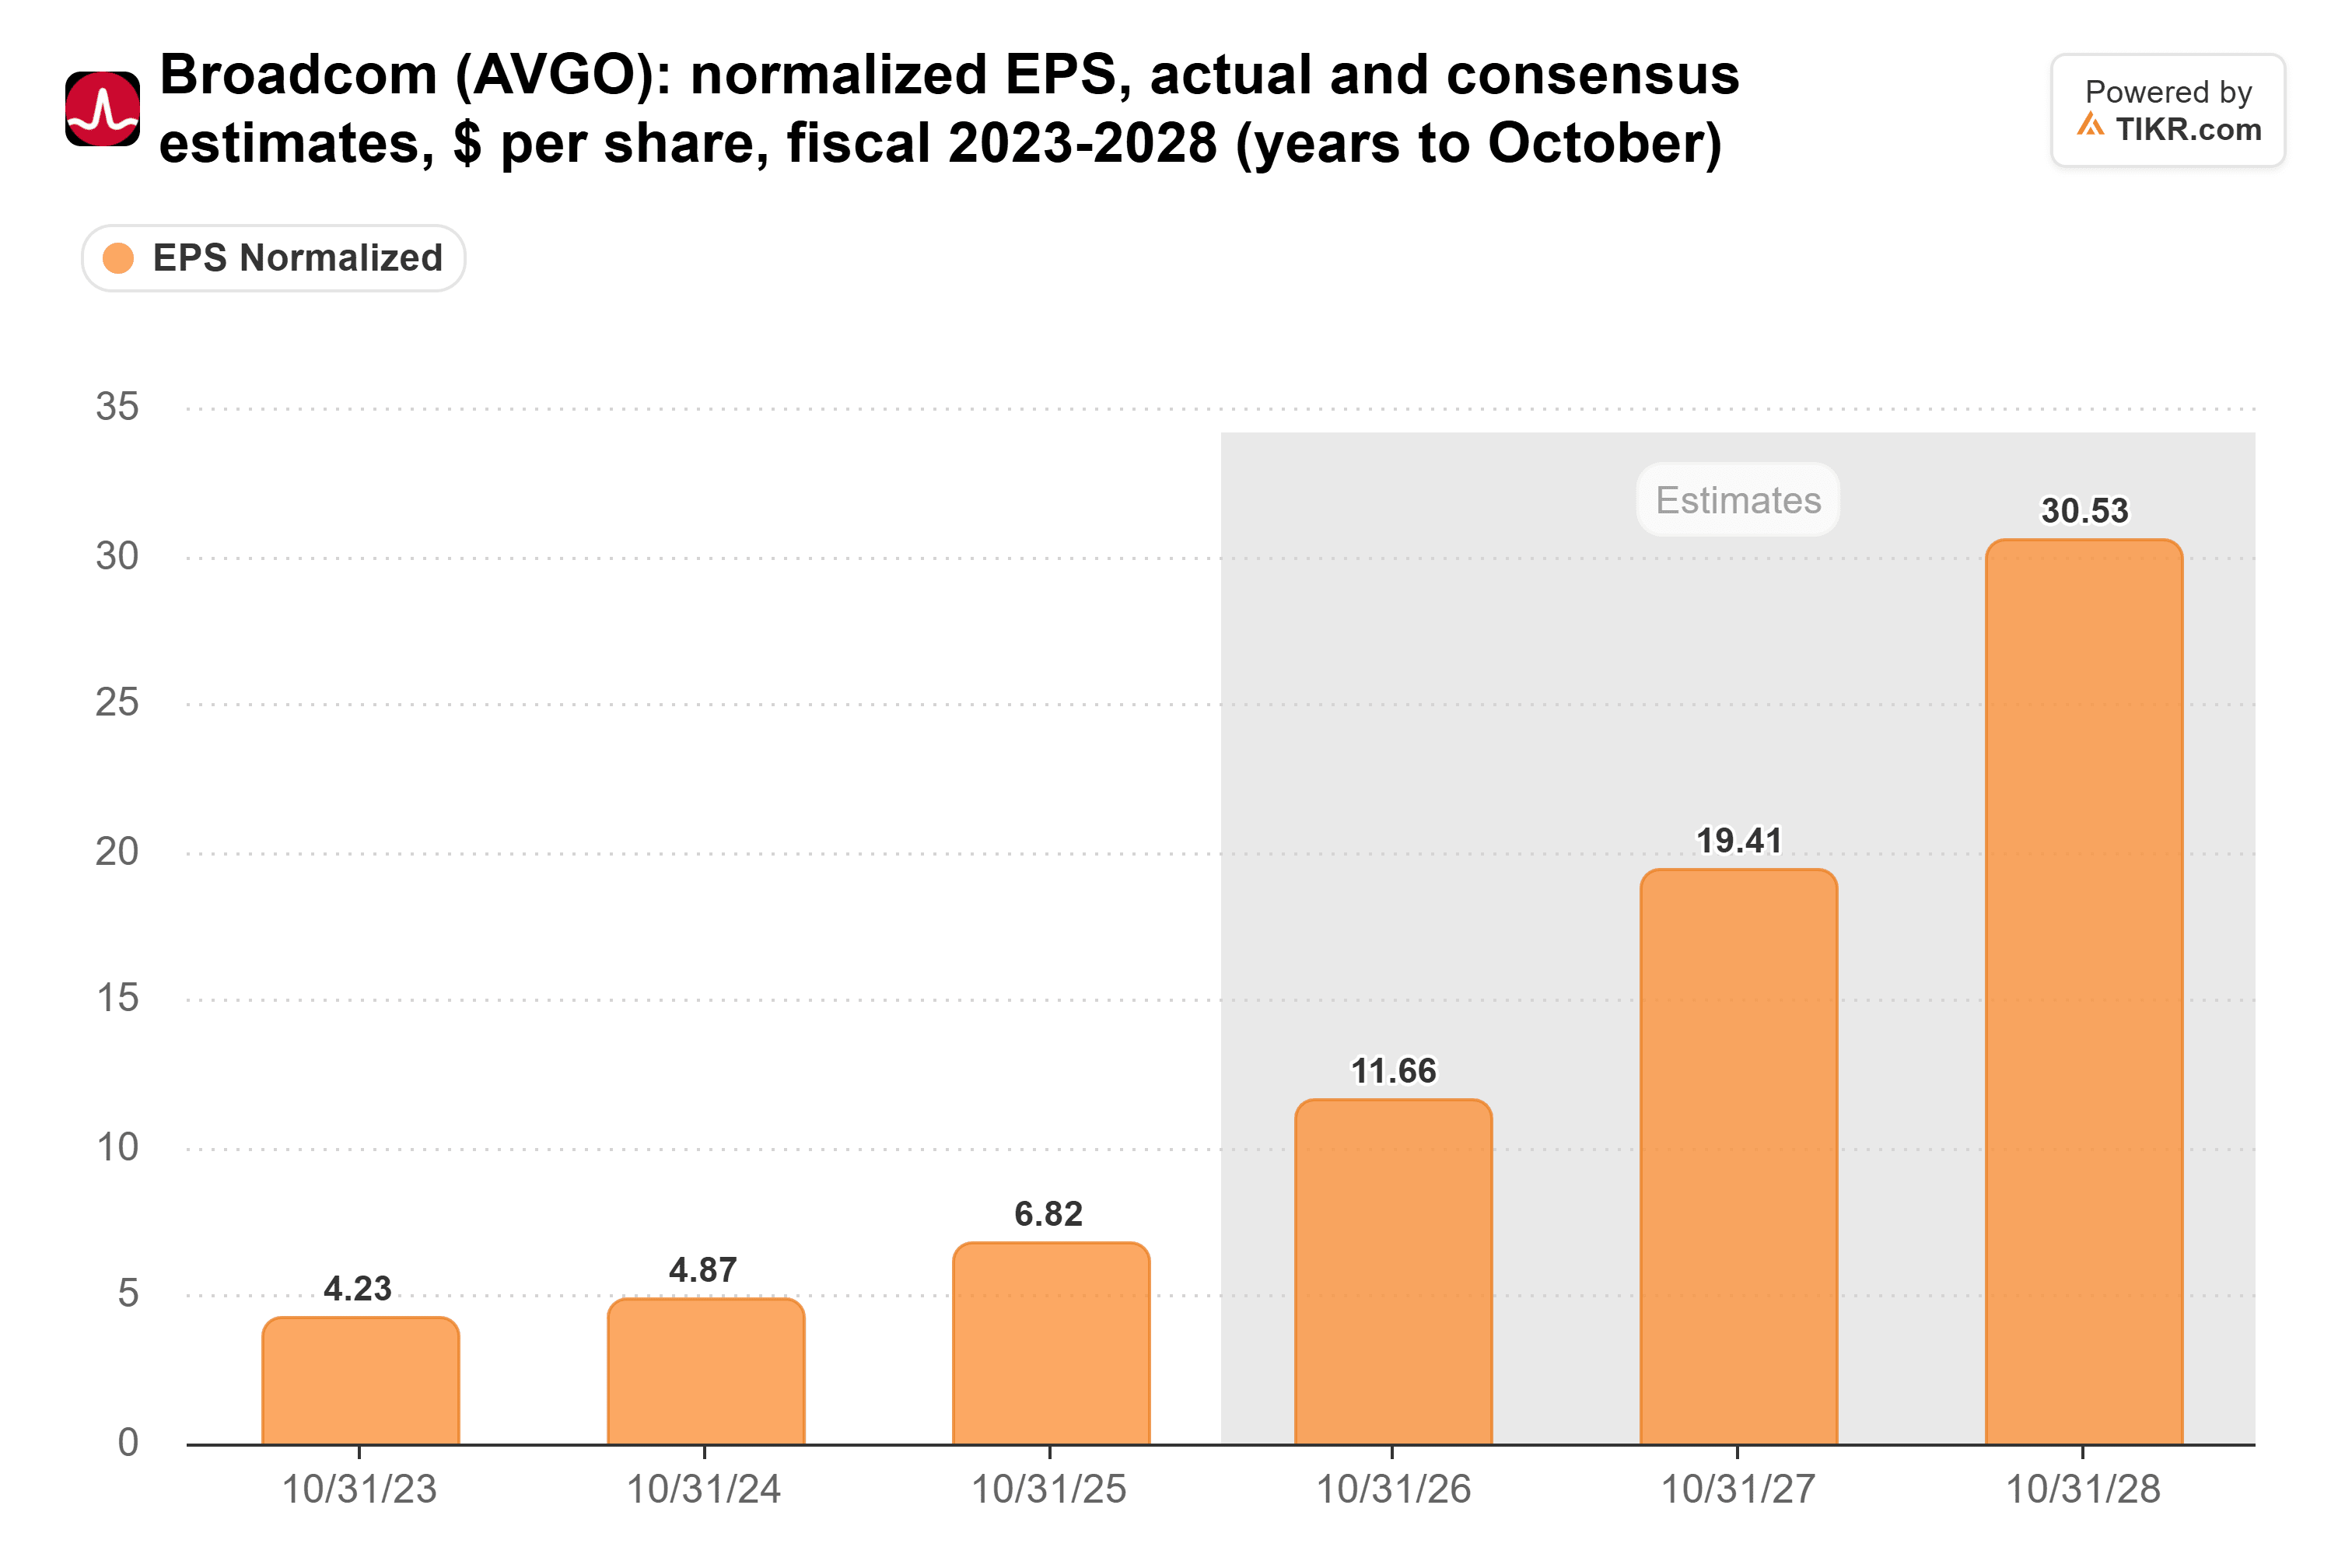
Those estimates build on management’s AI outlook: $58 billion of AI chip revenue in fiscal 2026, about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. Broadcom has beaten its AI revenue guidance in each of the last three quarters. Most recently it reported $16.7 billion in the quarter ended Aug. 2, up 221% from a year earlier. Its backlog of committed contracts reached $179.2 billion at Aug. 2, up from $33.3 billion nine months earlier, and analysts have more than doubled their fiscal 2028 EPS estimate over the past year.
Even so, the stock trades at 19x forward earnings, well below its five-year average of 24x:
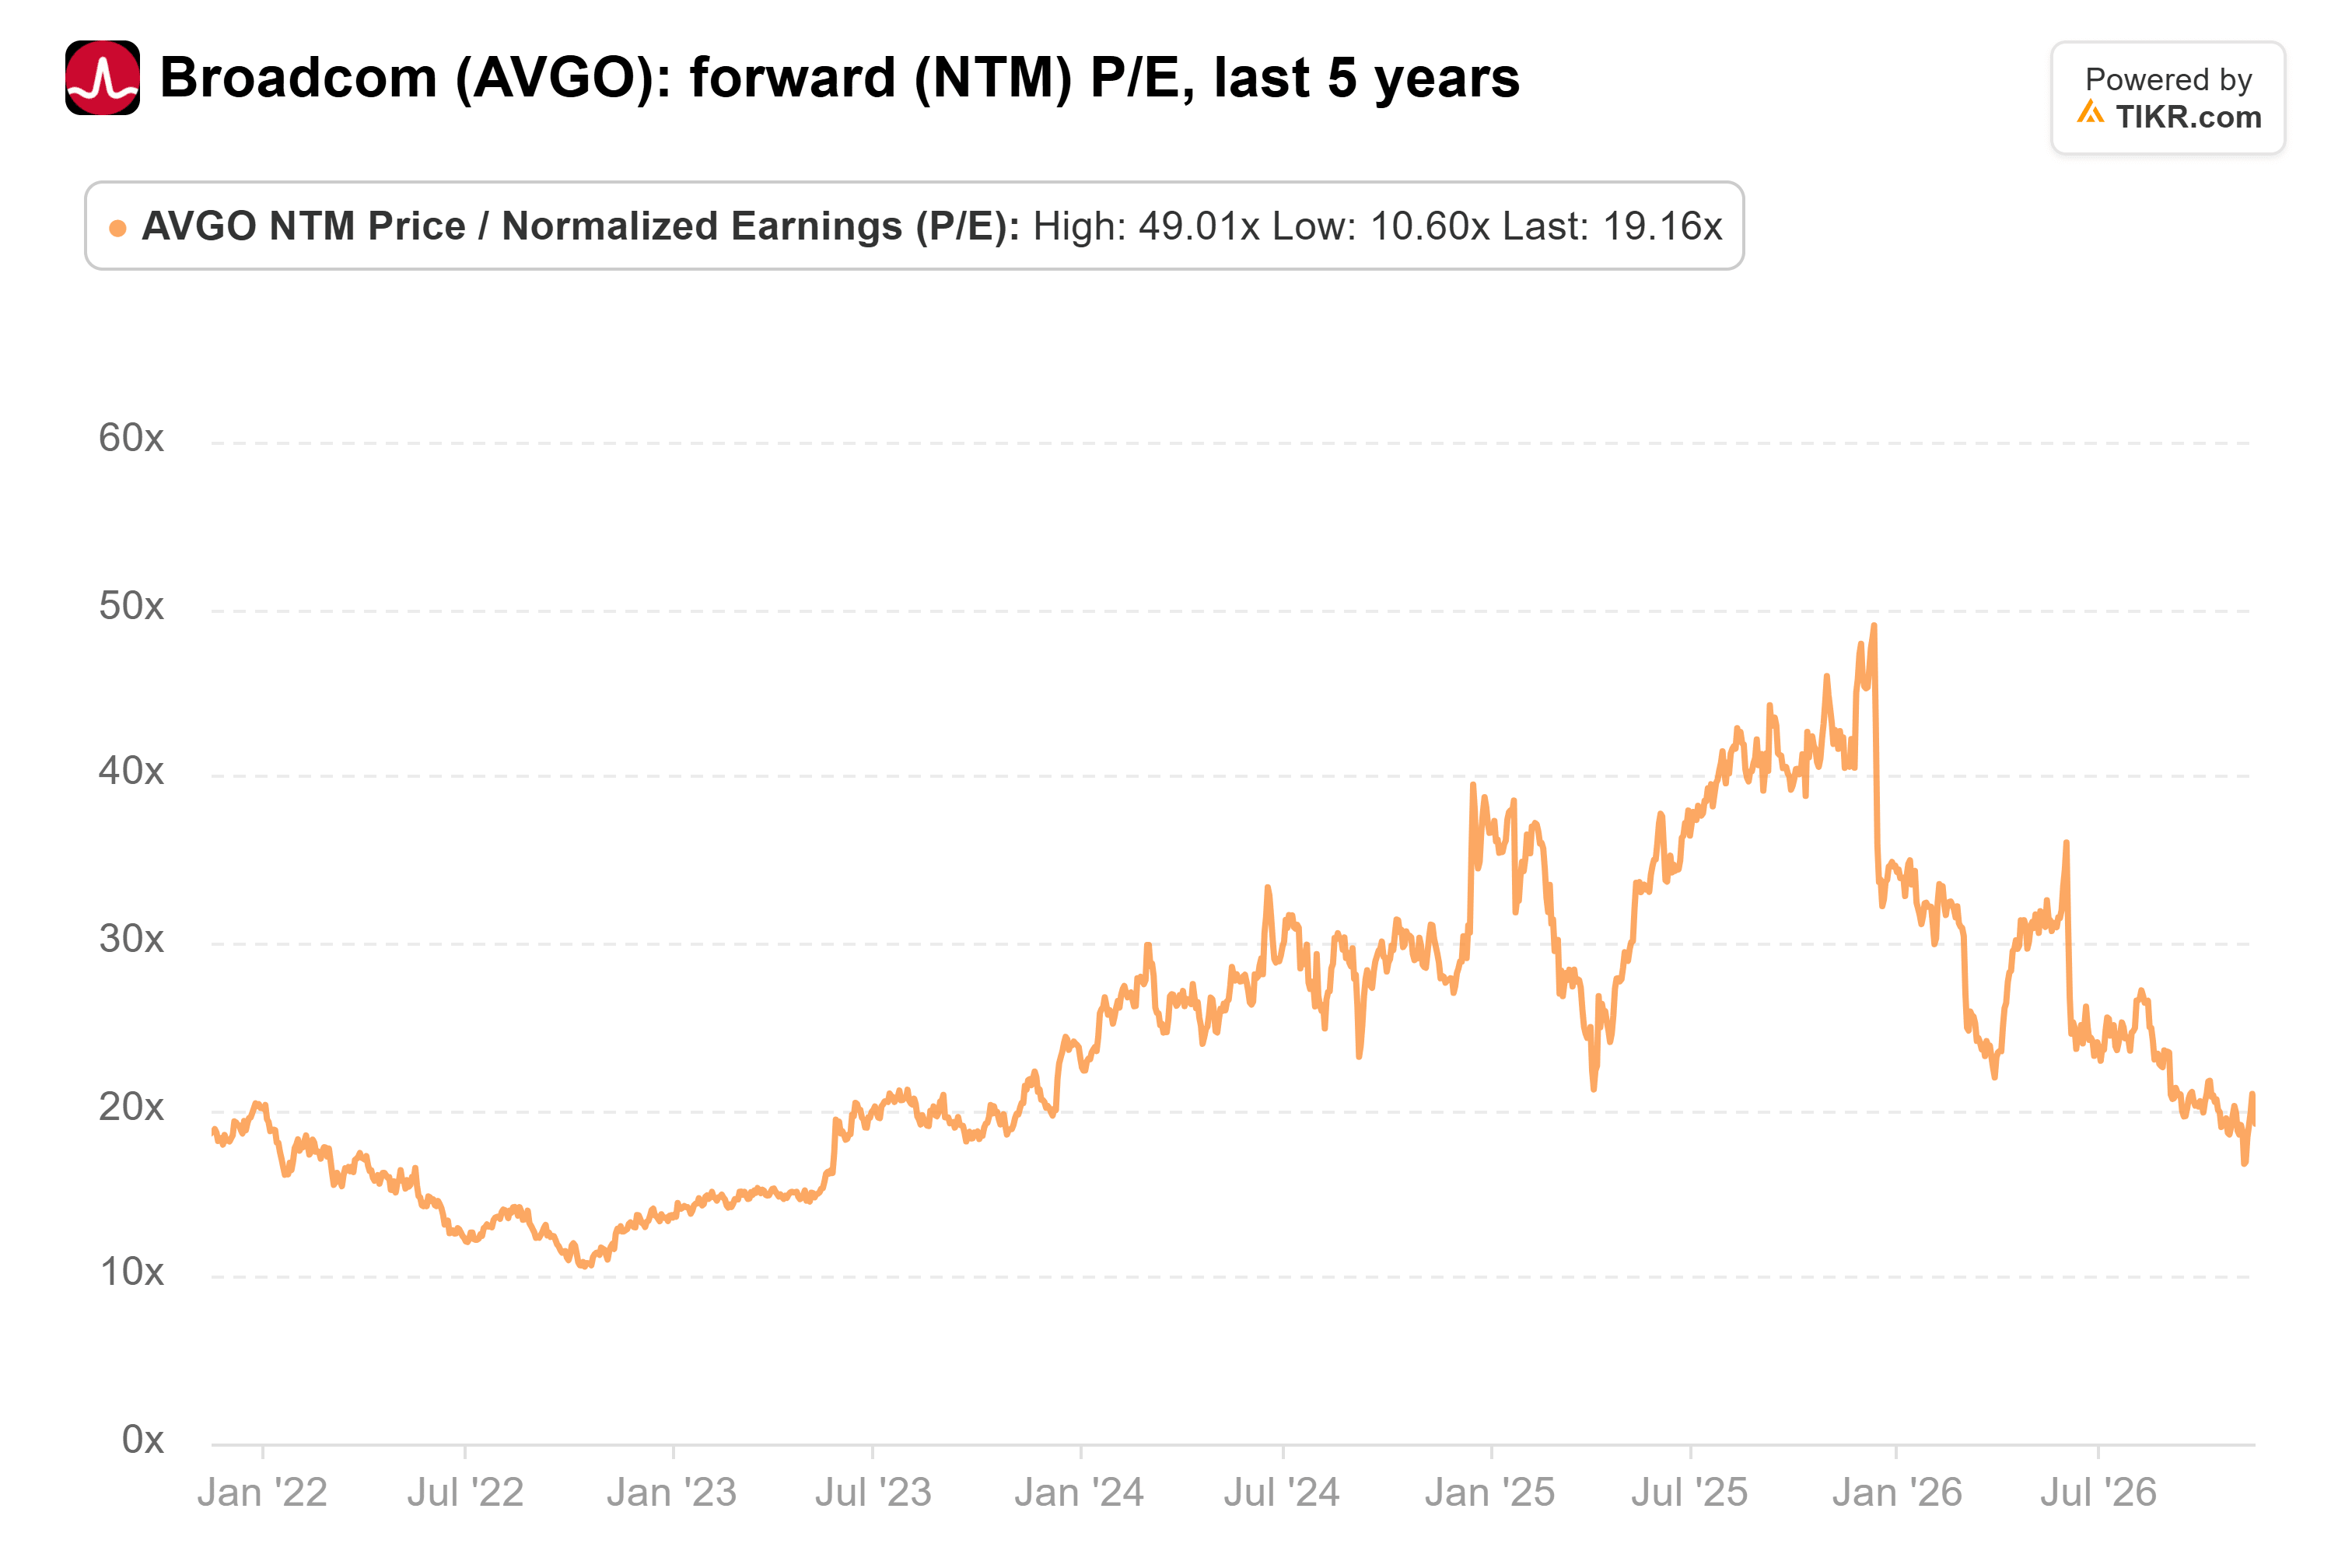
(It traded at 49x as recently as December 2025.)
Analysts’ average price target has climbed over the past year, to $528 from $396:
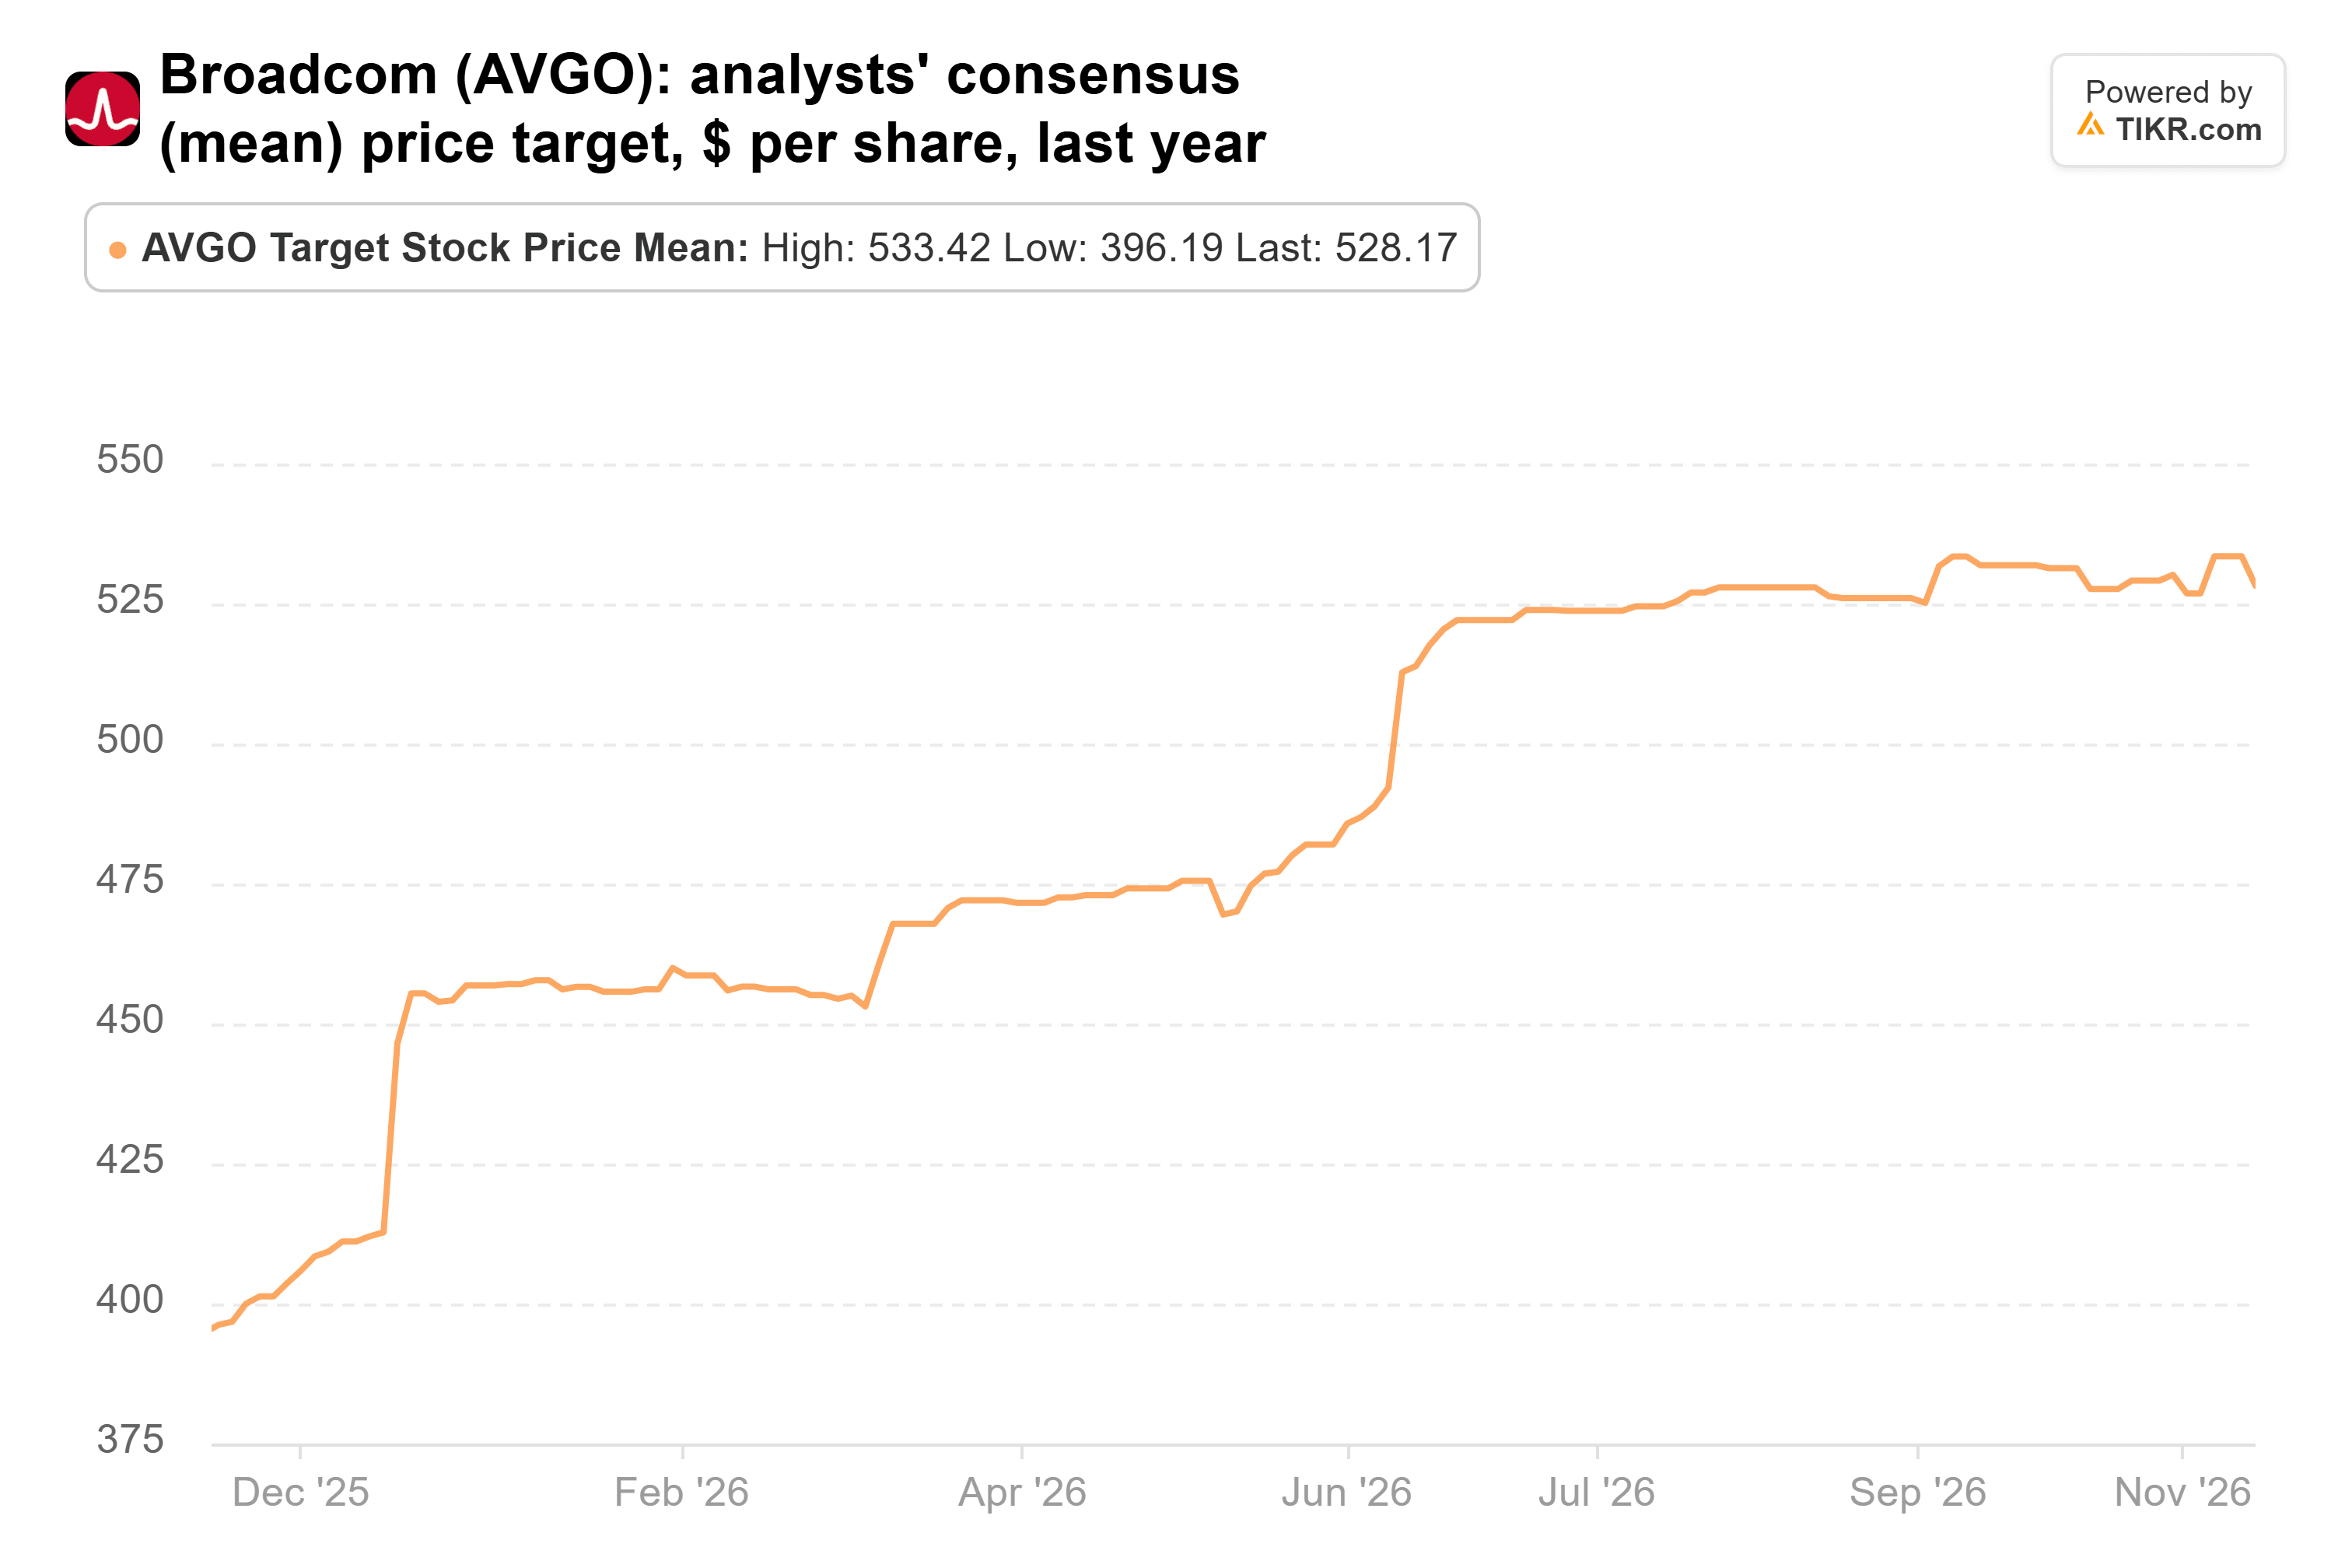
Over the same year, the stock slipped to $333.40 from $342.65. The $528 average target from the 51 analysts covering Broadcom is 58% above the last close. Even the Street’s lowest target, $398, is above it.
The catch is Anthropic
The risk is two customers. Management’s outlines put at least 21 of the roughly 30 gigawatts of AI capacity it sees across fiscal 2027 and 2028 with Anthropic and OpenAI. CEO Hock Tan says Broadcom’s other four custom-chip customers can fund their own compute, which leaves these two needing help.
So Broadcom is helping. According to its latest quarterly report, it backstops up to about $29 billion of leases on a financing platform built to pay for the labs’ compute. It may also lend Anthropic up to $42 billion through convertible notes. It held $24.0 billion of cash at Aug. 2.
Rothschild & Co Redburn pointed to exactly that when it downgraded Broadcom to Neutral and cut its target to $398 from $595 on Nov. 13. Redburn argued that the two labs have to beat open models and start paying their own way quickly, and that the payoff will take time. If either lab stalls, Broadcom loses growth and faces its own guarantees in the same year.
I’d call it a bargain
I think the funds are onto something. Broadcom trades well below its usual multiple even as analysts keep raising their estimates, and management keeps beating its own AI guidance. If fiscal 2027 earnings land anywhere near the $19.41 consensus, $333 is cheap for this business.
But with that much riding on Anthropic, I wouldn’t call it a sure thing. NVIDIA’s report this week gives the first read on AI chip demand, and Broadcom’s own report in early December is the bigger one: I’d want to hear management repeat its roughly $115 billion AI outlook for fiscal 2027. Anthropic’s IPO matters too, since a successful listing would ease the pressure on the financing Broadcom stands behind.
So what is Broadcom stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Broadcom could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


