Key Takeaways
- Bank of America cut its Snowflake price target to $400 from $470 on Nov. 20 and kept its Buy rating, leaving 56% upside.
- Datadog guided its fourth quarter flat, and MongoDB reports on Dec. 1, the day before Snowflake.
- On consensus earnings for the year ending January 2029, $400 is 92x, a lower multiple than the 106x Snowflake trades at now.
- The target looks within reach, but those adjusted earnings leave out stock pay, so dilution is the risk to watch.
Snowflake (SNOW) is down 33% from its September high, and Bank of America is still betting on a rebound ahead of its Dec. 2 report. On Nov. 20, analyst Koji Ikeda kept his Buy rating but cut his target to $400 from $470, still 56% above the share price.
The call comes between two peer reports. Datadog (DDOG), which also bills by usage, guided its fourth quarter flat on Nov. 4, and MongoDB (MDB), a rival for the same AI data budgets, reports on Dec. 1.
No bad news from Snowflake itself
Snowflake’s last report, on Sept. 2, showed product revenue growth speeding up for a third straight quarter, to 37%, and raised the full-year guide to 36% growth. The soft spot was the backlog: remaining performance obligations fell to $9.00 billion at July 31 from $9.77 billion in January.
Then on Nov. 4, Datadog grew third-quarter revenue 35% to $1.20 billion but guided the fourth quarter to $1.19 billion to $1.20 billion, after its largest customer cut its usage. Snowflake’s customer base looks different: CEO Sridhar Ramaswamy said on the second-quarter call that AI-native companies “continue to be a small part of our overall revenue stream.”
BofA trimmed, but it’s still a buyer
BofA’s cut follows UBS’s to $450 from $500 on Nov. 18, though UBS said partner and customer checks point to healthy adoption of CoCo, Snowflake’s AI agent for builders. Evercore ISI went the other way on Nov. 12, raising its target to $430 from $360. That leaves BofA’s target 8% below the $433 consensus.
TIKR tracks 51 analysts on Snowflake. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Snowflake, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Snowflake’s Analyst Ratings
Does $400 add up?
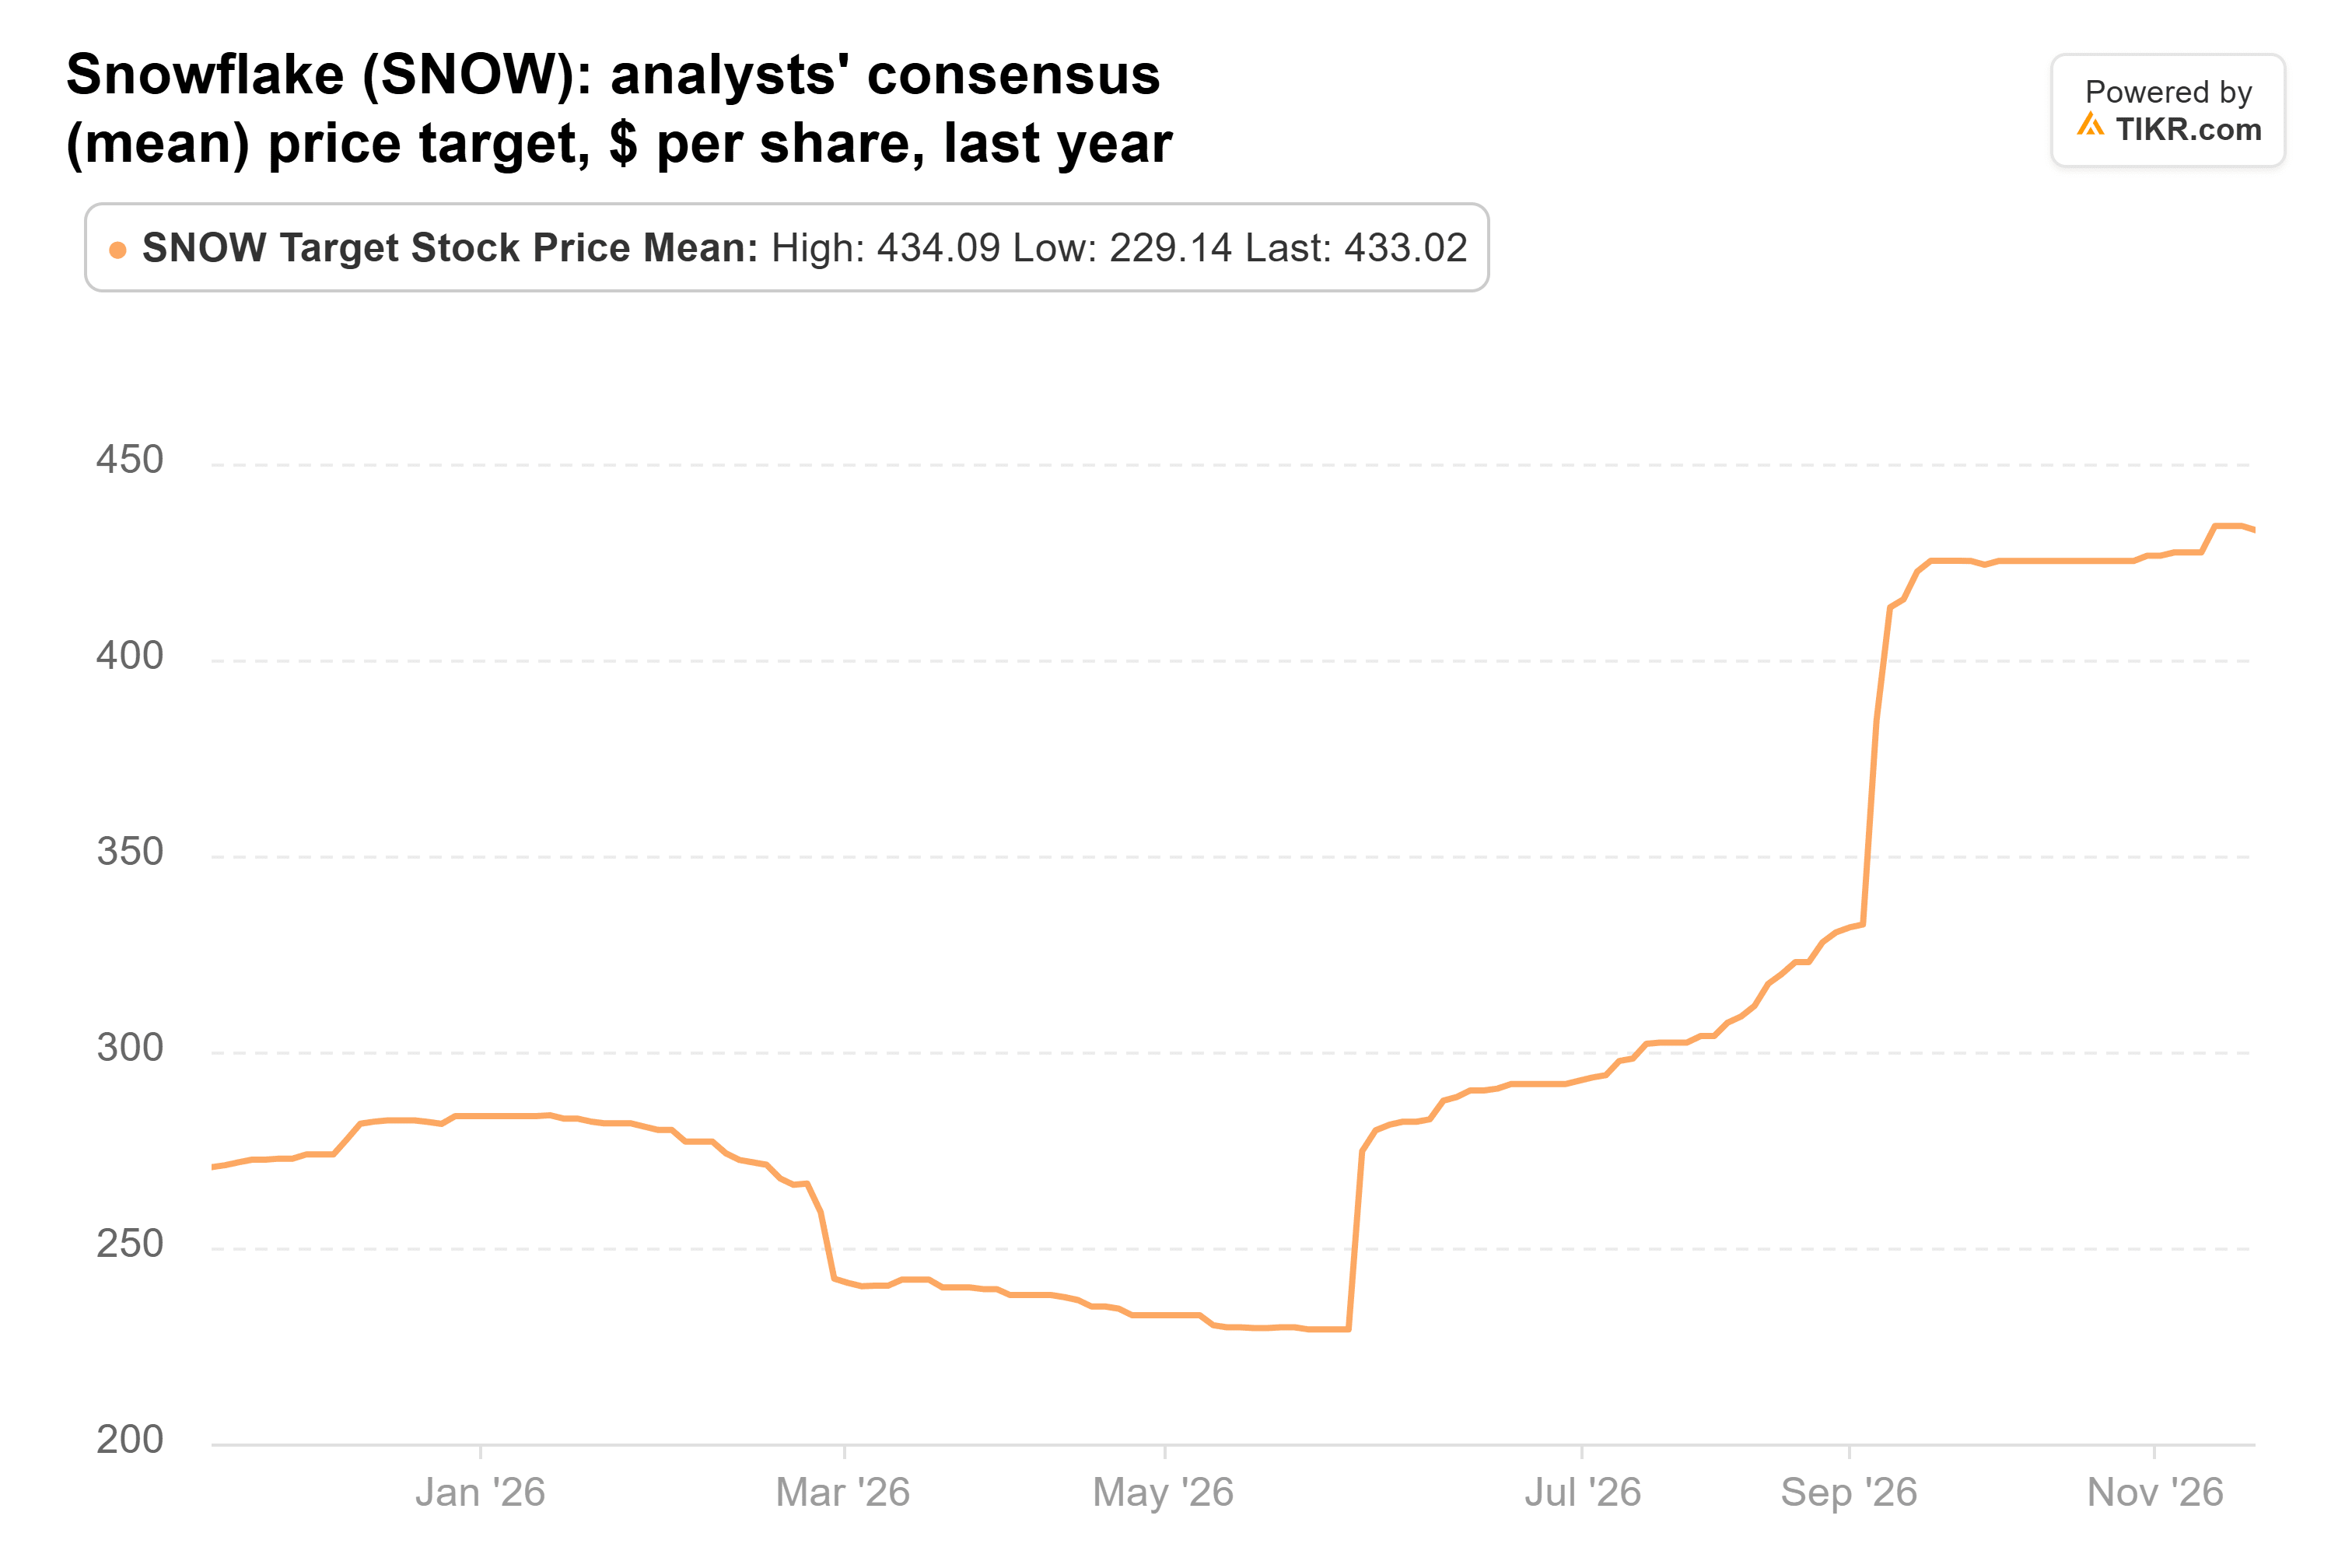
The Street’s average target has climbed from $271 a year ago to $433, and even the lowest target, $280, sits above the $257 share price.
Consensus adjusted EPS for the year ending January 2027 is $2.23, up from $1.94 three months ago, and analysts see it reaching $4.33 in the year ending January 2029:
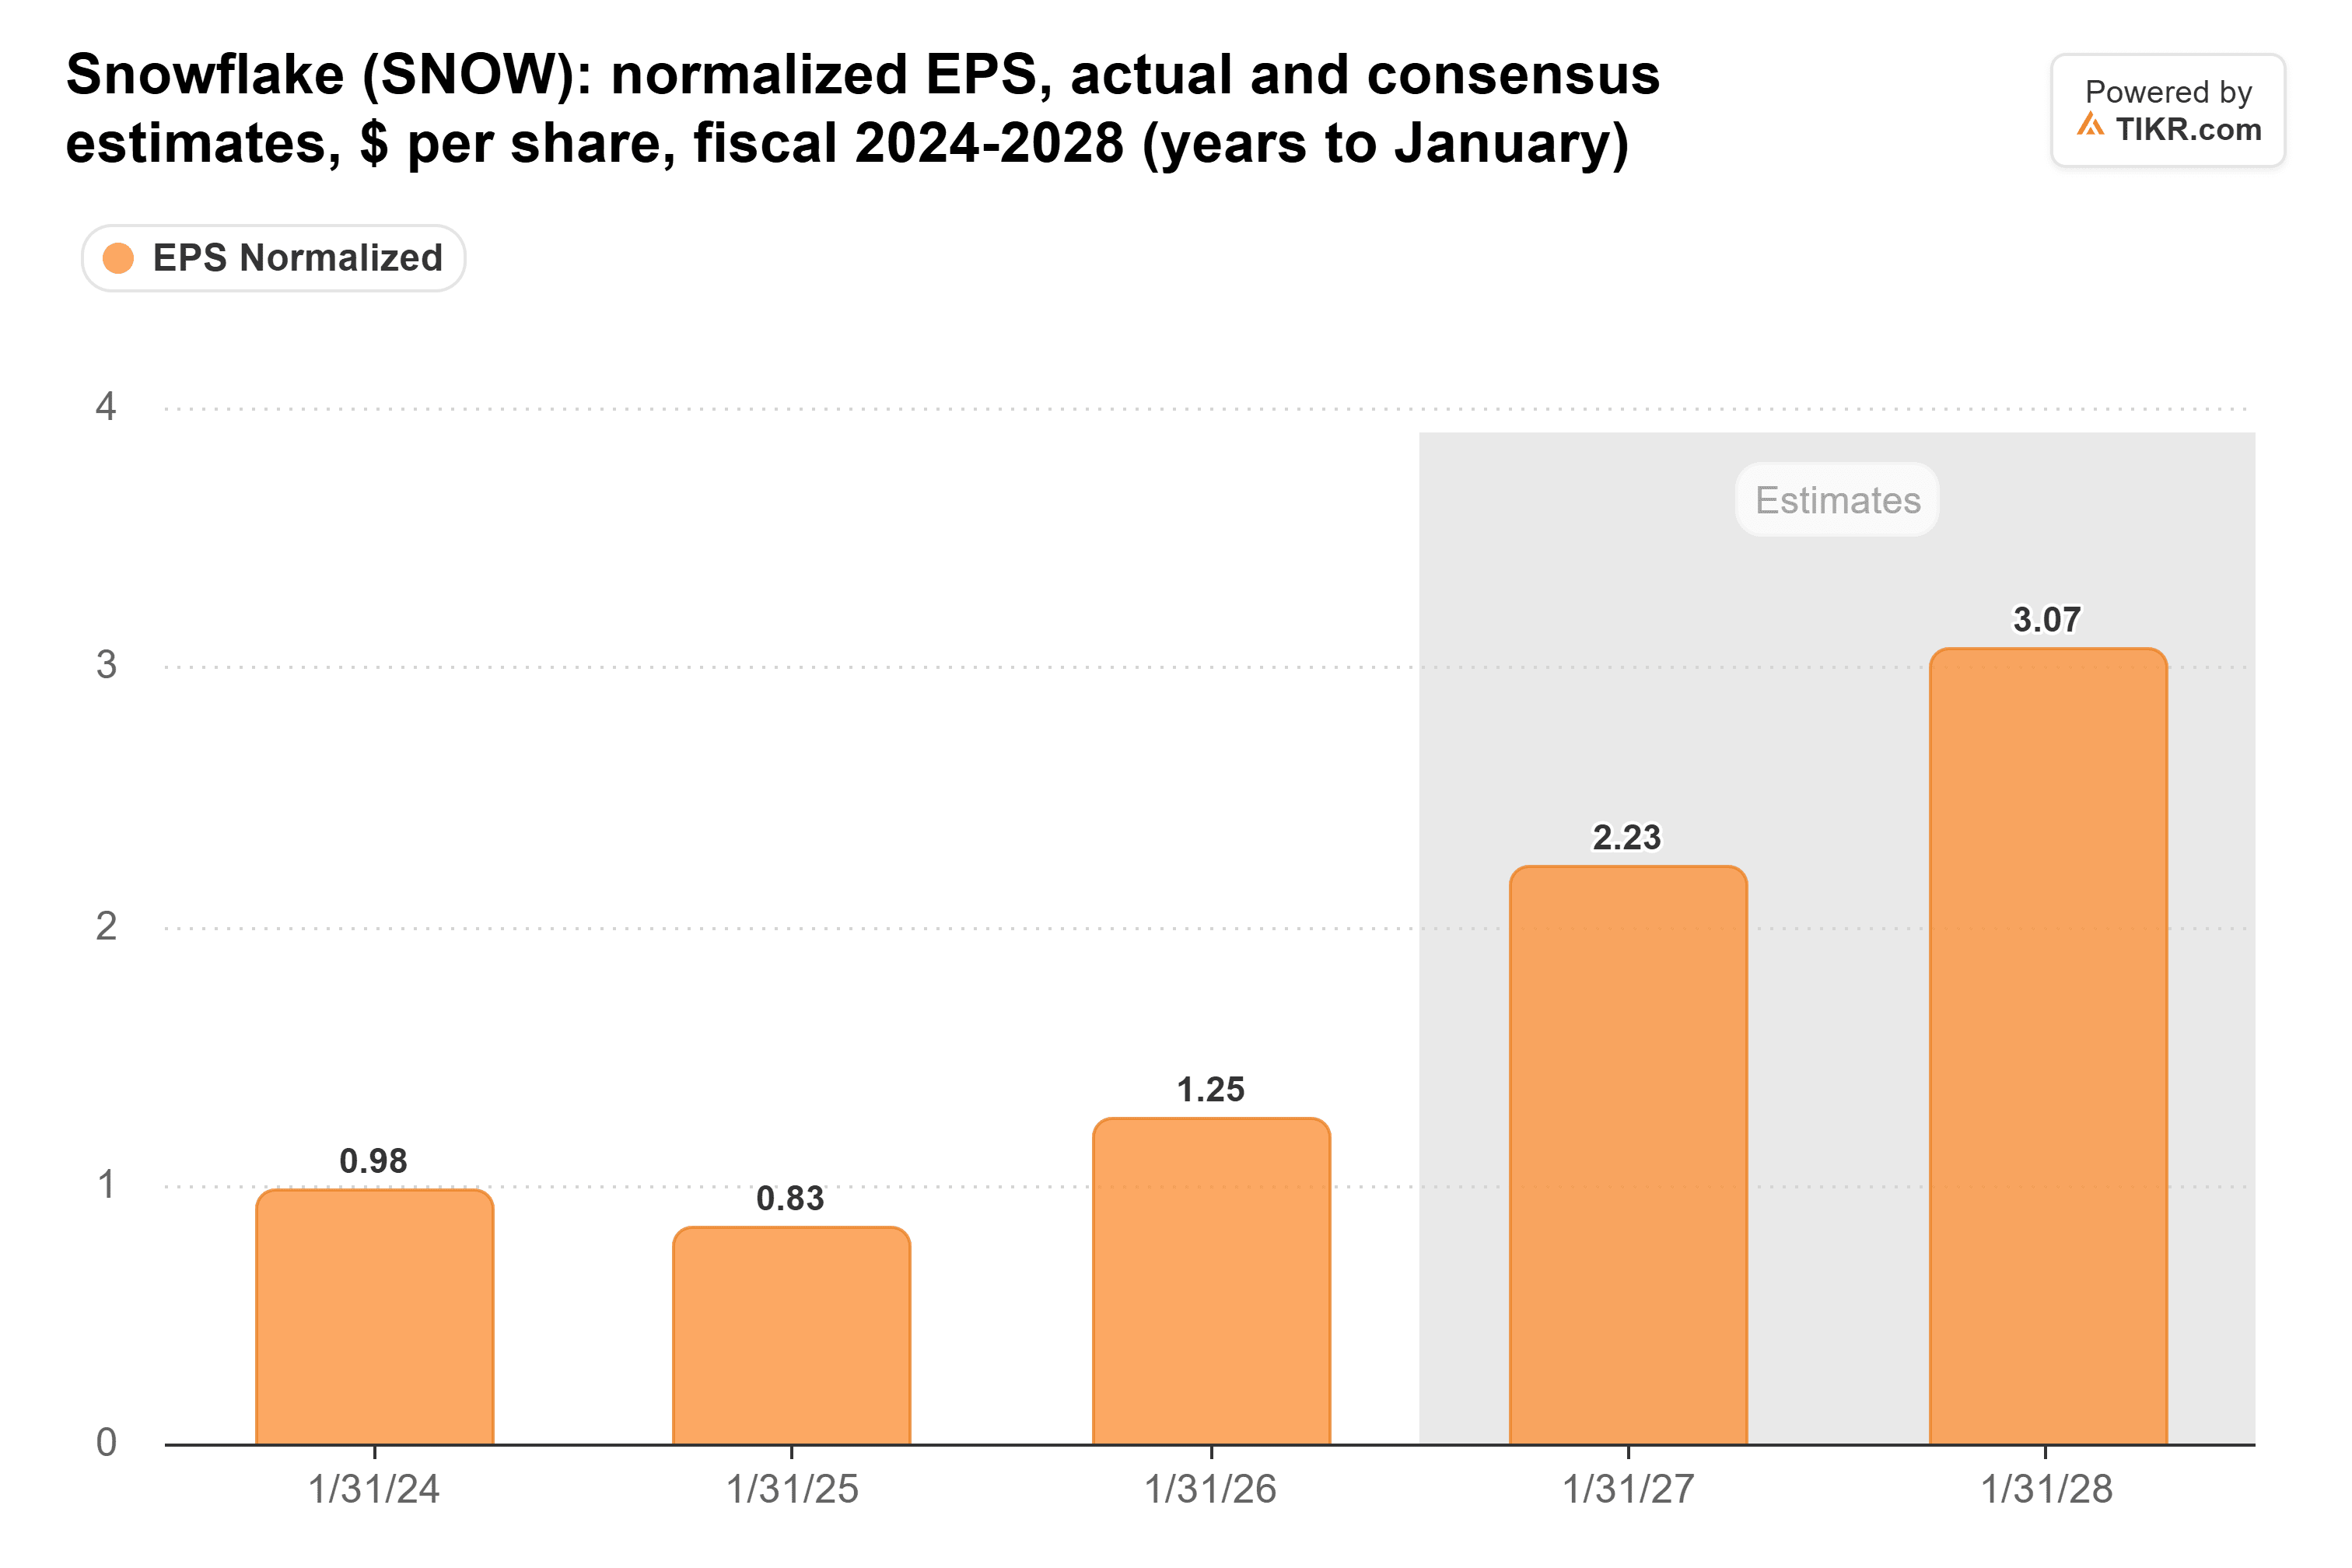
BofA hasn’t published its math, but on mine, $400 is 92x that $4.33, below the 106x the stock closed at on Nov. 19 and its three-year average of 165x. So the target needs earnings to grow 71%, with room for the multiple to shrink 13%.
Stock pay is the catch
Those adjusted earnings leave out stock pay, 34% of revenue in the year ended January 2026. Diluted shares rose to 349.26 million in the second quarter from 335.22 million a year earlier, and consensus GAAP EPS stays negative through fiscal 2029. Management targets stock pay at 27% of revenue this fiscal year and a GAAP profit in the fourth quarter of fiscal 2028.
So BofA’s $400 is within reach on the Street’s own estimates, and I’d side with the call. What I’d watch is how much of that growth reaches each share. MongoDB, which grew July-quarter revenue 30% to $771.8 million, reports first. Then Snowflake needs product revenue above its $1,588 million to $1,593 million guide and backlog above $9.00 billion, with stock pay tracking toward that 27%.
So what is Snowflake stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Snowflake could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!