


Key Takeaways
- Pfizer yields 6.3% and General Mills 7.7%, and both say they’ll hold their dividends at today’s rate for now.
- Pfizer’s dividend took 89% of its free cash flow over the last twelve months, and General Mills’s took 85%.
- General Mills’s net debt is 3.7x EBITDA, above its 3x target, against 2.0x at Pfizer.
- $10,000 pays $770 a year in General Mills dividends today and $630 in Pfizer dividends.
Any income investor hunting for yields above 6% is going to run into Pfizer (PFE) and General Mills (GIS). Pfizer yields 6.3% and General Mills 7.7%, as of Oct. 9, 2026, after General Mills’s stock fell almost 22% in September.
In its Sept. 23 earnings remarks, General Mills said it would hold its payout at the current rate while it pays down debt. In August, Pfizer’s CEO said its dividend will be maintained and will start growing again once its patent losses are behind it.
So with both raises on hold, which high-yield dividend is the better one to own?
| Metric | Pfizer (PFE) | General Mills (GIS) |
|---|---|---|
| Dividend yield | 6.3% | 7.7% |
| Annual dividend | $1.72 | $2.44 |
| Dividend growth, 5 years | 2.5% a year (fiscal 2020–2025) | 3.9% a year (fiscal 2021–2026) |
| Cash dividend payout ratio (TTM) | 89% (to June 28, 2026) | 85% (to Aug. 30, 2026) |
| Net debt/EBITDA (LTM) | 1.97x | 3.67x |
| Interest coverage (LTM) | 6.98x | 4.94x |
Pfizer is trading COVID for newer drugs
Pfizer’s sales are shifting from its COVID products to newer drugs. In the second quarter of 2026, revenue rose 3% from the year-earlier quarter to $15.0 billion, and launched and acquired products such as Padcev and Nurtec grew 18% operationally. It also raised its full-year revenue guidance by $500 million at the midpoint, to $60.5 billion to $62.5 billion.
The COVID years still show in the cash behind the dividend.
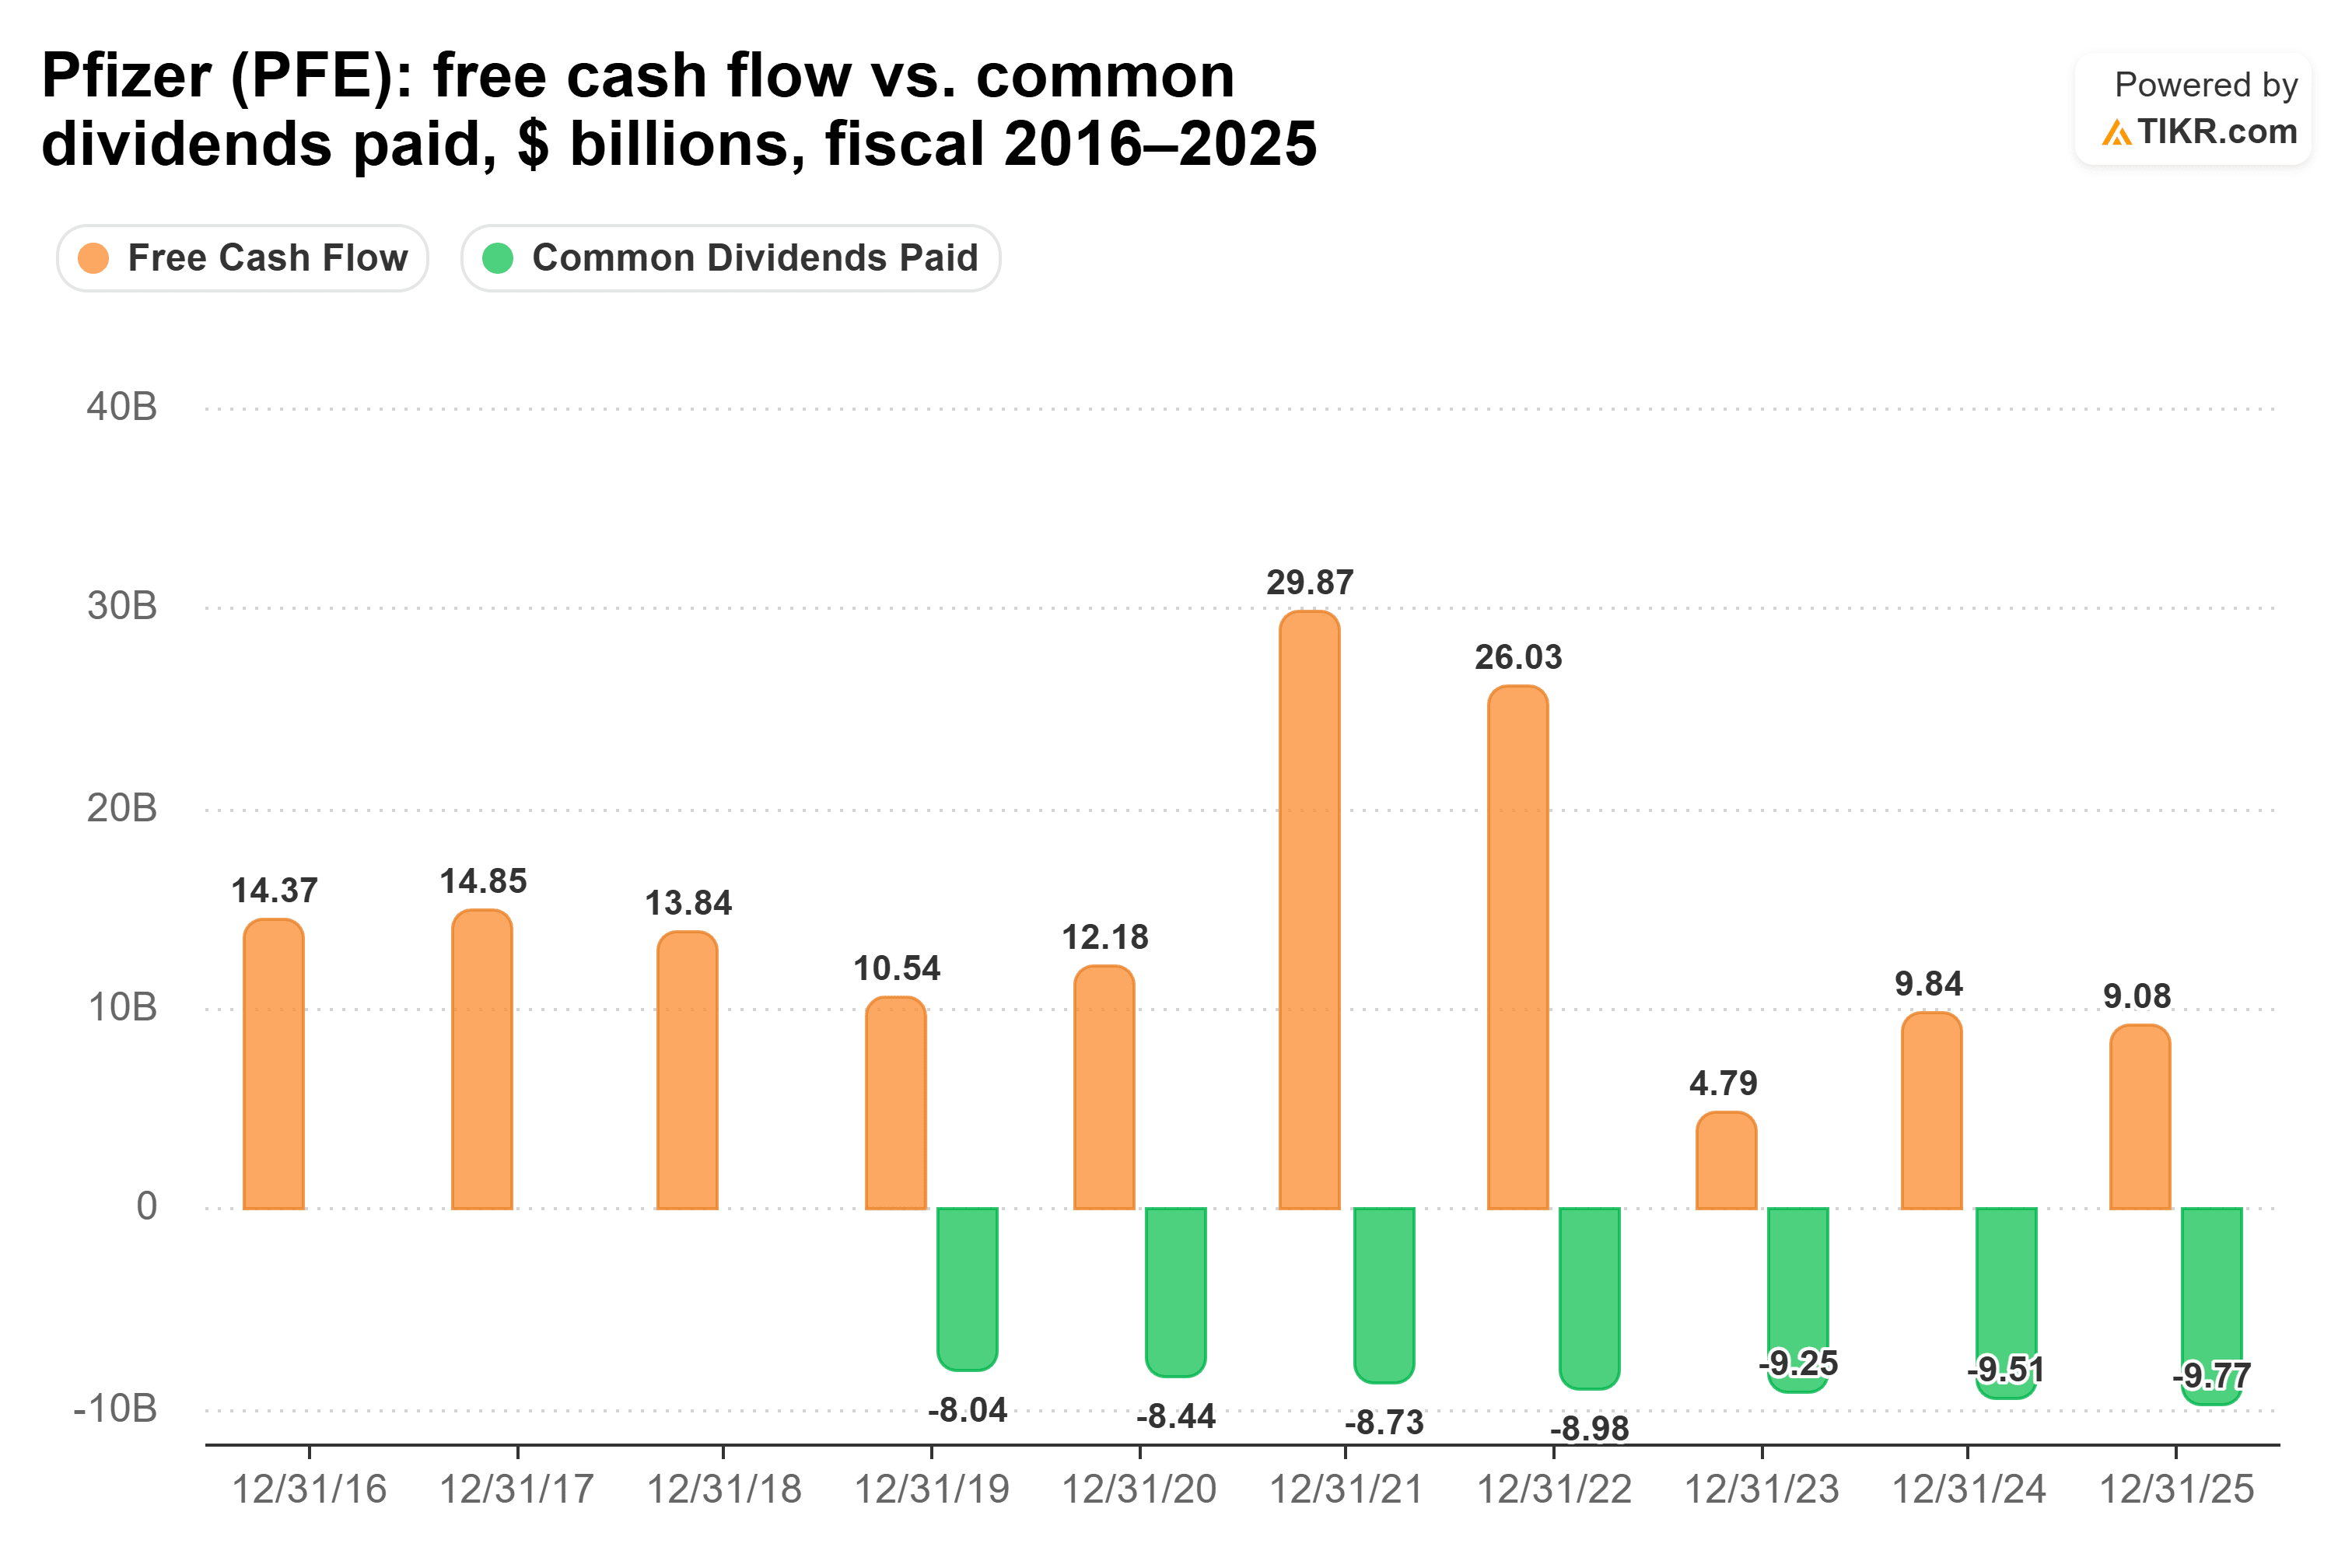
Free cash flow peaked at $29.9 billion in fiscal 2021. In fiscal 2025, $9.08 billion of free cash flow still didn’t cover $9.77 billion of dividends. Over the twelve months to June 28, 2026, the dividend took a tight 89% of free cash flow.
The risk is drugs losing exclusivity, which will weigh on revenue through 2028. Chairman and CEO Albert Bourla said on the August call: “even the most stretched scenarios that we are running, we will be able to maintain our dividend.” Management expects high single-digit yearly revenue growth from the end of 2028 through 2033.
General Mills is paying down debt first
General Mills has its own reason to hold the line, and it sits on the balance sheet.
The business is mixed. In the quarter ended Aug. 30, 2026, net sales were $4.4 billion, down 3% from the year-earlier quarter because of the sale of its U.S. yogurt business, and organic sales were flat. North America Retail fell 3% organically on weak cereal and snacks. For fiscal 2027, the company expects adjusted operating profit to fall 8% to 13% in constant currency, and adjusted EPS of $3.00 to $3.20, against $3.55 in fiscal 2026.
For years, the dividend had plenty of room.
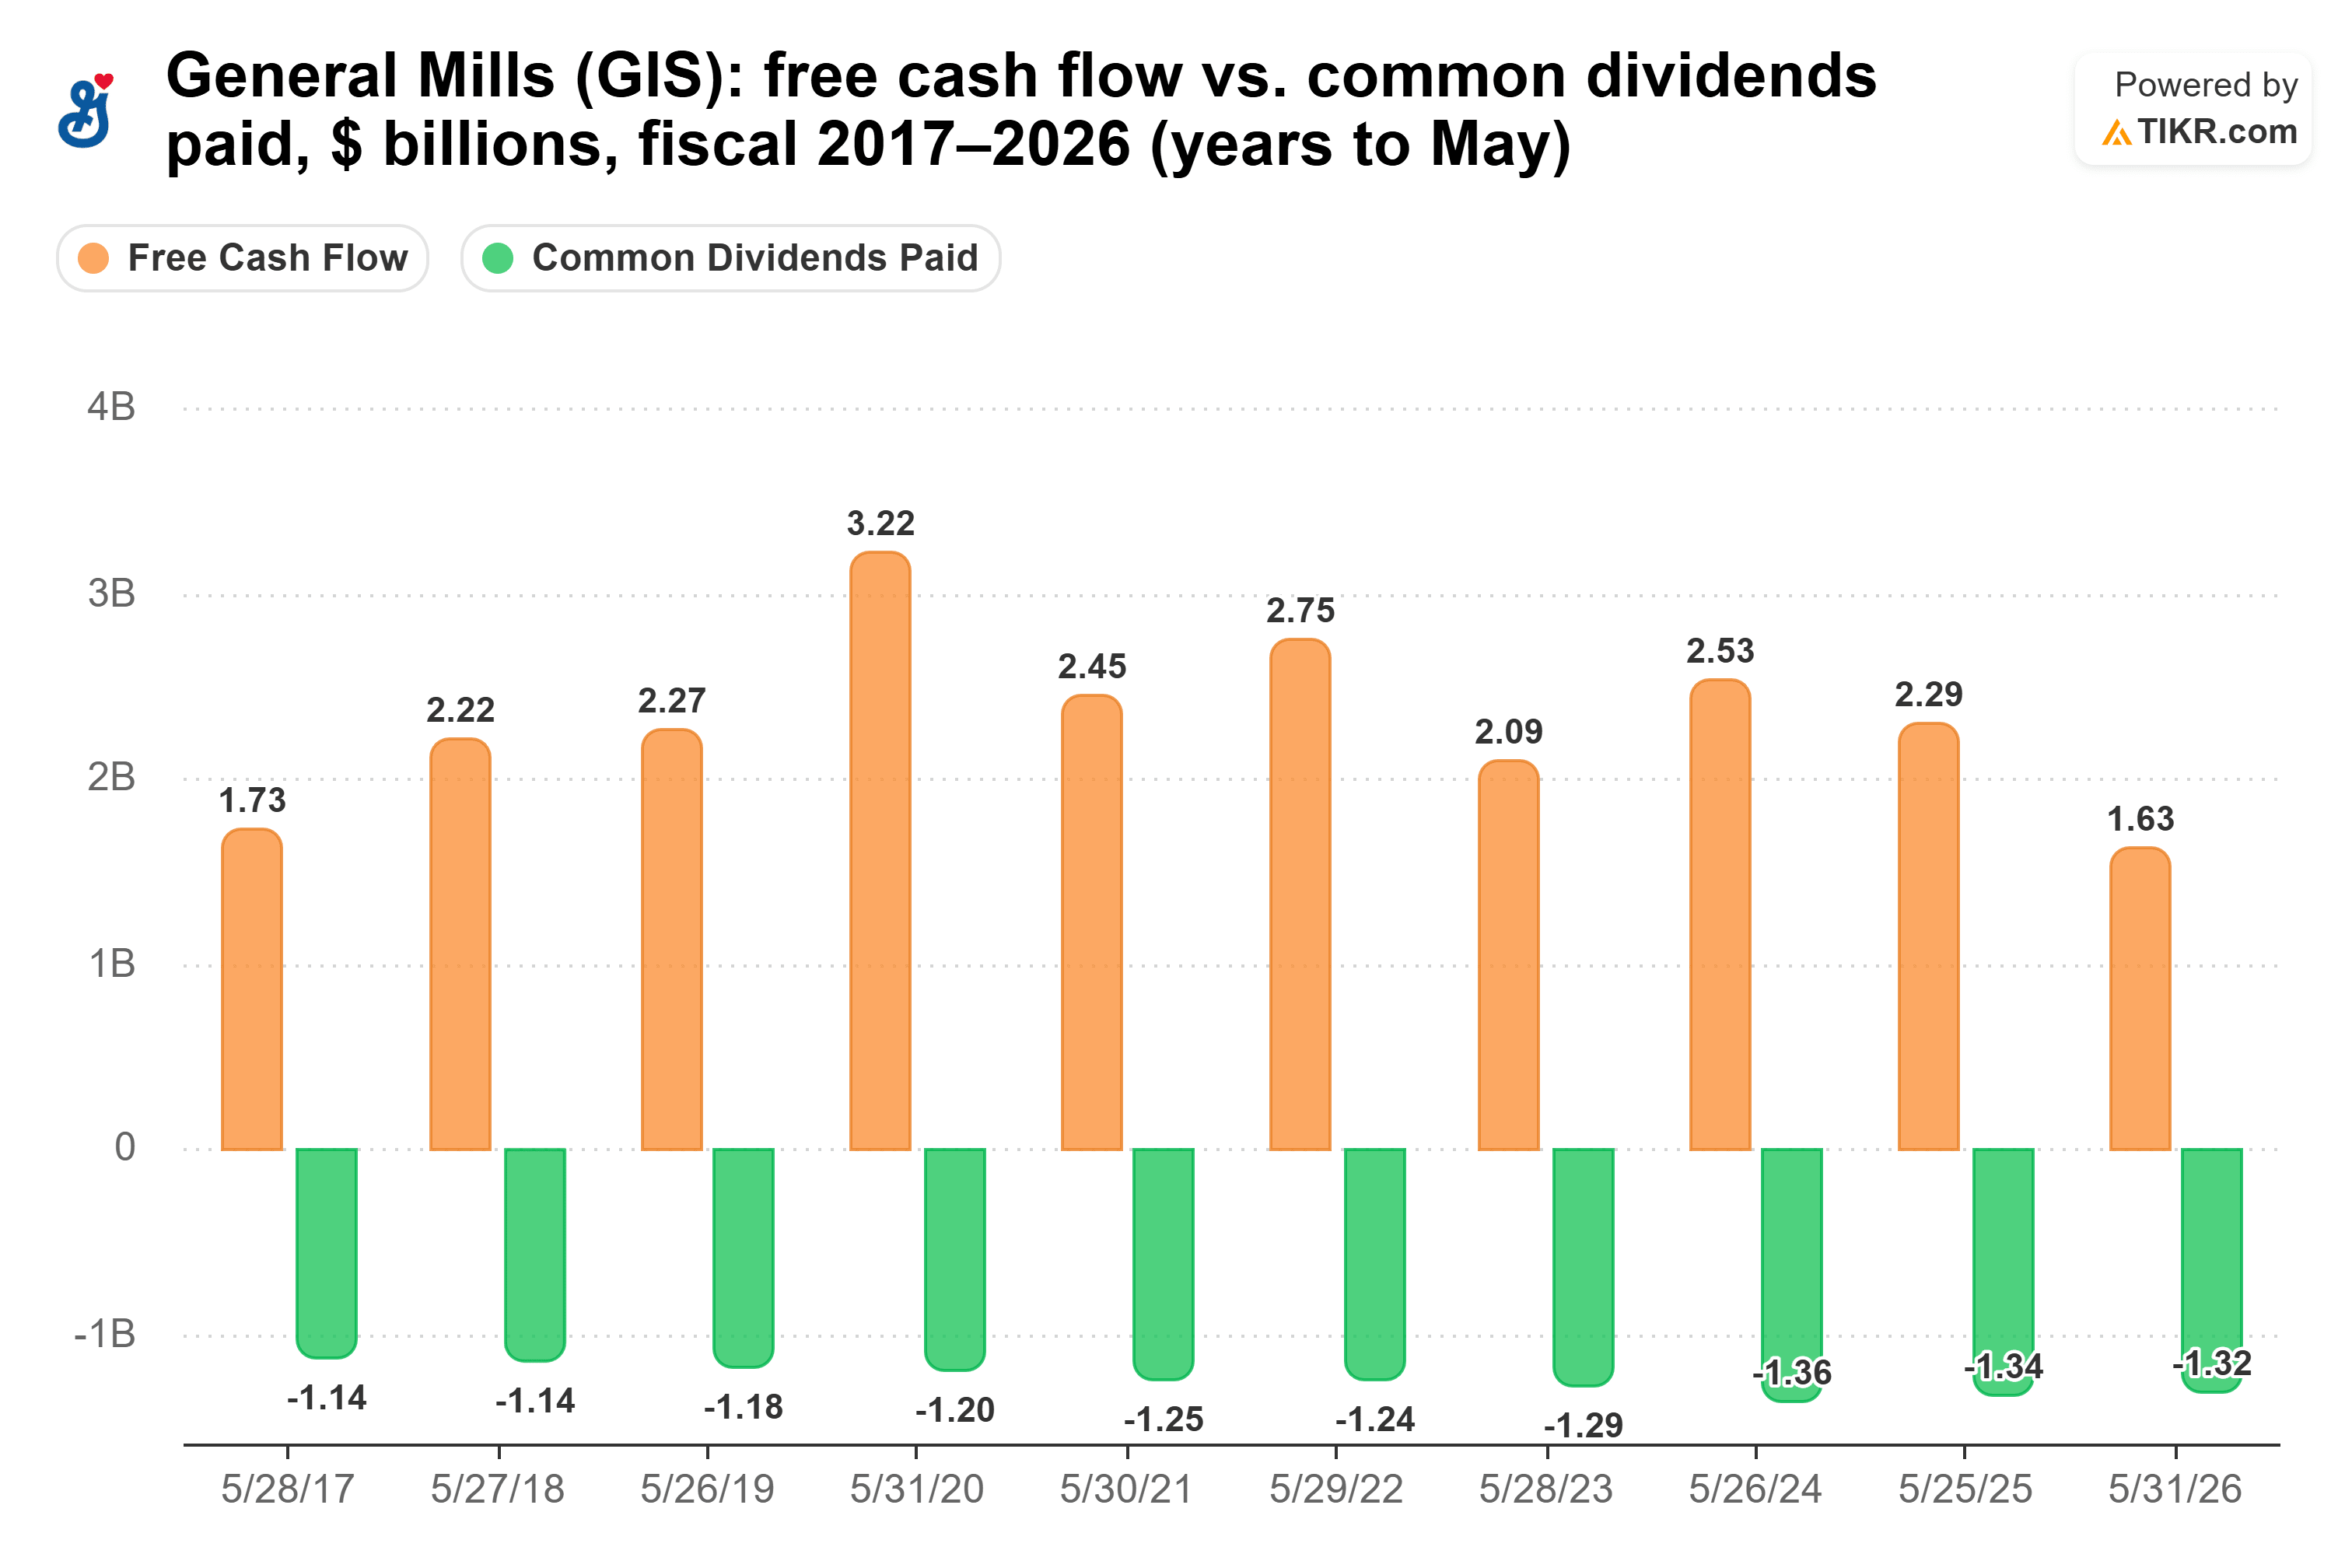
From fiscal 2021 to fiscal 2025, dividends took between 45% and 62% of free cash flow. Then free cash flow dropped from $2.29 billion in fiscal 2025 to $1.63 billion in fiscal 2026, against $1.32 billion of dividends, and the ratio jumped from 58% to 81%. Over the twelve months to Aug. 30, 2026, it was a tight 85%.
CFO Kofi Bruce says the company will “maintain the current rate per share while we prioritize deleverage,” and it doesn’t expect to buy back shares in the near term. So its 3.9% five-year rate overstates the raises ahead. The risk is that the core retail business keeps shrinking while that debt gets paid down.
So which dividend wins?
I’d go with Pfizer as the better high-yield dividend stock. Both payouts are tight today, but they’re moving in opposite directions: Pfizer’s payout ratio has improved from 108% of free cash flow in fiscal 2025, while General Mills’s has risen from 58%.
Pfizer also has the balance sheet to wait out its patent losses.

General Mills’s net debt rose from 2.7x EBITDA in fiscal 2022 to 3.7x in fiscal 2026, against 1.97x at Pfizer today. On the company’s own count it’s a little over 4x, Bruce confirmed on the Sept. 23 call, and he expects it will take “at least a couple of years to work ourselves back to our target of 3x net debt to EBITDA.”
This isn’t to say General Mills’s dividend is in trouble. $10,000 in the stock pays $770 a year today, against $630 from Pfizer. Even at each dividend’s pace now, Pfizer’s income wouldn’t pass General Mills’s until about 2055. General Mills covered its dividend comfortably for years, and management says it’s “fully committed” to it. It’s just that, for a dividend I’m counting on for years, I’d rather own the company with the lighter debt load and a business heading back toward growth.
Of course, Pfizer’s patent losses run through 2028, so the next few quarters of free cash flow will show whether that 89% keeps improving.
So what is Pfizer stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Pfizer could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


