Key Takeaways
- Qualcomm’s handset revenue fell 26% to $5.14 billion, missing estimates, while automotive revenue jumped 89% to a record $1.99 billion.
- CEO Cristiano Amon told Reuters that non-handset growth should “replace Apple entirely,” with fiscal 2027 guidance assuming no more Apple chip sales.
- Rising costs cut the chip segment’s pretax margin to 24% from 29%, and Bernstein called the margin outlook “lousy.”
- Qualcomm’s next report should show whether data center revenue tops $650 million and whether price increases start lifting margins.
Qualcomm (QCOM) just posted a quarter that showed both of its futures at once. Phone chip sales shrank by more than a quarter, while car chip sales nearly doubled.
Investors focused on the phones. Shares fell more than 6% in extended trading on November 4 after handset revenue missed estimates, partly because Apple (AAPL) keeps moving to its own modems.
The offsets are getting bigger, though. Amazon (AMZN) can buy up to $60 billion of Qualcomm’s AI data center chips under a September deal. On earnings day, SpaceX (SPCX) also picked Qualcomm to supply radio gear for its planned Starlink Mobile network starting in 2027.
In an interview with Reuters, CEO Cristiano Amon said the first-quarter forecast includes no further Apple sales. “We expect the non-handset (revenue) to replace Apple entirely,” he said.
Phones fell while cars surged
Adjusted revenue fell 7% to $10.44 billion, beating the $10.11 billion analysts expected. Adjusted EPS came in at $2.17, a penny above estimates but down 28% from a year earlier.
The split inside the chip business told the real story:
- Handsets: $5.14 billion, down 26% and below the $5.25 billion estimate
- Automotive: $1.99 billion, up 89% for a first $2 billion quarter
- IoT: $1.89 billion, up 4%
Memory explains most of the damage. Surging memory costs pushed up phone prices, and global smartphone shipments fell 20% in the quarter to a 14-year low. Qualcomm’s handset drop was steeper still because Apple orders are fading.
Here’s how fast the mix is moving…
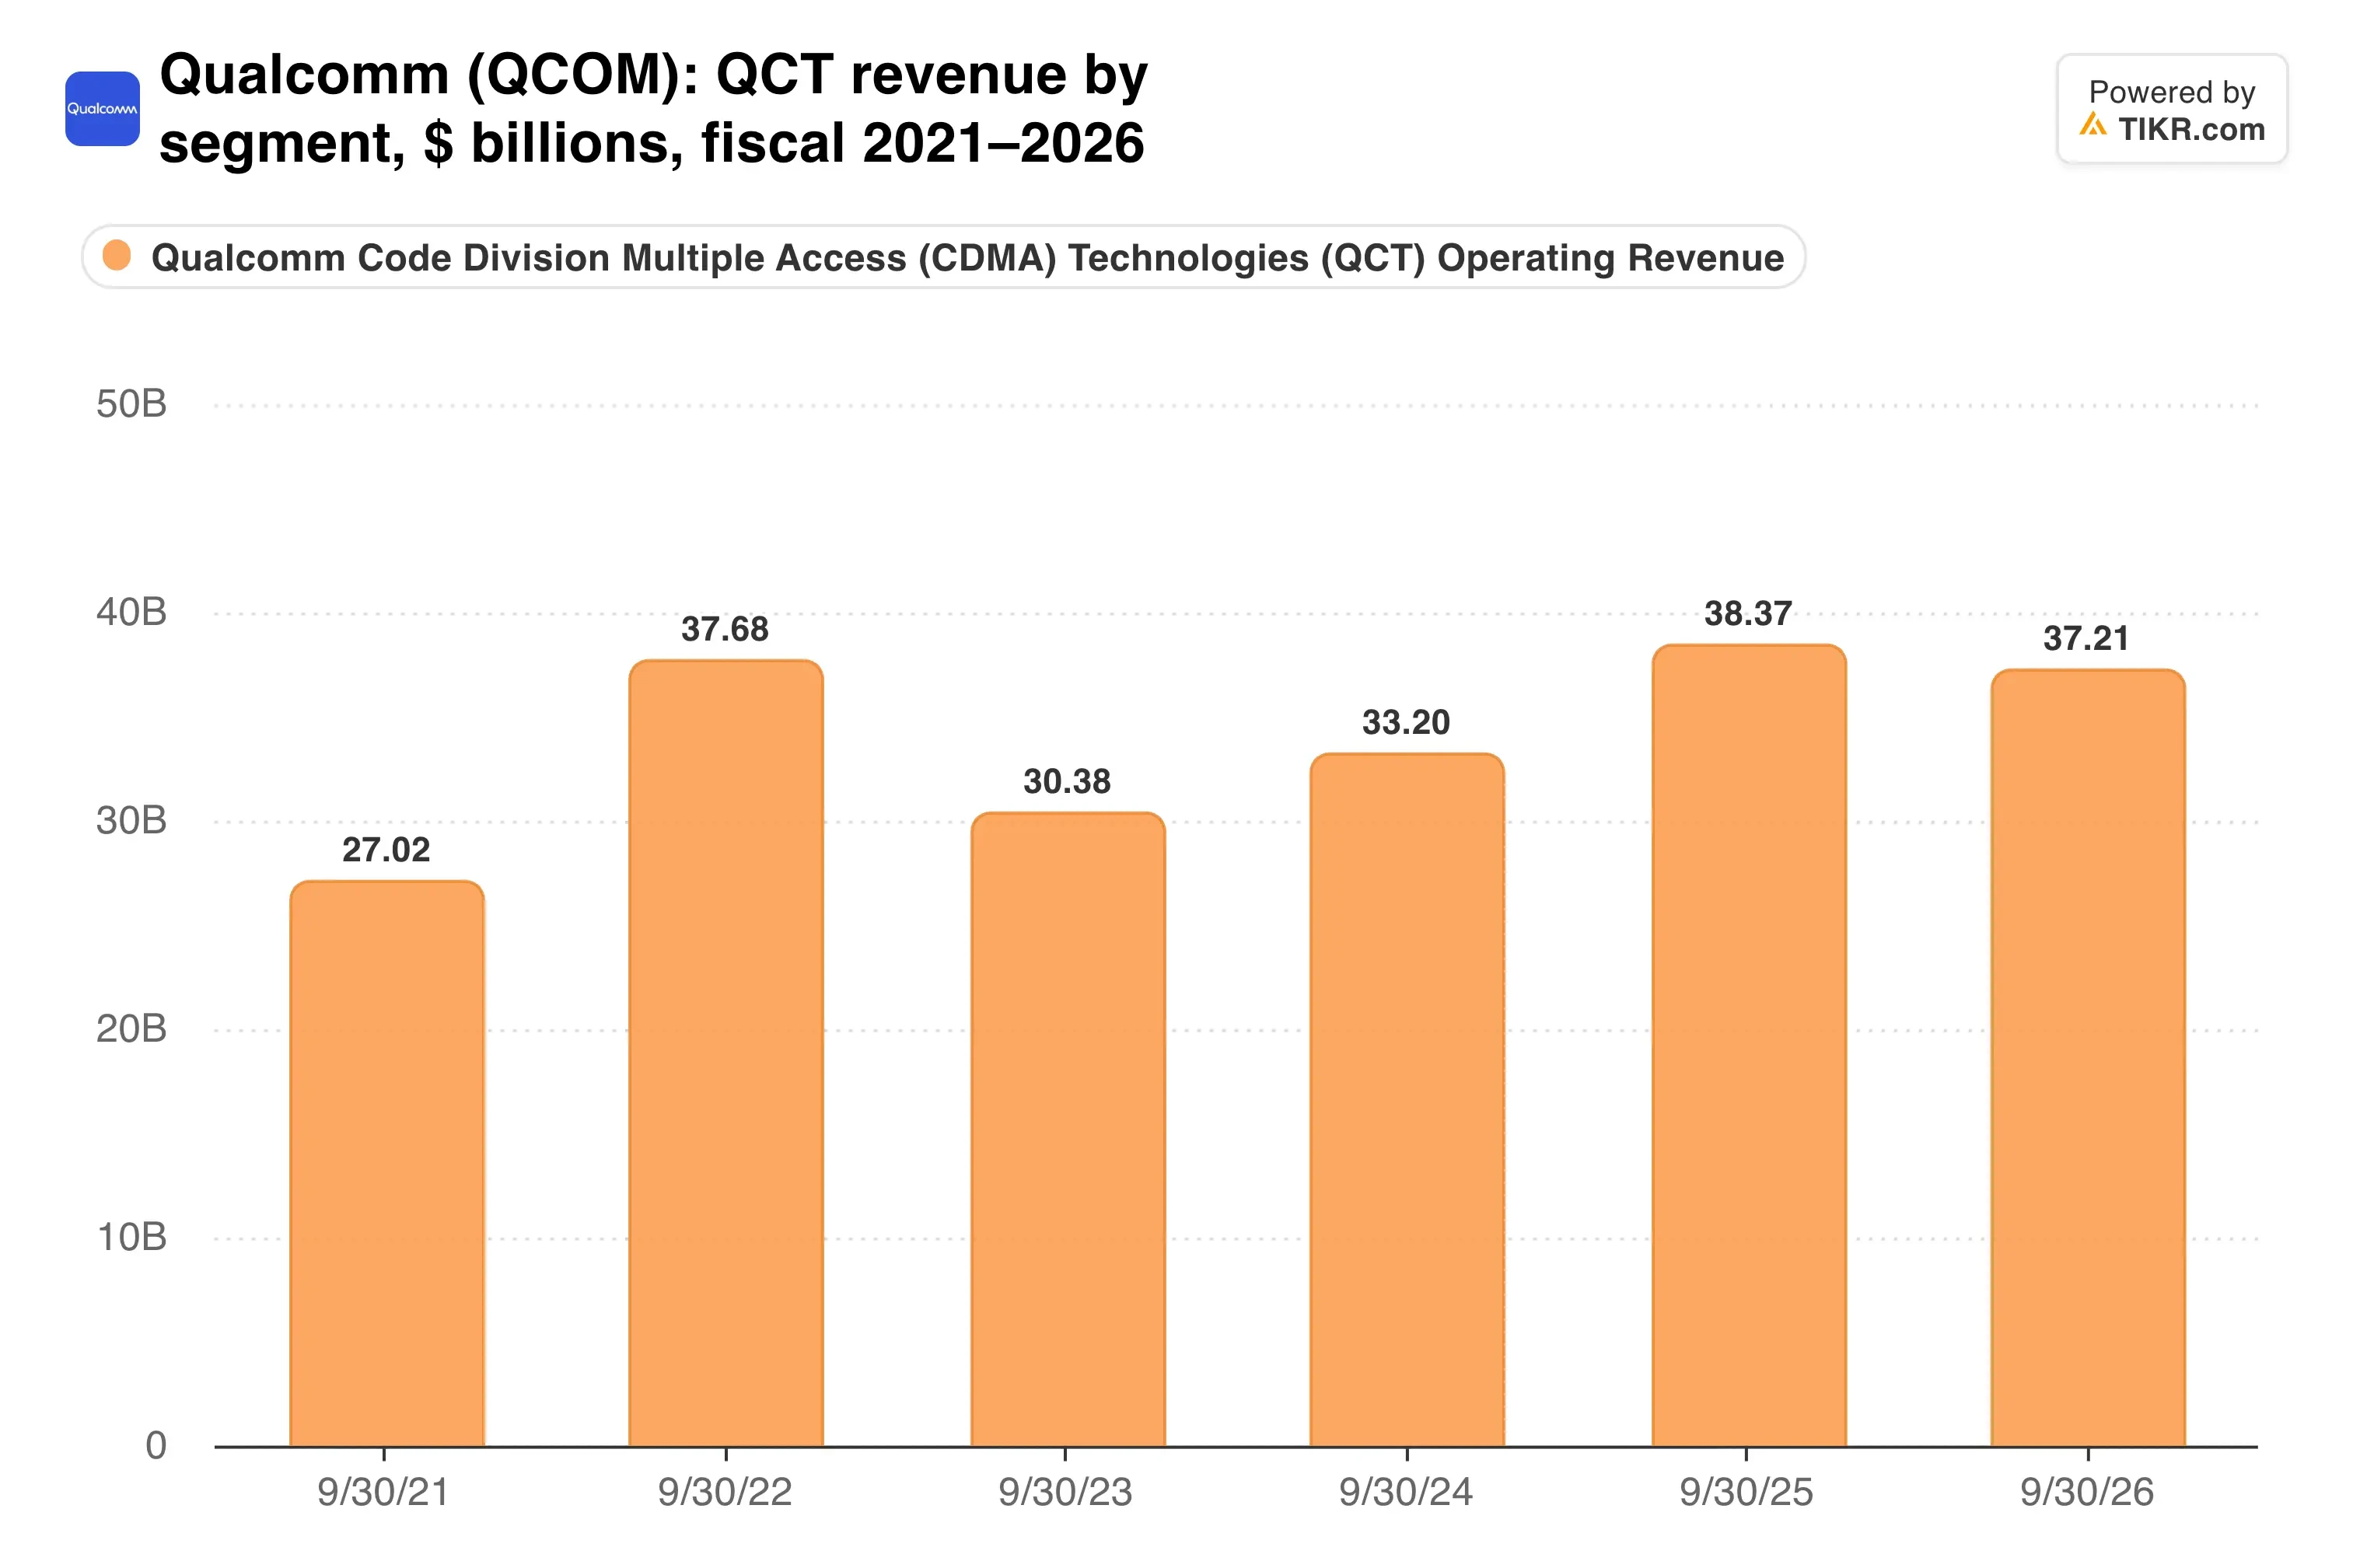
In fiscal 2026, automotive and IoT made up about 35% of chip revenue, up from roughly 28% a year earlier.
Data center becomes the swing factor
Fiscal 2027 is where the plan gets tested. Qualcomm expects more than $650 million of data center revenue in the December quarter, ahead of the $539 million analysts had penciled in. It reiterated a $5 billion full-year target.
Amazon anchors that ramp. Qualcomm supplies custom inference silicon and optical connectivity to AWS, and Amazon’s warrants for up to 25 million Qualcomm shares vest as it buys.
Building all this costs money now. Is the spending showing up yet?
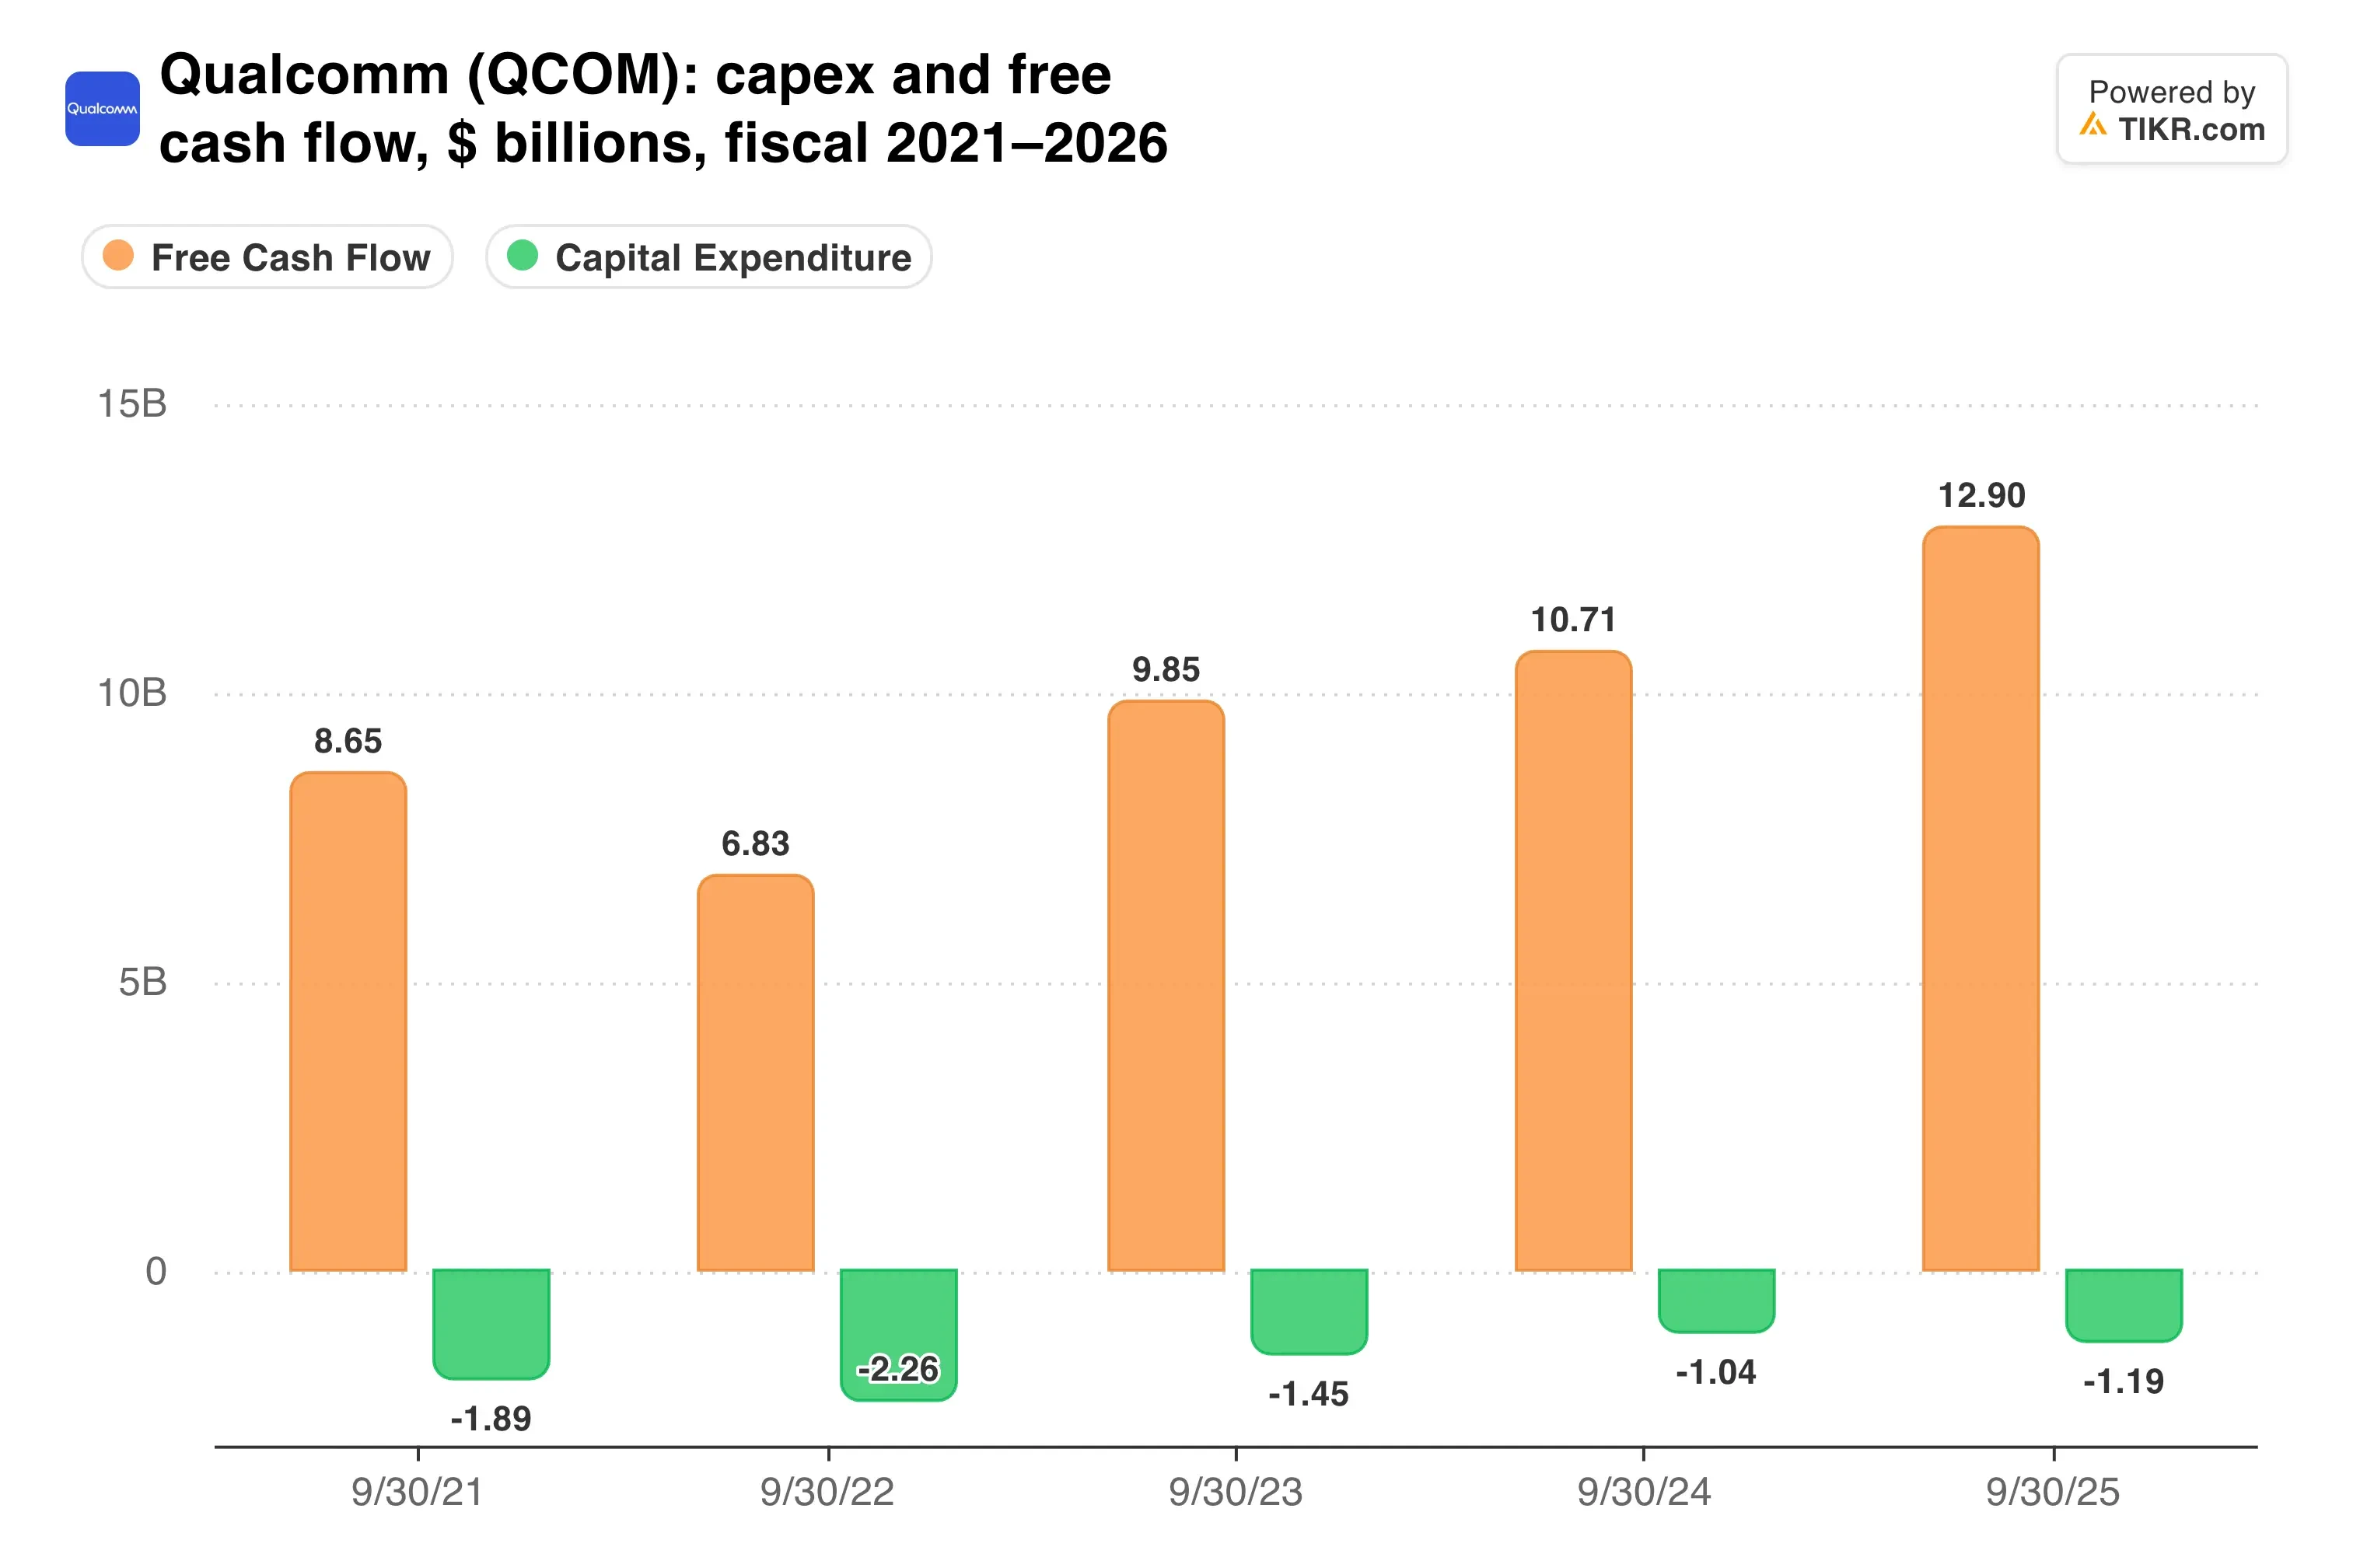
Capex more than doubled to $2.49 billion in fiscal 2026. Meanwhile, operating cash flow fell to $11.15 billion, so free cash flow dropped by about a third.
Buybacks and dividends still totaled $11.7 billion, well above free cash flow.
TIKR tracks 37 analysts on Qualcomm. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Qualcomm, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Qualcomm’s Analyst Ratings
Margins have to recover first
First-quarter revenue of $10.4 billion to $11.2 billion has a midpoint above the $10.48 billion consensus. Yet the $2.25 EPS midpoint landed just below the $2.27 estimate.
Costs explain the gap. Wafers, packaging and memory all got pricier, and the chip segment’s pretax margin slid to 24% from 29% a year ago. Bernstein’s Stacy Rasgon told Reuters the “margin outlook is lousy.”
Price increases should help. CFO Akash Palkhiwala expects baseline gross margin back at 48% to 50% by the March quarter.
Earnings power has reset lower, and rebuilding it will take time:
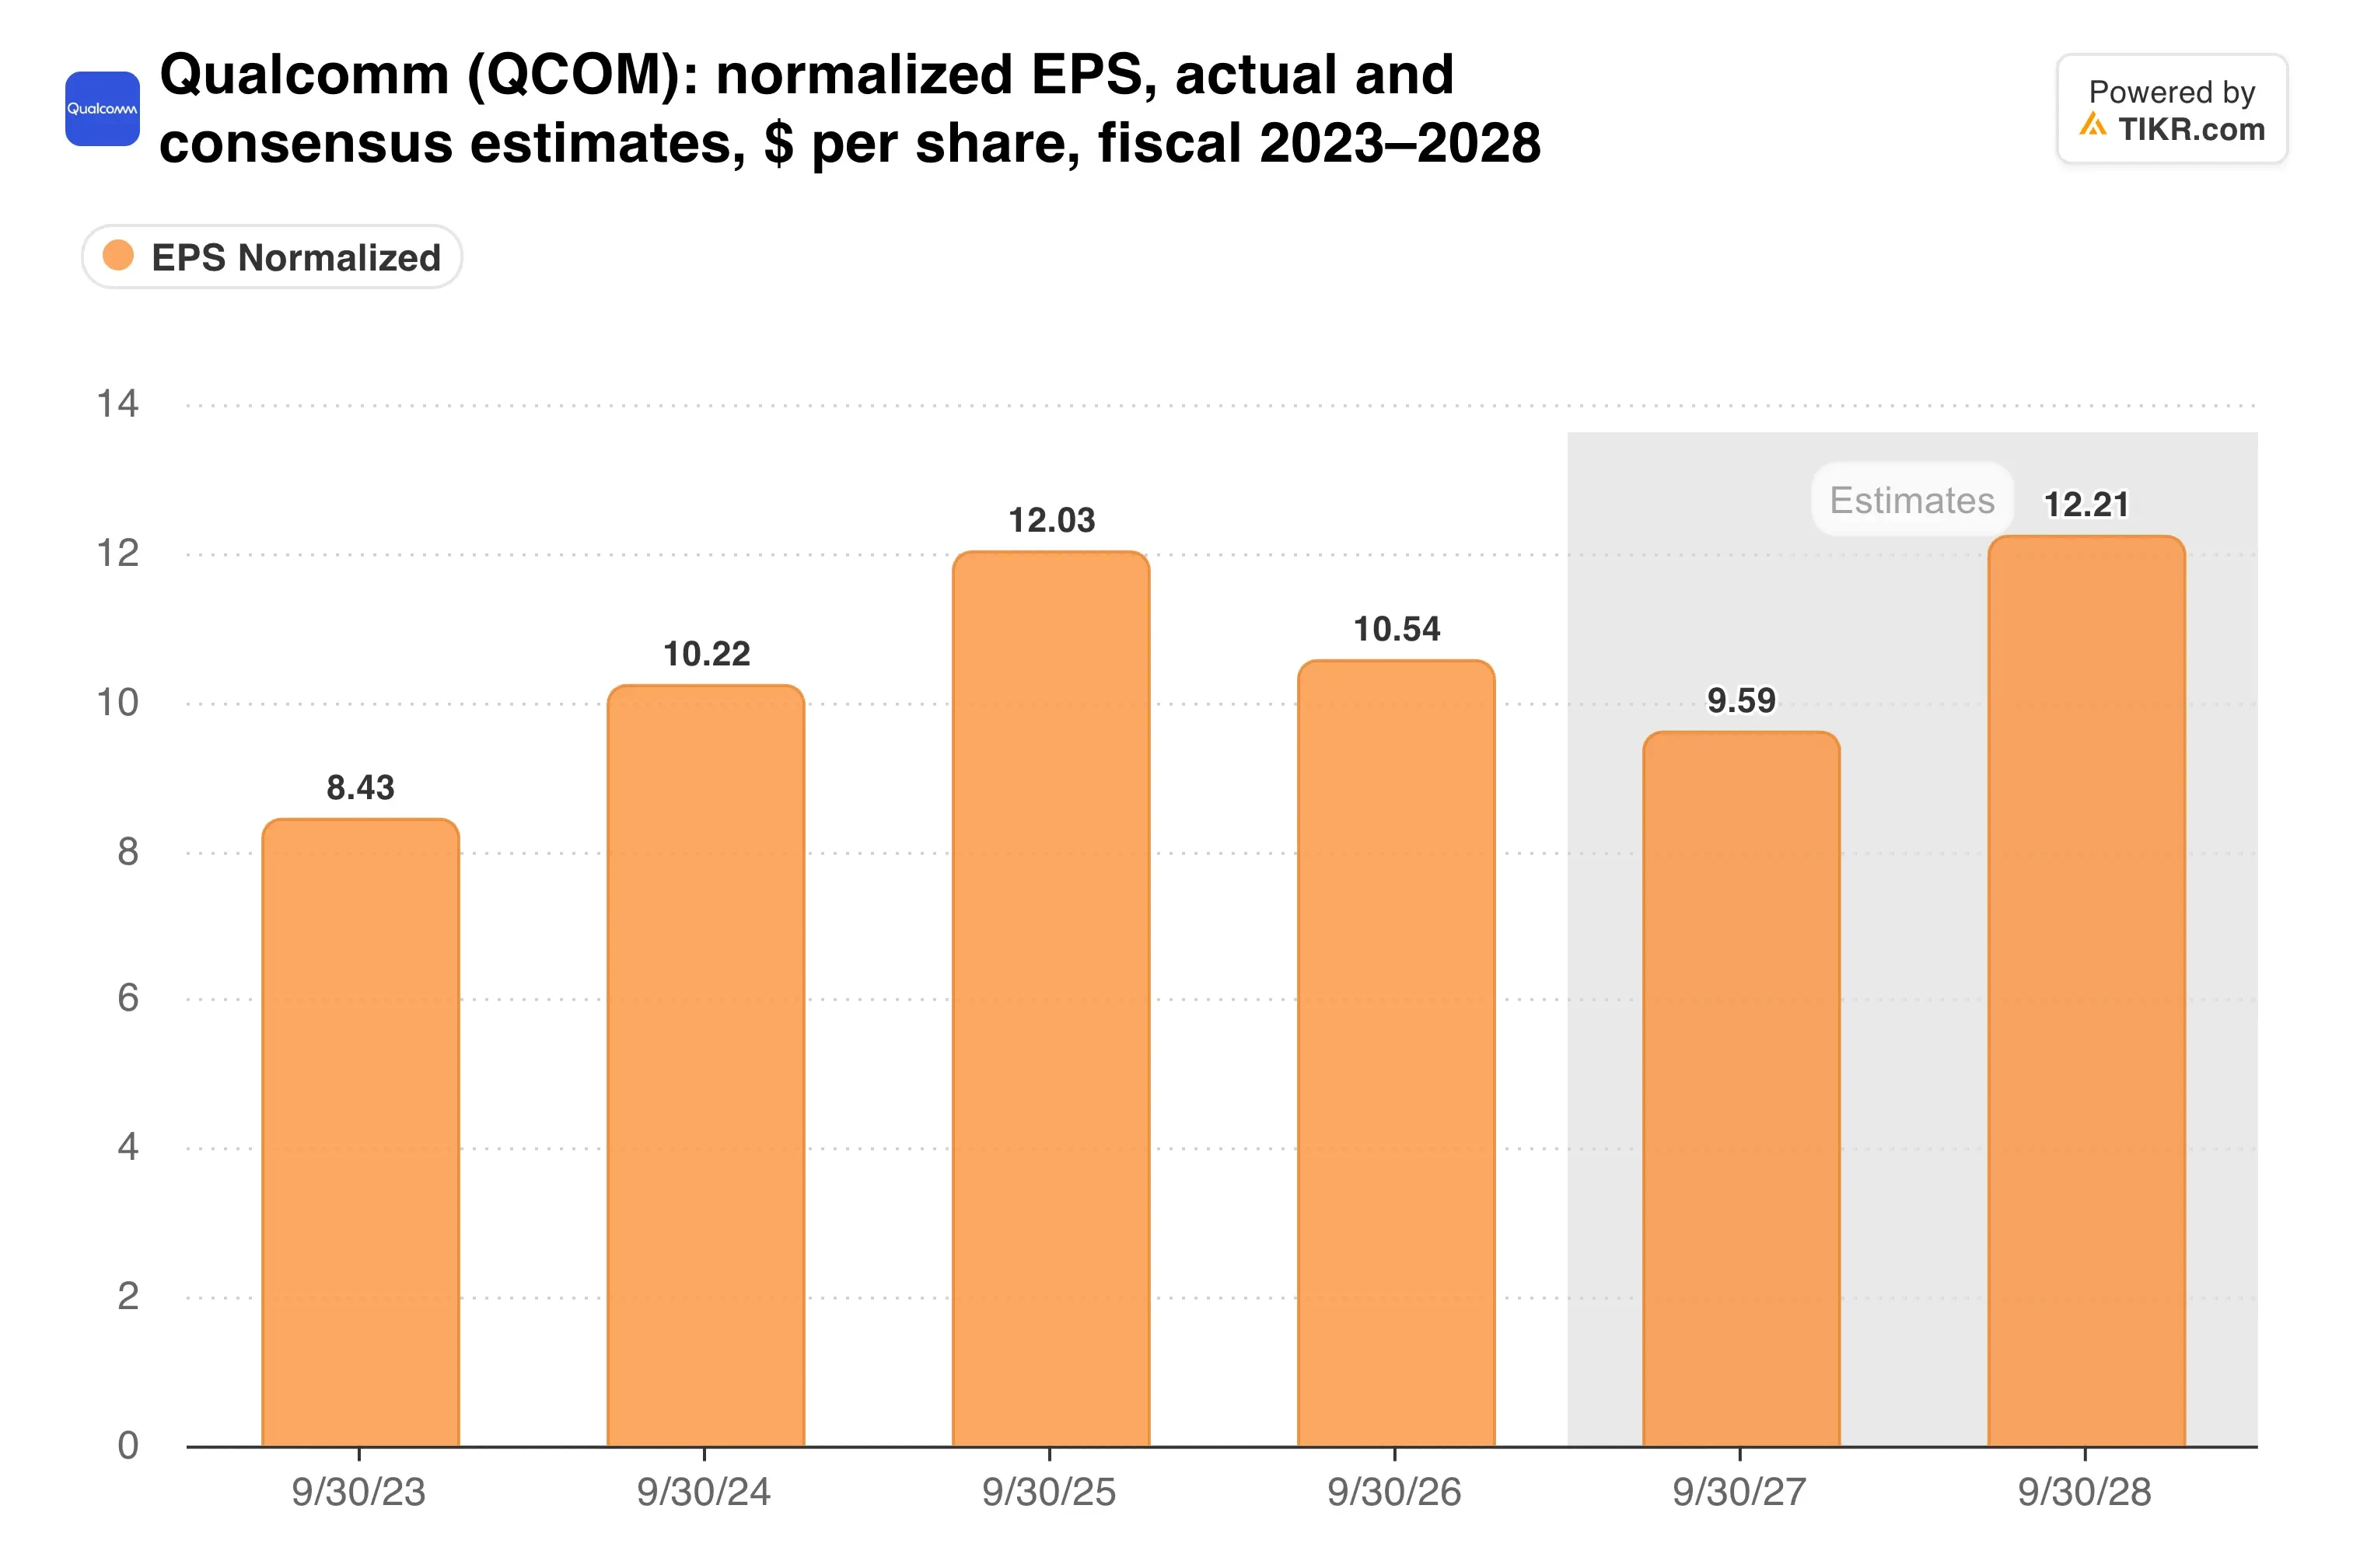
Adjusted EPS fell 12% to $10.54 in fiscal 2026, so any recovery depends on the new markets showing up.
My take: The diversification is real. Automotive grew 52% last year to $6 billion, and Amazon gives the data center story a credible anchor. But Qualcomm is paying for that future with margin and cash today, while handsets still made up 65% of chip revenue in fiscal 2026. I’d want to see the data center number land before calling this selloff a gift.
The fiscal first-quarter report, expected in early February, is the next checkpoint. It will show whether data center revenue clears $650 million and price increases lift margins.
So what is Qualcomm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Qualcomm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!