Key Takeaways
- General counsel Michael O’Sullivan bought $250,207 of Berkshire Class B stock at an average $594.32 on Nov. 12, the day it touched a 52-week high.
- The stock is up 18% in three months, though third-quarter operating earnings fell 5.8%.
- At 26x forward earnings, Berkshire trades well above its 22x five-year average, and the $565 consensus target sits below the price.
- His buy is a real vote of confidence, but the numbers don’t back paying $594.
Berkshire Hathaway (BRK.B) has climbed 18% in three months, setting a record close of $592.94 on Nov. 13, and one of its newer executives just bought more. Michael J. O’Sullivan, Berkshire’s senior vice president and general counsel, paid a weighted average of $594.32 a share for 421 Class B shares on Nov. 12, or $250,207 in all, according to the Form 4 he filed on Nov. 16.
He bought on the same day the stock touched its 52-week high of $596.92. It closed at $586.76 on Nov. 17, 1.3% below his price.
A Softer Quarter, and a Stock at Record Highs
Most of the stock’s three-month gain came before Berkshire reported third-quarter earnings. On Nov. 7, Berkshire reported third-quarter operating earnings of $12.7 billion, down 5.8% from $13.5 billion a year earlier. Insurance more than explains it: underwriting and investment income fell $1.46 billion combined, nearly twice the $780 million total decline. Underwriting alone fell 43% to $1.35 billion.
BNSF’s earnings rose 19% to $1.73 billion. Berkshire also bought back $9.6 billion of its own stock in the third quarter, more than double the second quarter’s $4.5 billion.
Berkshire’s Top Lawyer Is Putting His Own Money In
O’Sullivan joined Berkshire in January as its first general counsel, after serving as Snap’s general counsel and two decades at Munger, Tolles & Olson. The 421 shares take his stake to 1,572, held through a trust, so he added 37% to what he owned.
TIKR Tracks 4 Analysts on Berkshire Hathaway. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Berkshire Hathaway, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Berkshire Hathaway’s Analyst Ratings
Do the Numbers Back Him at $594?
Analysts expect Berkshire’s normalized EPS to rise from $20.62 in 2025 to $22.56 in 2026, then to just $22.82 in 2027:
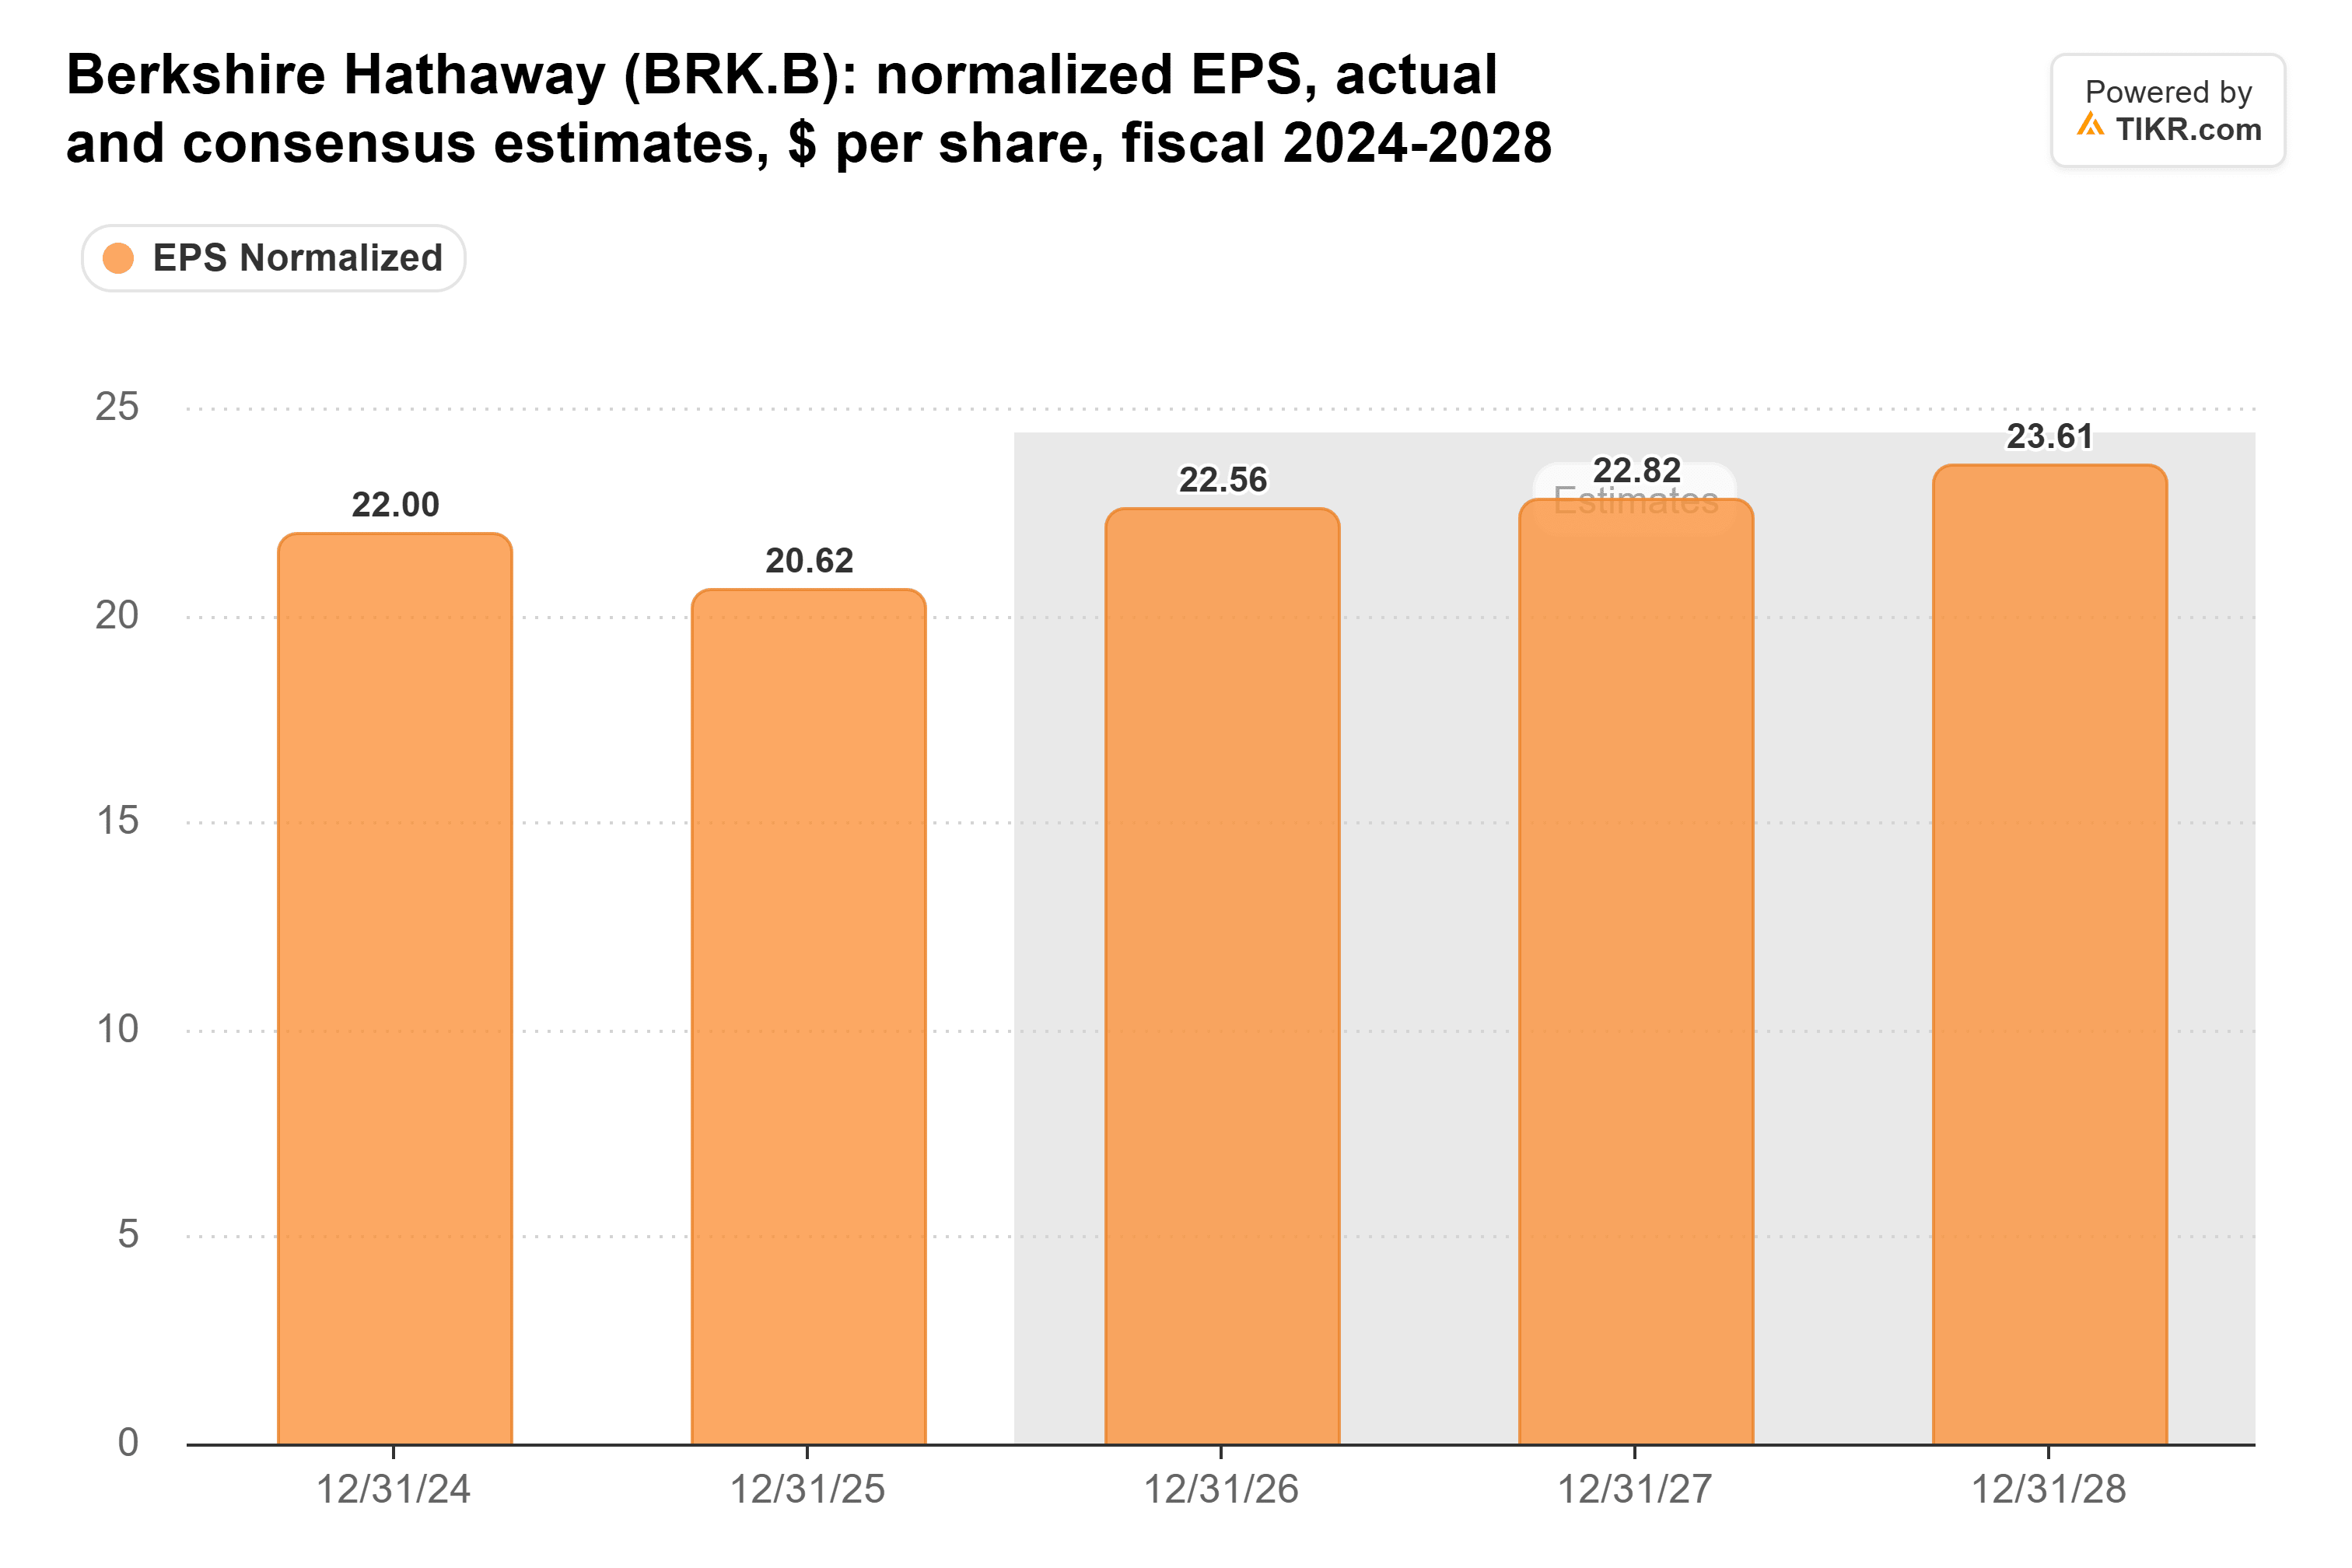
The estimates have edged up since late October, when 2027’s stood at $22.43. Shrinking insurance profits don’t point to faster growth.
That’s slow growth for a stock at 26x forward earnings, near the top of its five-year range of 18x to 27x and well above its 22x average:
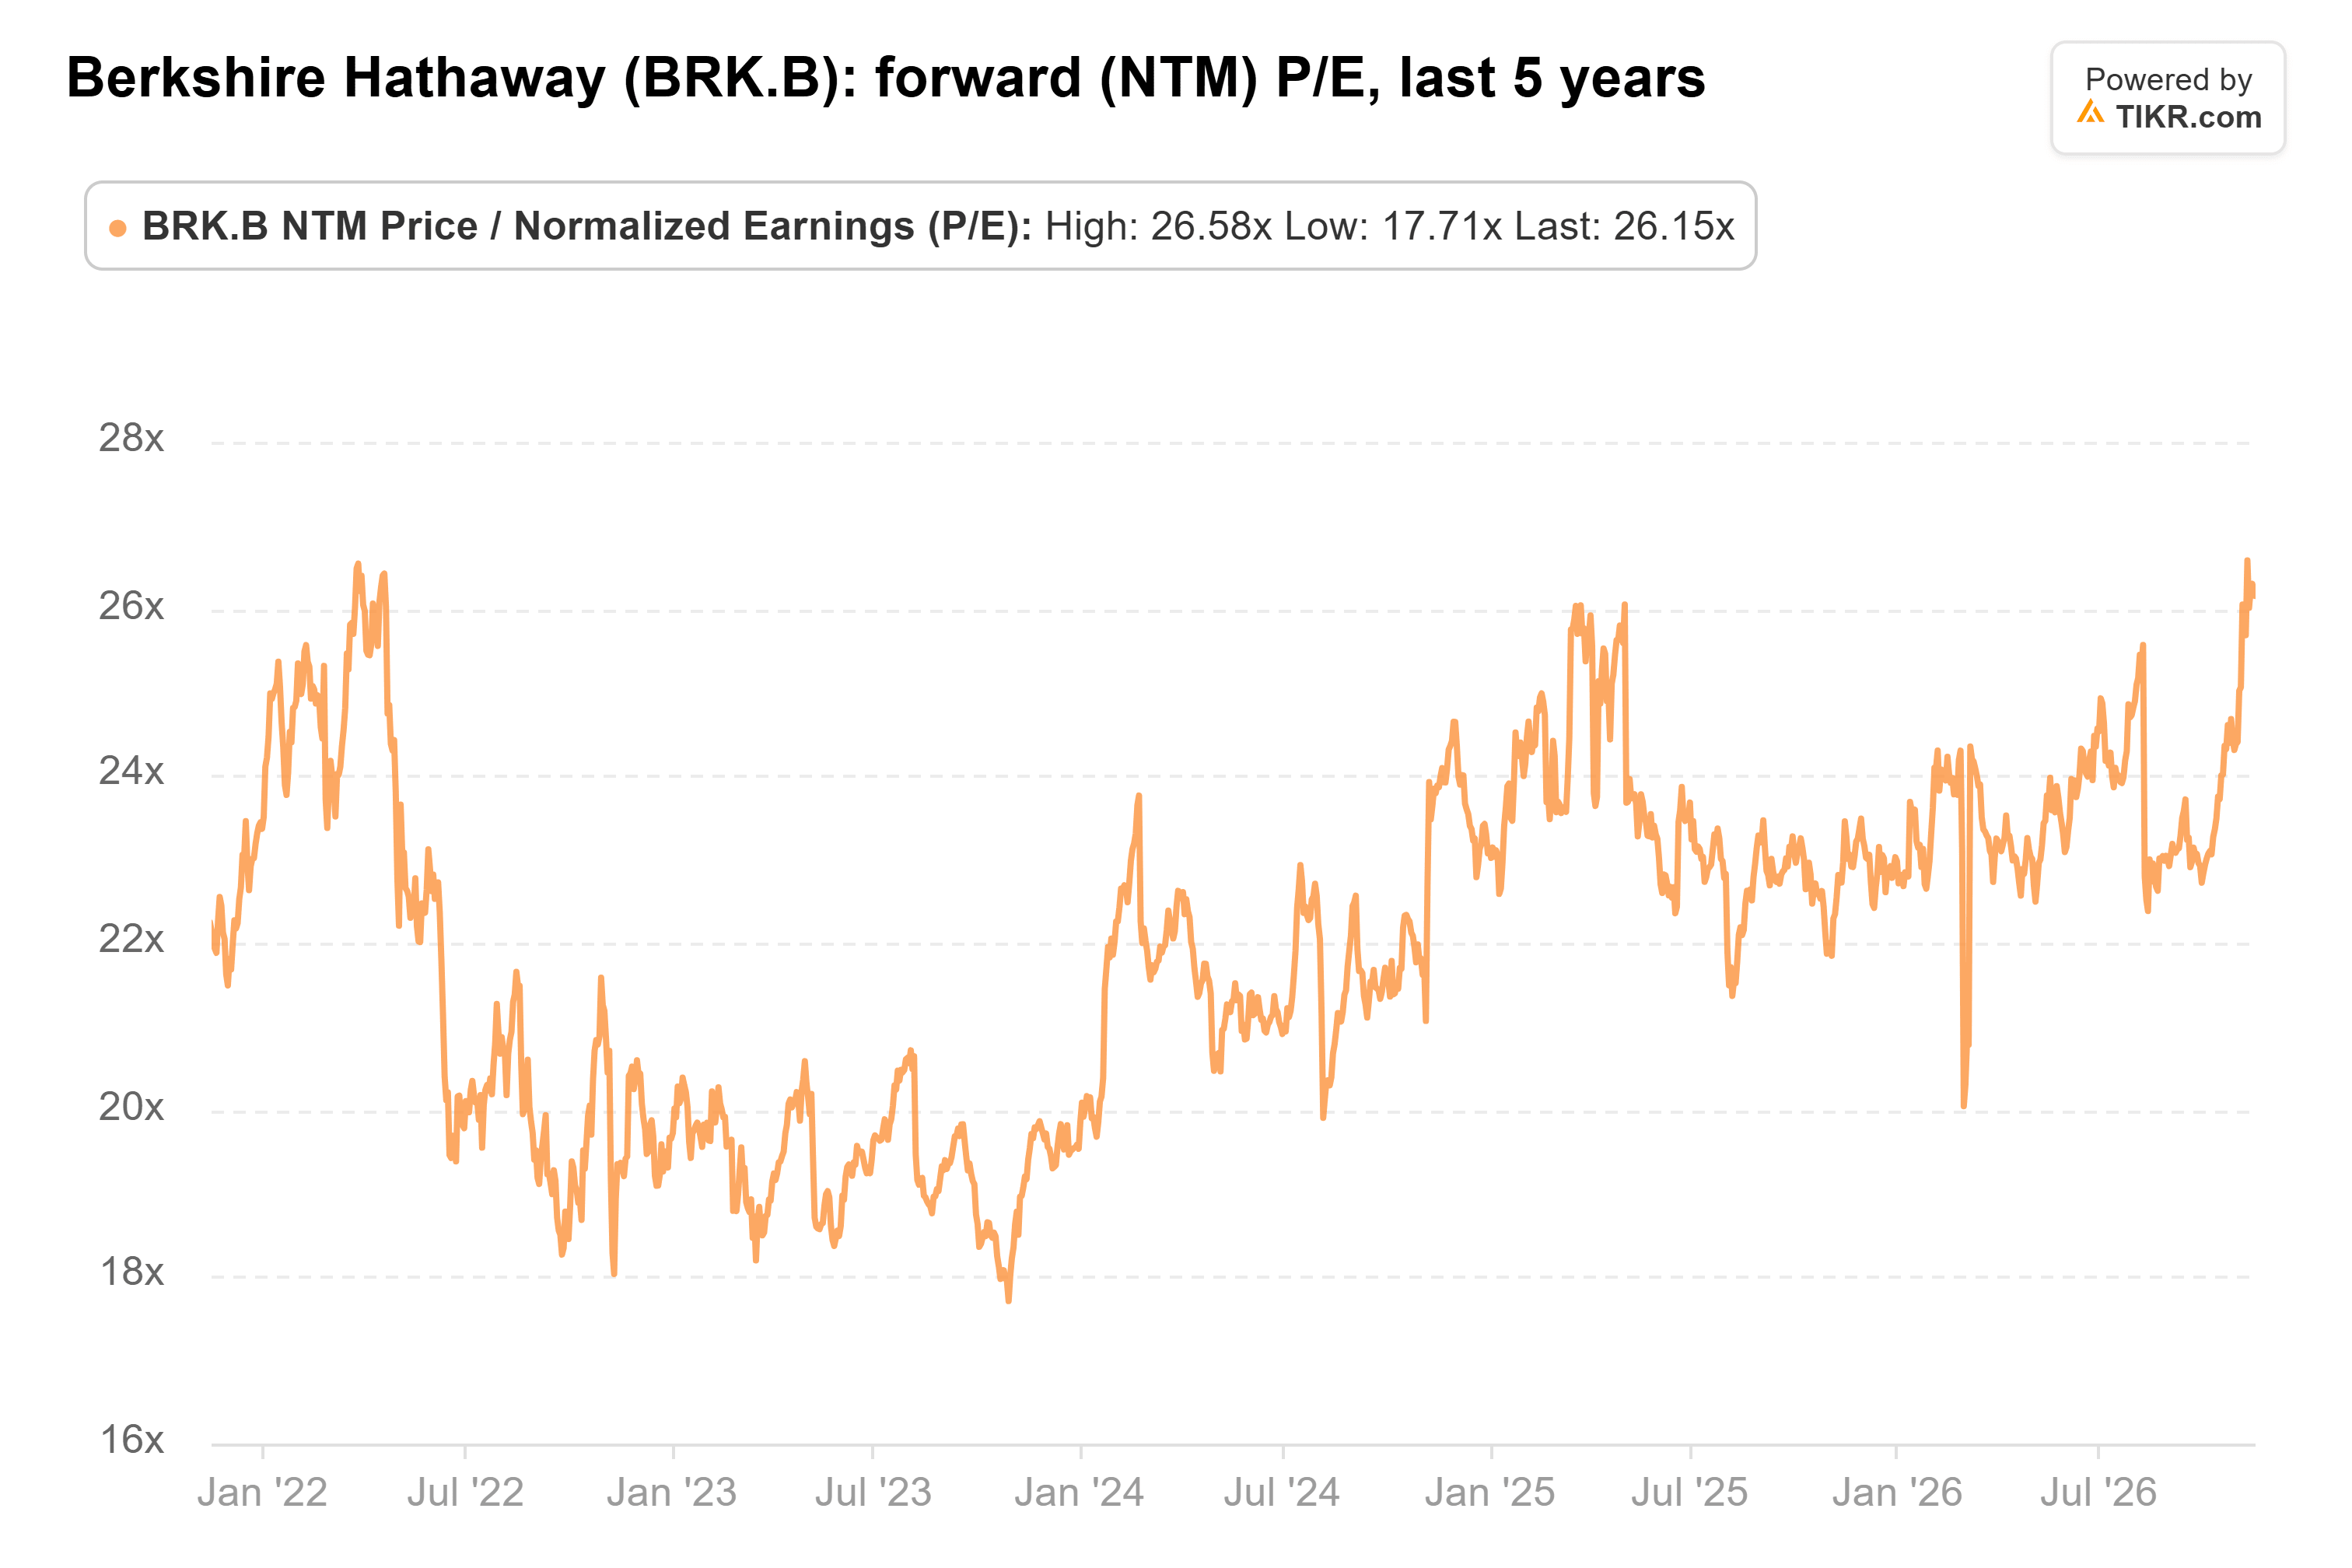
At that 22x average, the earnings analysts expect over the next year would put the stock closer to $500. That’s where it began and ended the third quarter, when Berkshire was buying back stock.
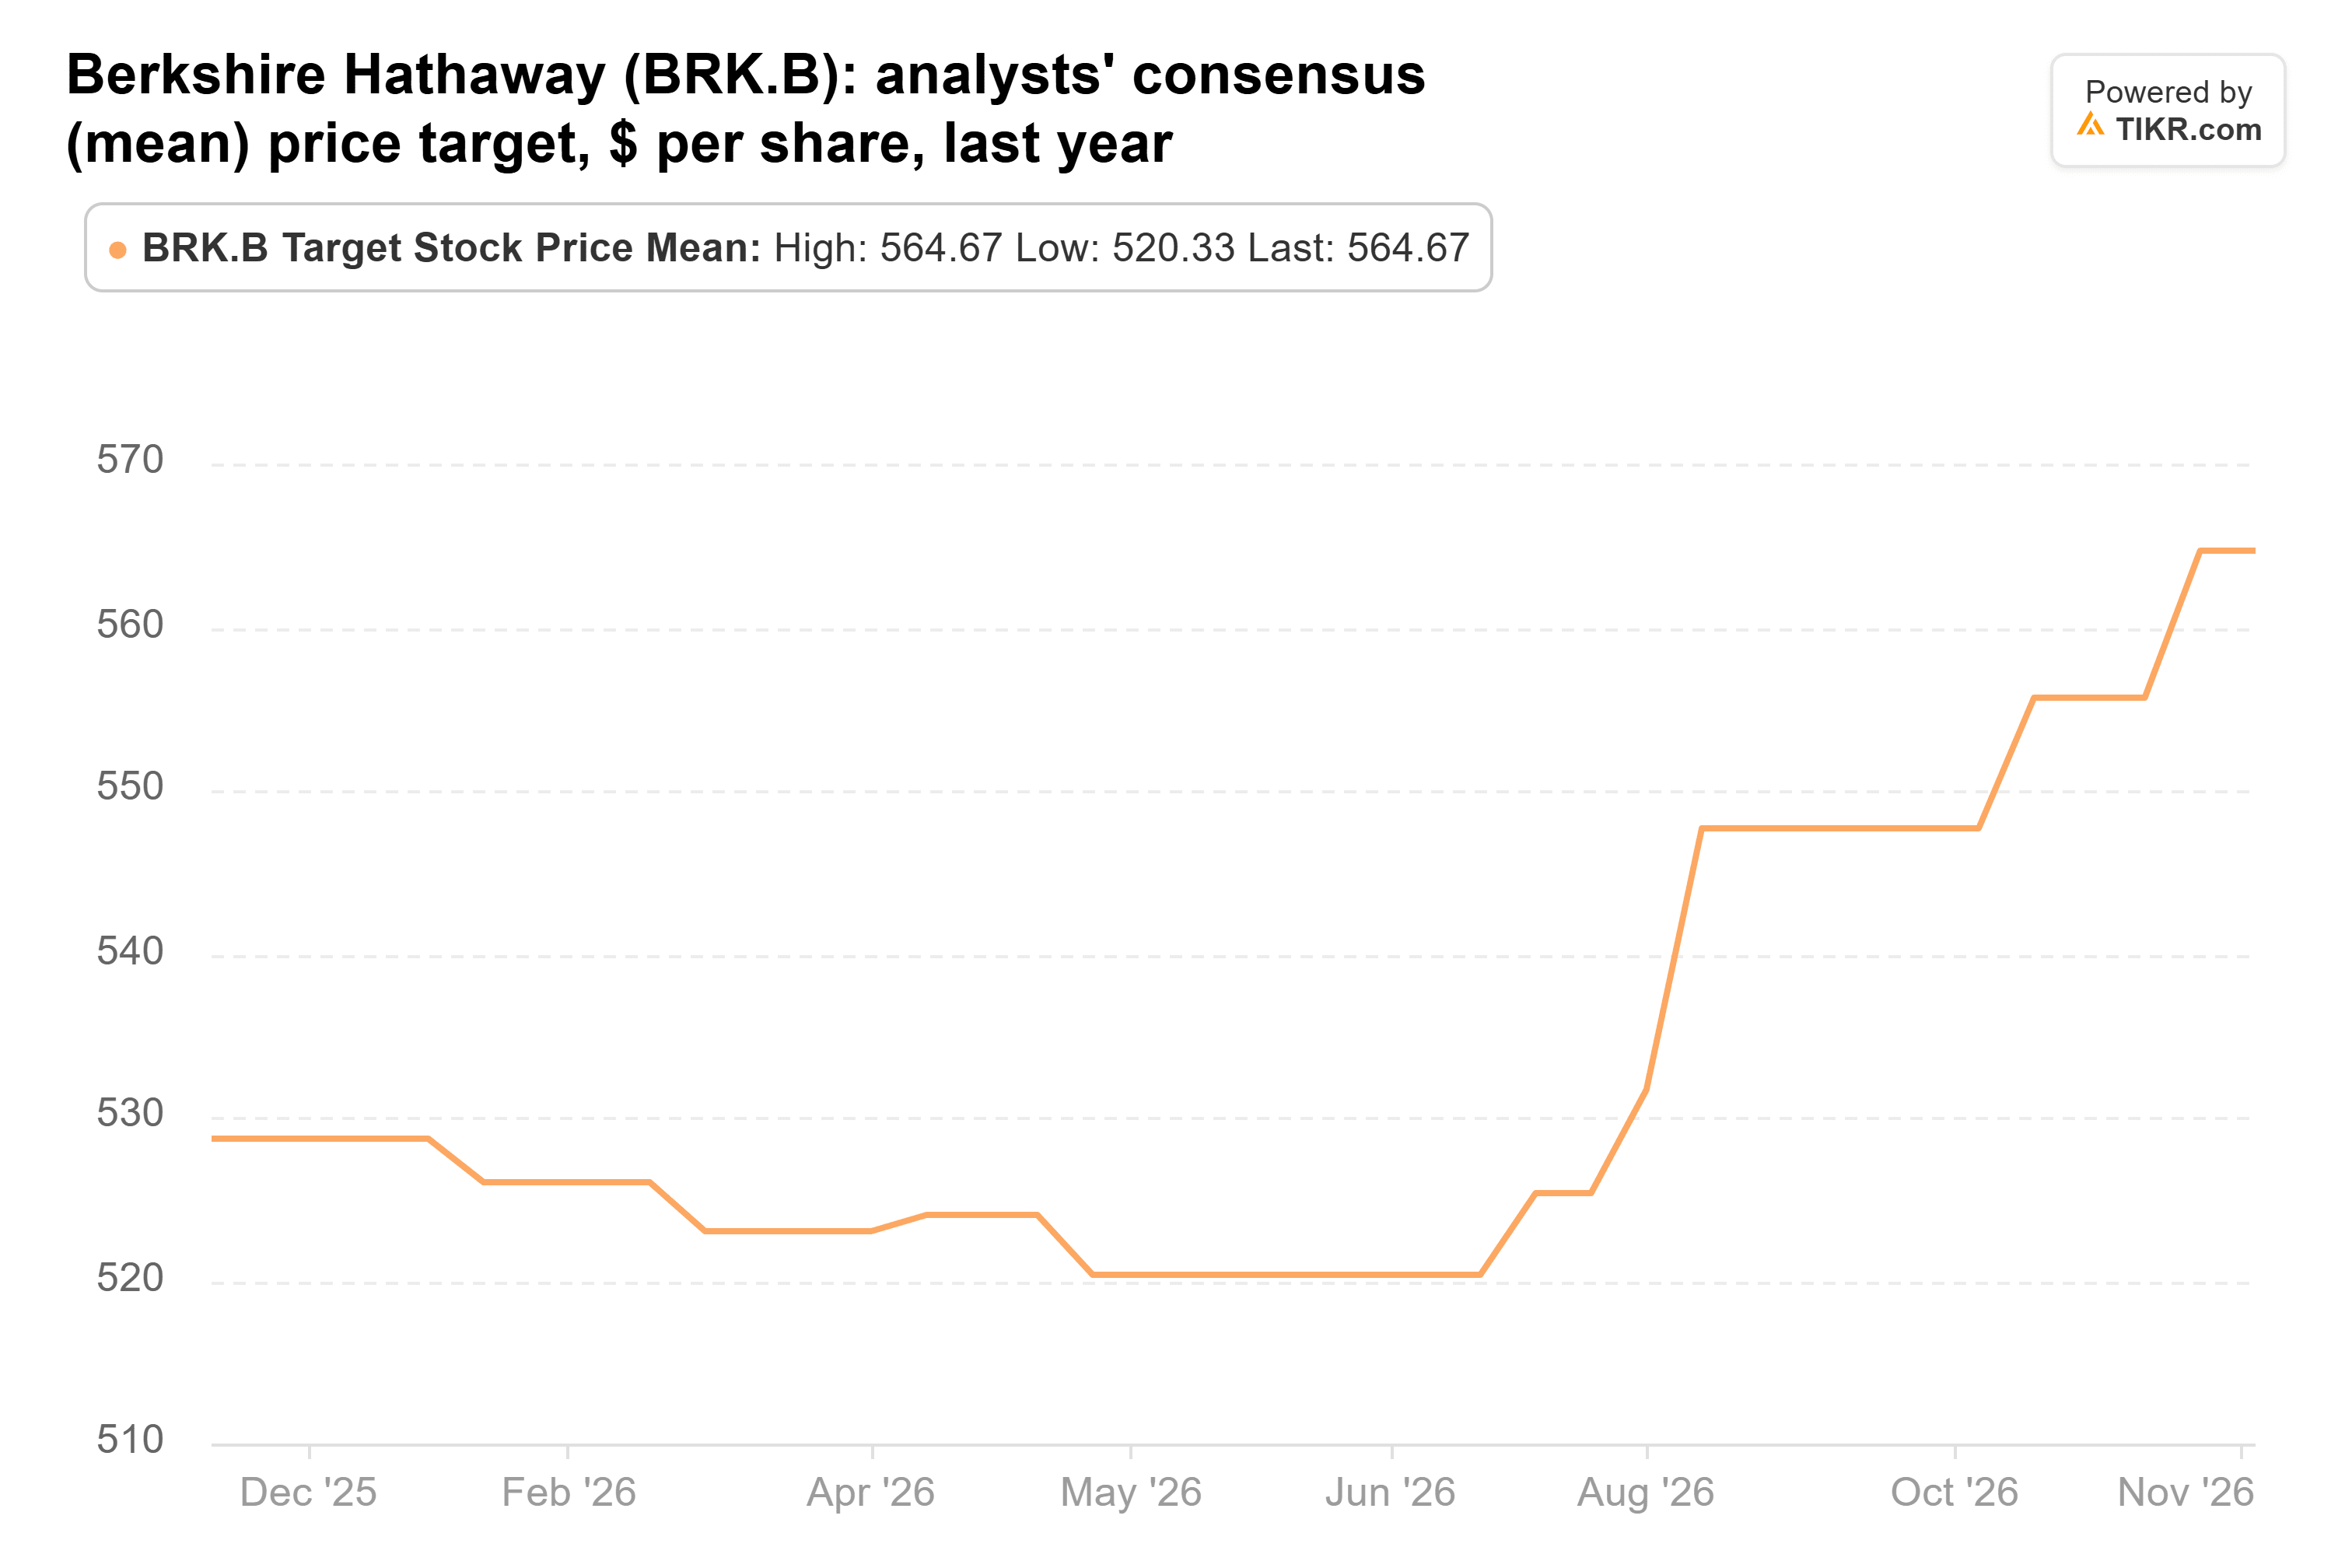
The consensus target has climbed from $529 in December 2025 to $565, about 4% below today’s price, and even the highest of the three targets, $628, is only 7% above it:
A Vote of Confidence in Berkshire at a Full Price
The case for paying up is that Greg Abel puts the $352.3 billion of cash and Treasury bills in Berkshire’s insurance and other businesses to work at returns the estimates don’t show. That’s possible, but those deals haven’t happened yet.
O’Sullivan’s buy says more about his confidence in Berkshire under Abel than about the value at $594 a share. At 26x earnings that analysts expect to grow slowly, the numbers made a better case for the buybacks Berkshire did while the stock sat near $500.
Berkshire’s annual report, due early next year, will show whether the company kept buying back stock at these prices.
So What Is Berkshire Hathaway Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Berkshire Hathaway could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Berkshire Hathaway for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!