Key Takeaways
- Bausch + Lomb shares jumped 16% after a third-quarter profit beat and raised full-year guidance.
- Profit is the story: adjusted EBITDA rose 34% on 7% revenue growth.
- Johnson & Johnson’s contact lenses grew too, putting the spotlight on Cooper Companies’ flat lens sales.
- Debt remains the main risk.
Bausch + Lomb (BLCO) shares jumped 16% today after its third-quarter profit blew past expectations. Adjusted EPS came in at $0.34 against a $0.22 consensus, and revenue rose 7% to $1.375 billion.
Its contact lenses grew too, and so did those of Johnson & Johnson (JNJ). That makes The Cooper Companies (COO), whose CooperVision lens sales were flat last quarter, stand out.
Profit is doing the heavy lifting
Adjusted EBITDA climbed 34% to $325 million.
Bausch + Lomb raised the midpoint of its full-year adjusted EBITDA guidance by $65 million, against just $10 million for revenue.
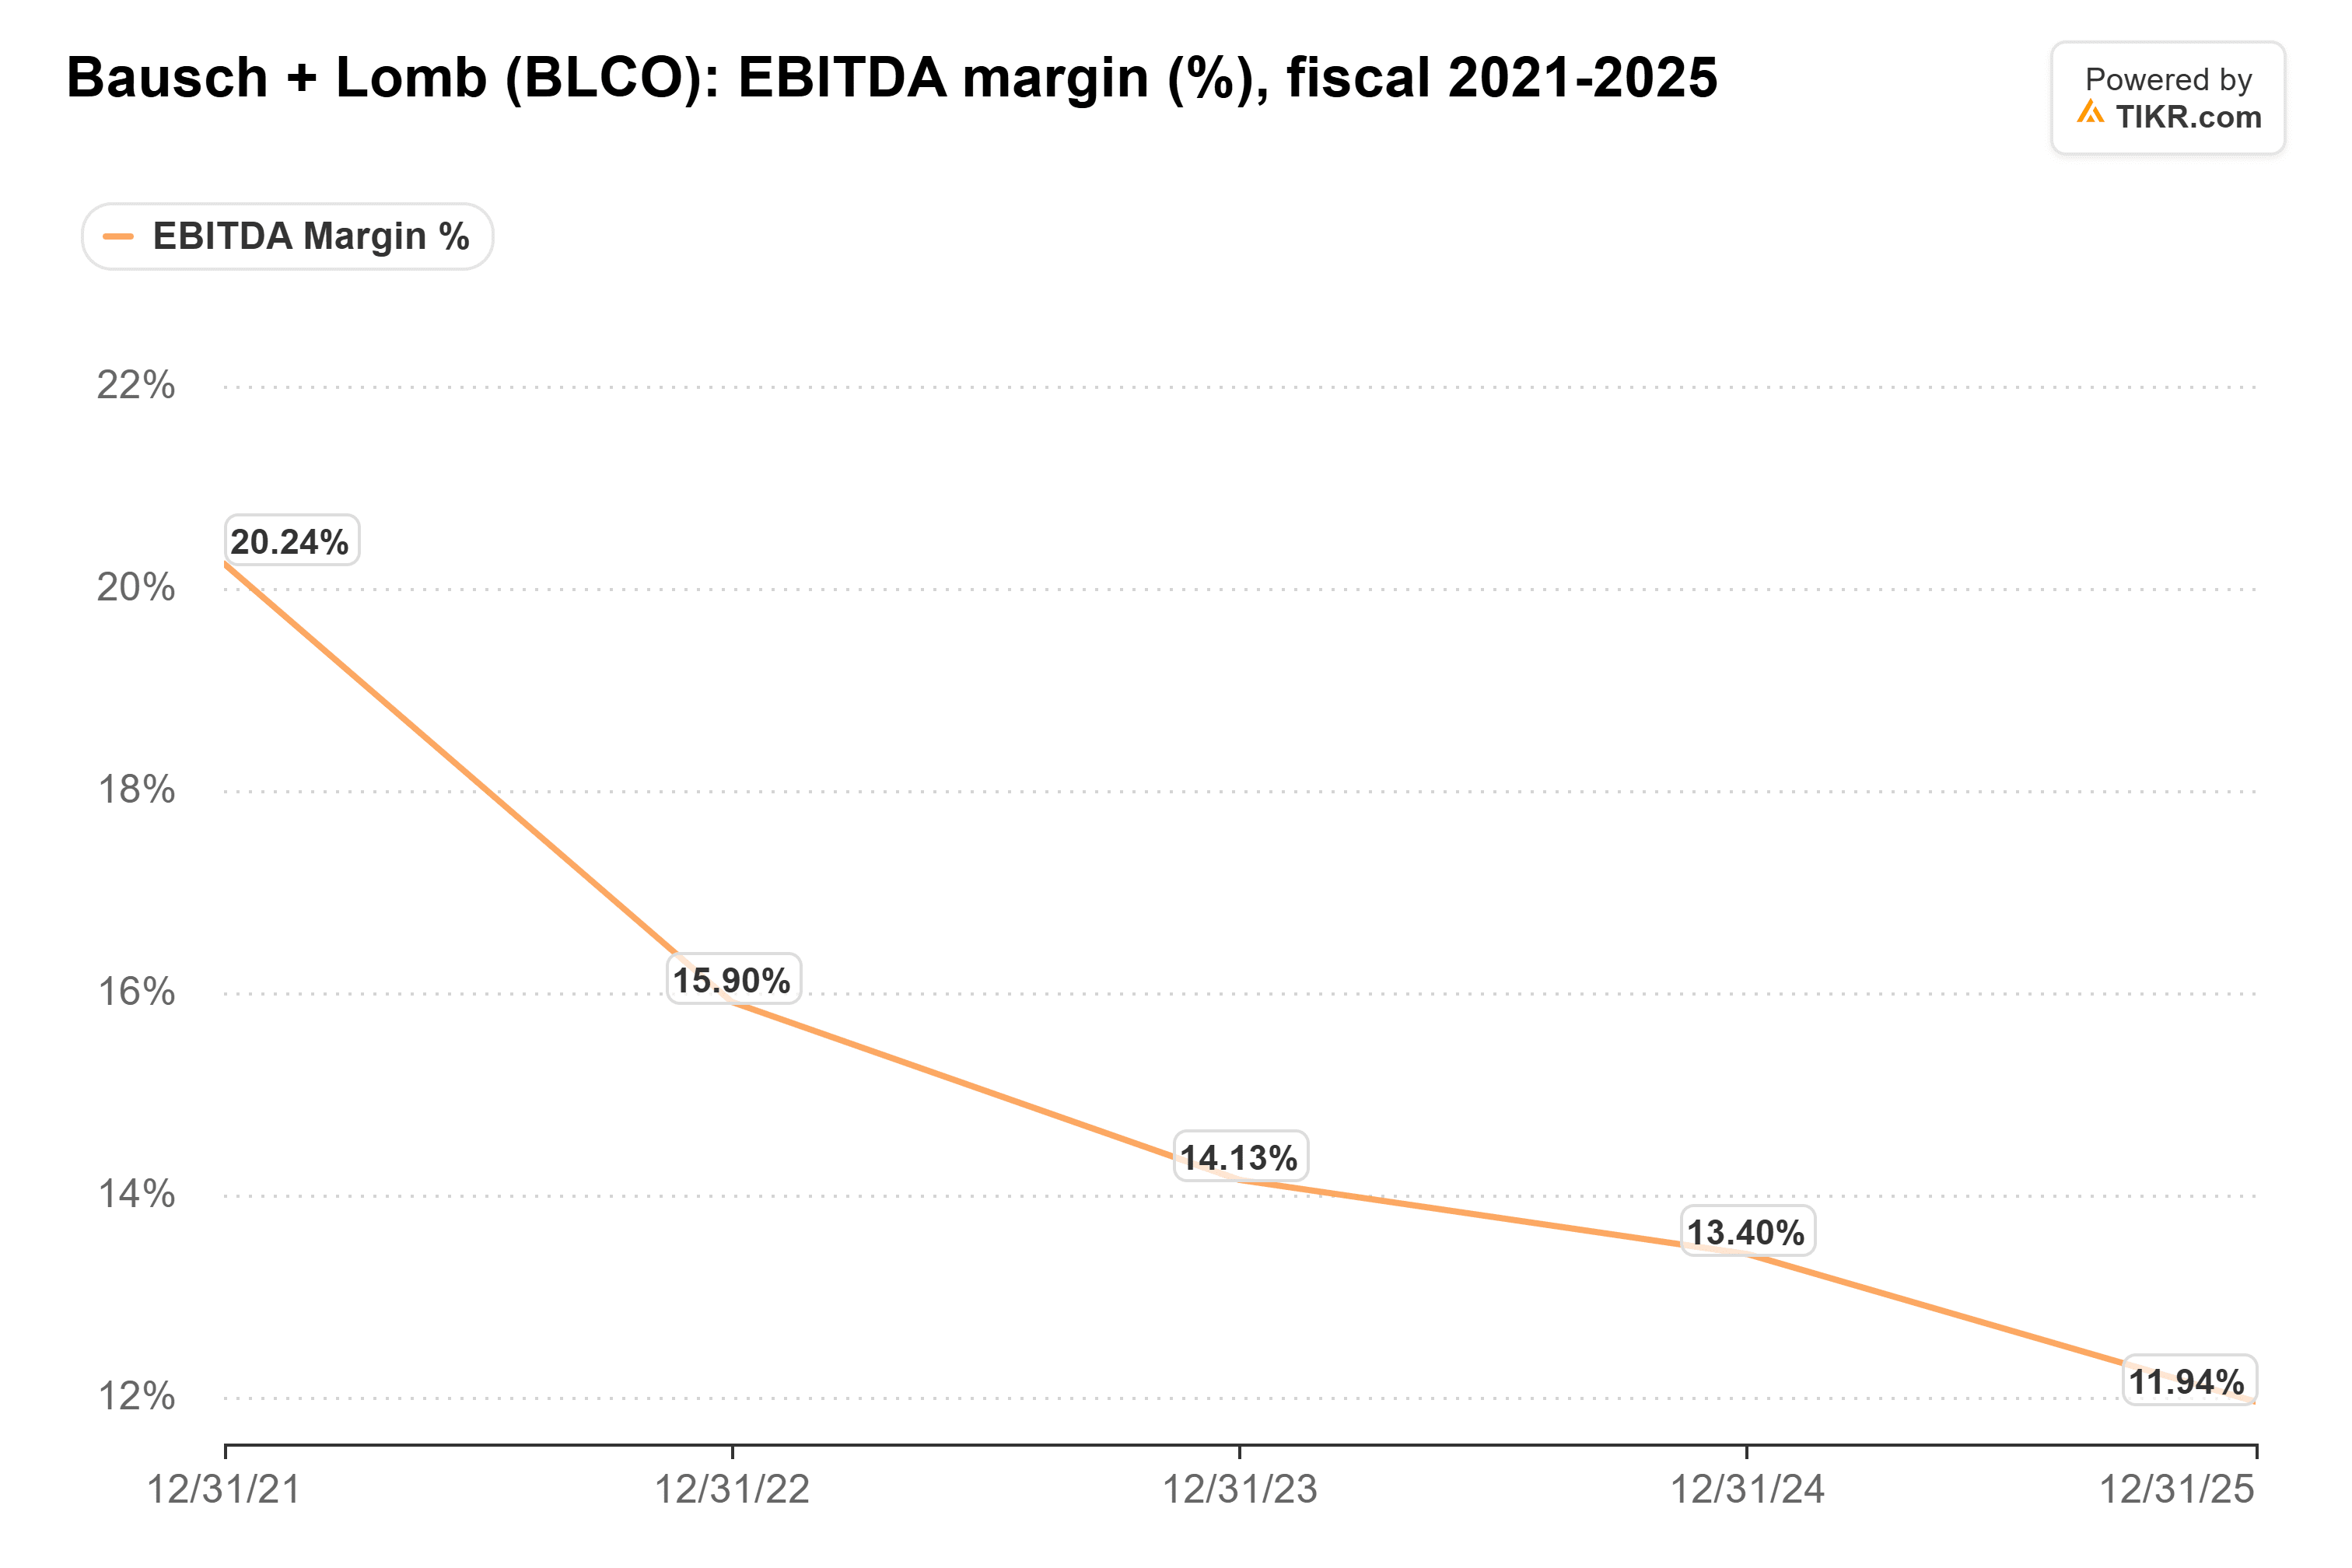
TIKR’s EBITDA margin for the company fell every year from 20.2% in fiscal 2021 to 11.9% in 2025:
MIEBO sales grew 42% to $119 million, LUMIFY 35%, and premium intraocular lenses about 70%.
Estimates should move up
Analysts expected normalized EPS to nearly triple from 2025 to 2028:

Those estimates date to Oct. 16, before a 12-cent beat and a raised EBITDA outlook, so I’d expect them to rise.
At yesterday’s close, the stock traded at 17x forward earnings, below its 21x three-year average:

At today’s price it’s about 19x, still under that average.
TIKR tracks 15 analysts on Bausch + Lomb. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Bausch + Lomb, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Bausch + Lomb’s Analyst Ratings
Cooper is the odd one out
J&J’s Vision sales rose 4.4% to $1.46 billion in the quarter ended Sept. 27, with contact lenses up 3.5% and surgical vision up 6.8%. Bausch + Lomb’s Surgical segment grew 9%. Can J&J’s surgical business keep pace when it reports in January?
CooperVision’s revenue was flat at $717.0 million in the quarter ended July 31, as Cooper cut U.S. channel inventory, and it guided to organic growth of -2% to 0% this quarter. Today Cooper also said CEO Al White is stepping down.
Is CooperVision’s slump just inventory, or lost share? Its fiscal fourth-quarter report in early December should tell us.
The margins are the reason to own it
Debt is the risk: interest expense was $95 million in the quarter, against $155 million of operating income.
Still, margins are doing the work. At a below-average multiple, the stock has room to keep climbing.
Of course, an interim CEO is in charge, and the fourth-quarter report early next year will show whether the gains hold.
So what is Bausch + Lomb stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Bausch + Lomb could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!