Key Takeaways
- Axon shares fell 27% in a week to a new 52-week low after a revenue miss and a lower 2026 outlook.
- Delayed federal Dedrone deployments drove the cut, while Motorola Solutions and Tyler Technologies point to healthy demand.
- Axon needs about $450 million of free cash flow in the fourth quarter.
- At its lowest forward P/E in five years, the stock looks oversold if that cash shows up.
Axon Enterprise (AXON) fell 27% in the week through Nov. 10 to a new 52-week low, closing at $302.54, after a third-quarter revenue miss, a lower outlook and a $1.2 billion drone bet.
But Axon’s customers aren’t pulling back. Motorola Solutions (MSI), its biggest police-tech rival, reported a record $16.6 billion backlog on Nov. 4 and slipped just 0.5% on Nov. 6, the day Axon fell 18%. Tyler Technologies (TYL), which sells into the same government budgets, posted record quarterly free cash flow of $277.0 million.
Three federal deployments slipped
Revenue of $909 million missed the roughly $937 million analysts expected. Axon now guides to about 30% growth for 2026, below its earlier 32% to 34%, because it no longer expects three federal Dedrone deployments worth about $130 million to land this year. CFO and COO Brittany Bagley said on the call, “we’re not seeing an underlying risk to demand or need for this product. It truly is just a timing piece.”
Analysts trimmed their estimates anyway, taking the 2027 EPS consensus to $9.55 from $10.51 before the report:
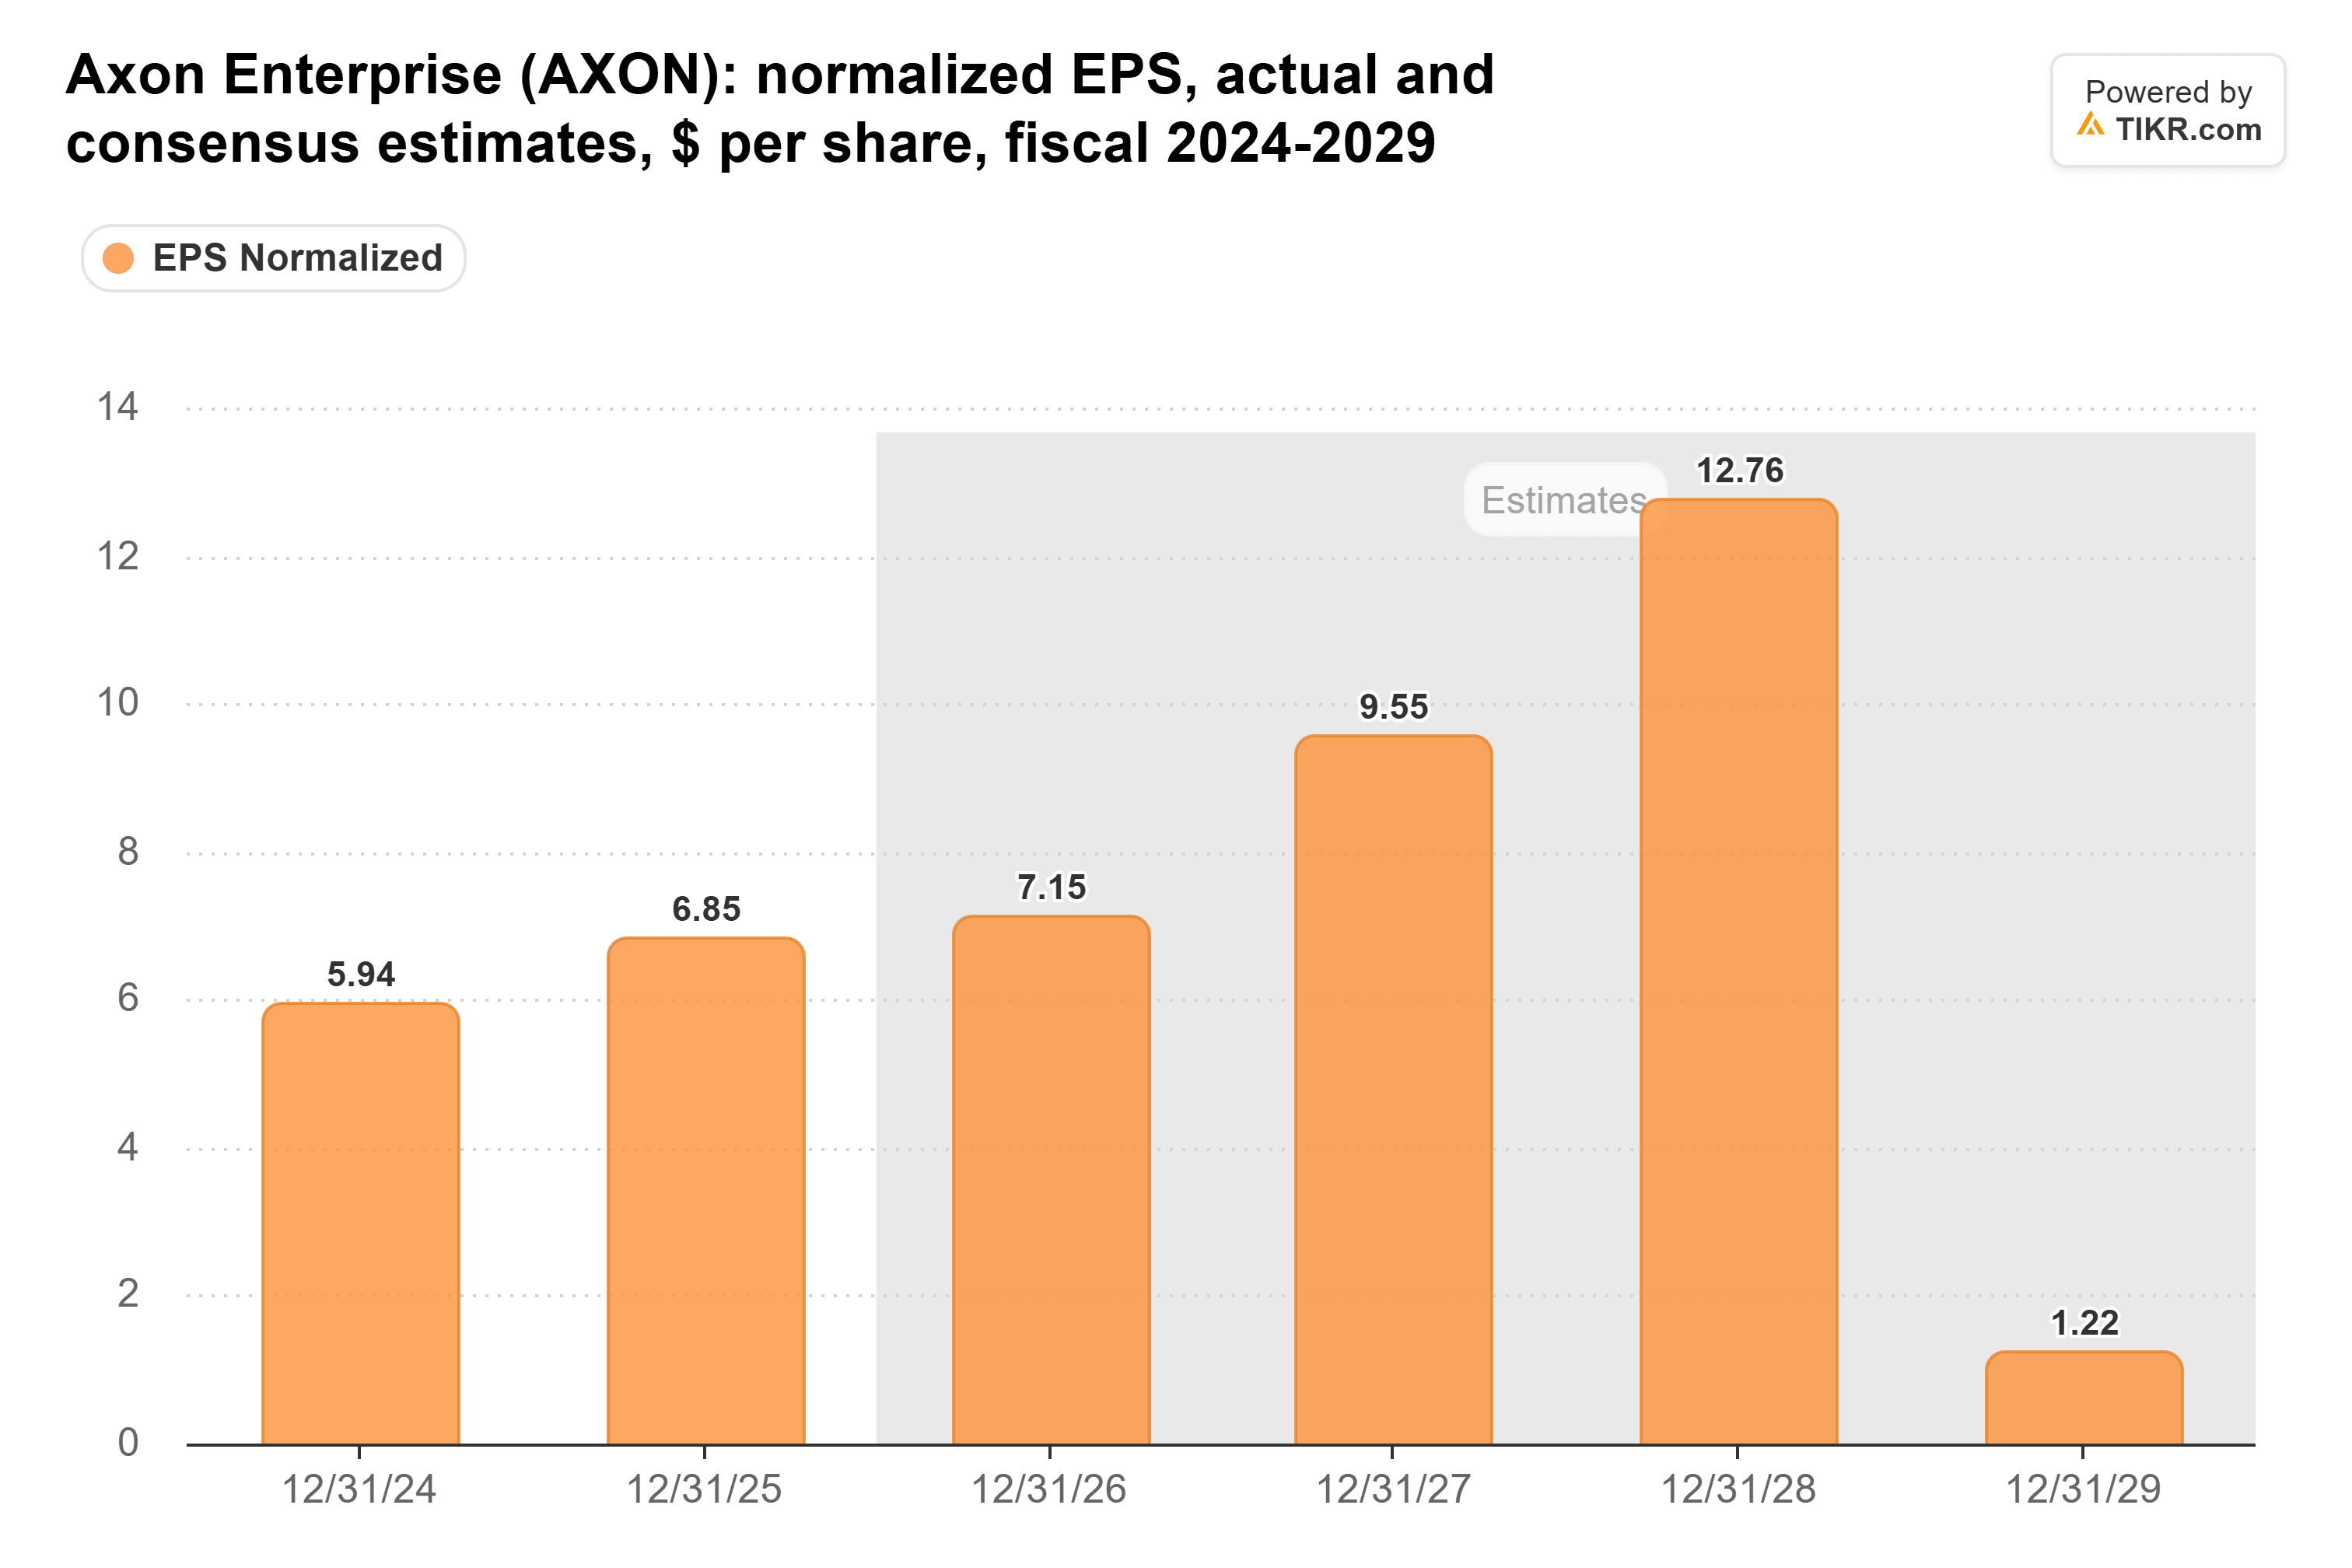
That’s still about 34% growth on this year’s estimate.
Axon needs about $450 million in one quarter
Tyler has already turned that demand into cash, and Axon still has to. Axon’s third-quarter free cash flow was an outflow of $19 million. It also cut its 2026 target to $350 million to $400 million, from $450 million. With the first nine months in the red, hitting that range takes roughly $425 million to $475 million in the fourth quarter alone, far more than Axon has produced in any quarter of the past two years.
The Skydio deal, paid about 60% in cash and 40% in Axon stock, makes Axon the drone maker’s exclusive public-safety distributor in the U.S. and Canada. Motorola is taking a different path: it led a $125 million funding round in drone maker BRINC in July and closed its $1.3 billion purchase of D-Fend, a Dedrone rival, in the third quarter.
TIKR tracks 21 analysts on Axon Enterprise. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Axon Enterprise, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Axon Enterprise’s Analyst Ratings
Cheaper than it’s been in five years
The consensus target is now $541, down from $680 in late October. Axon’s forward P/E was 36x at the Nov. 6 close, its lowest in five years and far below its 77x average:
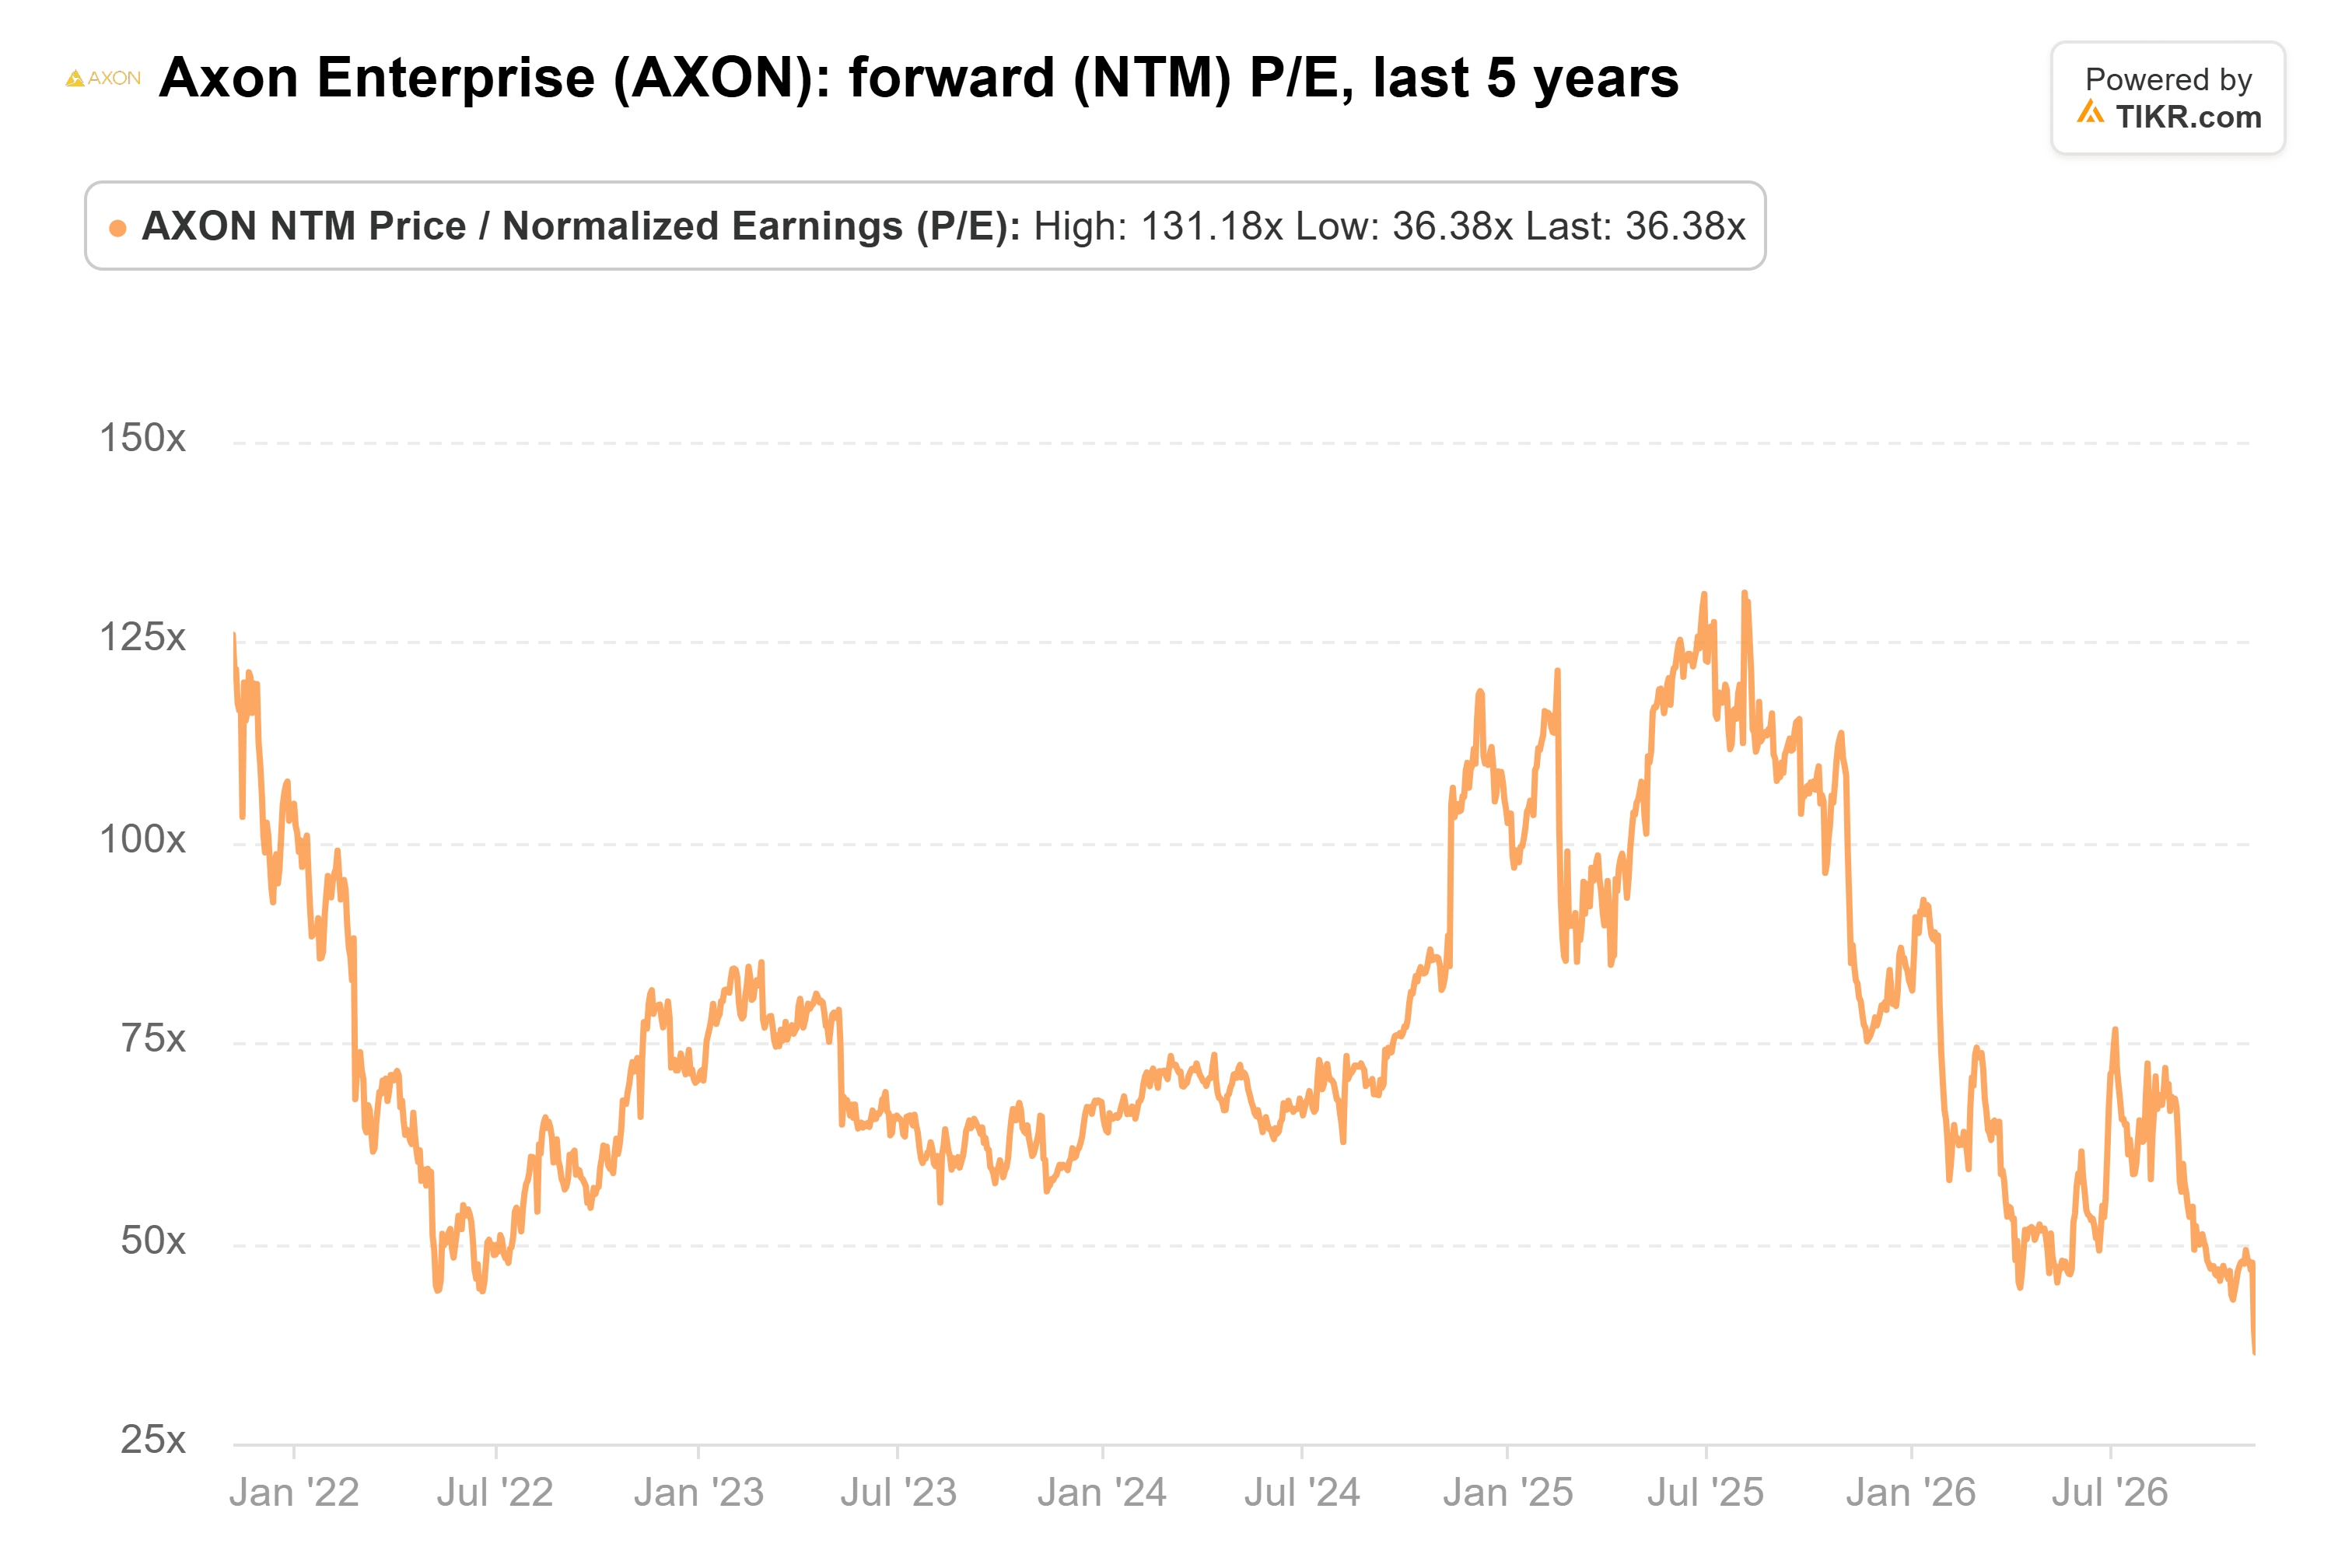
The selling looks overdone. Three deployments slipped, software is still growing 43%, and the stock is priced as if the delays never end. Even so, the fourth-quarter report expected in late February has to show those deployments landing and close to $450 million of cash.
So what is Axon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Axon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!