Key Takeaways
- Astera Labs (ALAB) fell 26% over five trading sessions, closing at $191 on November 6 despite record third-quarter revenue and strong guidance.
- Marvell Technology (MRVL) announced a $115 billion acquisition agreement, while Intel (INTC) reported 78% Data Center and AI revenue growth and Advanced Micro Devices (AMD) posted 97% data center growth.
- Astera’s revenue surged 154% to $584.9 million, while fourth-quarter guidance of $730 million to $750 million points to continued growth despite customer concentration risks.
What Happened?
Astera Labs (ALAB) stock fell approximately 26% over five trading sessions, declining from $259 on October 30 to $191 on November 6 despite strong quarterly results.
The selloff reflected concerns about AI infrastructure valuations and whether accelerating technology spending will deliver sustainable returns.
Marvell Technology (MRVL) announced an all-stock agreement to acquire Lumentum at an implied enterprise value of $115 billion, highlighting the growing importance of optical connectivity in AI data centers.
The deal could intensify competition in AI connectivity, although its direct implications for Astera remain uncertain.
Meanwhile, Intel (INTC) reported $7.3 billion in Data Center and AI revenue, up 78% year over year.
Advanced Micro Devices (AMD) also reported $8.5 billion in data center revenue, representing 97% annual growth.
Astera reported record third-quarter revenue of $584.9 million, increasing 154% year over year and 49% sequentially.
Non-GAAP earnings reached $1.32 per share, while non-GAAP gross margin stood at 72.4%.
CEO Jitendra Mohan attributed the performance to “broad-based growth led by Scorpio,” which became Astera’s largest product family by revenue.
Nevertheless, the stock’s decline suggests investors remain concerned about future growth expectations and valuation.
Strong Revenue Growth Raises Expectations for 2027
Astera guided for fourth-quarter revenue of $730 million to $750 million, exceeding the earlier $648 million to $668 million threshold needed to support its previous 2026 revenue consensus.
With $1.29 billion generated through September, the outlook implies approximately $2.02 billion to $2.04 billion in full-year revenue.
That represents roughly 137% to 139% growth compared with the company’s 2025 revenue of $852.5 million.
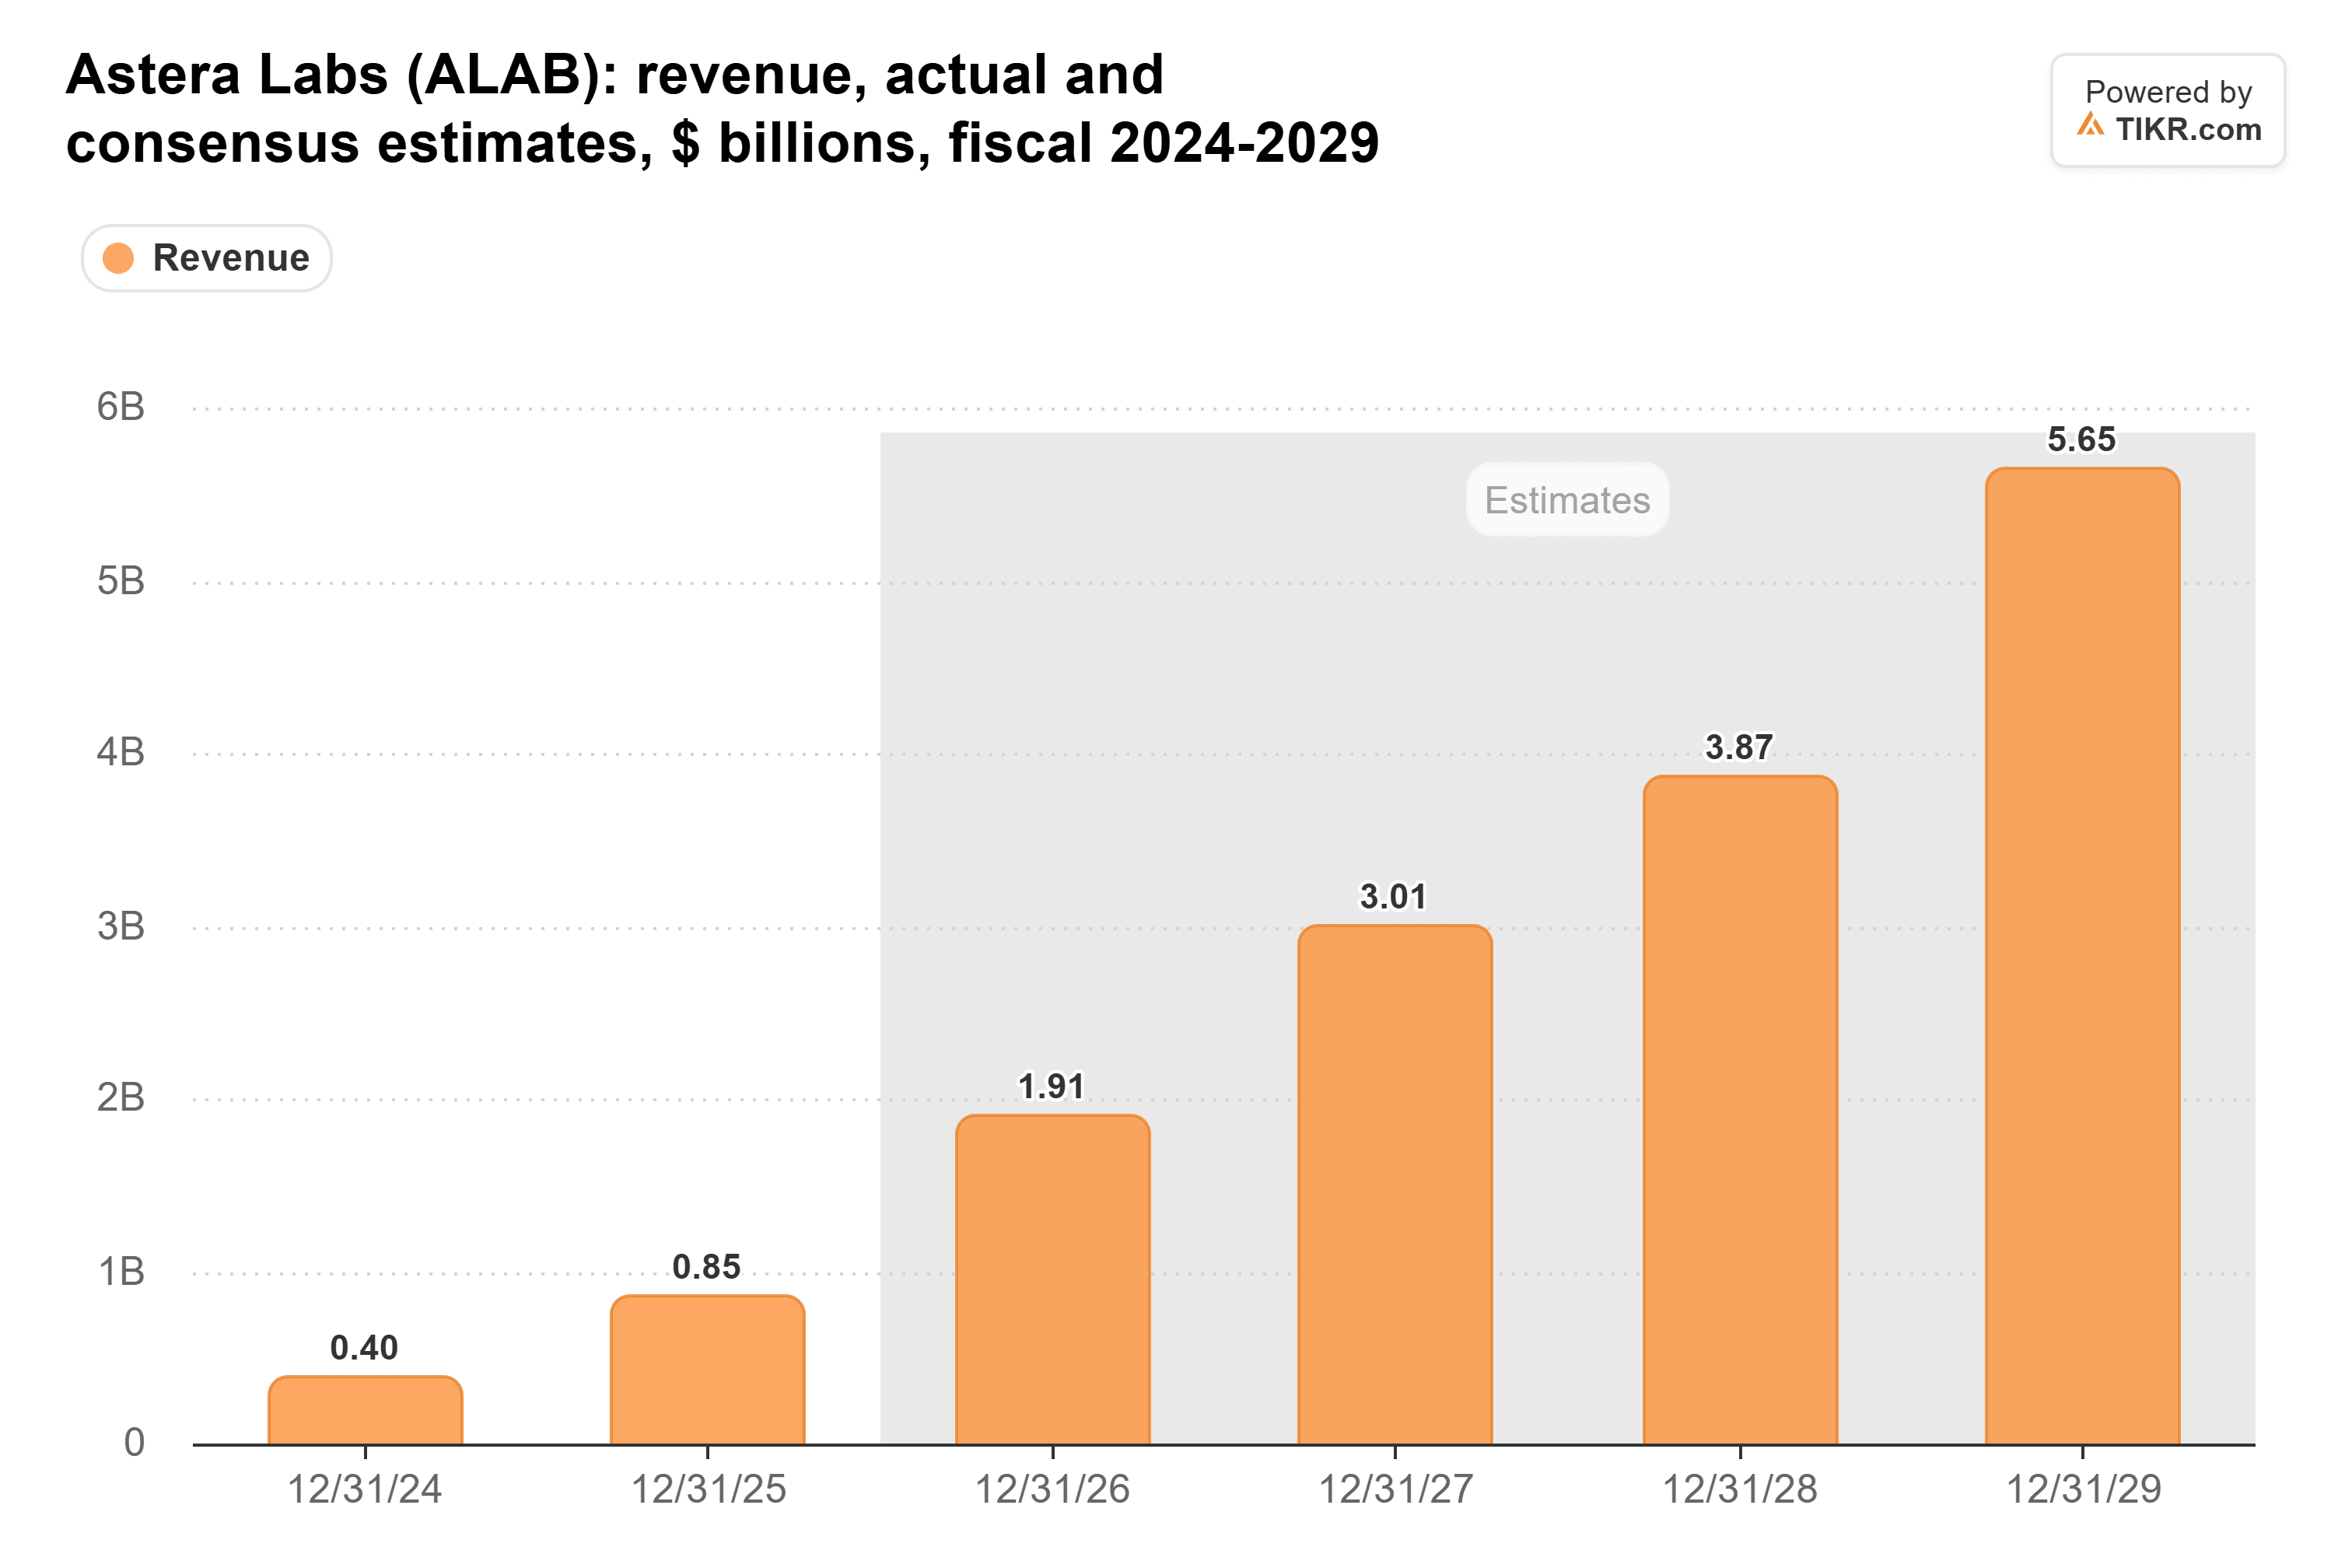
Astera’s Scorpio fabric switches, Aries 7 connectivity products, and Leo memory solutions create additional opportunities as AI infrastructure becomes more complex.
However, maintaining profitability remains essential.
Management expects approximately 72% non-GAAP gross margin in Q4, compared with 72.4% in Q3.
Sustained product adoption and stable margins will be important for supporting earnings growth in 2027.
Is Astera Labs Stock Undervalued After the Selloff?
Astera Labs appears potentially undervalued after its sharp decline, although substantial growth expectations and customer concentration create meaningful risks.
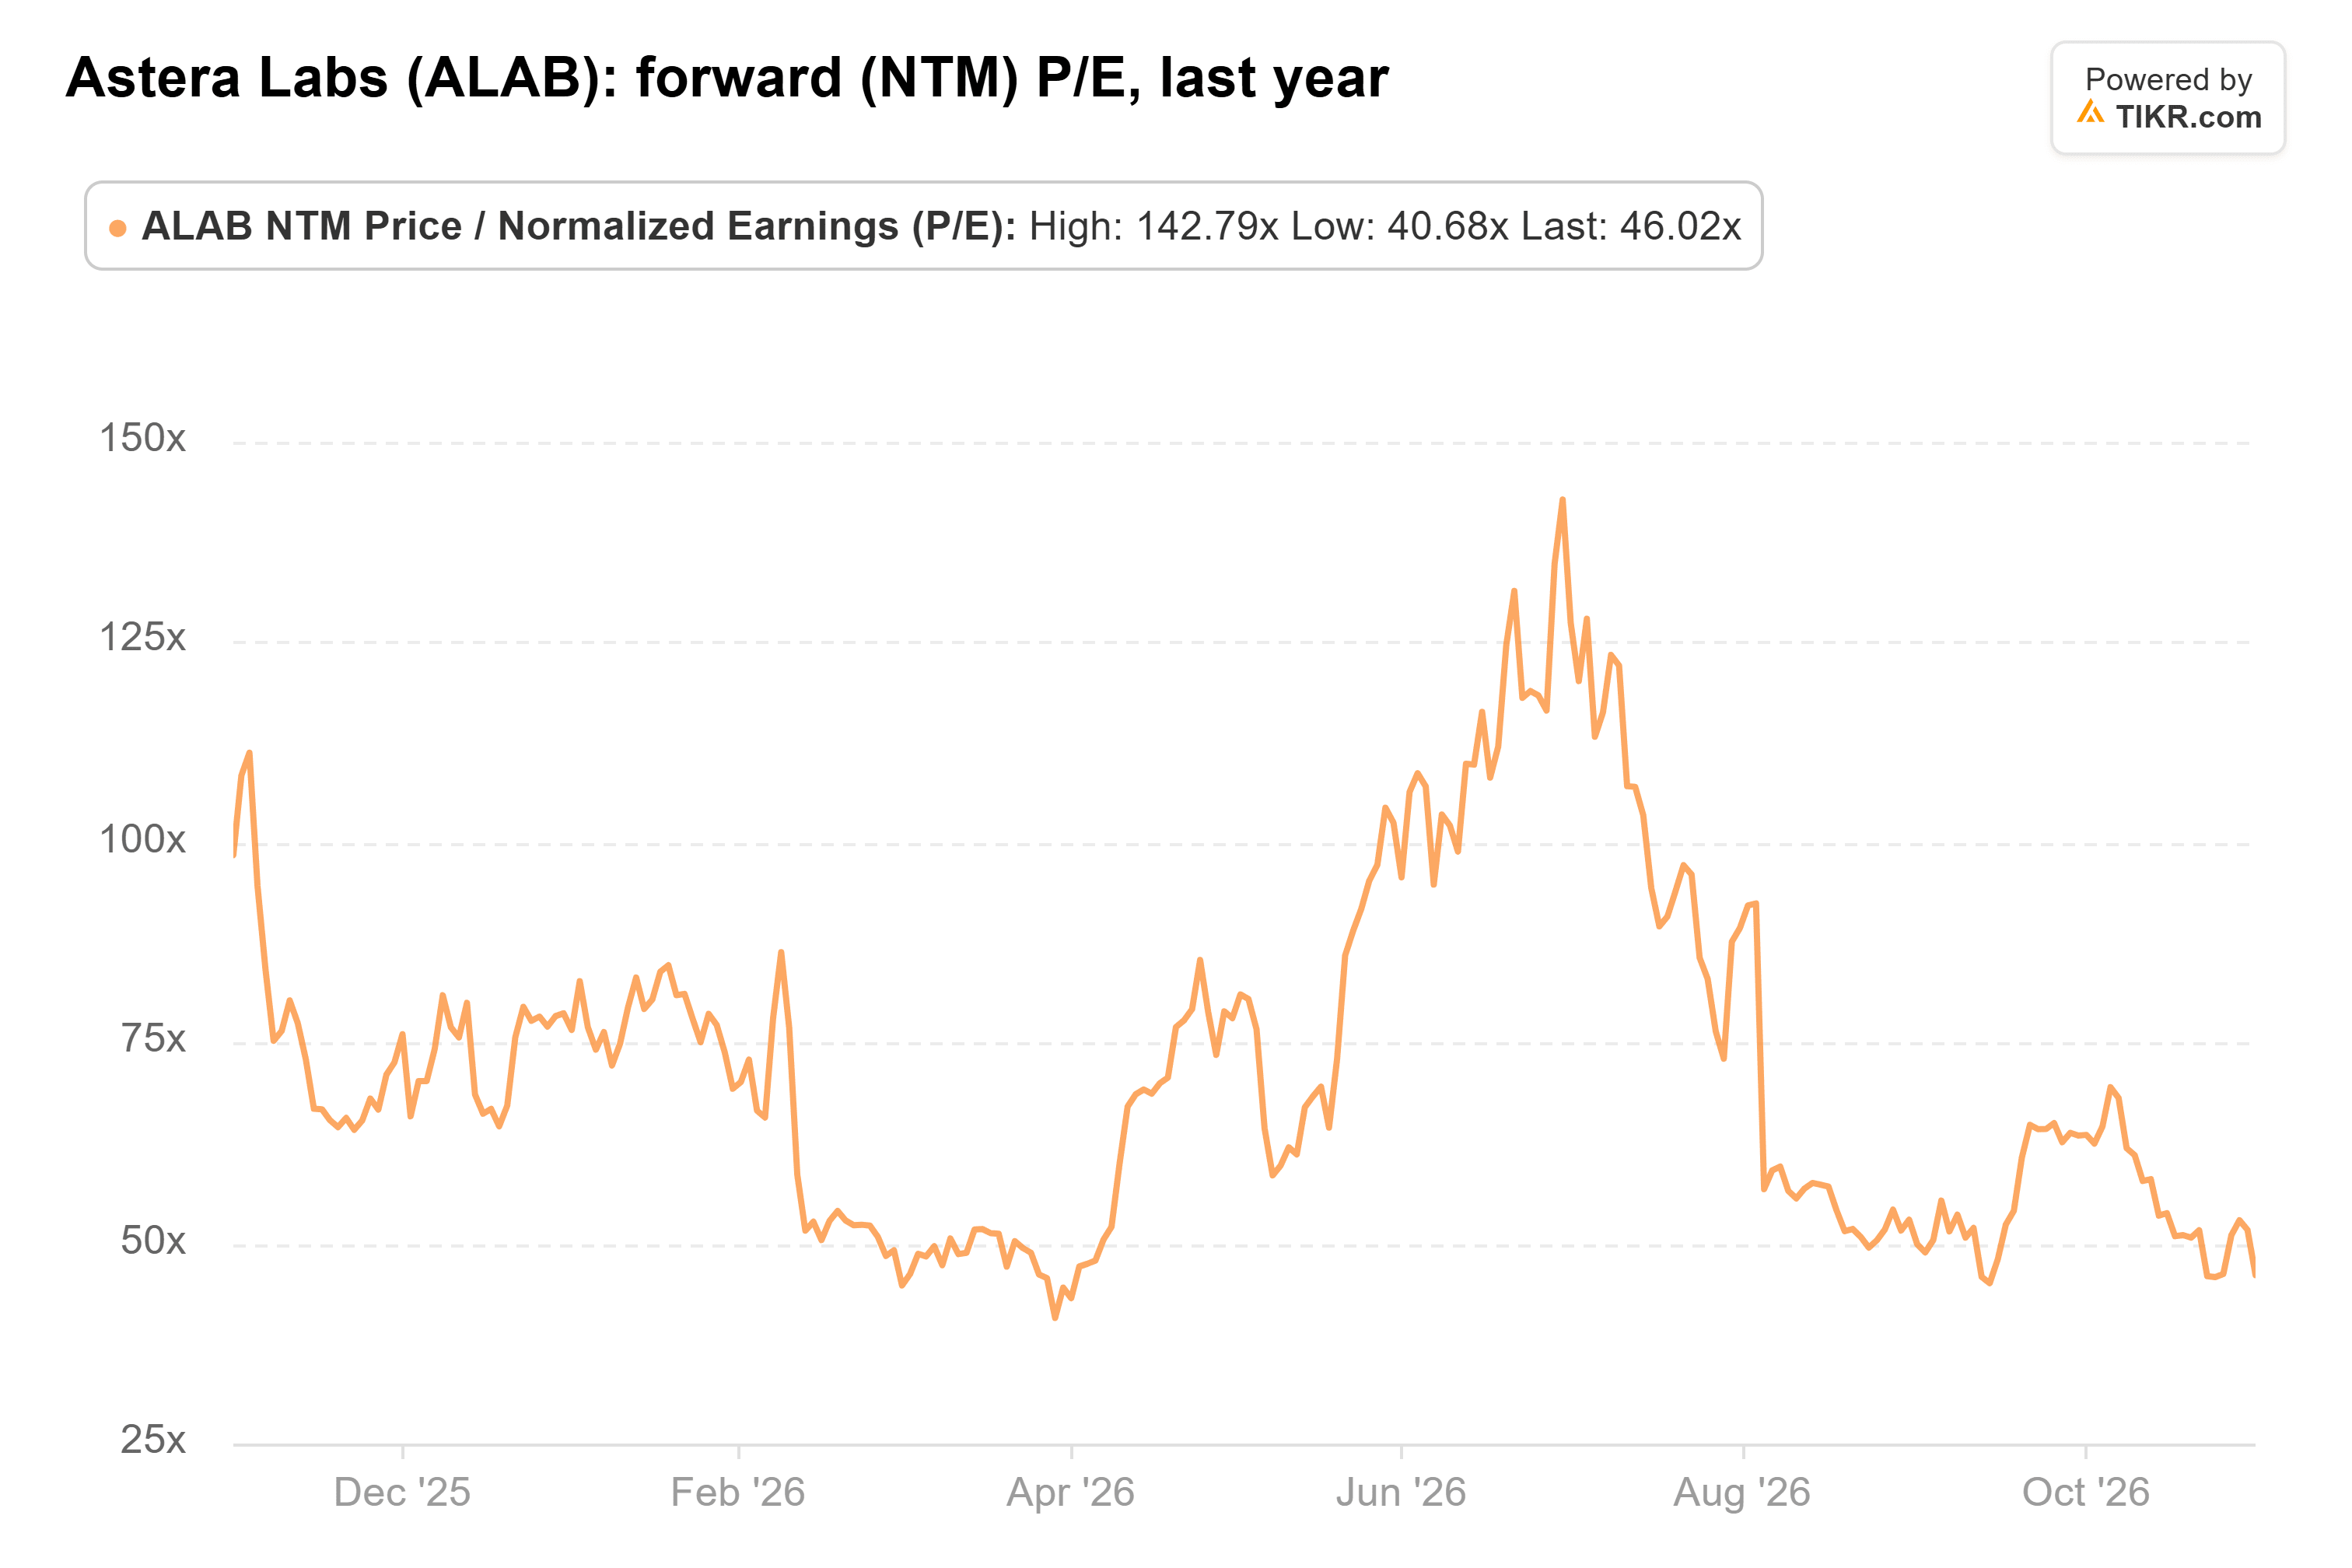
Following its sharp decline to approximately $191 per share, Astera’s valuation looks more attractive, although its earnings outlook remains critical to determining whether the stock is undervalued.
Wall Street’s analyst price targets suggest potential upside, but Astera’s future valuation depends on continued earnings growth and sustained demand for AI connectivity products.
However, Astera’s three largest end customers accounted for approximately 86% of 2025 revenue, making the company vulnerable to changes in hyperscaler spending.
Over the next 12 months, Scorpio adoption, stable gross margins, and sustained AI infrastructure investment will determine whether earnings growth supports a higher valuation.
Astera looks potentially undervalued following the selloff, but customer concentration and demanding growth expectations make it a higher-risk AI investment.
So what is Astera Labs stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Astera Labs could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!