Key Takeaways
- Arm posted record fiscal second-quarter revenue of $1.44 billion, up 27%, yet shares slid about 12% the next day as chip stocks sold off.
- Licensing revenue jumped 50% to $773 million, while royalties rose only 8% and missed estimates as memory prices weighed on smartphones.
- Bank of America flagged “circular financing concerns” over SoftBank, though related parties made up a smaller share of revenue than a year ago.
- Arm guided third-quarter revenue to $1.54 billion, and its CEO calls $2 billion in AGI CPU sales “now very achievable.”
Arm Holdings (ARM) just posted the best second quarter in its history, and the stock got hit anyway.
Revenue rose 27% to $1.44 billion for the quarter ended September 30, ahead of the $1.38 billion analysts expected. Yet shares slid about 12% on November 5 as chip stocks had their worst day since March 2020. Advanced Micro Devices (AMD), the x86 rival Arm keeps taking server share from, dropped 15% that day.
The long-term story got stronger. Oracle (ORCL) plans to offer Arm’s own AGI CPU in its cloud in 2027. Meanwhile, CEO Rene Haas told Reuters that $2 billion in AGI CPU sales is “now very achievable.”
But the quarter also exposed a lopsided mix, weaker cash flow and a SoftBank question that won’t go away.
Licensing carried the whole beat
Licensing did most of the lifting this quarter:
- License and other revenue rose 50% to $773 million, against estimates near $625 million.
- Royalty revenue grew 8% to $670 million, short of the roughly $721 million expected.
- Adjusted EPS came in at $0.52, ahead of the $0.47 consensus.
Royalties are the steadier stream, so that miss mattered more. Memory prices squeezed the smartphone market, and that offset data center royalties that doubled year over year. Arm calls licensing a leading indicator for royalties, so this quarter’s 50% jump should show up there later.
On the bottom line, the trend looks cleaner…
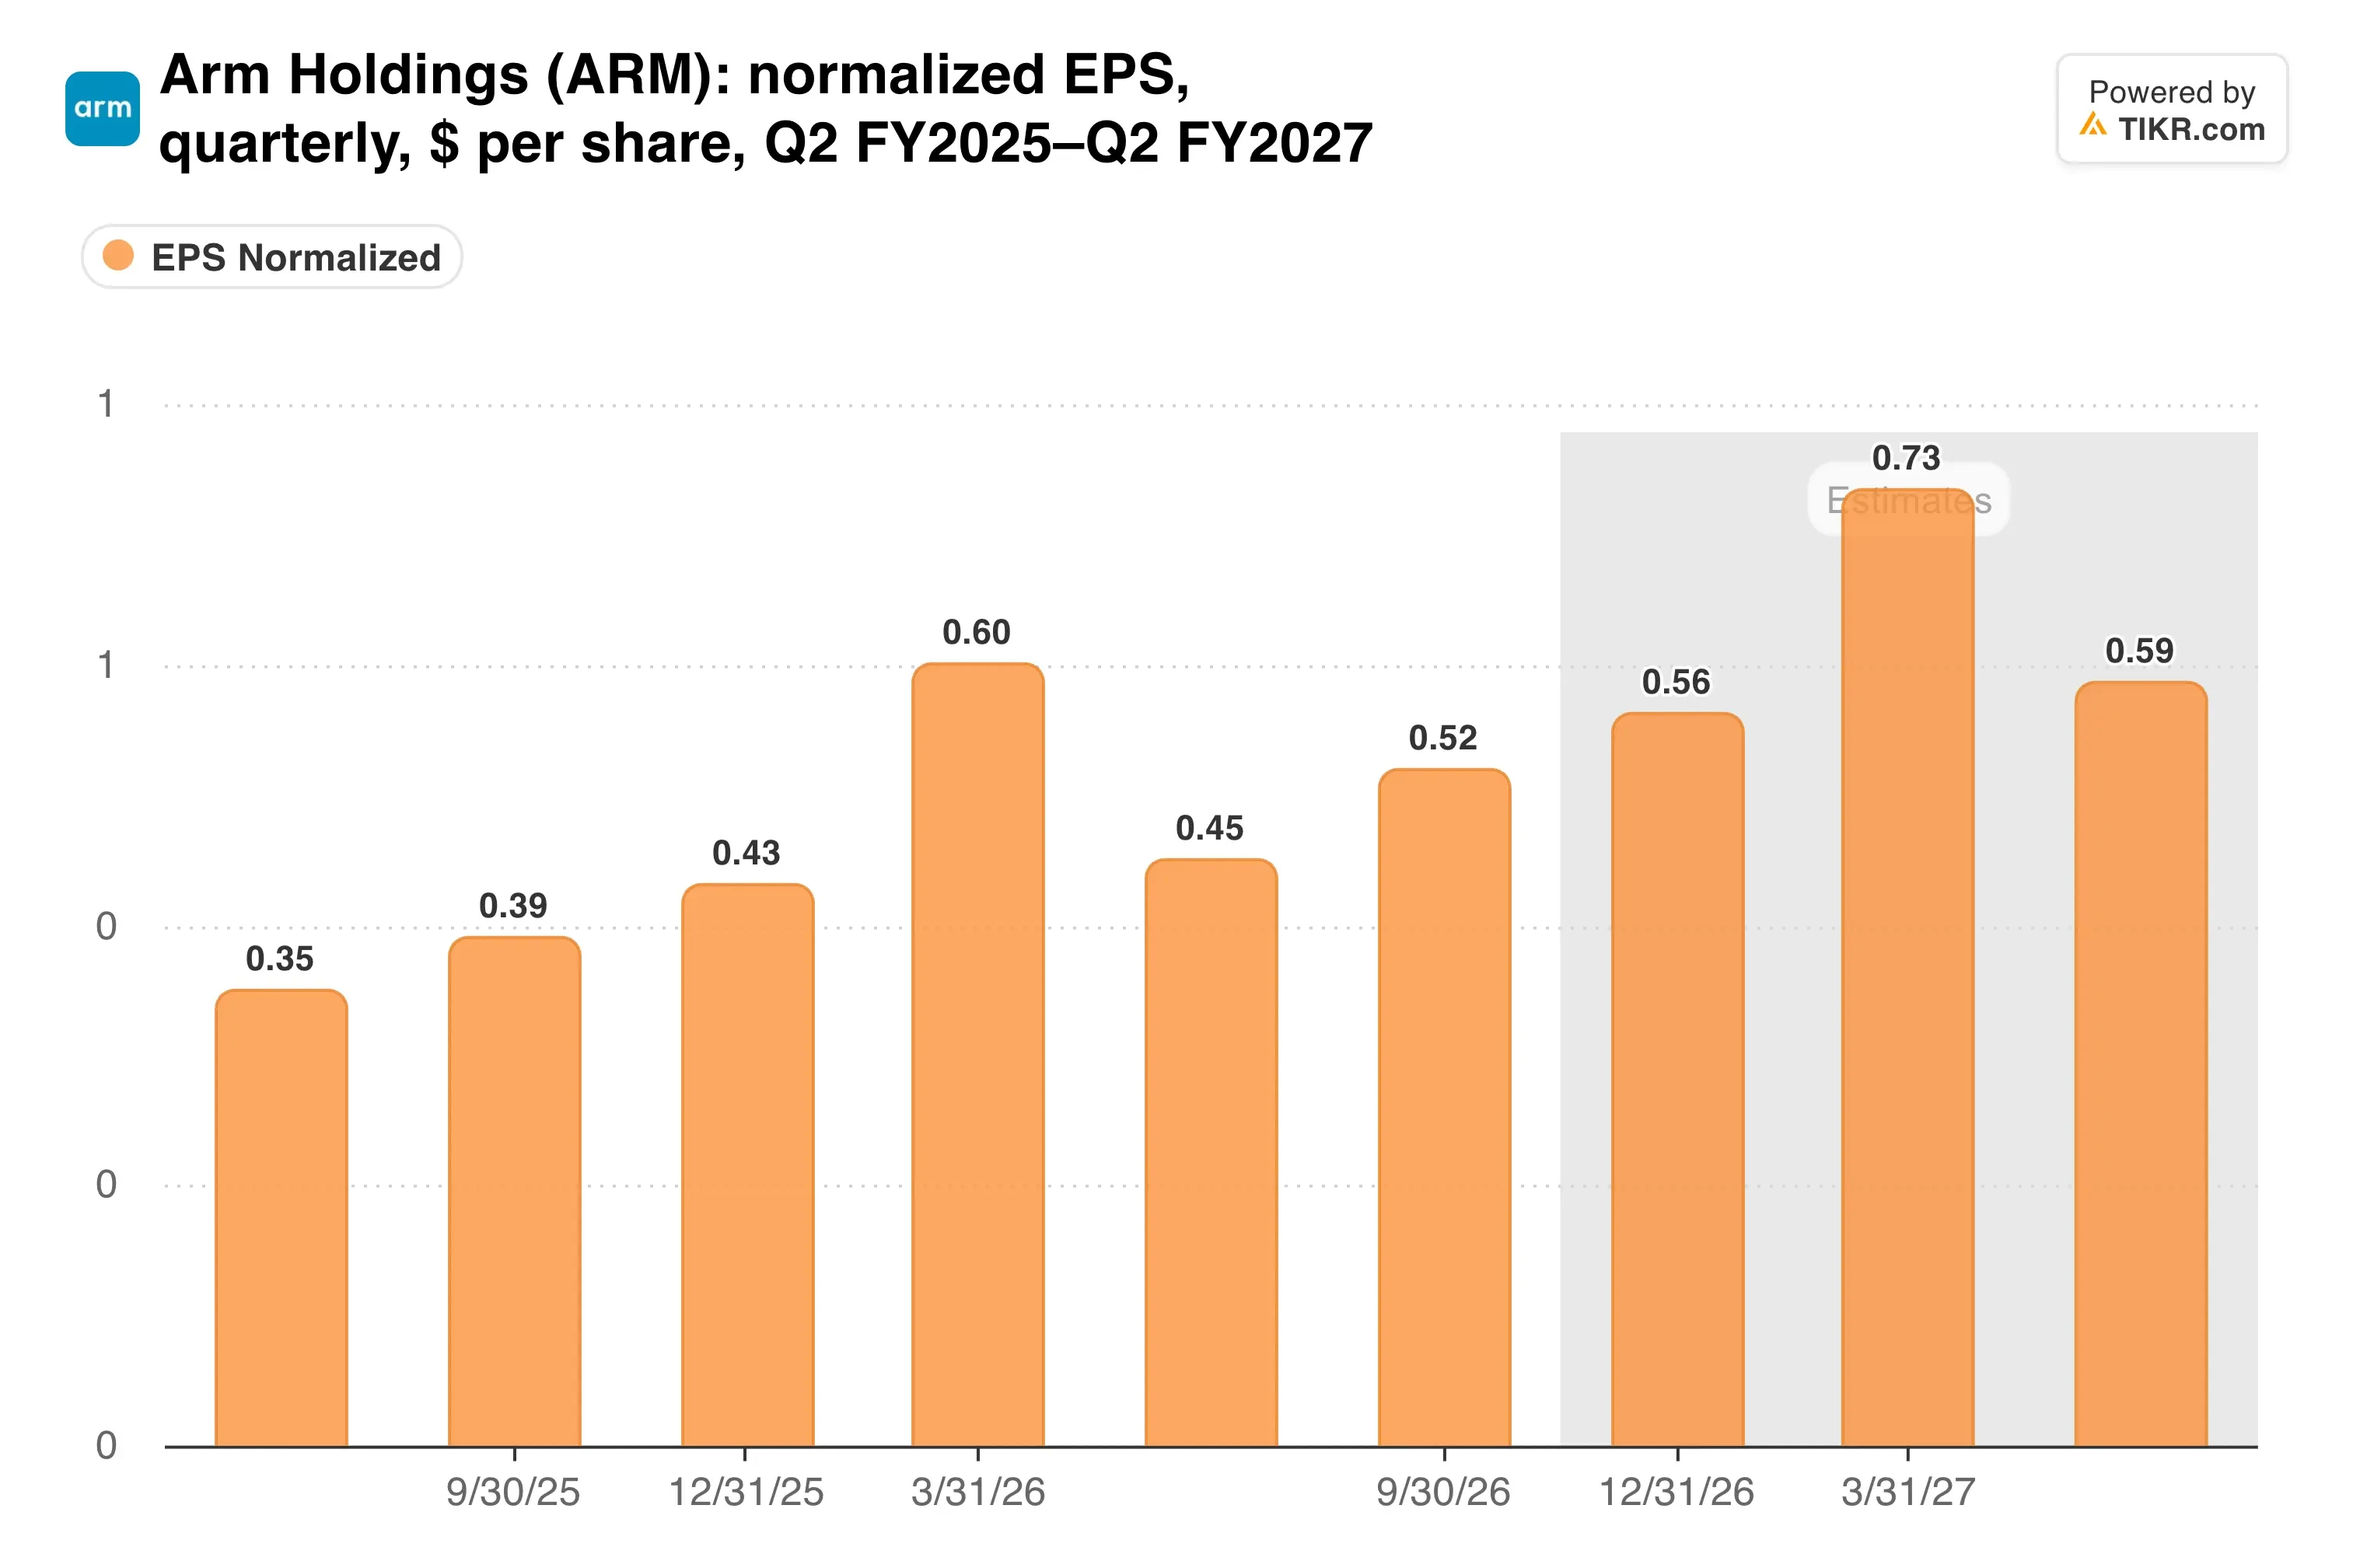
Adjusted EPS rose 33% from $0.39 a year earlier, even as Arm kept increasing R&D spending.
Two engines in the data center
The bull case rests on data centers. Arm-based chips went from 15% of server deployments at the top hyperscalers in 2024 to more than 50% in 2025. That share should pass 60% by the end of 2026, Arm expects.
The AGI CPU is the second engine. Arm launched it in March with $1 billion in orders, and first deliveries are due in its fiscal fourth quarter. In testing Arm cited, the chip delivered roughly double the performance per rack of AMD’s EPYC 9755.
So where does revenue go from here?
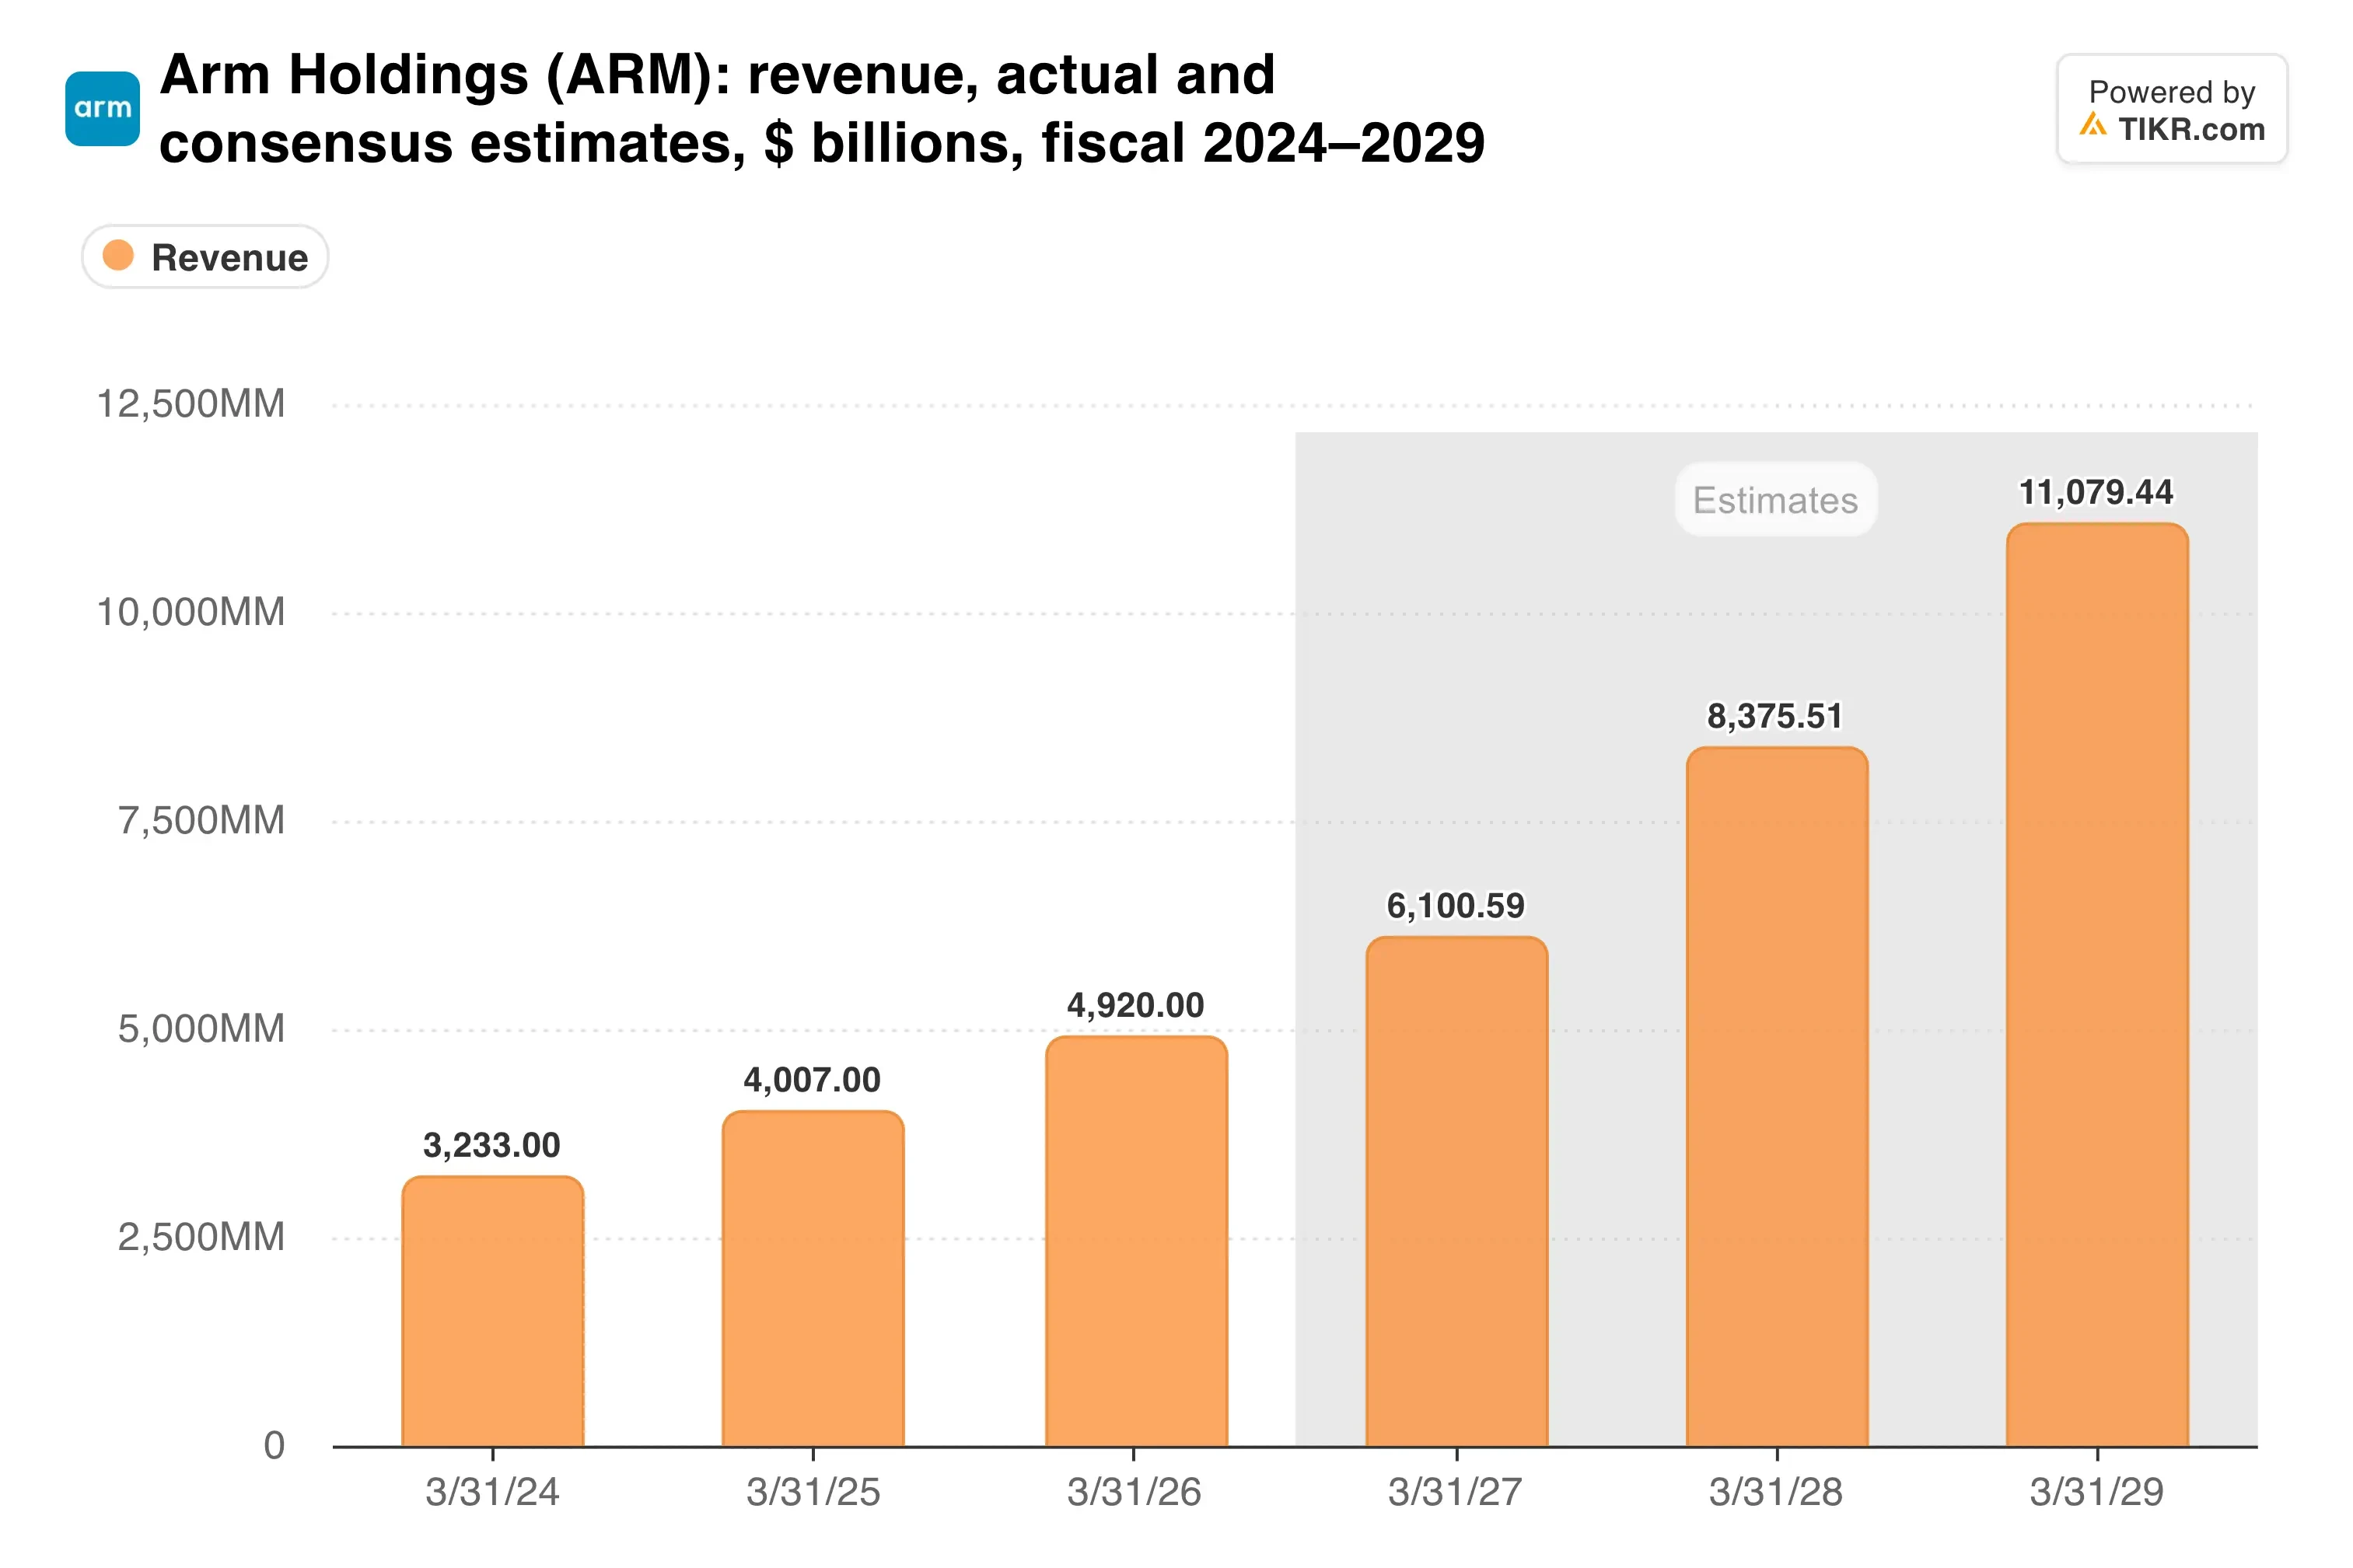
Third-quarter guidance of $1.54 billion implies about 24% growth. Analysts expected $1.53 billion, so the outlook barely cleared the bar.
TIKR tracks 43 analysts on Arm Holdings. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Arm Holdings, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Arm Holdings’ Analyst Ratings
Cash and SoftBank cloud the picture
GAAP results look far weaker. Net income fell 45% to $130 million as share-based compensation jumped to $376 million from $265 million. Still, adjusted operating margin widened to 44.2% from 41.1%.
Cash flow, meanwhile, moved the other way.
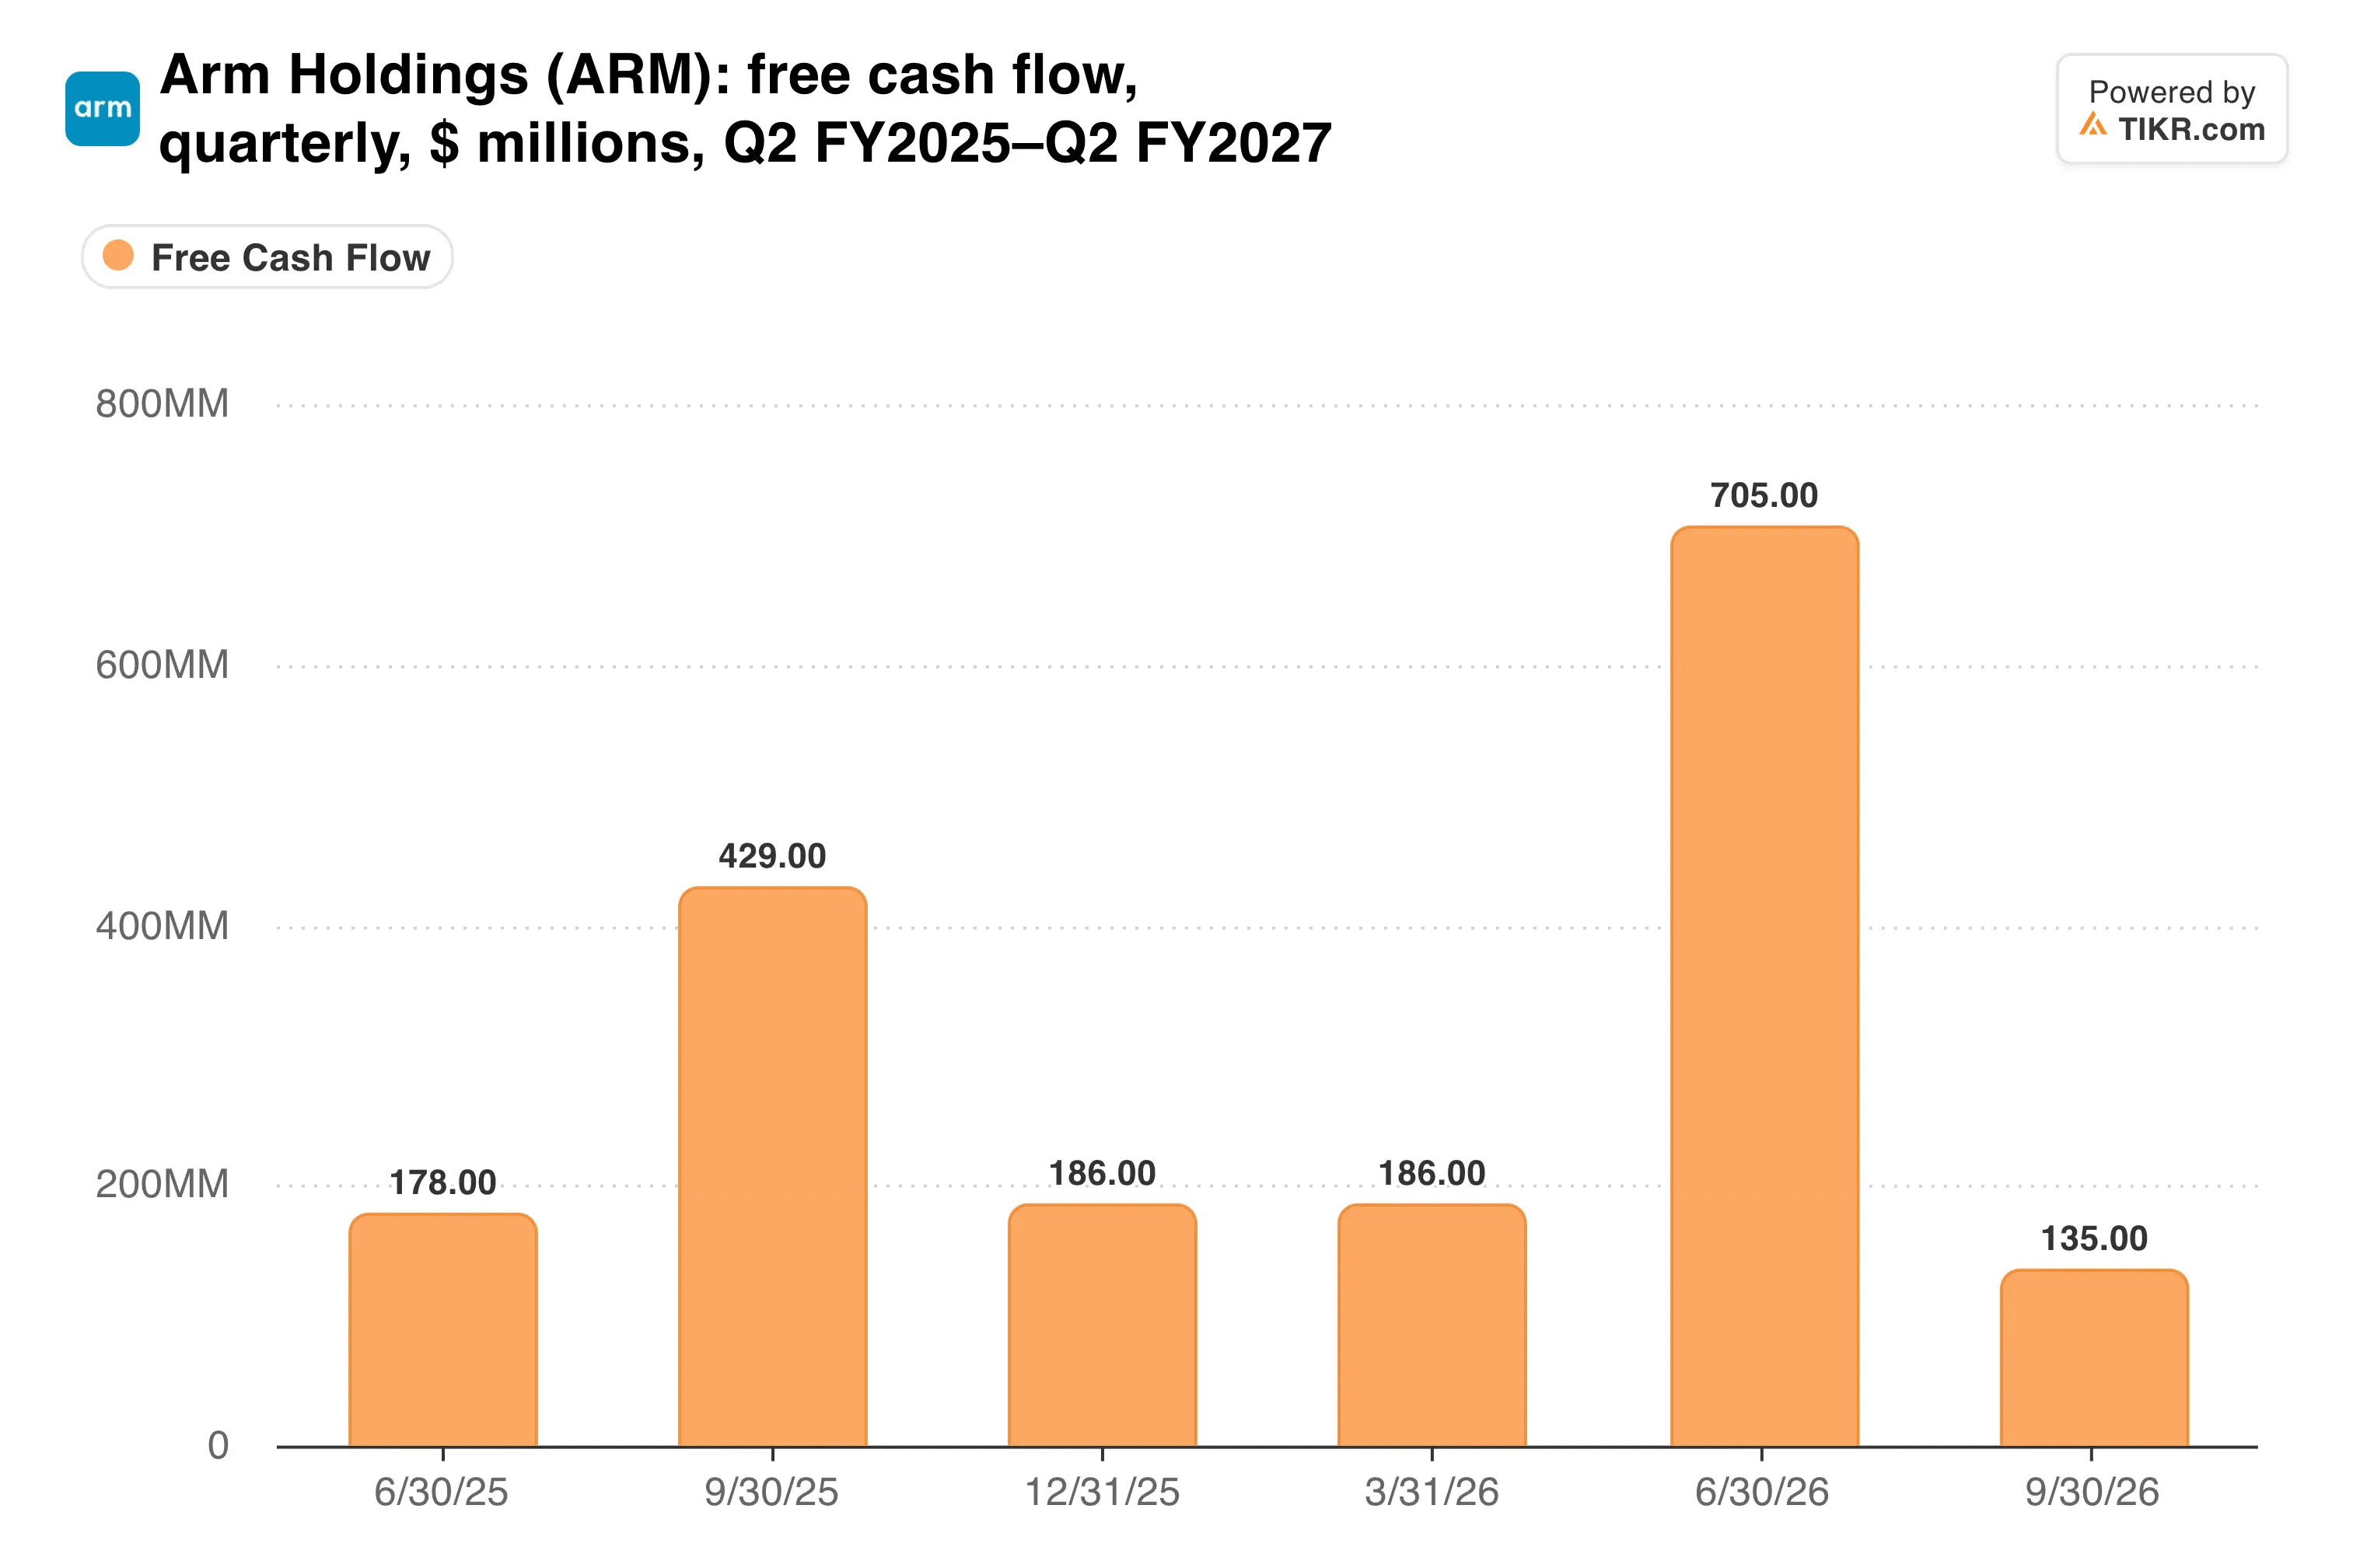
Free cash flow fell to $110 million from $411 million a year earlier, though the trailing twelve-month total held near $1.1 billion.
Then there is SoftBank. Bank of America’s Vivek Arya wrote that “Arm’s increasing dependence on SoftBank for Licensing revenue could pose circular financing concerns.” The filing complicates that view. Related parties supplied $424 million, or 29% of revenue, down from 37% a year ago, while outside customers grew 43%.
Qualcomm also lingers, since a Delaware jury awarded it just $2 but left the royalty disputes to a judge.
My take: Arm’s business looks healthier than a 12% one-day drop suggests, and the data center share gains are real. But licensing can be lumpy, and I’d want royalties to reaccelerate before trusting the beat. Selling finished chips will also test gross margins that have run near 98%.
The next test is the fiscal third-quarter report, expected in early February 2027. It should show whether royalties catch up and whether AGI CPU deliveries stay on schedule.
So what is Arm stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Arm could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!