Key Takeaways
- Applied Materials gained 11% in a week as chip stocks rebounded, Lam Research and KLA included, and CoreWeave’s results eased AI fears.
- A record quarter beat estimates, but a soft guide and 13 target cuts gave back part of the gain.
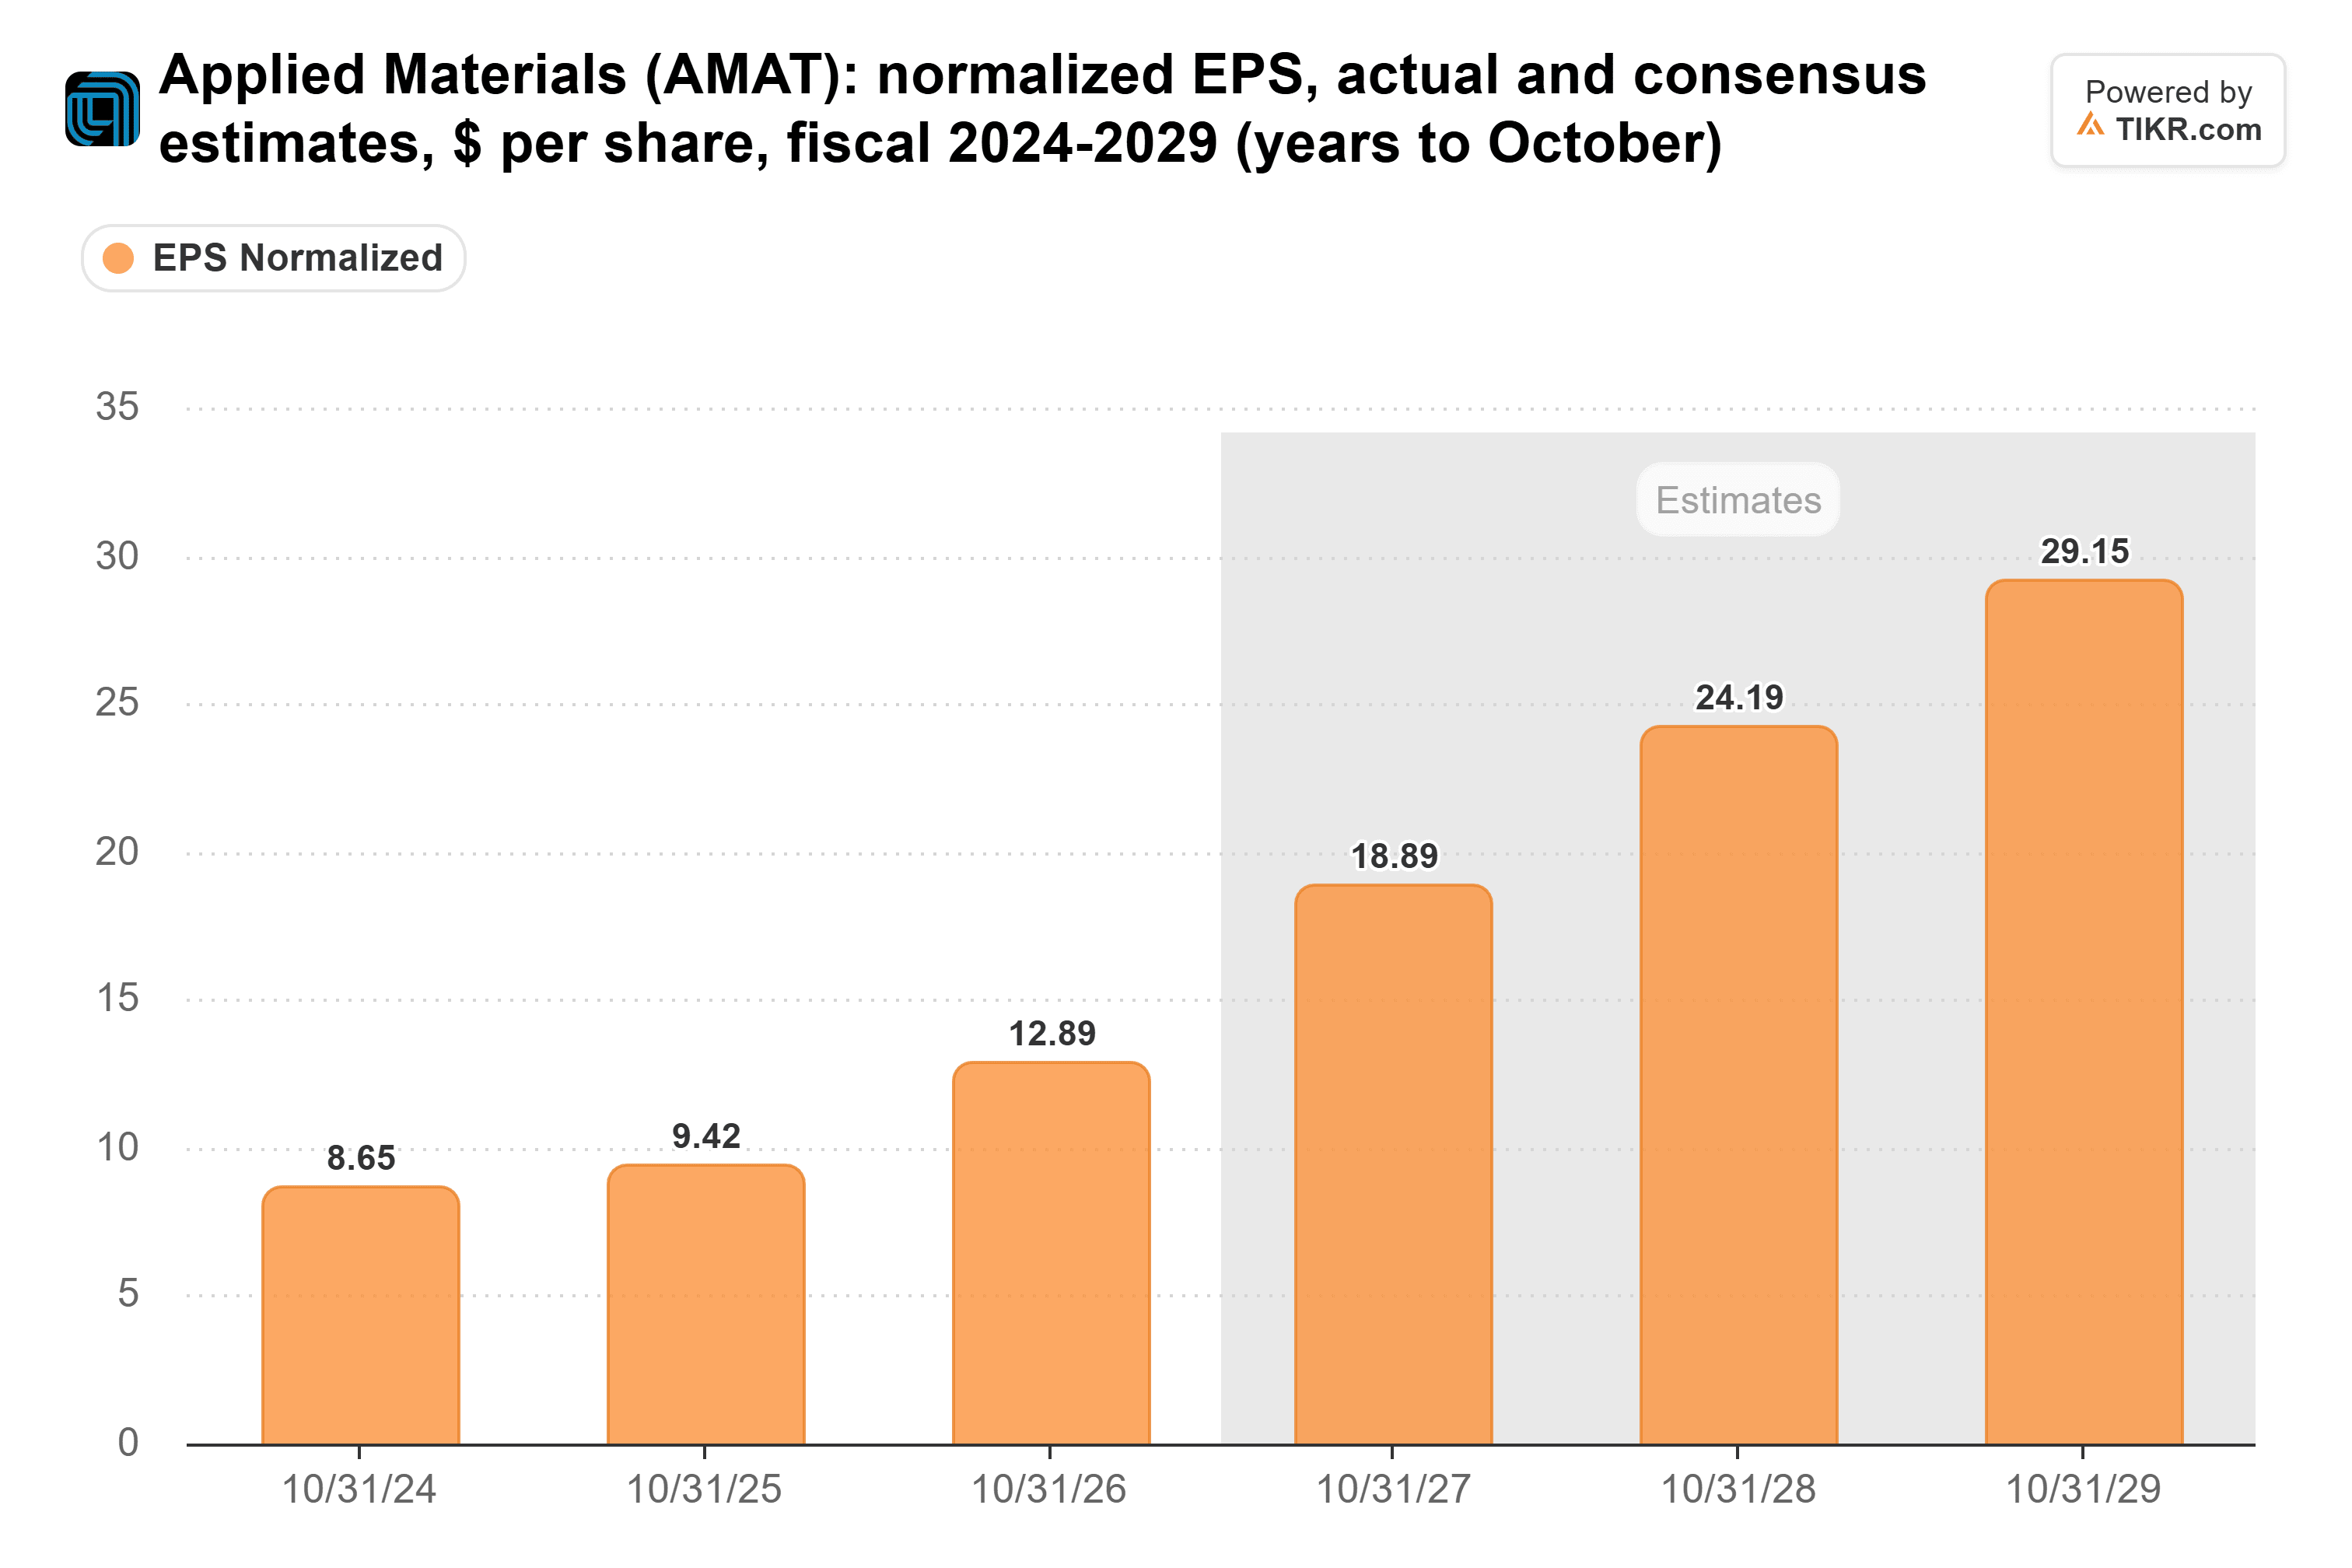
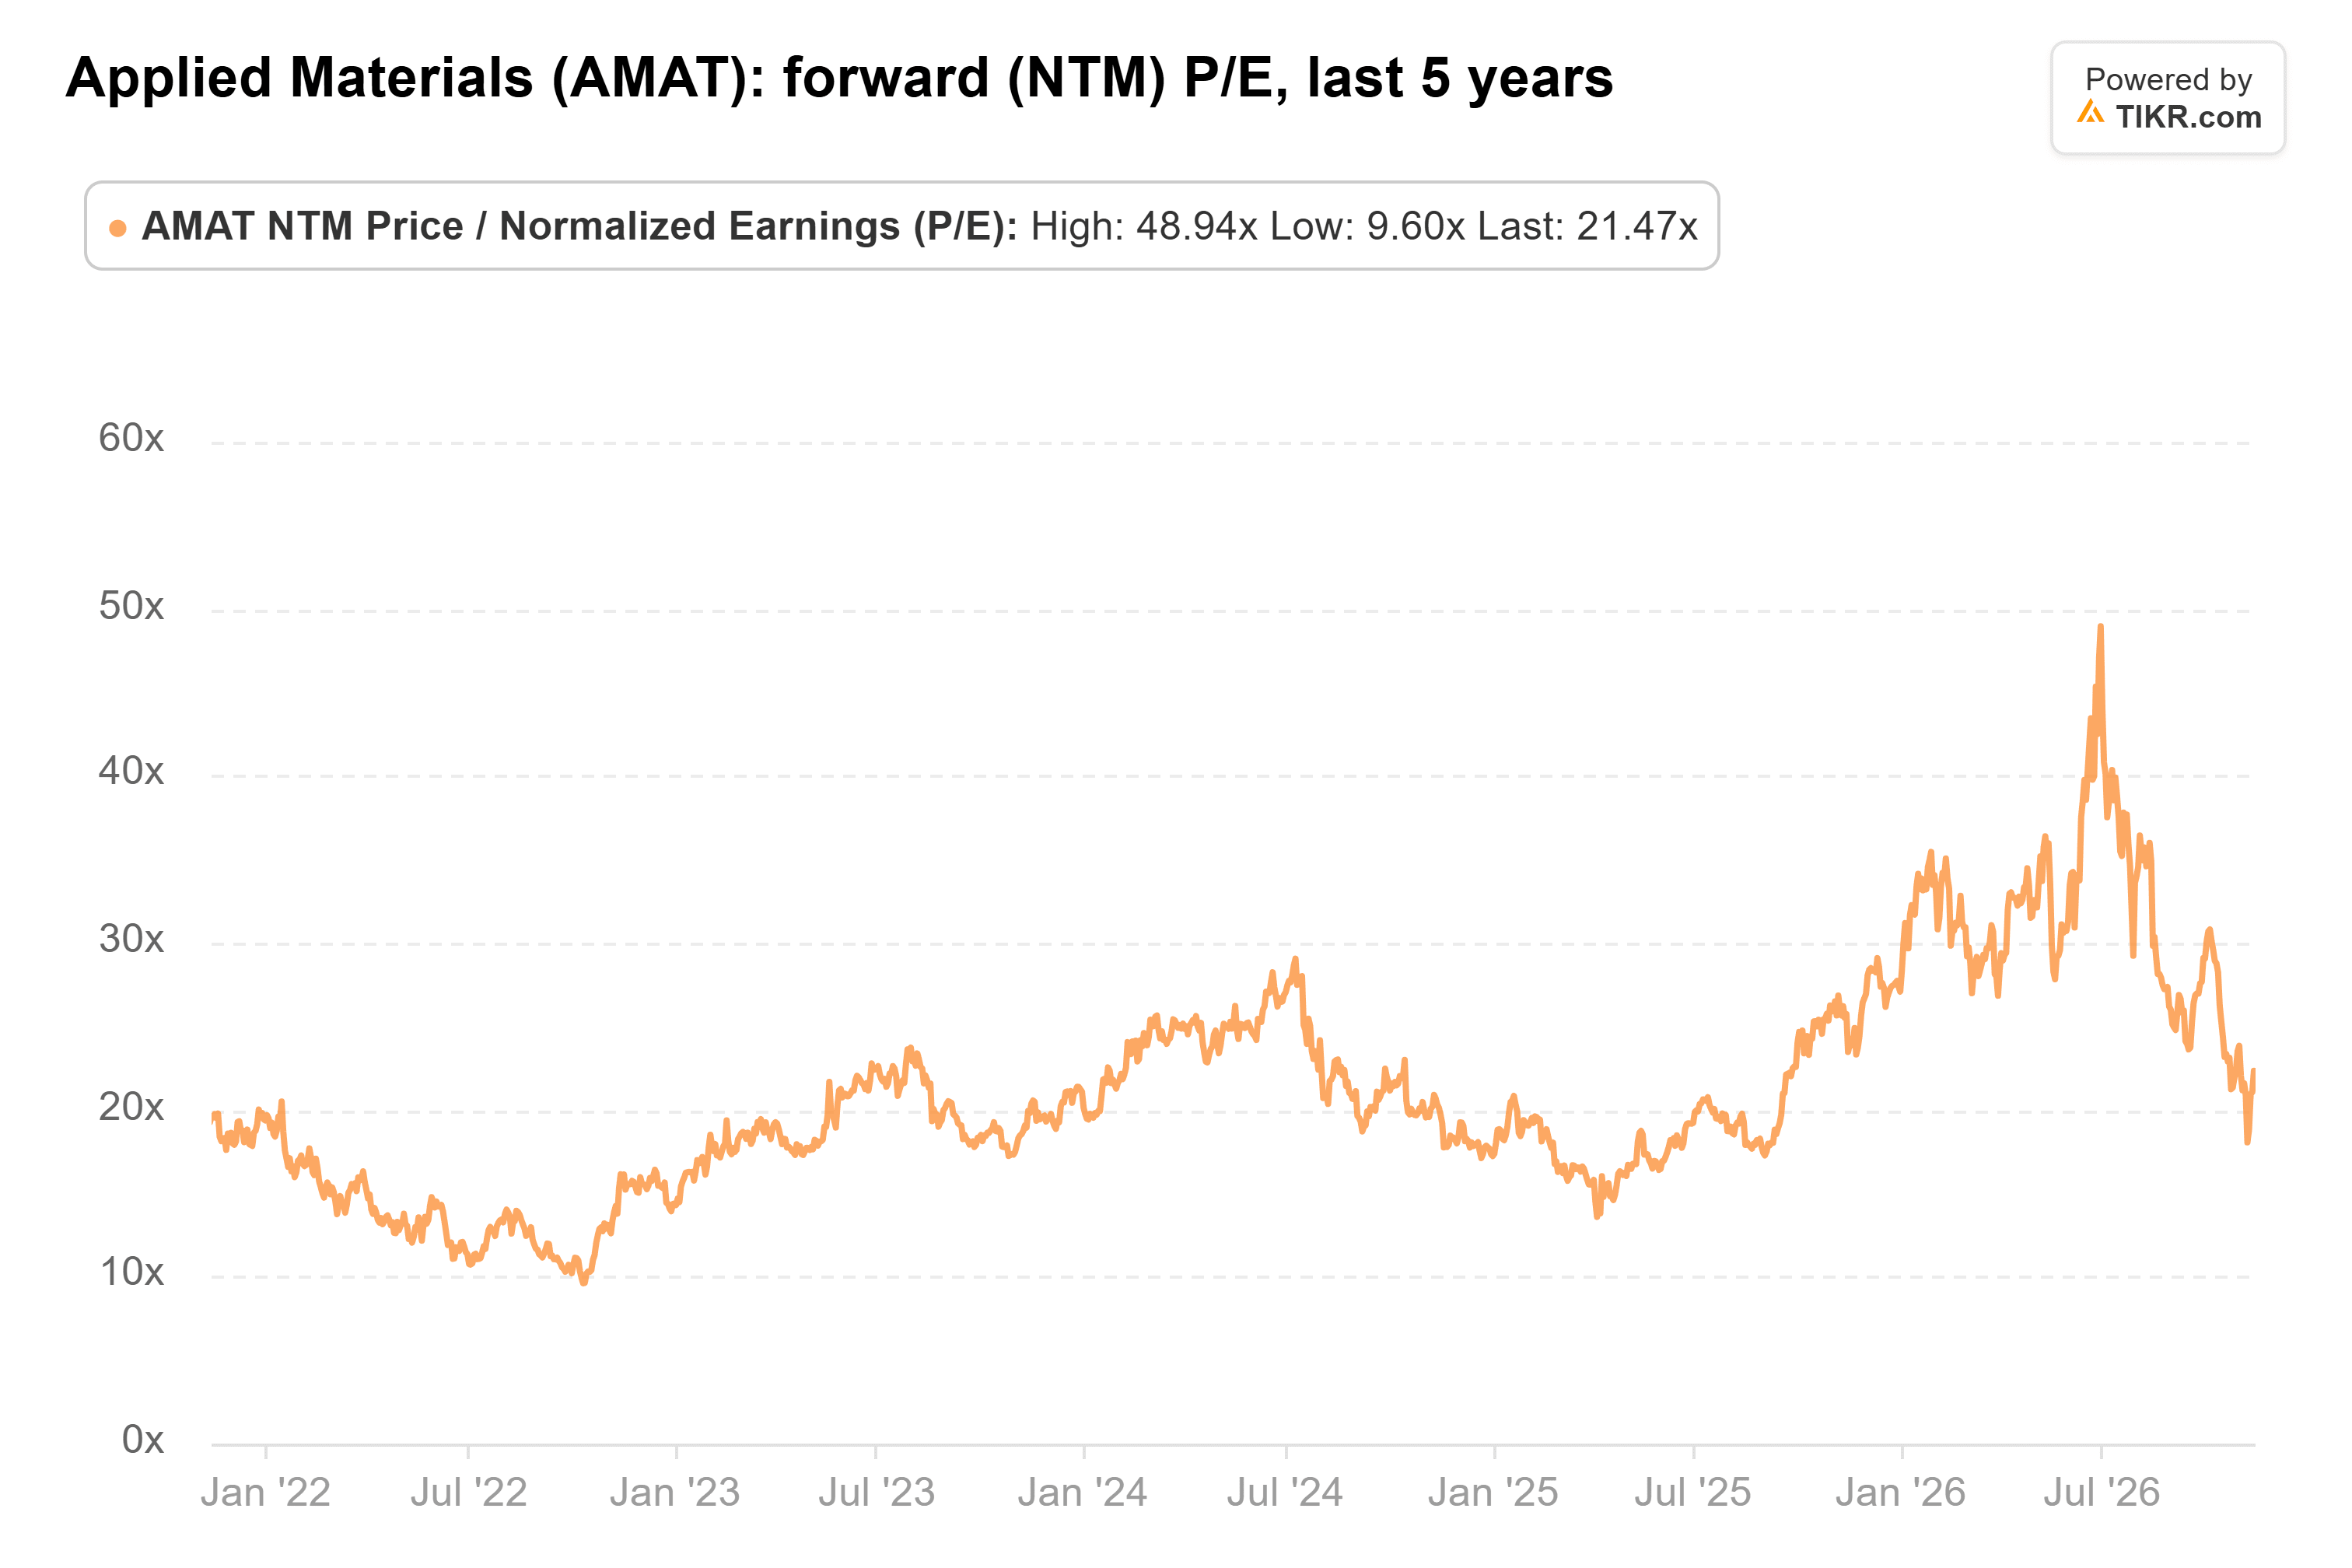
- Analysts expect normalized EPS to grow 47% in fiscal 2027, and the forward P/E is near its five-year average.
- The stock looks like a buy ahead of February’s report.
Applied Materials (AMAT) stock is up 11% in the past week, and the chip group did most of the lifting.
Chip stocks bounced on Monday from the post-midterm AI selloff that cost Applied 15% the week before. Lam Research (LRCX) and KLA (KLAC) jumped 10% and 9%. Then CoreWeave (CRWV) beat estimates after Tuesday’s close. It also raised its 2026 revenue guide to $13.0 billion to $13.3 billion. The low end of its capex range rose to $37 billion. That eased fears of an AI slowdown, and chip-equipment stocks rose again Wednesday.
A record quarter, sold anyway
After Thursday’s close, Applied posted record fiscal fourth-quarter revenue of $10.41 billion, up 53%. Non-GAAP EPS rose 92% to $4.16, and both figures beat estimates. But its $11.1 billion first-quarter revenue guide came in below the $11.41 billion consensus. Management said tight supply held it back. On Friday, 13 firms lowered their targets, and a tech selloff pulled Applied lower.
CEO Gary Dickerson said on the call that “wafer fab equipment demand will be up more than 30% year-over-year” in 2027. Lam and KLA sell into the same chipmaker budgets and already guide higher. For the December quarter, Lam guides to $8.60 billion of revenue at the midpoint, from $8.22 billion. KLA guides to $4.7 billion, from $4.14 billion. If Dickerson’s 30% holds, all three get paid.
TIKR tracks 40 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Estimates keep rising, so I’d buy more
When Applied peaked on June 30, analysts expected $16.40 of normalized EPS for fiscal 2027. Now they expect $18.89:
So the stock’s 50% fall from its high came from the multiple. Applied traded at 21.5x forward earnings on Nov. 12, near its 21.0x five-year average and less than half its 48.9x peak in June:
A year from now, investors will be pricing fiscal 2028. At 21x its $24.19 estimate, Applied would be worth about $508 a share, 37% above Friday’s close. The risk is a turn in the cycle. But with estimates rising and the multiple back to normal, I’d buy more.
February’s first-quarter report is the next test: revenue at or above $11.1 billion would show chipmakers are still taking every tool Applied can ship.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!