


Key Takeaways
- Applied Materials stock is up 59% over the past year, even after losing about half its value since its June 30 record close.
- Record quarters drove the climb, and worries about AI spending, sparked partly by Lam Research’s outlook, drove the fall, with no bad news from Applied itself.
- Analysts have raised Applied’s fiscal 2027 earnings estimate 13% since June, and memory customers like Micron plan to spend even more on new capacity.
- Back at its five-year average multiple, the stock looks like a buy, with the Nov. 12 report as the next test.
Applied Materials (AMAT) stock is up 59% over the past year. It’s also 49% below its June 30 record close. That’s a strange place for a company whose CEO, Gary Dickerson, told Bloomberg Tech on Oct. 14 that “we are investing to prepare to double our output over the next two years.”
Most of the drop came from outside the company. Lam Research (LRCX) put out an October outlook that revived worries about AI spending across chip-equipment stocks. Meanwhile, memory customer Micron Technology (MU), up 205% over the past year, plans to spend even more on new capacity.
Applied kept posting records
On May 14, Applied reported record quarterly revenue of $7.91 billion. Dickerson then said “we now expect our semiconductor equipment business to grow more than 30 percent in calendar 2026.”
The third quarter topped that. Revenue rose 25% to a record $9.12 billion, the biggest quarter-over-quarter jump in Applied’s history. Non-GAAP gross margin also rose from a year earlier for the 13th straight quarter. Applied guided fourth-quarter revenue to $10.25 billion, which would be up 51%. Dickerson added that Applied expects “another strong growth year” in 2027.
TIKR tracks 40 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Chip stocks sold off, and Applied went with them
The turn came at Applied’s Oct. 13 investor event, where it gave no forecast for equipment spending. Then on Oct. 21, Lam guided its December quarter to $8.6 billion, plus or minus $400 million, which only matched estimates, and the whole group sold off. Yet Lam CFO Doug Bettinger said on its call that the guide “would have been a bit higher if not for some near-term supply chain constraints.” Lam still expects industry equipment spending to top $200 billion in 2027. That sounds like a company that can’t build tools fast enough.
Intel’s guidance on Oct. 29 deepened the selloff, and the rout got worse on Nov. 5 after Democrats’ midterm gains. None of it was Applied’s own news.
Applied’s own numbers haven’t cracked
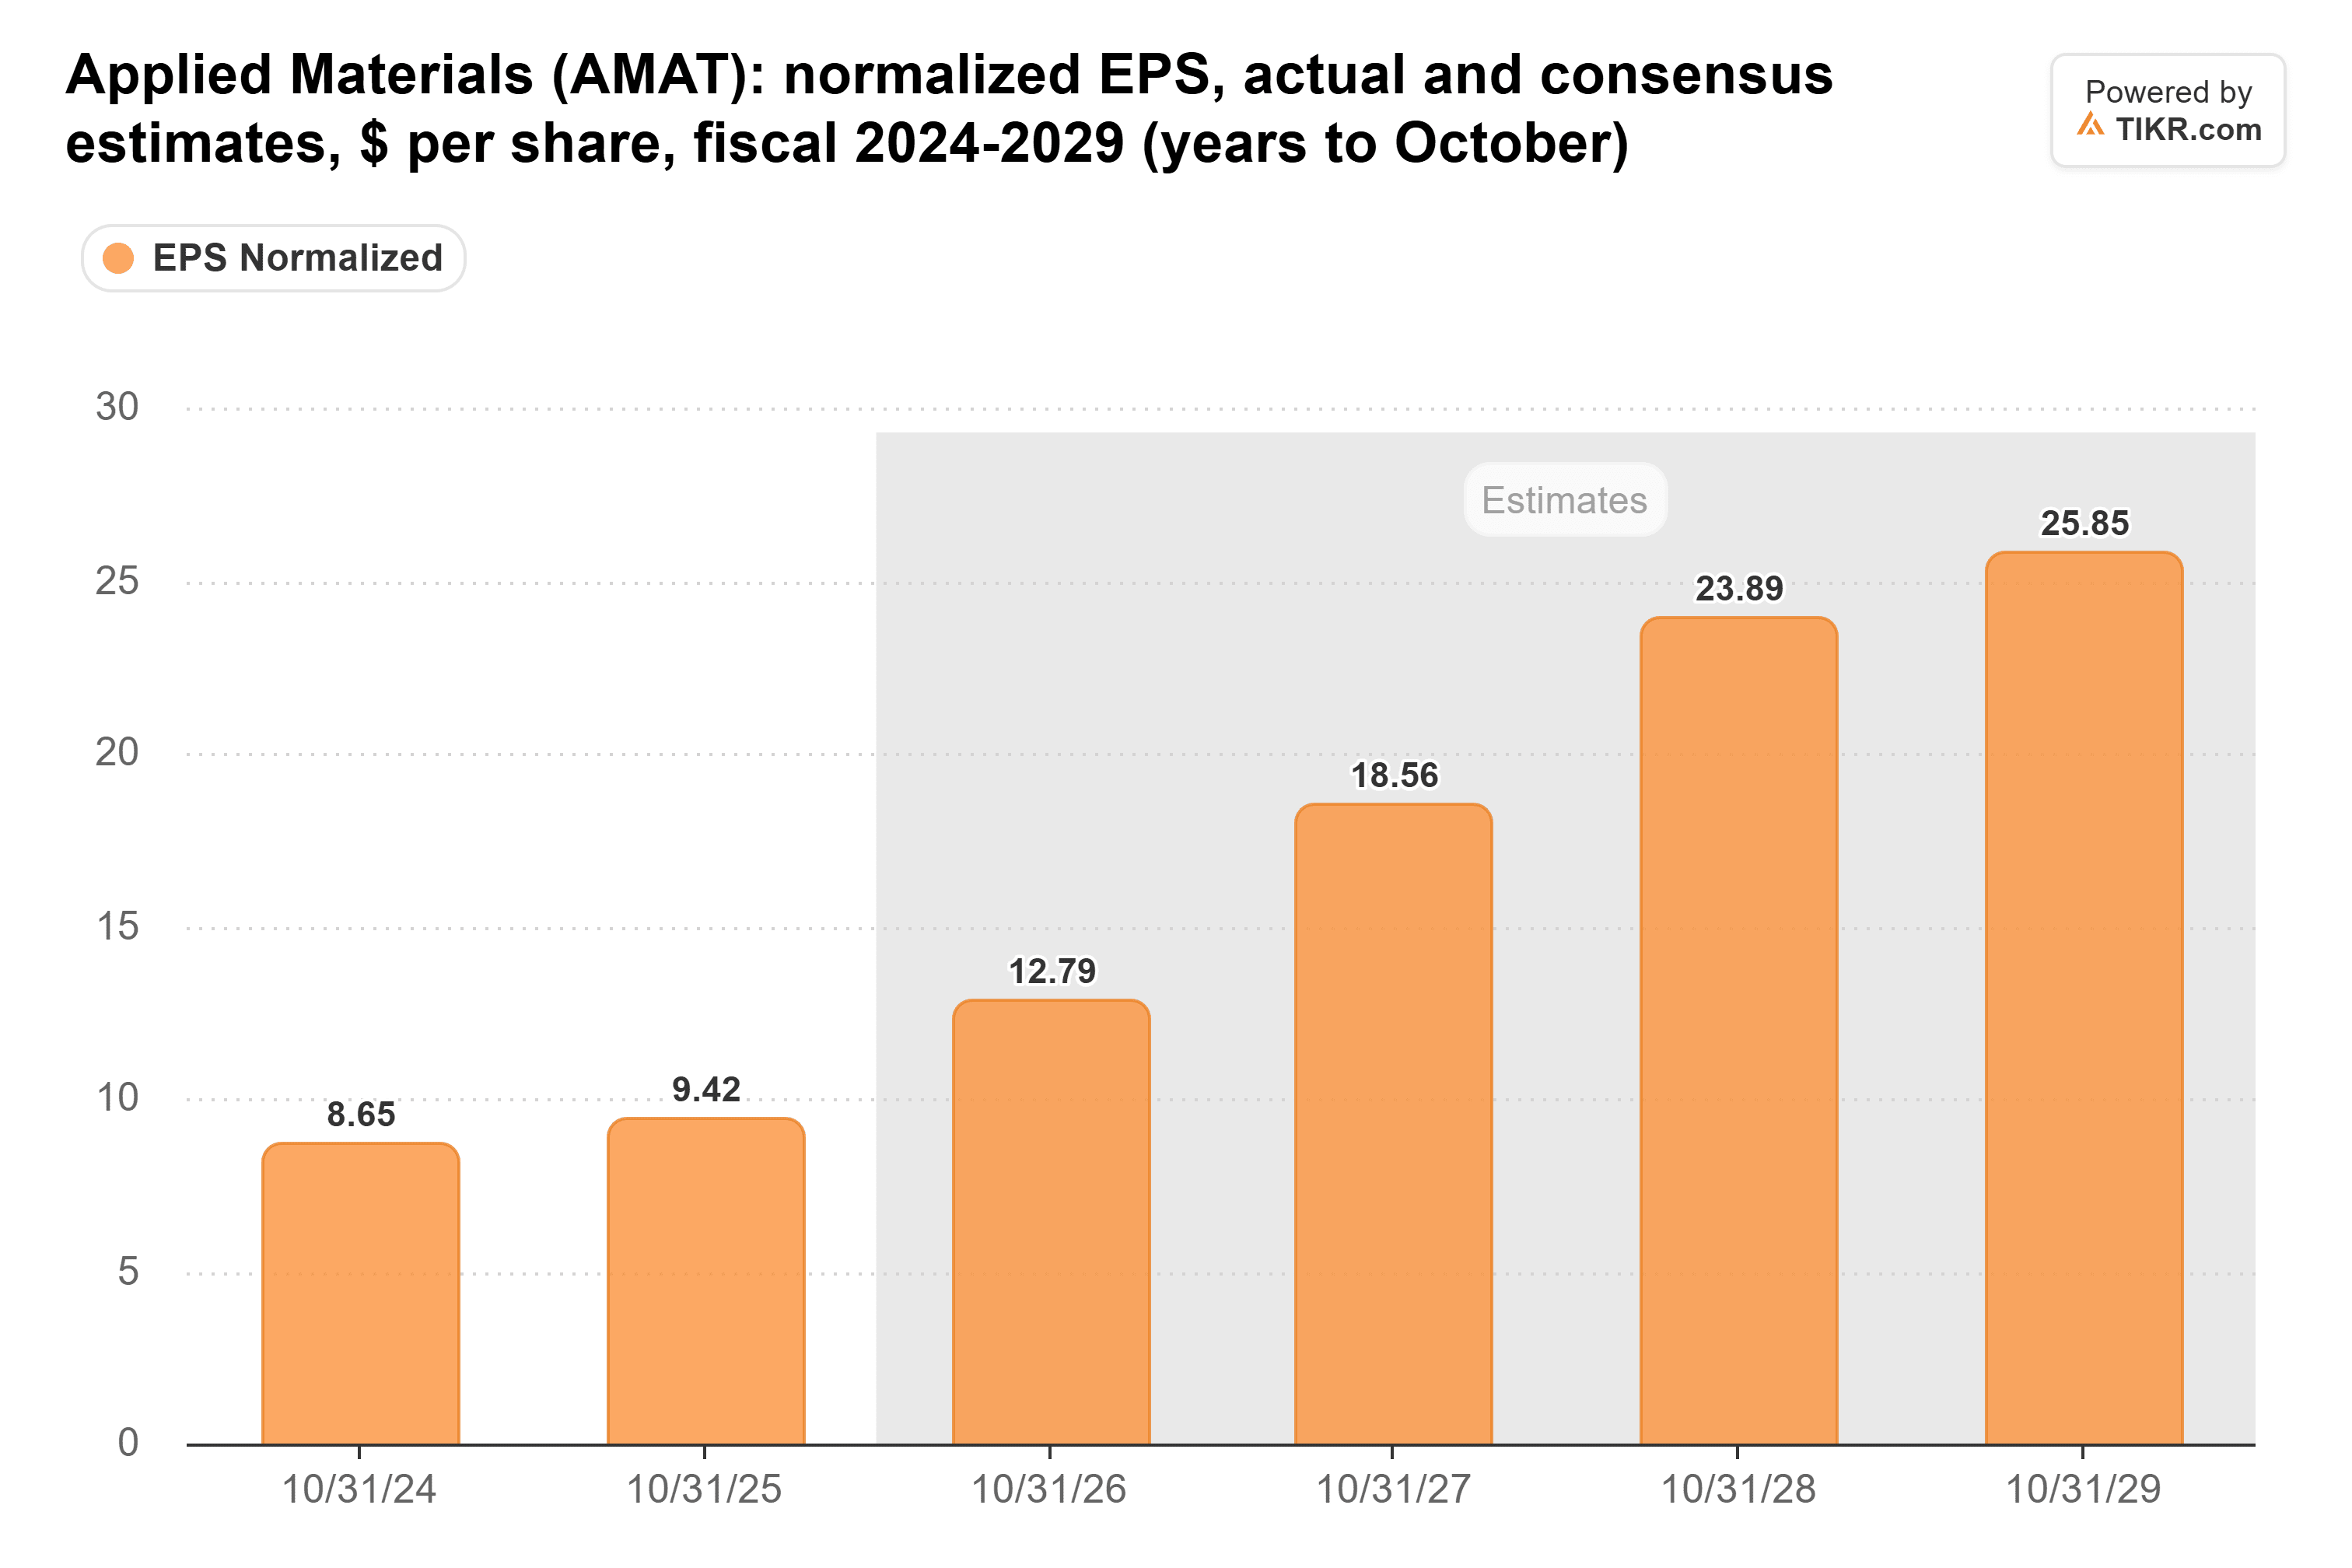
Analysts kept raising their estimates through all of it. The fiscal 2027 normalized EPS estimate is $18.56, up from $16.40 at the end of June and nearly double the $9.42 Applied earned in fiscal 2025:
Micron shows where that demand comes from. Its revenue for the quarter ended Sept. 3 was $54.2 billion, up from $11.3 billion a year earlier. It guided first-half fiscal 2027 capital spending to about $25 billion, versus $27.4 billion for all of fiscal 2026. Micron said most of the increase over its prior plans goes to construction first. Applied works with Micron on next-generation DRAM and HBM. For Applied, building first pushes some tool orders out, but it also means more cleanrooms waiting for tools.
Back at its usual multiple, I’d buy
The whole fall came out of the valuation. Applied traded at 49x forward earnings on June 30, its five-year high. Now it’s back to about 21x, right at its five-year average:
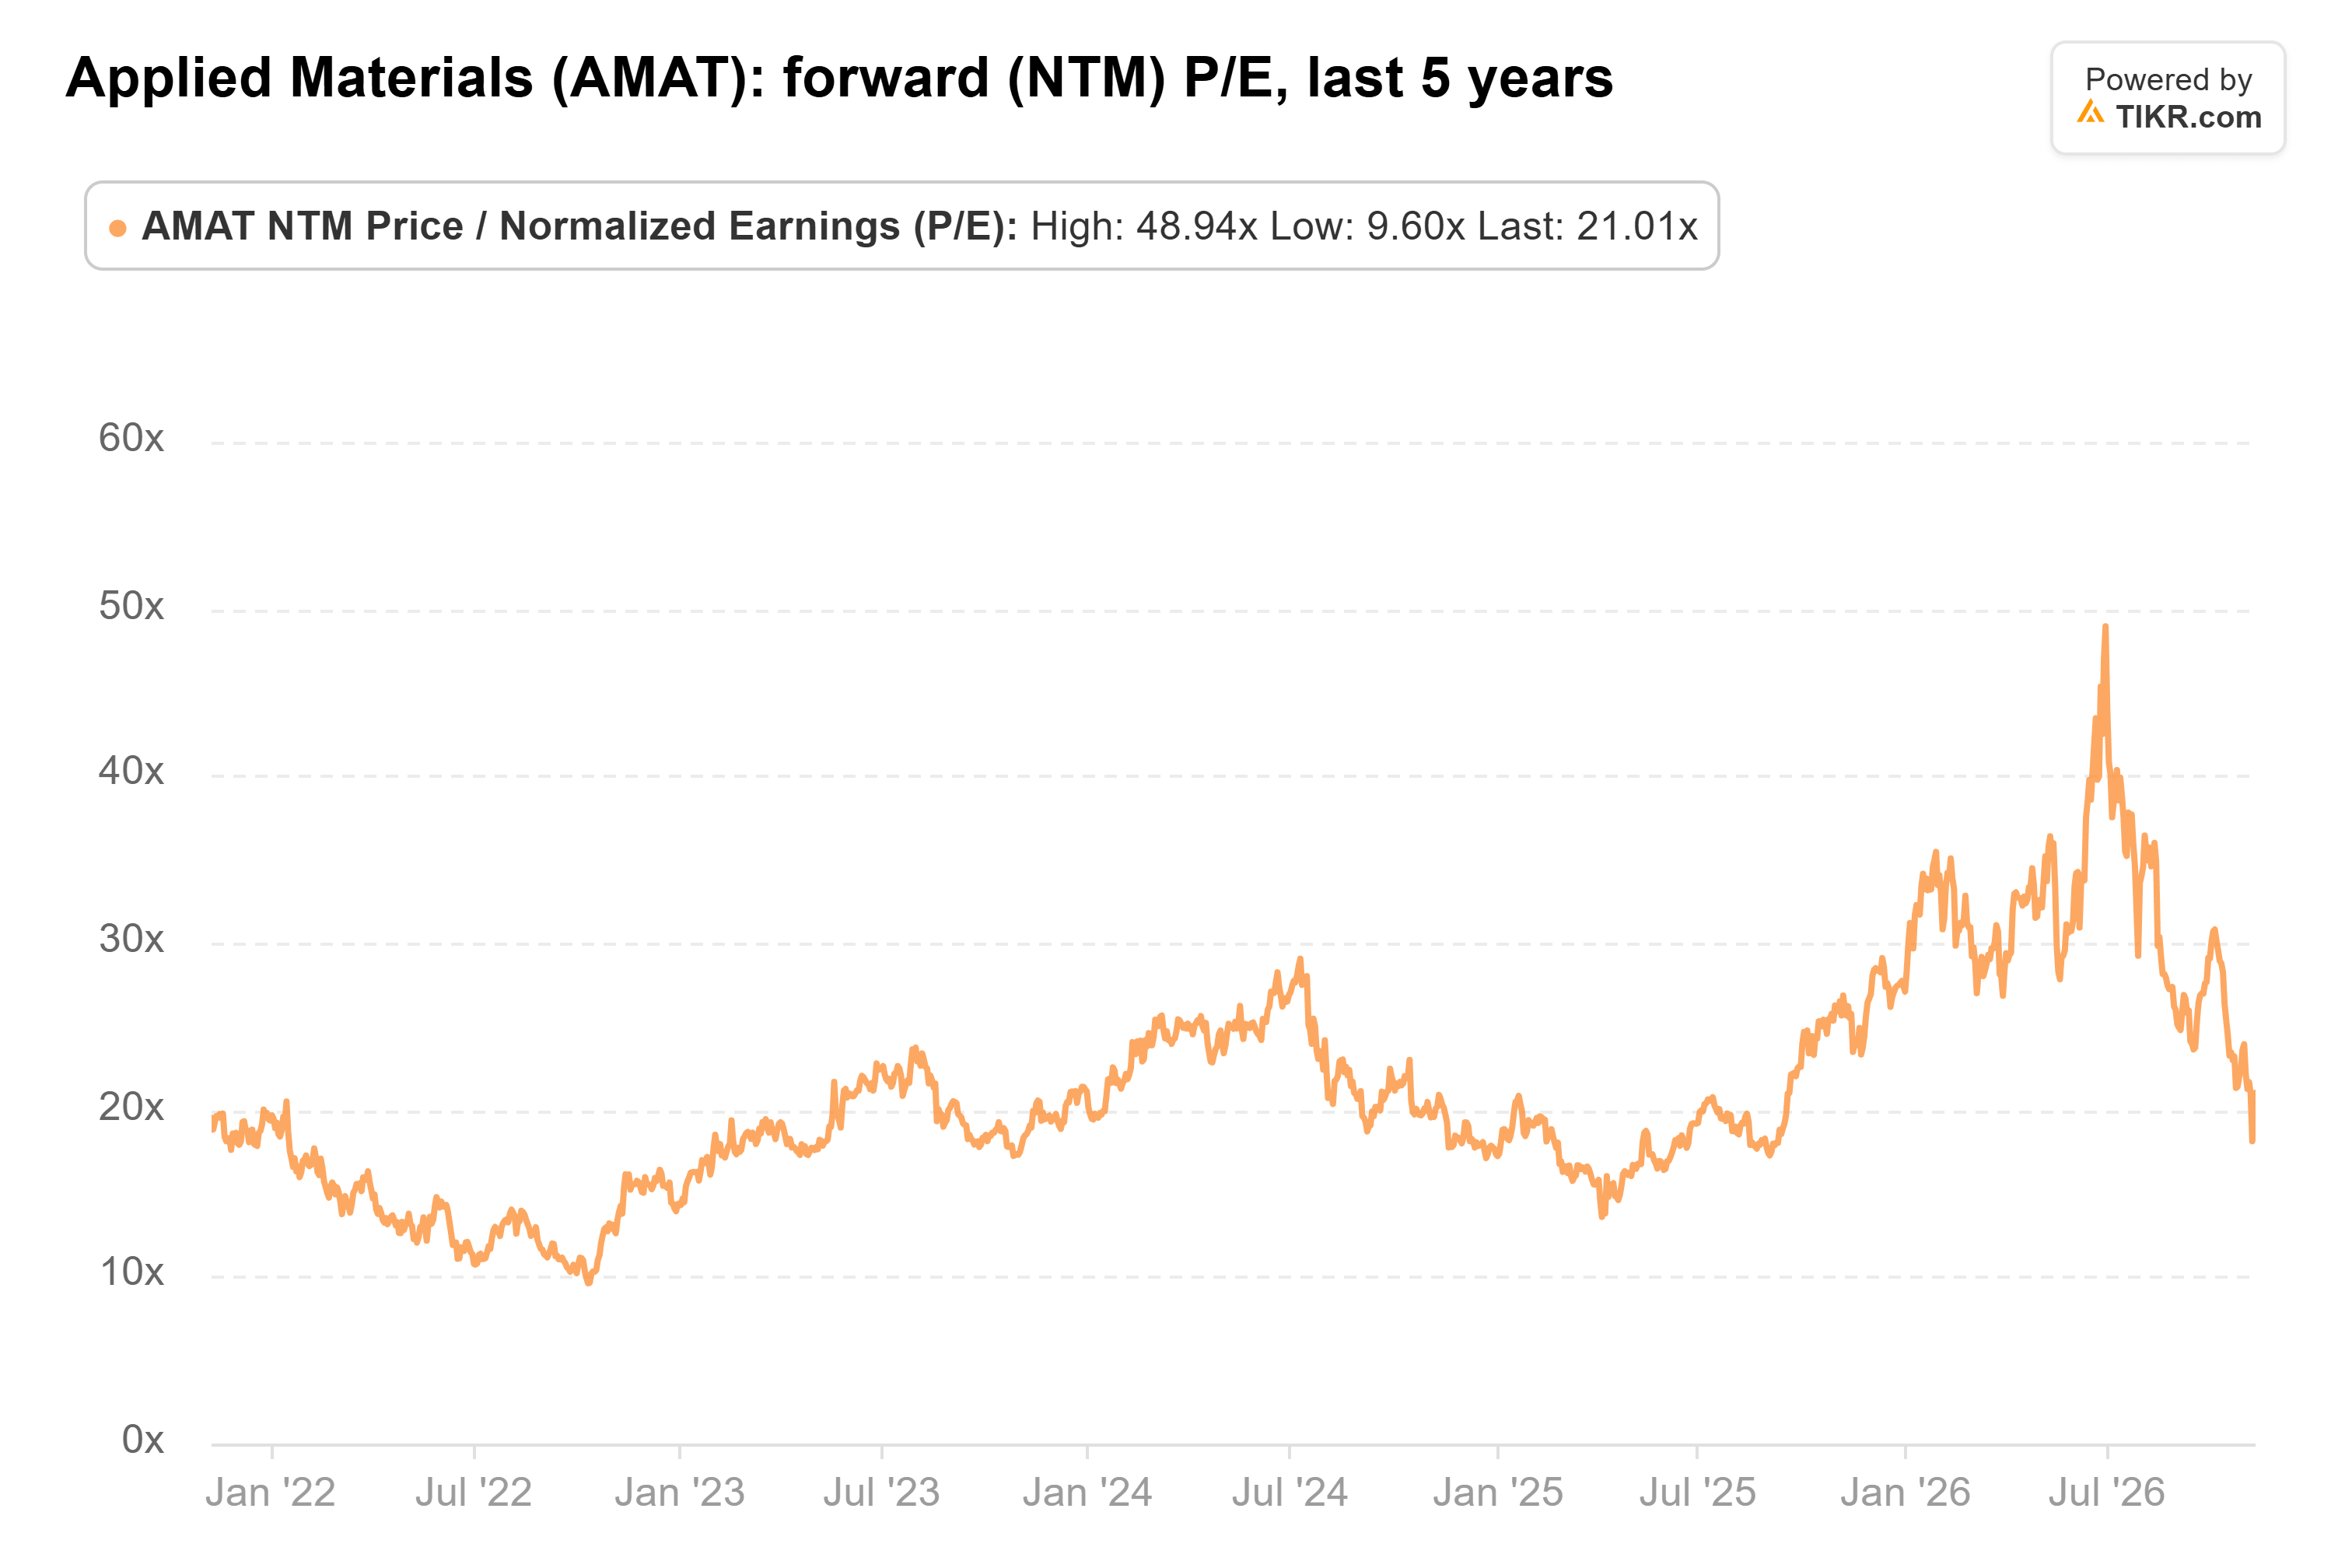
The cycle is the risk. Two customers supplied 34% of revenue in the first nine months of fiscal 2026. Free cash flow has also lagged earnings. When the 2018 boom ended, the forward multiple fell to about 8x and revenue dropped 13% in fiscal 2019.
At an ordinary multiple for earnings analysts keep raising, I’d buy Applied here. Its own numbers show no sign of the cycle turning yet. The next read comes after the close on Thursday, Nov. 12. Watch fourth-quarter revenue against the $10.25 billion guide and the first outlook for fiscal 2027’s 14-week first quarter. A guide that shows equipment sales flattening would change my mind.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!






