Key Takeaways
- Apple (AAPL) reports its September-quarter results after the close on Monday, Nov. 2. Its stock trades at 38x forward earnings, the top of its five-year range.
- Investors are paying that price for Apple’s free cash flow. Alphabet (GOOGL) had its worst day ever on Oct. 29 after posting negative free cash flow, while Apple closed at a record.
- Without tariff refunds, Apple’s gross margin fell from 49.3% in the March quarter to 48.1% in June, and its September guide implies 46.5% as memory costs climb.
- The December-quarter gross margin guide is the number to watch, because Apple expects less help from its memory stockpile after September.
Apple reports its September-quarter results after the close on Monday, Nov. 2, and the market is pricing it as Big Tech’s cash machine. The stock closed at a record $348.91 on Thursday.
Cash is how investors are judging the whole group this earnings season. Alphabet’s free cash flow was negative $9.1 billion in its third quarter as its AI spending ran past its operating cash. With search growth also slowing, its stock fell 13% on Thursday, its worst day as a public company. Apple rose 1.5% the same day.
On a Bloomberg earnings special about Alphabet’s quarter, Bloomberg’s Ed Ludlow put it simply: “The best performers are those throwing off cash. NVIDIA, Apple. The worst performers in the stock market are those with negative free cash flow.”
Apple is on the right side of that split. But at this price, it can’t afford to let memory costs cut into the cash.
TIKR Tracks 43 Analysts on Apple. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Investors Are Paying Up for That Cash
Sitting out the AI capex race has pushed Apple to its highest valuation in company history, at nearly 11 times sales. On earnings, it trades at 38x forward, the top of its five-year range and well above its 29x average over that stretch:

AAPL Stock NTM P/E: 5-Year (TIKR)
Wall Street’s average price target of $328 sits about 6% below Thursday’s close.
The cash behind that multiple is real. Apple’s free cash flow was $31.9 billion in the June quarter, up from $24.4 billion a year earlier, and it hasn’t dropped below $20 billion since the September 2023 quarter:
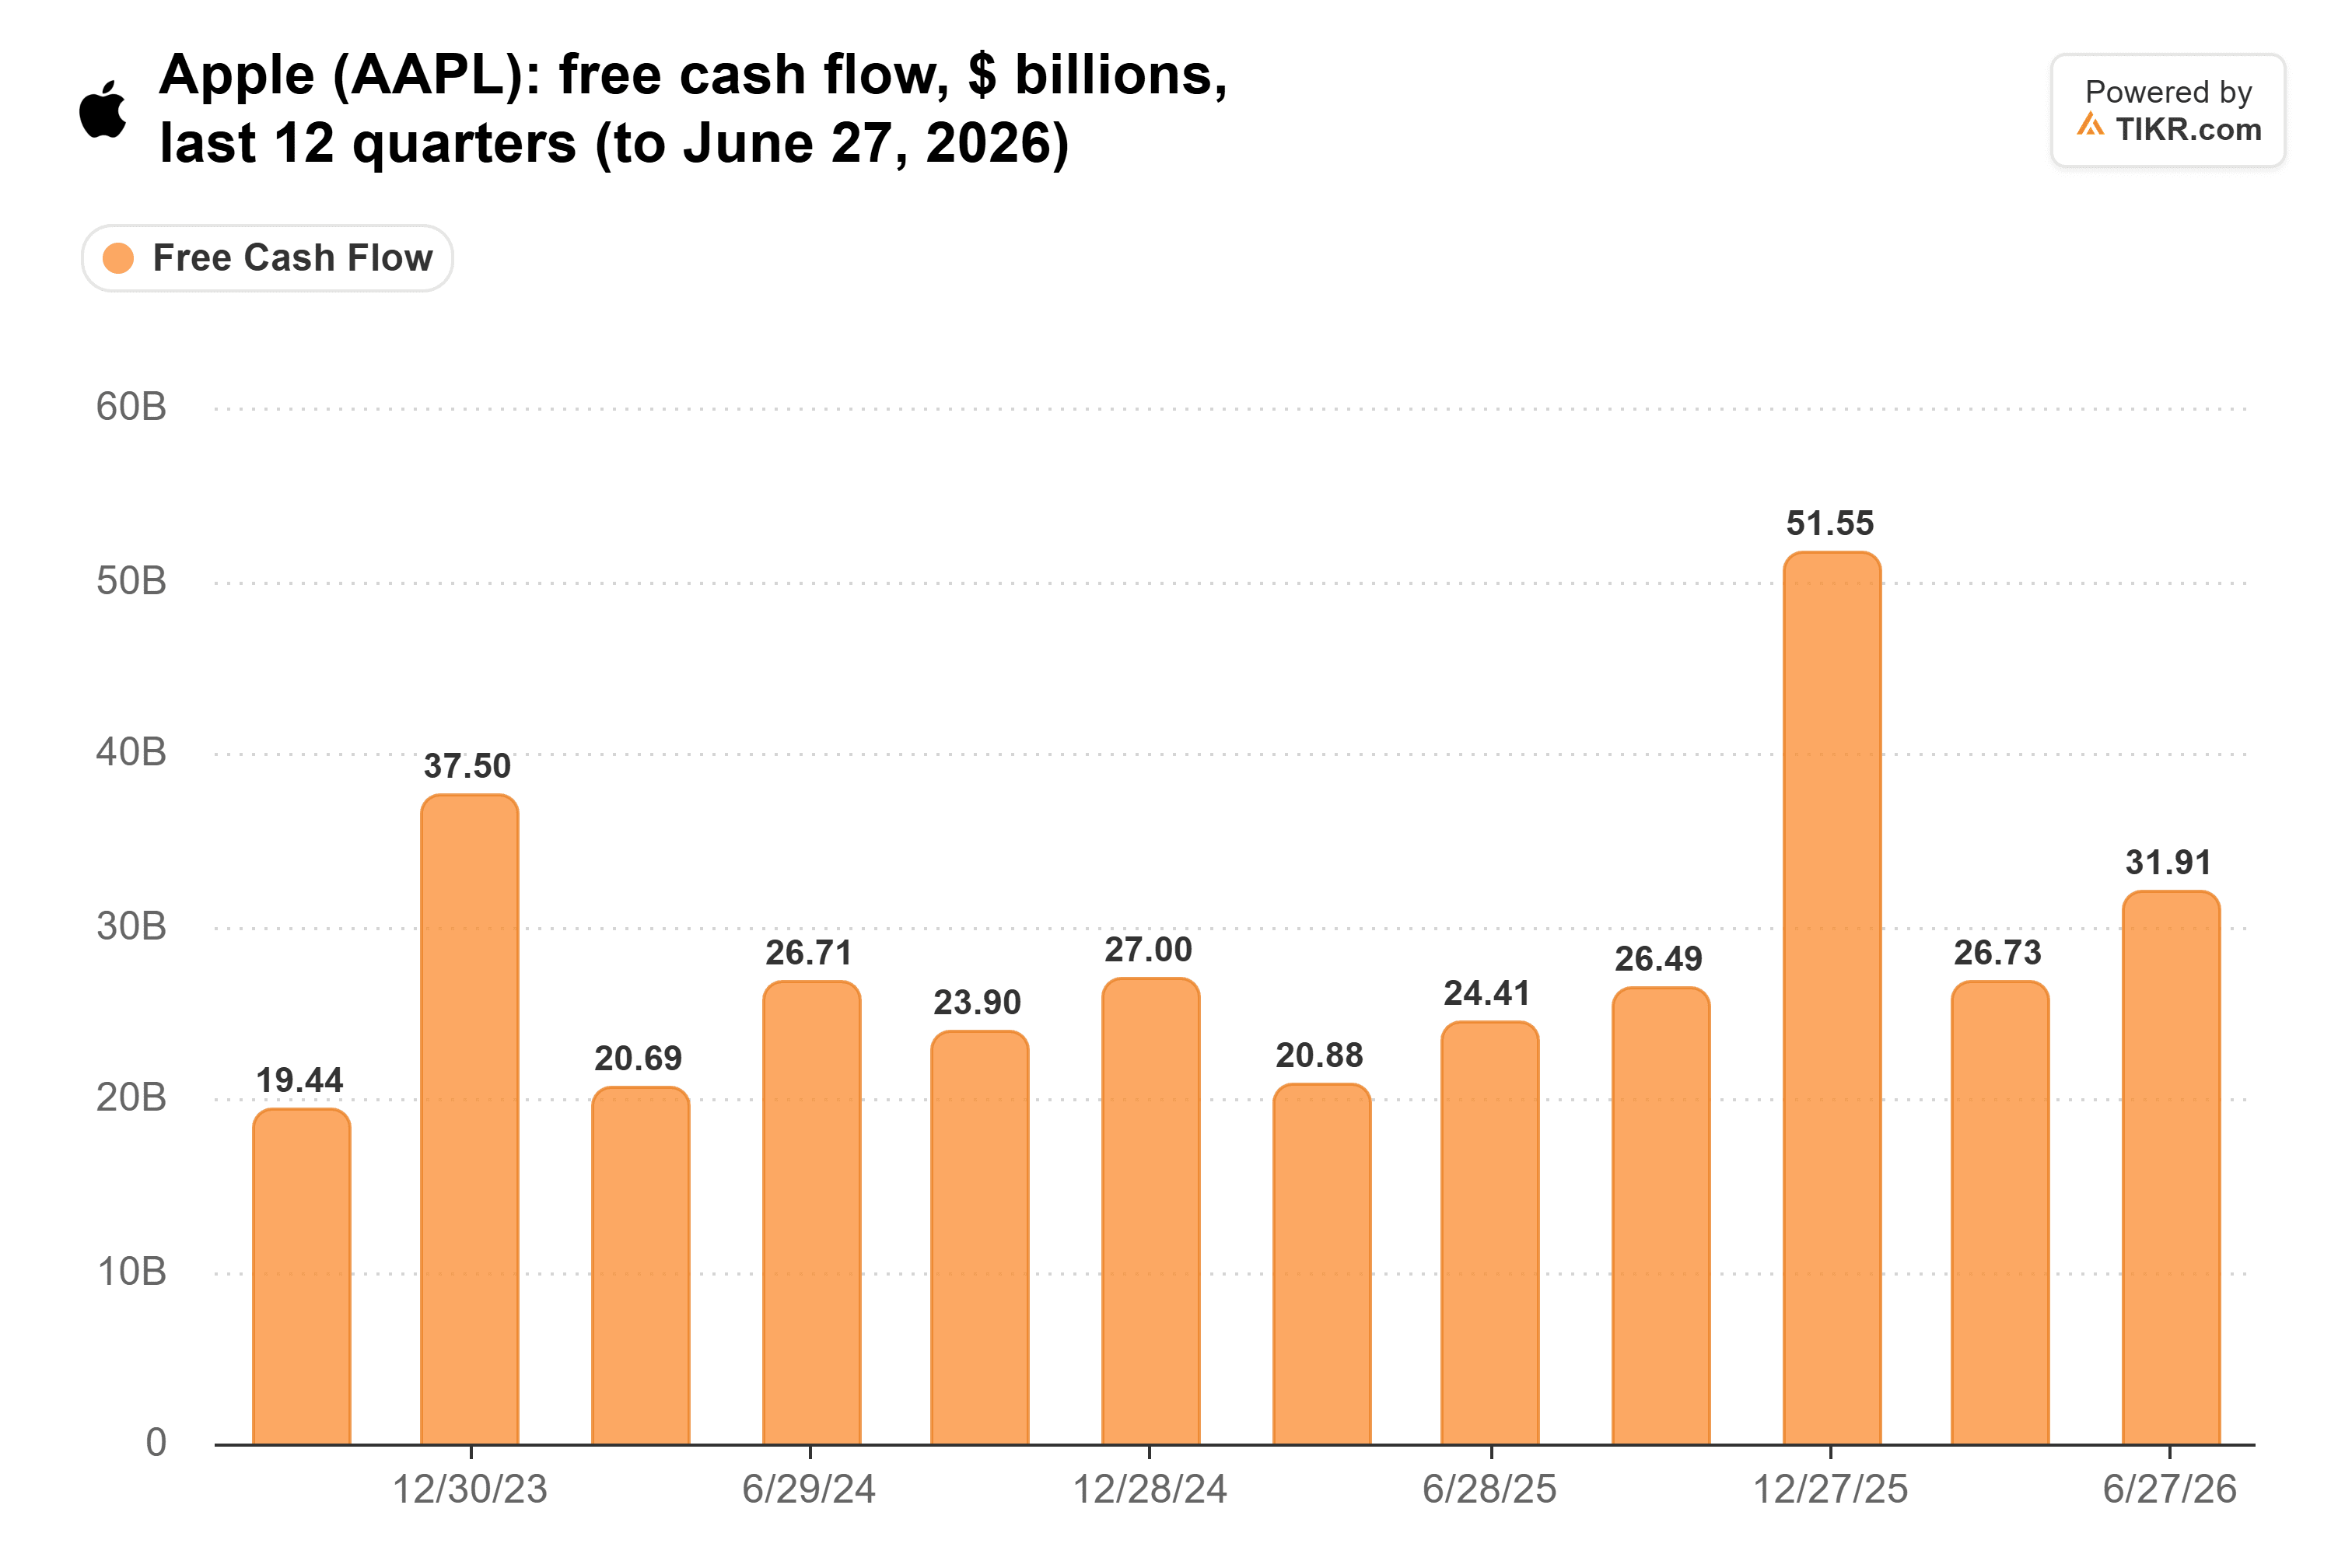
AAPL Free Cash Flow: Quarterly, Sept. 2023-June 2026 (TIKR)
Some of this year’s gain is timing, though. In the nine months to June, Apple paid down much less of what it owed suppliers than a year earlier, and it paid $10.7 billion less in cash taxes. That makes the $26.5 billion it generated in last year’s September quarter the cleaner bar for this one.
Memory Is Already Biting
Memory costs are the biggest threat to that cash, and they hit the gross margin first. On Apple’s July earnings call, Tim Cook, then its CEO, called memory pricing “a 100-year flood.”
Apple’s reported gross margin doesn’t show it yet. It rose to 50.1% in the June quarter, up from 46.5% a year earlier:
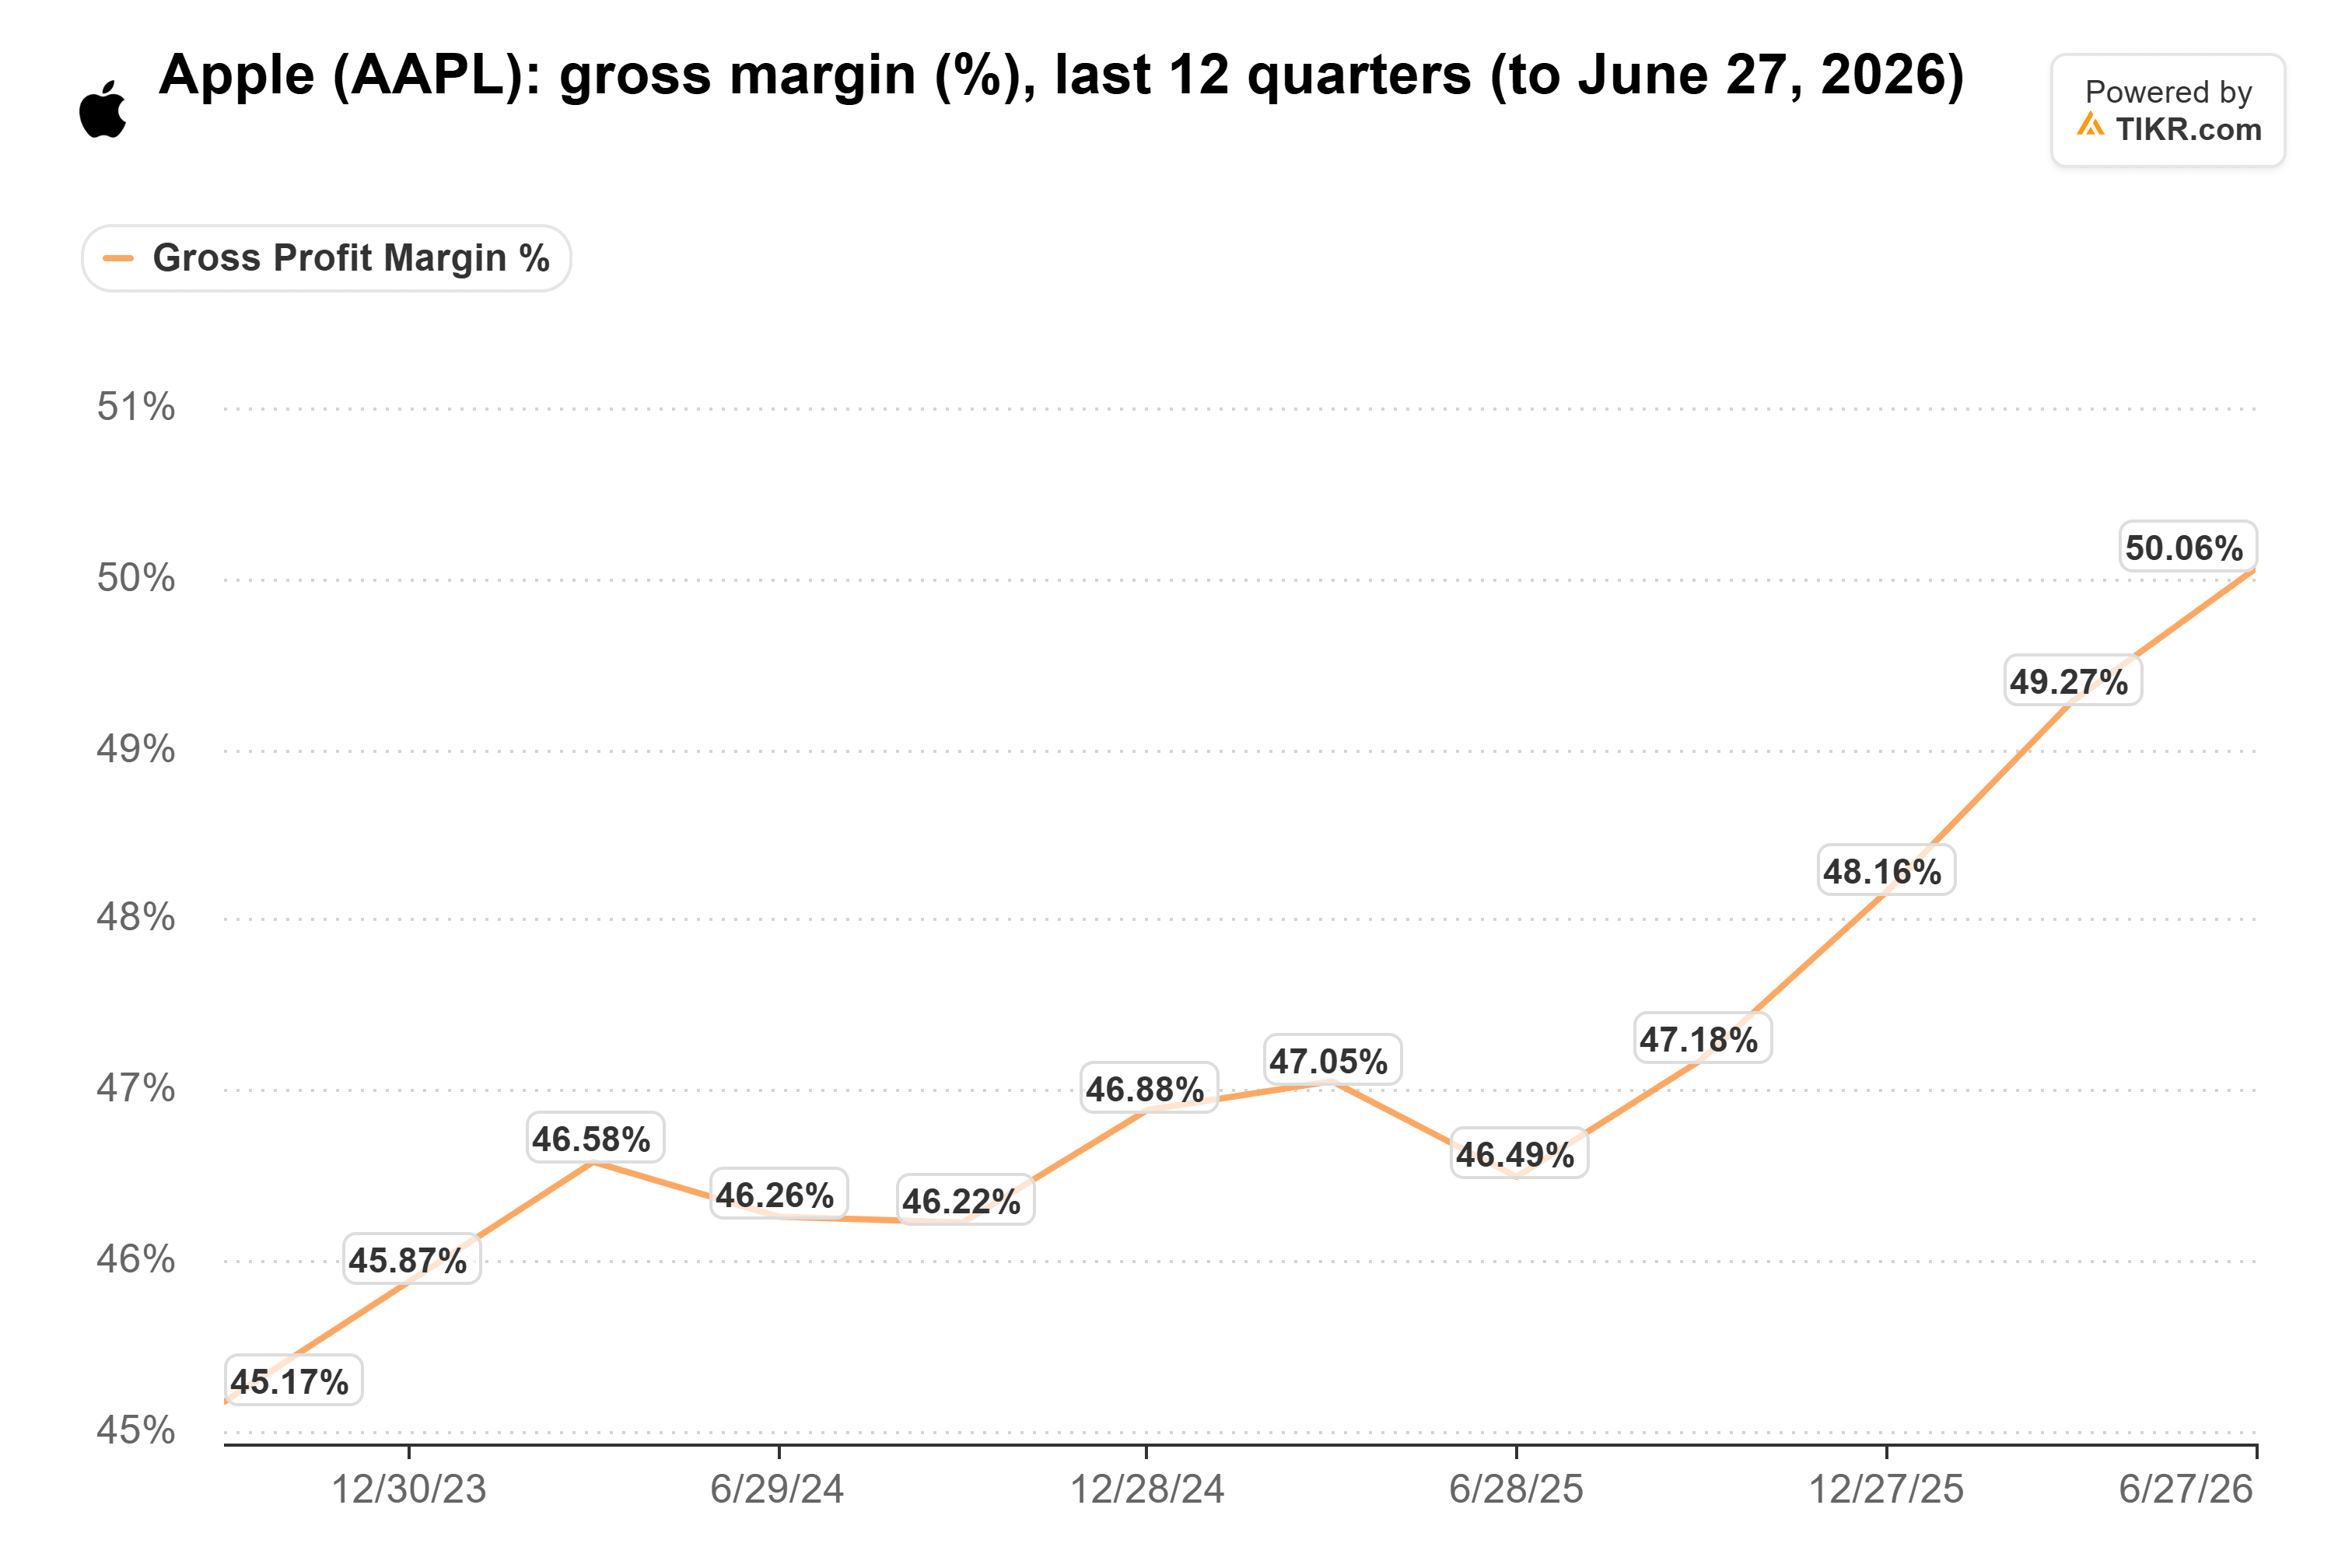
AAPL Gross Margin: Quarterly, Sept. 2023-June 2026 (TIKR)
But that 50.1% includes about 2 points of tariff refunds. Without them, gross margin fell from 49.3% in the March quarter to 48.1% in June. The September guide of 47%-48% includes about a point of refunds, so it implies 46.5% without them. CFO Kevan Parekh said memory accounted for more than 100% of each drop.
Rising costs are also showing up in Apple’s prices. Cook said in July that Apple had “reluctantly” raised them. On TBPN, co-host John Coogan said: “we are no longer in that era because of the memory crunch and the price of components going up.”
The December Guide Matters Most
The September quarter may not move the stock much, because Apple stocked up ahead of the price spike. Its components inventory rose to $7.6 billion on June 27, from $2.1 billion at the end of fiscal 2025, and that stockpile kept memory costs down. Cook said in July that the benefit would decrease beyond the September quarter, and that Apple expected to pay still more for memory in September.
So the number to watch is the December-quarter gross margin guide. December quarters usually get a lift from new launches and higher volume. A guide at or above 46.5% before refunds would show Apple holding its margin despite memory costs, with help from mix and cheaper non-memory parts. A guide below that would put analysts’ 47.4% gross margin forecast for fiscal 2027 at risk, and that forecast is already down from 48.6% for fiscal 2026.
It’s also John Ternus’s first call as CEO, and investors will want to hear how iPhone Duo is selling since it started shipping on Oct. 23. Selling more phones lifts revenue, but it doesn’t help the margin if each phone costs more to build.
Apple’s cash machine is still running, but at 38x, the stock is priced as if memory costs will pass without leaving a mark. A December guide below 46.5% would be the clearest sign that they won’t, and I’d expect the multiple to come down if that happens.
The flip side is that if memory prices cool sooner than management expects, the squeeze could ease within a quarter or two. The first place that would show is the guide on Nov. 2.
So what is Apple stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!