Key Takeaways
- Stagwell (STGW) shares jumped 13% on Thursday after record third-quarter results and a higher full-year profit outlook, then gave back about 3% after hours.
- Digital Transformation grew 23% organically and The Marketing Cloud grew 108%, while Marketing Services shrank.
- Stagwell’s 11% organic revenue growth (7% on net revenue) beat Omnicom’s (OMC) 7.2% and WPP’s (WPP) 0.5% like-for-like in the third quarter.
- Stagwell still trades at a single-digit forward P/E, leaving room for the multiple to climb.
Stagwell stock jumped 13% on Thursday to close at $9.95, a new 52-week high, after record third-quarter results and a raised outlook. Shares gave back about 3% after hours, to $9.65. CEO Mark Penn says the quarter shows Stagwell is “on track to become number one in marketing transformation.”
WPP grew revenue just 0.5% like-for-like in the third quarter it reported the same morning (its preferred measure, revenue less pass-through costs, fell 2.1%), and Omnicom grew 7.2% organically in its quarter. Stagwell grew 11%, or 7% on net revenue.
What Stagwell Reported
Stagwell reported before the open:
- Revenue rose 10% to $816 million, a little short of estimates
- Adjusted EPS rose 42% to $0.34, ahead of the $0.31 consensus
- Adjusted EBITDA rose 25% to $145 million, a 22% margin on net revenue
- Full-year guidance went up to $490 million to $540 million of adjusted EBITDA and $1.07 to $1.21 of adjusted EPS
The Tech Side Is Doing the Heavy Lifting
Digital Transformation’s net revenue grew 23% organically to $119 million, and The Marketing Cloud’s more than doubled to $56 million. Together, they’re now 26% of net revenue. Stagwell also doubled its 2027 target for enterprise tech bookings to $150 million, after already booking $59 million this year against an initial goal of $25 million.
That work pays better: The Marketing Cloud’s adjusted EBITDA margin was 44% this quarter, more than twice the 19% at Marketing Services.
Marketing Services is still a third of net revenue, and it shrank 7.5% organically. WPP, up nearly 5% on Thursday, has the same problem: its creative business fell 5.1% like-for-like. WPP expects to return to growth during 2027. Stagwell already has a fast-growing tech business to make up the gap.
Omnicom, up 4% on Thursday, raised its core adjusted EBITA margin to 18.2% from 16.2%, helped by cost savings from the Interpublic deal. Stagwell is cutting costs too, but its tech mix should keep lifting margins after the cuts.
TIKR Tracks 8 Analysts on Stagwell. How Many Say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Stagwell, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Stagwell’s Analyst Ratings
Still Priced Like an Agency
Analysts already expected adjusted earnings to climb from $0.83 a share in 2025 to $1.61 in 2028.
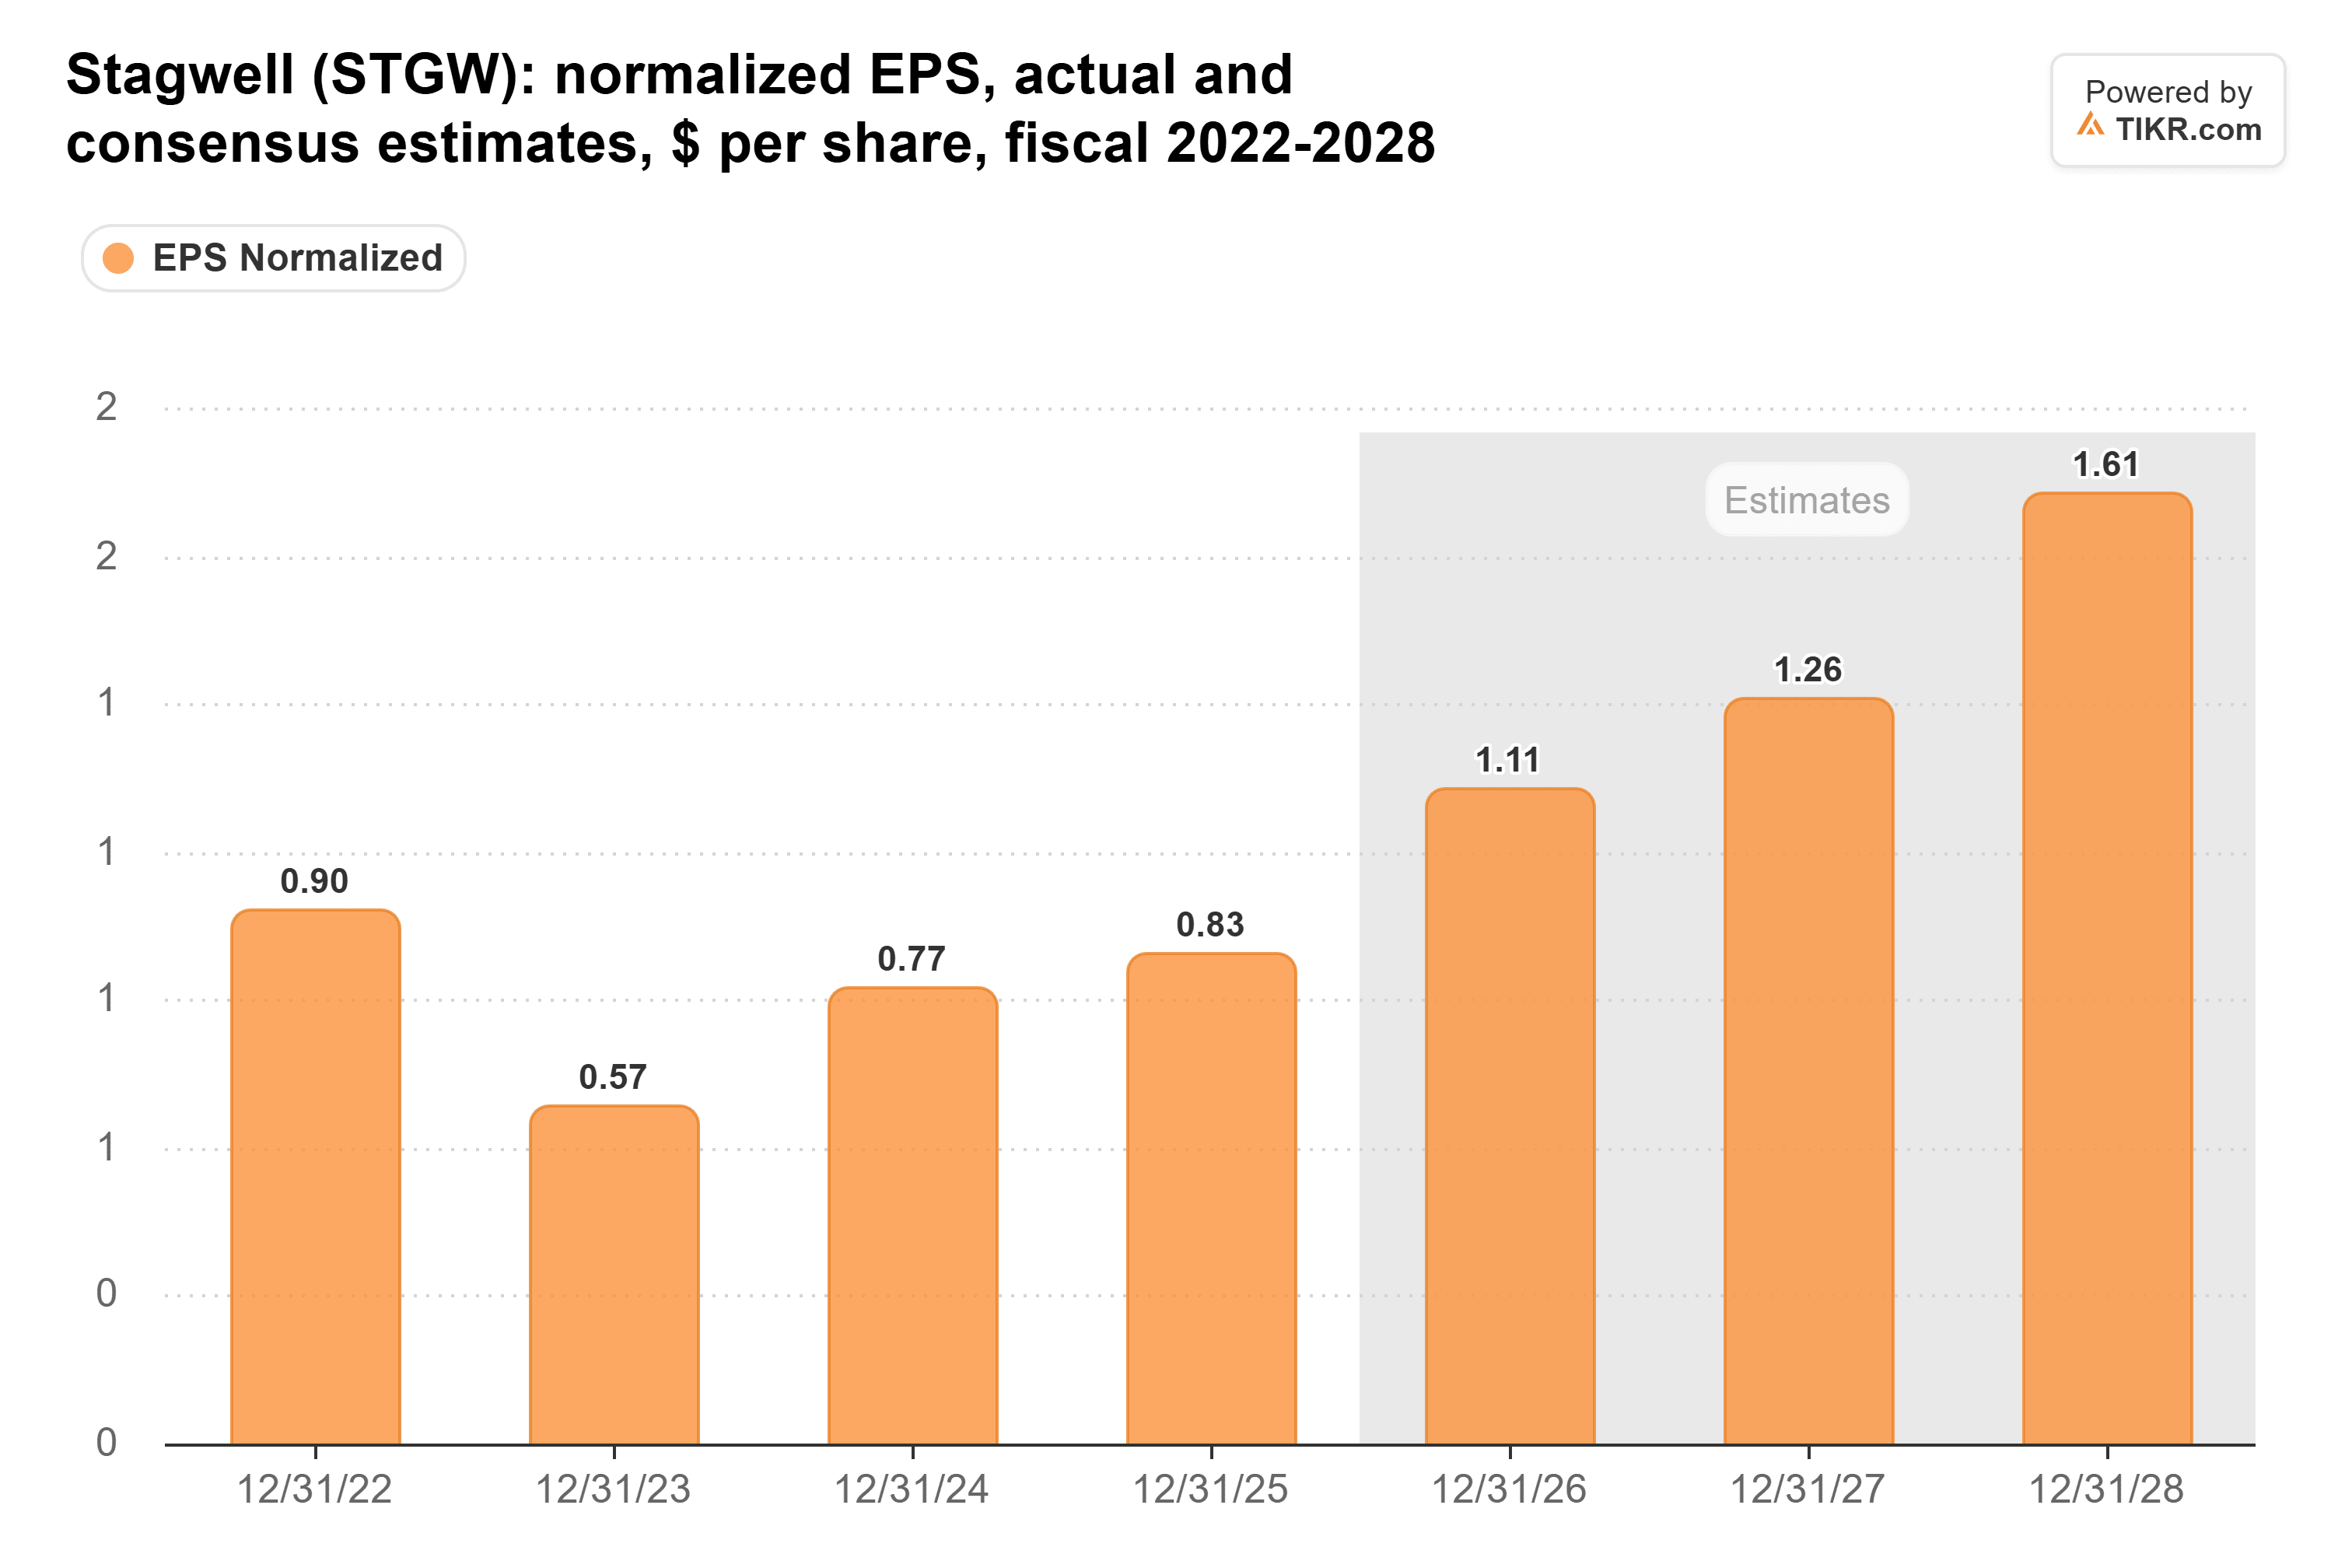
The midpoint of the raised guidance, $1.14, is above the $1.11 consensus for 2026, so that estimate should move up.
Before the report, the stock traded at 7.4x forward earnings, a little above its three-year average of 6.8x.
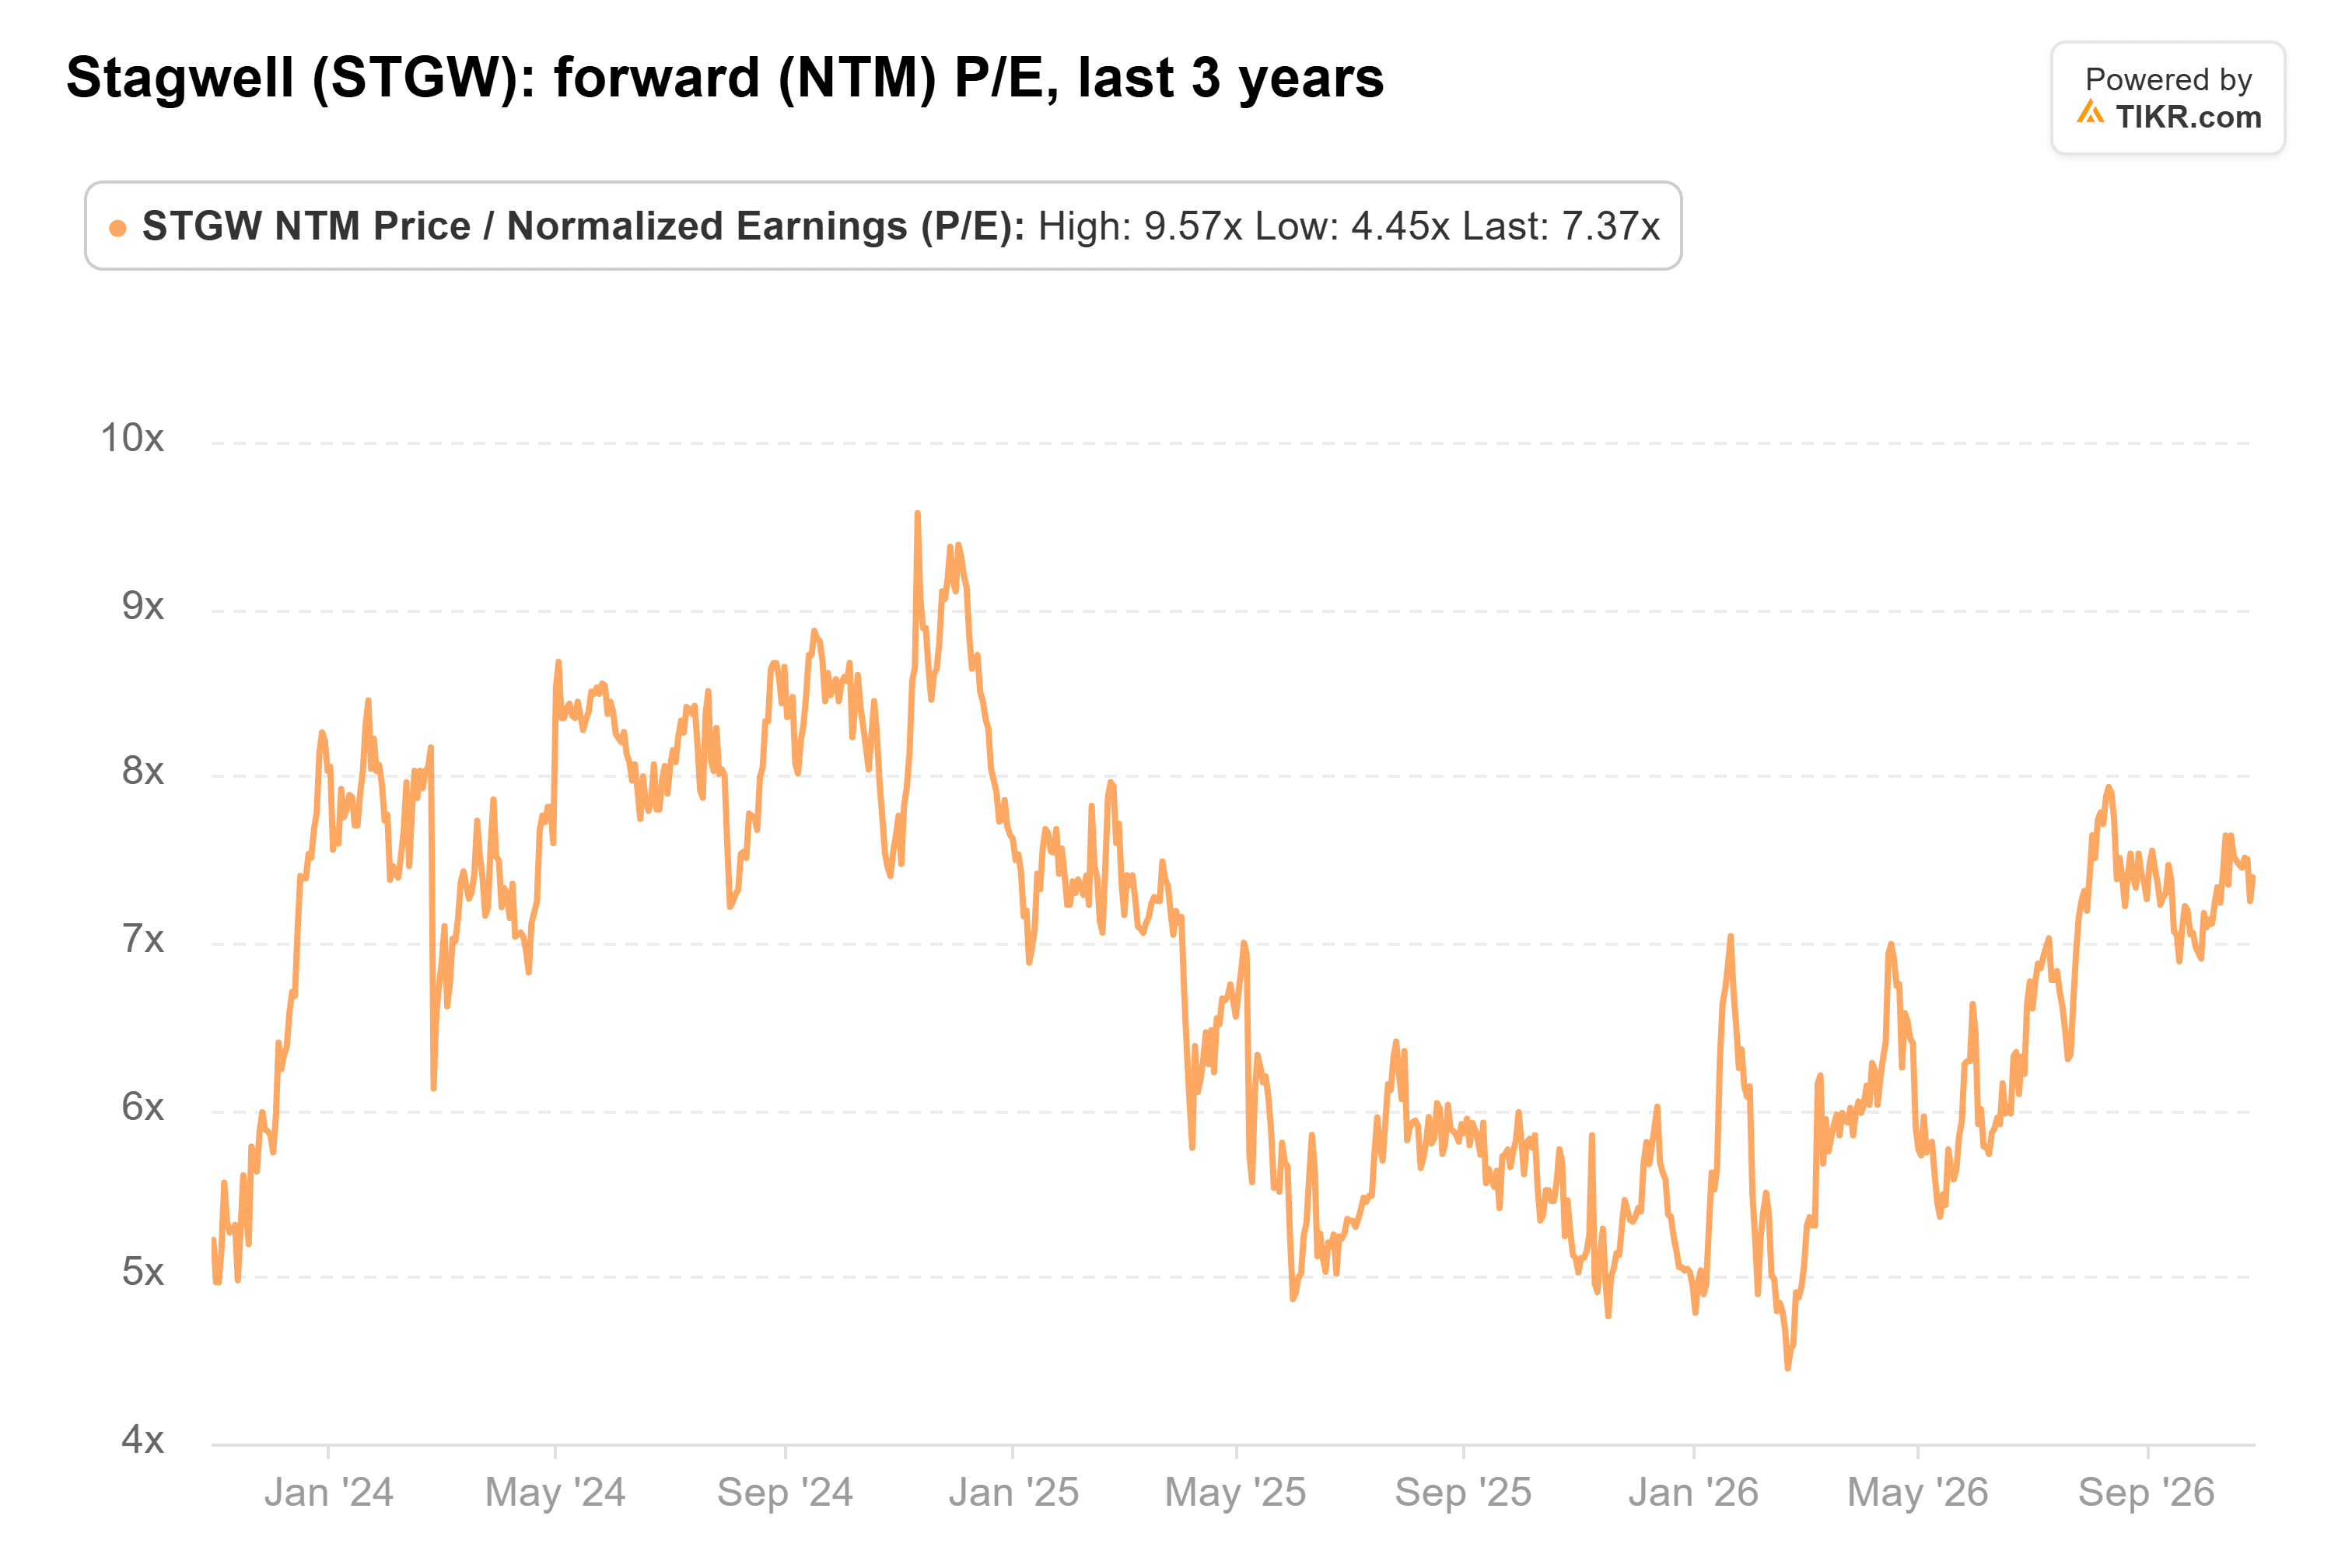
At Thursday’s close, it’s about 8.3x, still below its 9.6x peak from November 2024.
The pivot is showing up in the numbers. A business where a quarter of net revenue now comes from faster-growing tech segments earning 32% to 44% margins shouldn’t trade at an agency’s multiple, and at about 8x, Stagwell still does. Part of this quarter leaned on political spending ahead of the midterms, which helped Stagwell’s Communications segment and, by Omnicom’s account, its quarter too. That won’t repeat in 2027, so the agency side has to stop shrinking before the multiple gets much closer to its old peak.
So What Is Stagwell Stock Actually Worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Stagwell could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!