Key Takeaways
- Apple is building its own AI agent that can run devices, browse the web and write code, which puts it up against Anthropic, OpenAI and Alphabet’s Google.
- Apple trades at 37x forward earnings, the price of a company that collects fees from AI, yet its agent will start from models rebuilt on Google’s Gemini.
- Apple’s R&D spending jumped 32% to $45.8 billion in fiscal 2026, while analysts expect earnings per share to grow only about 5% in fiscal 2027.
- Apple’s biggest edge is controlling how rival agents reach its devices, and the Justice Department is already suing it over that kind of control.
Apple (AAPL) is building its own AI agent, one that can write code, browse the web, control apps and run your devices for you, Bloomberg reported Thursday after the close.
That puts Apple in a race with OpenAI and Anthropic (ANT). And Apple will run that race on technology from Alphabet (GOOG), which is arguably a competitor as well.
Mark Gurman, the reporter who broke the story, said on this week’s episode of his Power On podcast that saying “Siri” to his iPhone wakes up a HomePod mini two rooms away. That happens, he said, “because Apple has no idea what the hell it’s doing in AI. They never have. And it’s a joke.”
Apple starts on Google’s engine
Development is reportedly still early, and Apple is aiming to launch as soon as the end of next year. (Or, as we’d all call it now that AI has sped things up, an eternity.) The bigger problem is what’s underneath. Gurman says Apple has stayed out of the race to build its own large language models, and that its Apple Foundation Models “have been rebuilt with that core from Google, which in itself is embarrassing, but they had no choice.”
Gemini already powers parts of Apple Intelligence and Siri AI, and on Thursday Google added the ability to control a computer to Gemini. Google supplies the engine under Apple’s AI and competes with it for the same users, and I’d rather be in that spot than Apple’s.
TIKR tracks 45 analysts on Apple. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Apple, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Apple’s Analyst Ratings
Investors are paying for a toll collector
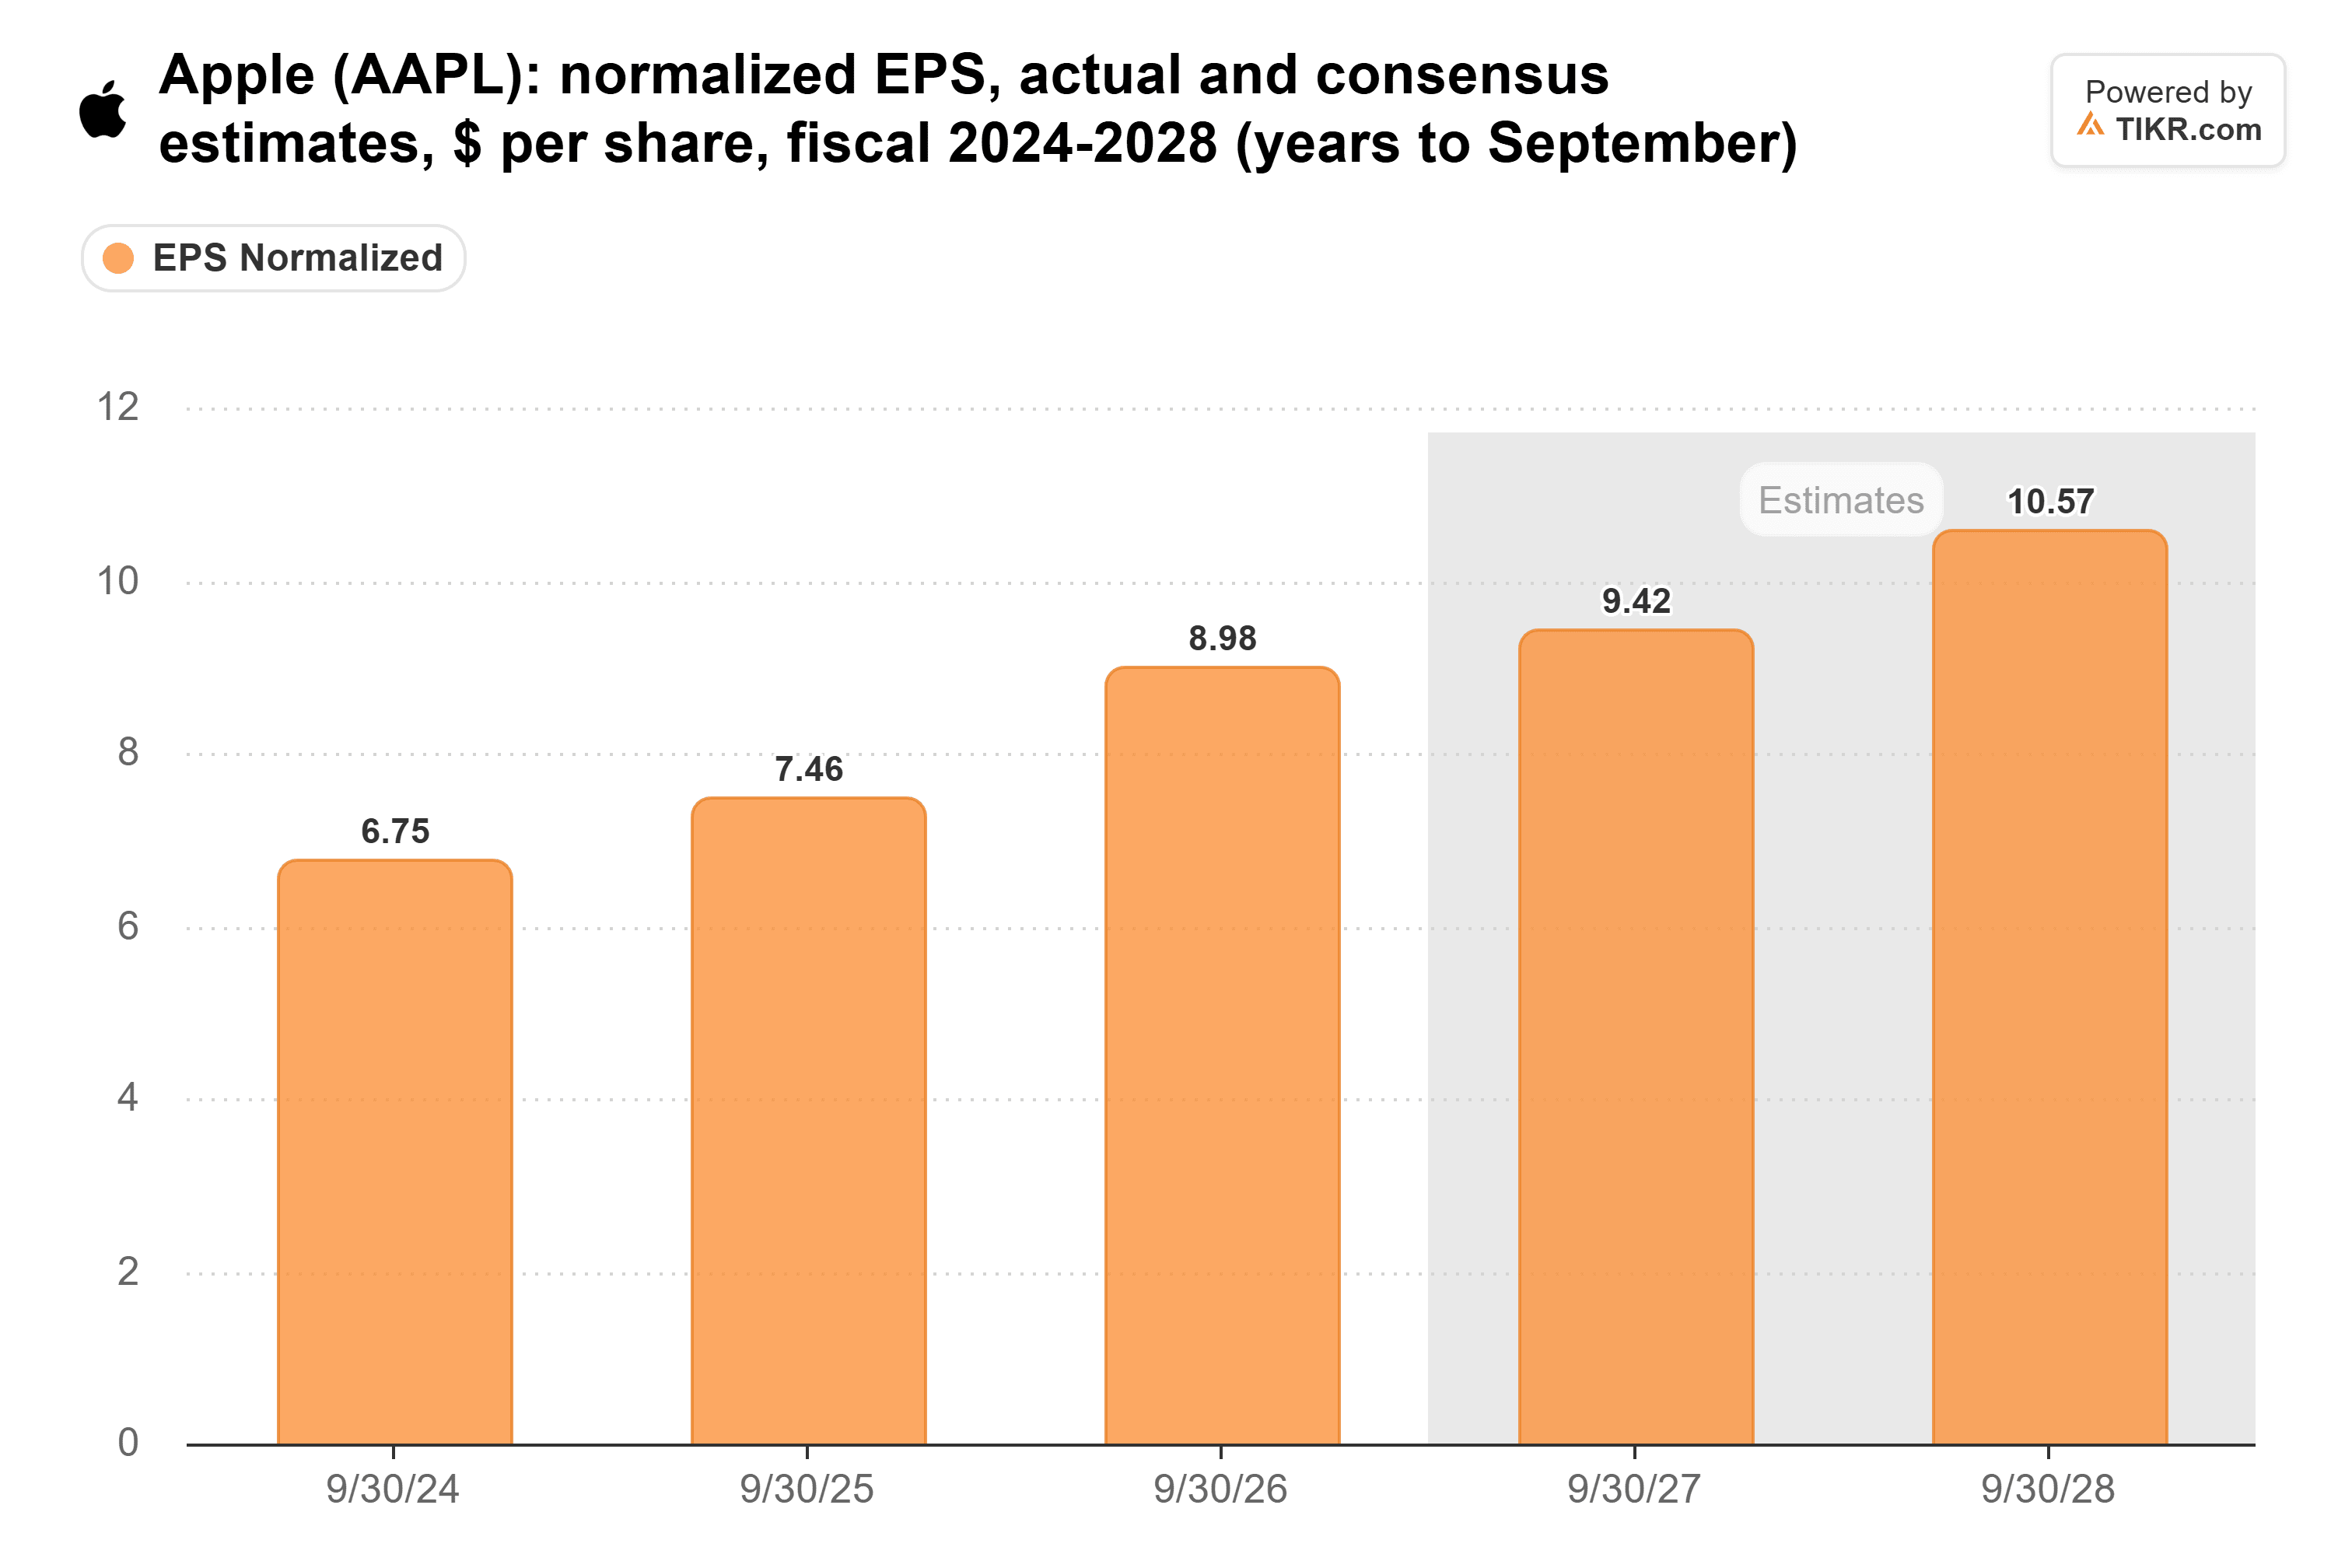
Analysts expect Apple’s earnings growth to slow to about 5% in fiscal 2027 before picking back up to about 12% in fiscal 2028:
The multiple is a different story. Apple trades at 37x forward earnings, just below the five-year high of 38x it hit in October and well above its 29x average:
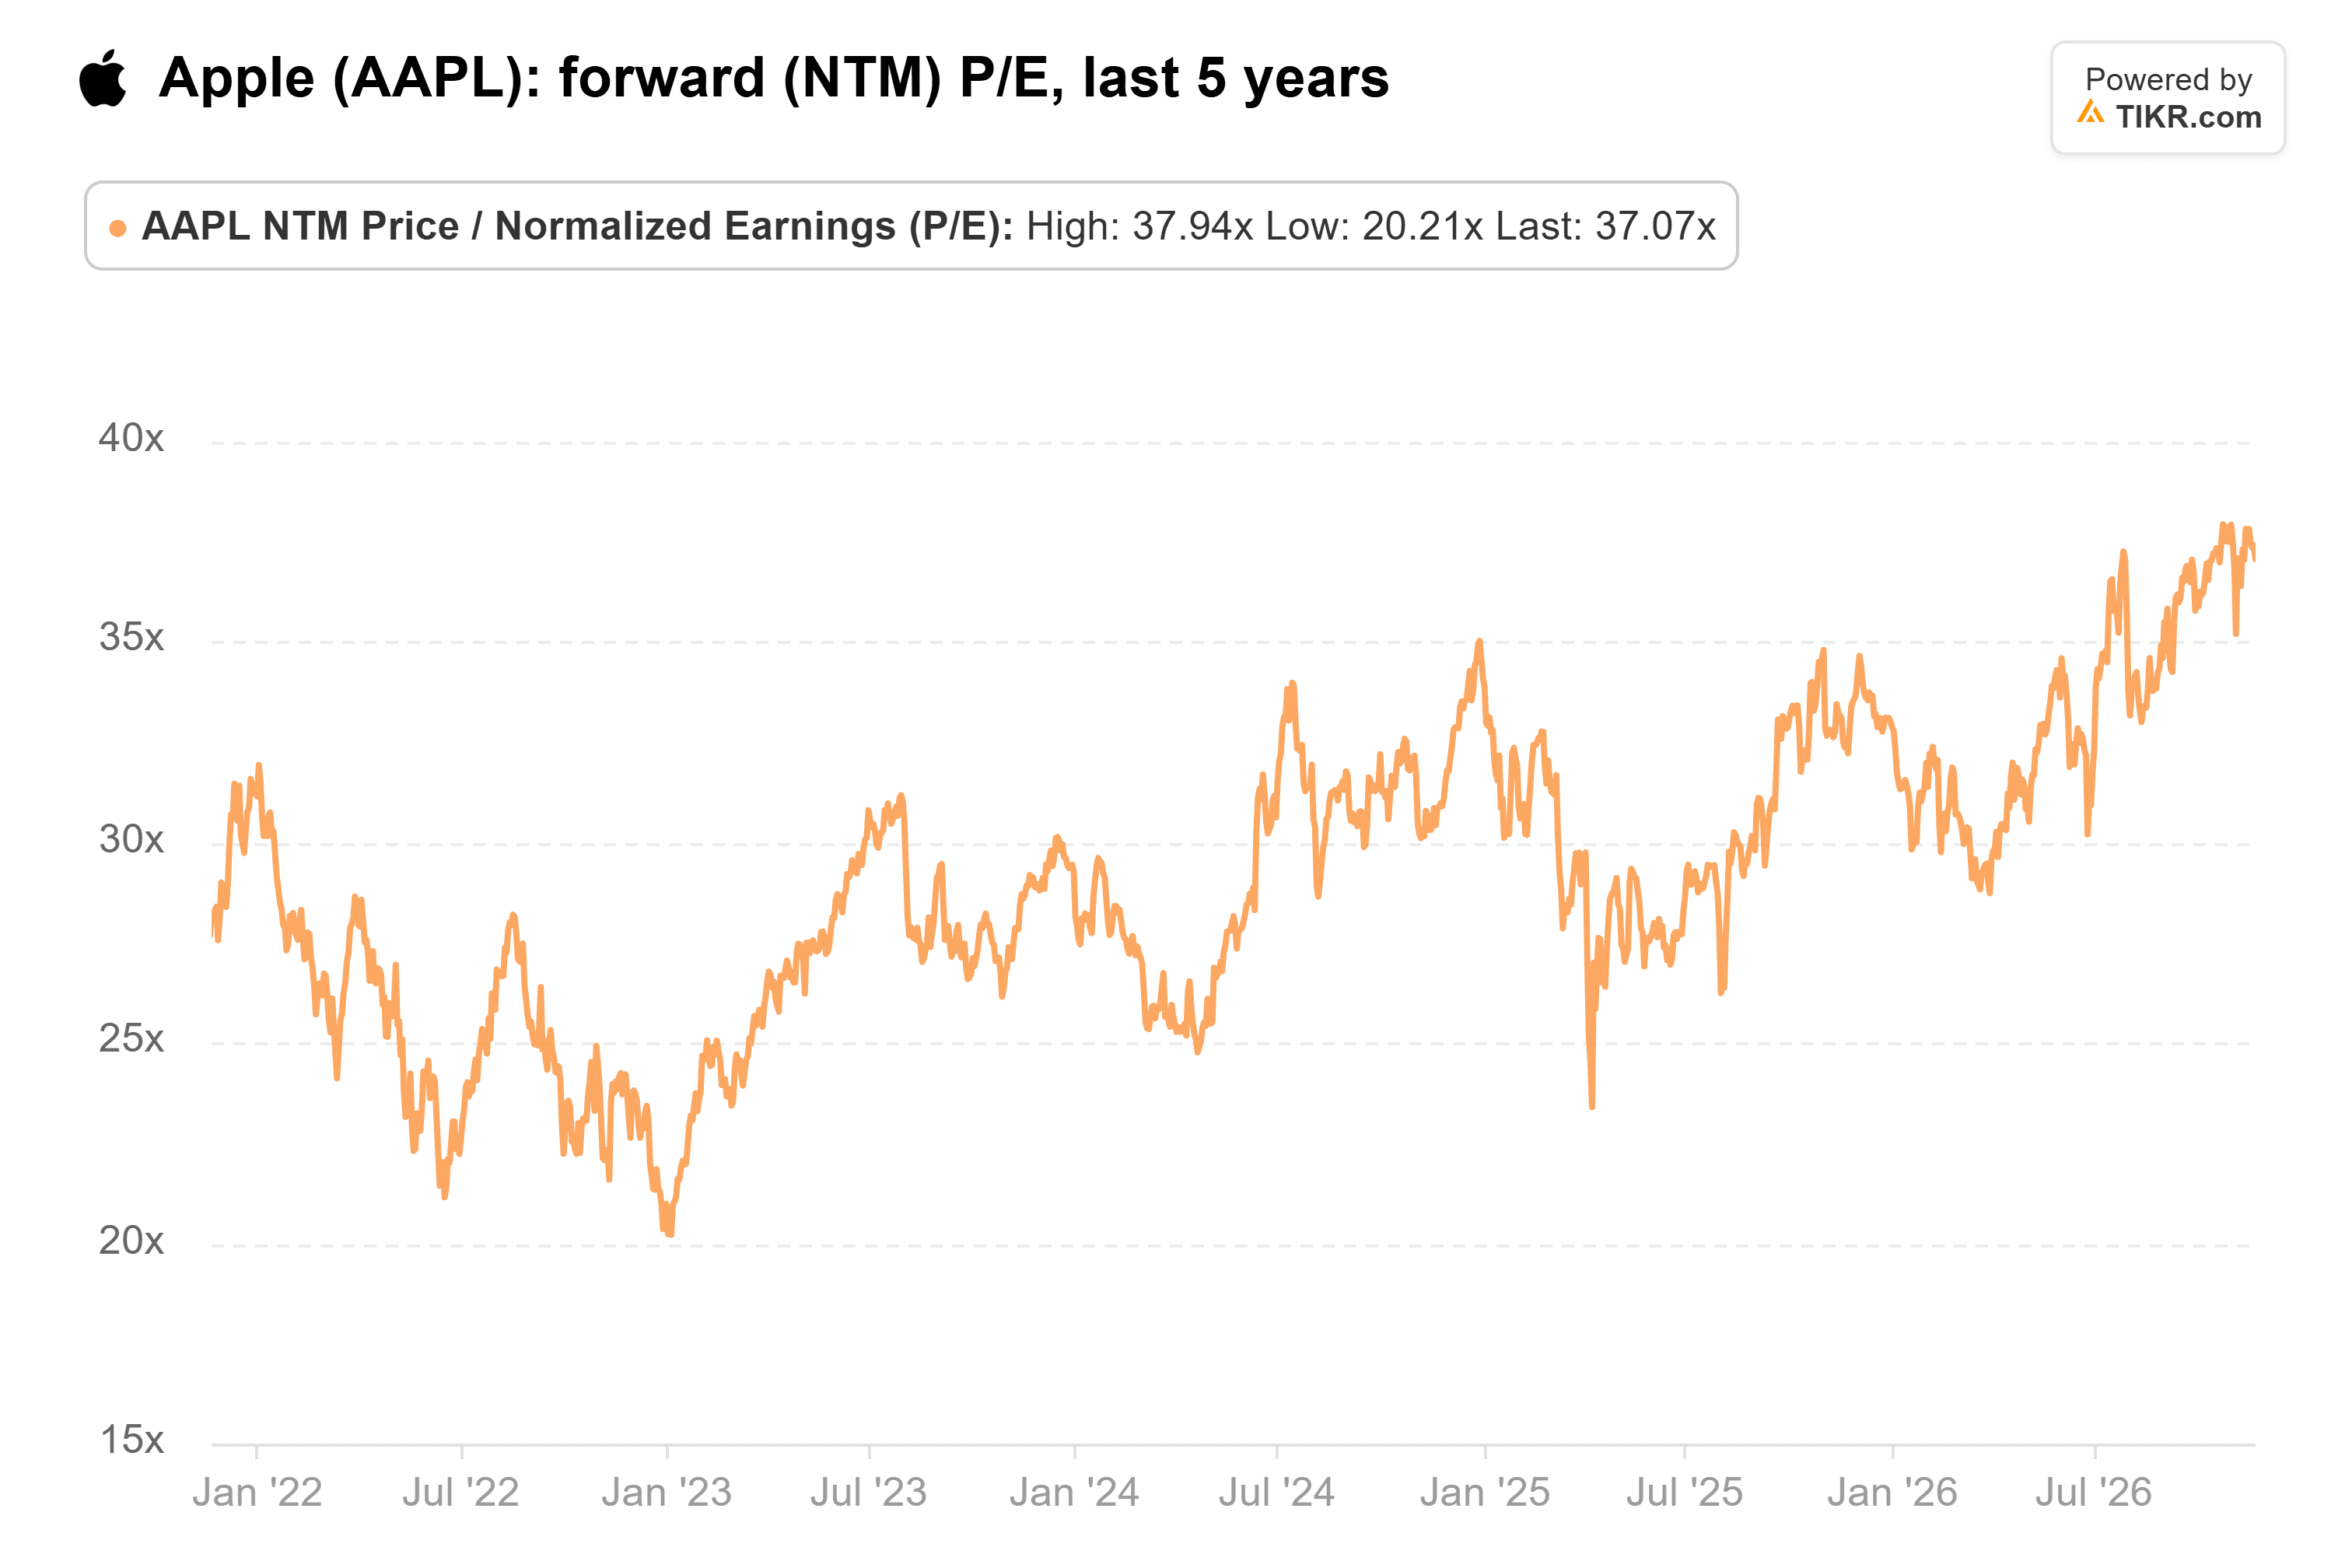
Investors have paid that much for a company that sat out the AI spending race. Apple’s capital spending fell 29% in fiscal 2026, while Google kept paying to be Safari’s default search engine and developers kept paying App Store commissions. That only makes sense if Apple keeps collecting fees while everyone else spends.
Catching up costs money
Apple pays for AI mostly through R&D, and that line is already climbing fast. R&D jumped 32% to $45.8 billion in fiscal 2026, after rising 5% to 14% a year over the three years before:
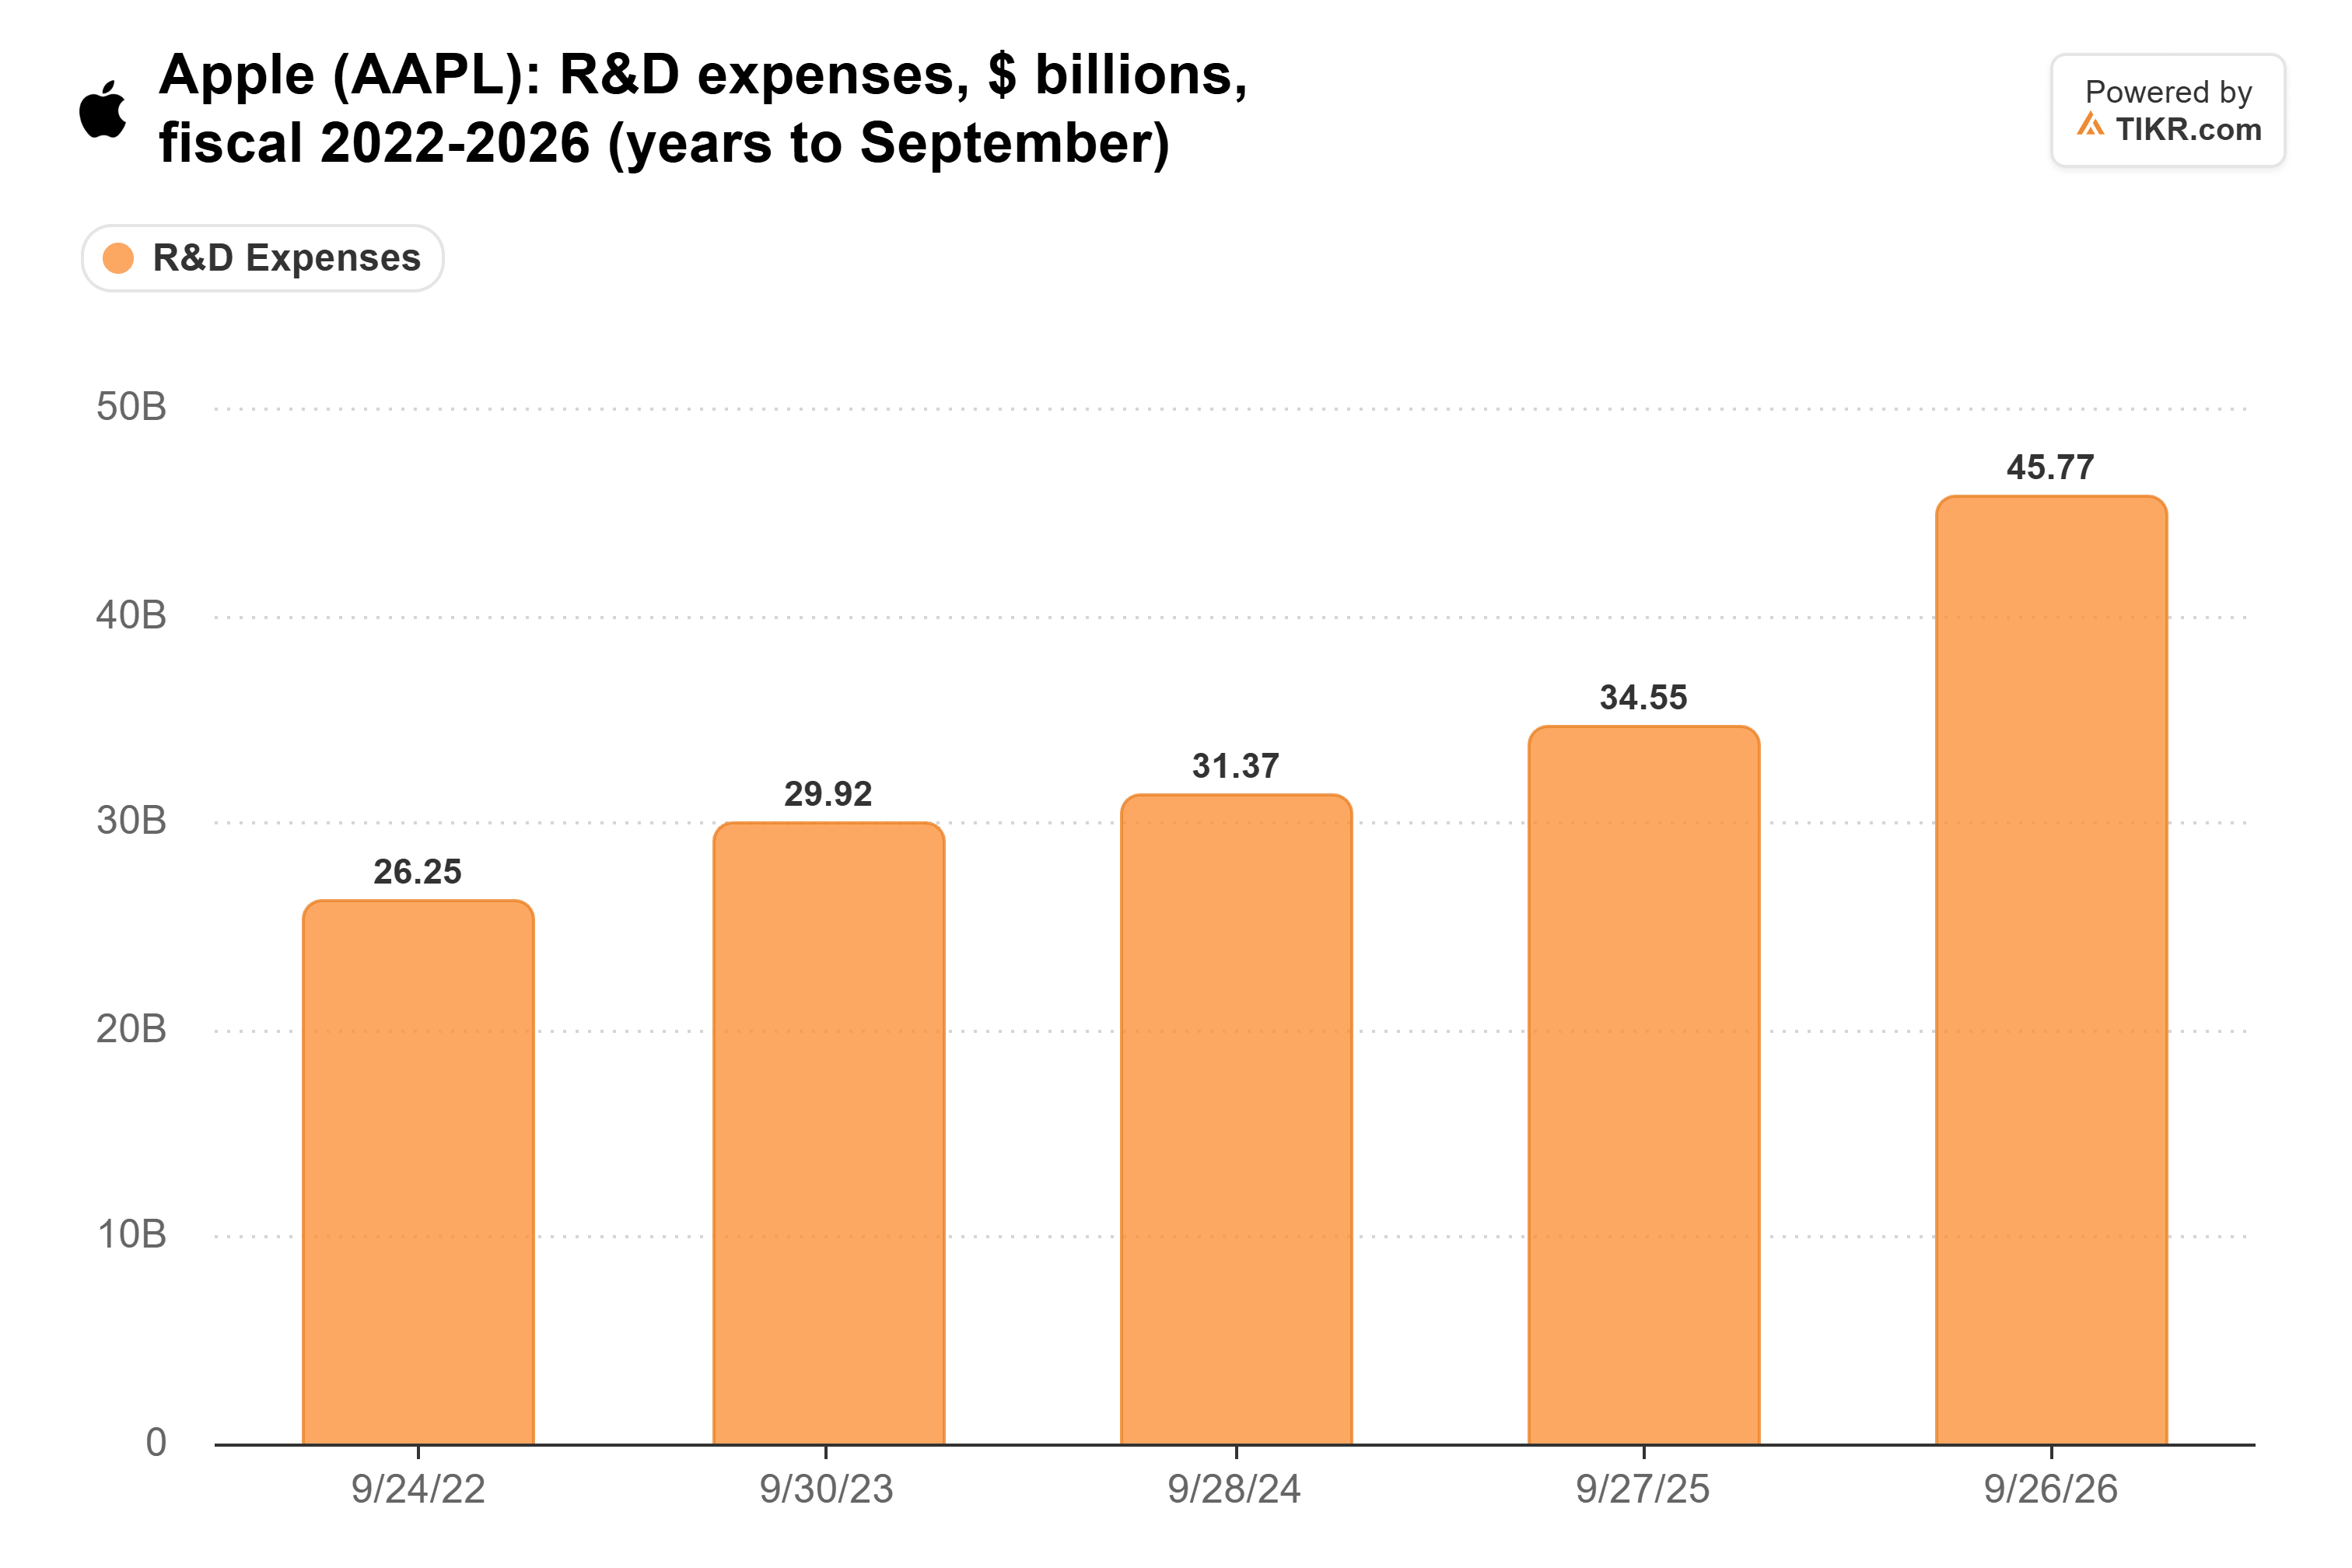
Not all of that is AI. But an agent that runs code and acts for you needs tight permissions and sandboxing, by Apple’s own description, and Apple has to build it fast against rivals that Gurman says ship new features “on a weekly, if not more frequent basis.” All of that spending comes out of the earnings investors are paying 37x for.
Apple still controls the front door
Plus: Apple doesn’t need the best model if it gets to decide how other agents reach its more than 2.5 billion active devices. In the macOS 27.3 beta, ChatGPT users reportedly need 14 steps to let a third-party tool take control of their Mac, up from four.
I suspect those extra steps matter more to Anthropic than Apple’s agent does, since Claude is a top-five free app in Apple’s own App Store. Of course, the Justice Department has already sued Apple over blocking third-party access to features and hardware, so tightening the gate could bring more of the same.
Wait for a better price
Building an agent is the right move, since Apple has to own one or watch assistants route around the App Store. But Apple is starting behind, on Google’s models, while its R&D bill climbs and the stock sits near the top of its five-year range. At 37x, I’d wait for a better price.
The next test is Apple’s December-quarter report in late January. If operating expenses keep growing faster than revenue, analysts’ $9.42 of fiscal 2027 EPS gets harder to reach, and the multiple has room to fall.
So what is Apple stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Apple could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!