


What Happened?
Anthropic’s spending is becoming large enough to materially change the outlook for public companies.
Akamai Technologies (NASDAQ: AKAM) shares surged after Anthropic committed $11.6 billion over seven years to Akamai’s cloud infrastructure. Barron’s called Akamai a “New Hot AI Stock” and said it “won’t be the last,” raising the question of which infrastructure supplier could benefit next as AI agents require more compute, networking, and gateway capacity.
Cloudflare (NYSE: NET) is one of the clearest names to watch, but its valuation suggests investors already expect far more growth from the company than they historically expected from Akamai.
Anthropic Just Changed Akamai’s Growth Story
Anthropic committed approximately $11.6 billion over seven years for Akamai cloud capacity and managed services. The relationship can expand by another $9 billion, bringing the total potential commitment to roughly $20 billion. Akamai also issued Anthropic a warrant that could ultimately represent approximately 5% of Akamai’s common stock outstanding.
Rather than repeat the full transaction structure, TIKR’s earlier Akamai coverage breaks down the deal in more detail.
The more important point here is how much a contract of this size can alter Akamai’s growth profile.
Akamai generated about $4.21 billion in revenue in 2025, after revenue had grown at roughly mid-single-digit rates in recent years. TIKR consensus estimates now call for approximately $4.49 billion in 2026, $5.19 billion in 2027, $6.29 billion in 2028, and $8.17 billion in 2029.
That would accelerate annual revenue growth from around 7% in 2026 to roughly 16% in 2027 and 21% in 2028.

That acceleration shows why the Anthropic contract matters. Akamai had been a relatively slow-growing infrastructure company, so one multibillion-dollar customer agreement can materially change its growth trajectory.
The economics also require substantial investment. Akamai expects roughly $5.5 billion of cumulative capital expenditures tied to the initial commitment. Service is expected to begin in late Q2 2027, revenue should ramp during the second half of 2027, and Akamai expects to reach the full contracted run-rate by the end of 2028. After that, the agreement is expected to contribute approximately $1.7 billion of annual revenue for the remainder of the term.
Anthropic Is Starting to Move Supplier Stocks
Akamai is not the only listed company getting attention from an Anthropic relationship.
Anthropic and Accenture recently announced that each company expects to invest at least $1 billion over five years to build a team focused on model evaluation, red-teaming, alignment assessments, and safeguards.
Anthropic also selected Twist Bioscience to independently manufacture and test AI-designed protein binders created using Claude. Twist evaluated 1,260 binders across 15 targets in less than three weeks, showing that Anthropic’s supplier relationships already extend beyond traditional computing infrastructure.
Akamai is different because the size of Anthropic’s commitment is large enough to directly reshape its financial outlook.
That gives more weight to a recent point from Box CEO Aaron Levie.
Speaking on TBPN, Levie said the “Cloudflares of the world” were “totally on fire” because AI agents need sandboxes, compute, networks, and gateways.
The Akamai deal makes that argument more concrete.
Cloudflare Is the More Expensive AI Edge Bet
Cloudflare provides networking, cybersecurity, application delivery, developer infrastructure, and edge computing services that overlap with several of the infrastructure needs Levie described.
As AI agents interact with websites, APIs, enterprise applications, and cloud environments, they require secure connectivity, traffic routing, compute, and gateways. That could create additional demand for Cloudflare’s network.
The key question is how much of that opportunity investors already expect.
Cloudflare currently trades at roughly 145x NTM EV/EBITDA, compared with approximately 11x for Akamai, according to TIKR.
Over the past three years, Cloudflare’s multiple has averaged around 106x, versus roughly 10x for Akamai.
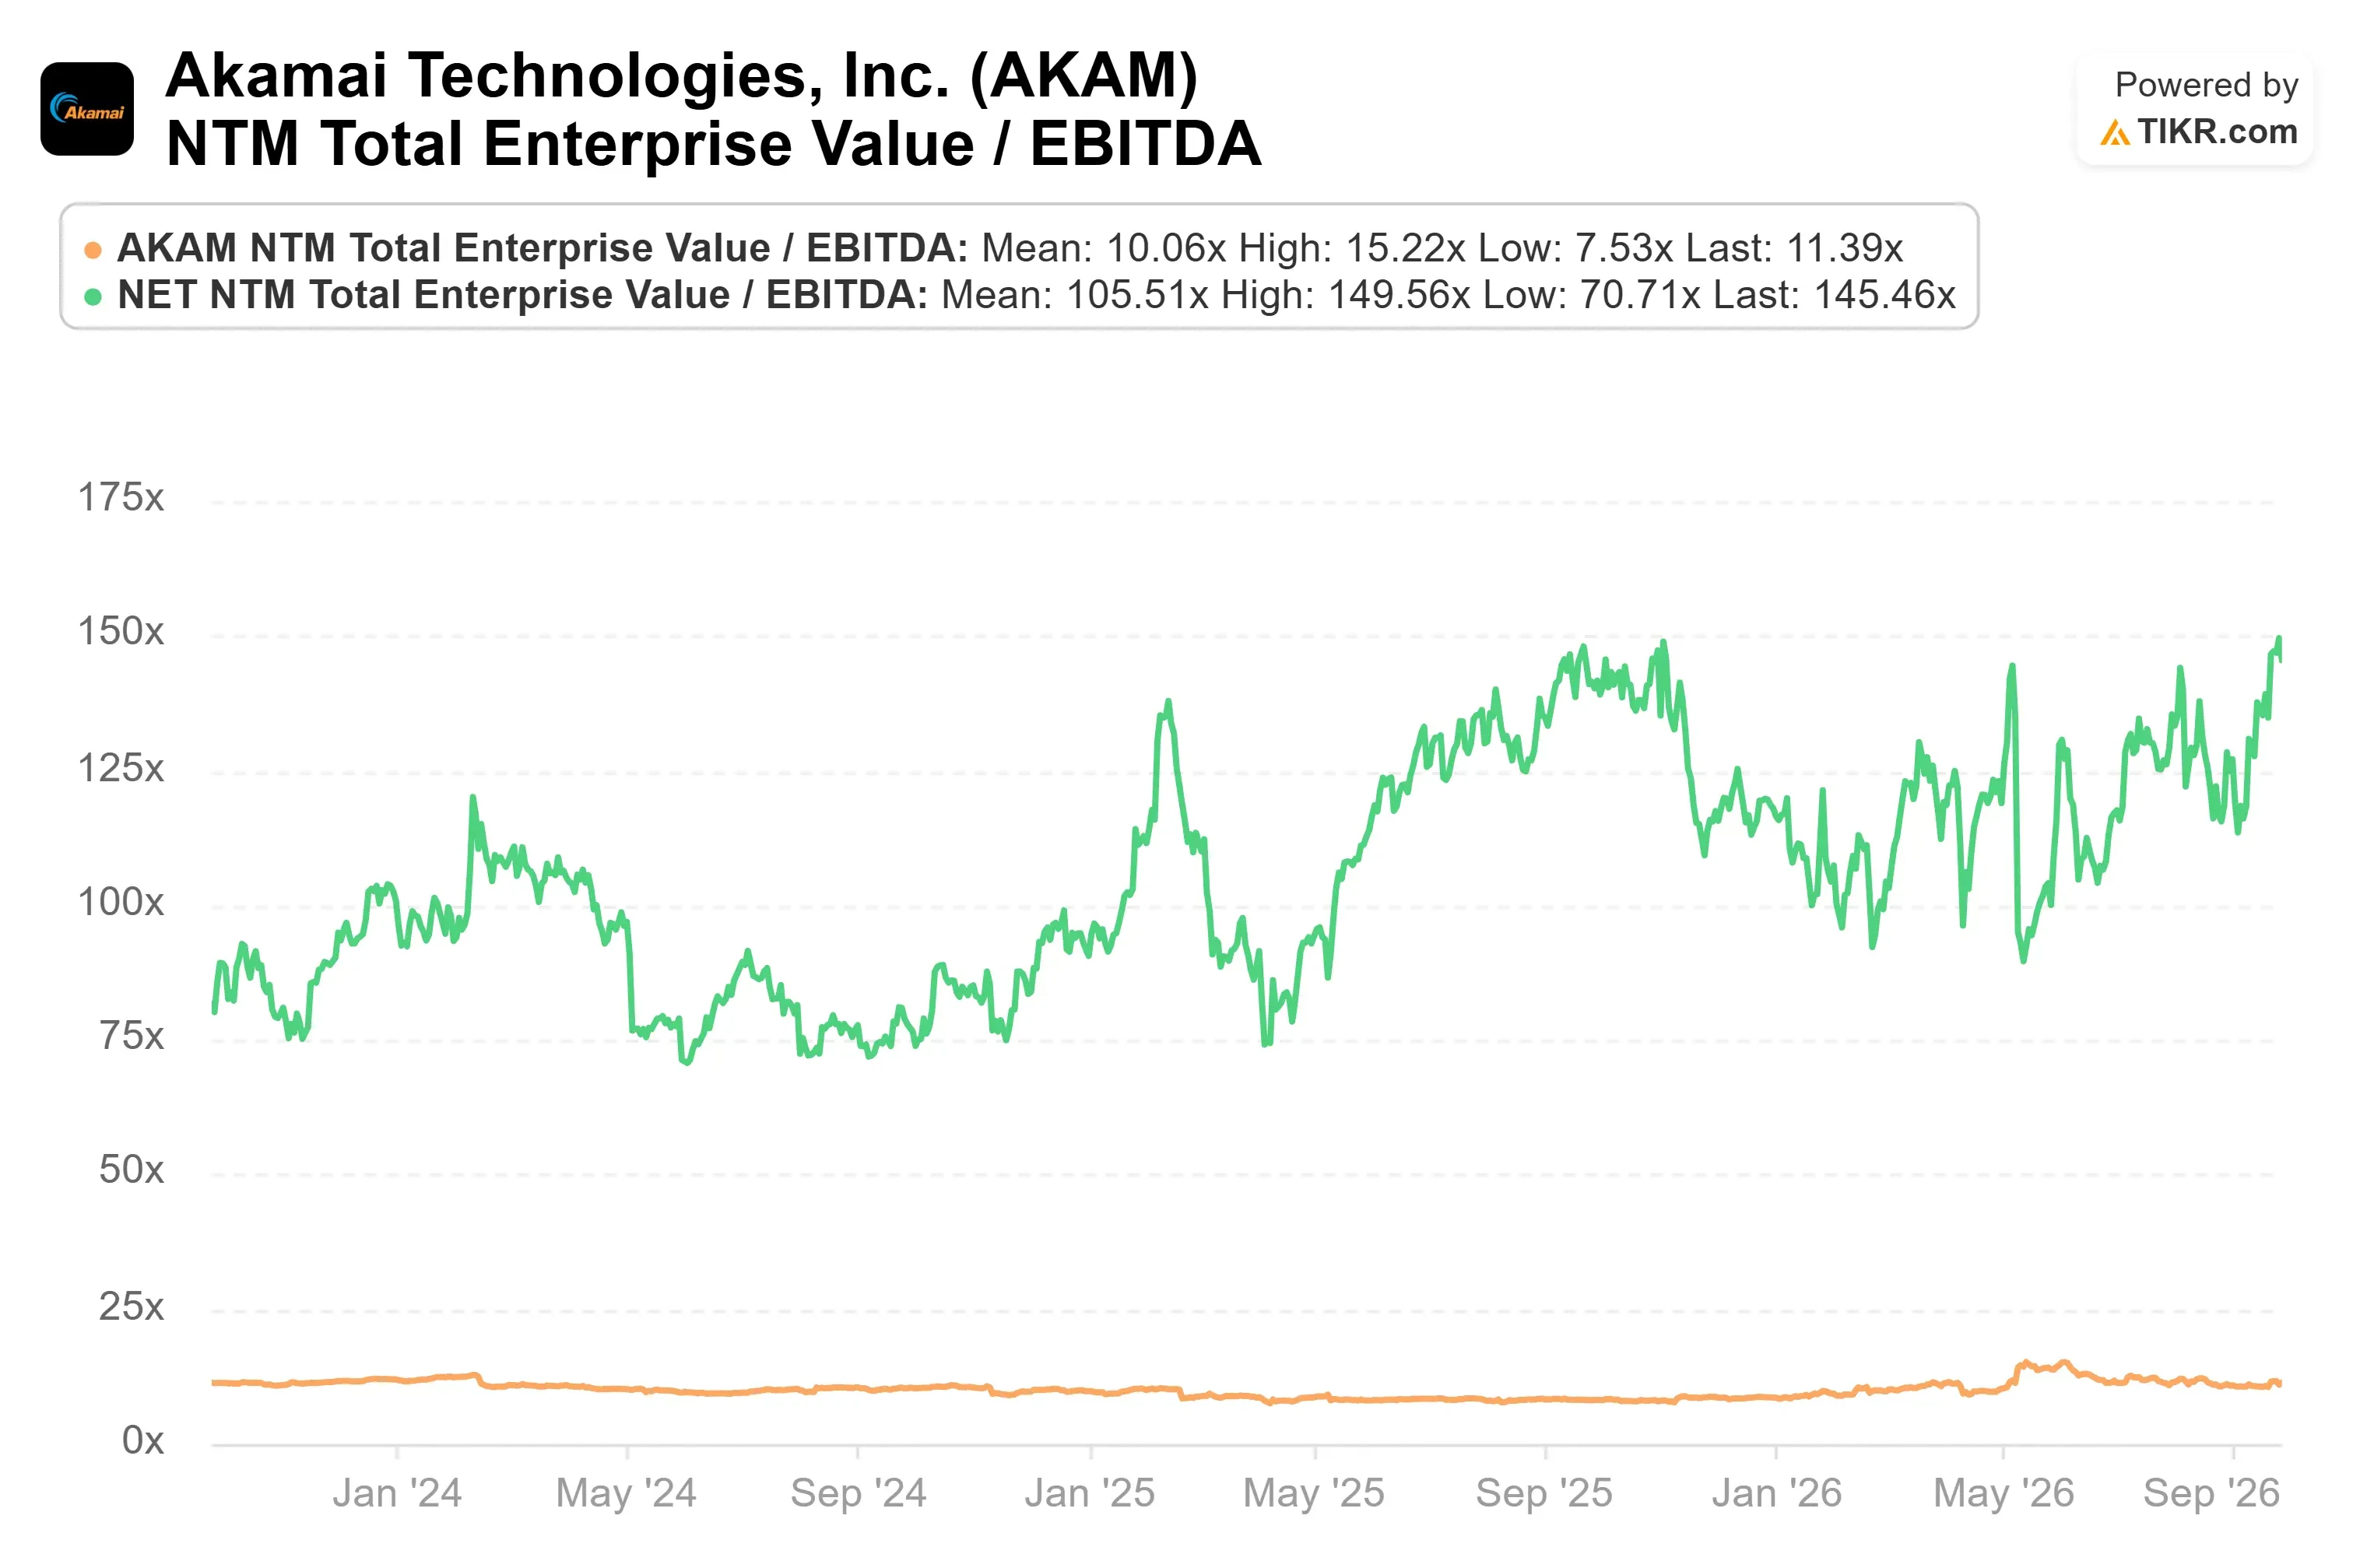
That valuation gap explains why the Anthropic announcement could re-rate Akamai so sharply.
Akamai entered the announcement trading at a valuation more typical of a mature infrastructure company. Cloudflare already carries a large premium for faster expected growth.
An AI-agent boom could therefore benefit Cloudflare’s business without necessarily creating the same valuation reset Akamai experienced.
Cloudflare’s Estimates Already Assume Strong Growth
Cloudflare’s revenue estimates reinforce that point.
TIKR consensus estimates call for roughly $2.87 billion of revenue in 2026, increasing to approximately $3.70 billion in 2027, $4.74 billion in 2028, and $6.00 billion in 2029.
That represents expected annual growth of about 32% in 2026, 29% in 2027, 28% in 2028, and 27% in 2029.

Those forecasts leave Cloudflare with a much higher bar.
AI-agent demand could help the company sustain or exceed that growth, but Cloudflare already trades at a valuation that assumes years of rapid expansion.
One Akamai Deal Does Not Prove an Edge Boom
The biggest objection is that Anthropic’s Akamai agreement may say more about Anthropic’s specific infrastructure needs than about the entire edge market.
Akamai said the contract will support Anthropic’s growing CPU workload demands, so the agreement does not automatically mean other networking and edge providers will receive similar commitments.
The headline contract value also does not translate directly into profit.
Akamai expects approximately $5.5 billion of cumulative capital spending to support the initial commitment, including roughly $1.7 billion in Q4 2026 and approximately $3.1 billion in 2027.
The deal therefore shows that AI companies can materially change a supplier’s revenue outlook, but it does not yet prove a broad edge-infrastructure boom.
What Comes Next
Cloudflare now provides a useful test of whether Anthropic’s infrastructure spending points to a broader opportunity.
The company already trades at roughly 145x NTM EV/EBITDA, while analysts expect revenue growth to remain near the high-20% range through 2029.
The next evidence will come from whether AI agents generate enough additional network traffic, security demand, developer workloads, and gateway usage to push Cloudflare above those already-high expectations.
Akamai showed how dramatically one Anthropic contract can alter the outlook for a slower-growing supplier.
For Cloudflare, the question is different: can AI-agent demand grow fast enough to support expectations that are already extremely high?
See analysts’ growth forecasts and price targets for Cloudflare (It’s free) >>>
How Much Upside Do AKAM and NET Stocks Have From Here?
Investors can estimate what Akamai Technologies, Cloudflare, or almost any stock could be worth in under a minute using TIKR’s New Valuation Model tool.
All it takes is three simple inputs:
- Revenue Growth
- Operating Margins
- Exit P/E Multiple
From there, TIKR calculates the potential share price and total returns under Bull, Base, and Bear scenarios so you can quickly see whether a stock looks undervalued or overvalued.
If you’re not sure what to enter, TIKR automatically fills in each input using analysts’ consensus estimates, giving you a quick, reliable starting point.
Value Akamai Technologies and Cloudflare in under 60 seconds with TIKR (It’s free) >>>


