


Key Takeaways
- Microsoft shares fell as much as 3% Tuesday after Anthropic launched Claude Sheets, Claude Whiteboards and Claude Data, a set of office tools.
- Anthropic product leader Nicholas Lin called Claude Sheets “fairly basic” for now, while Microsoft 365 cloud revenue grew 17% to $27.8 billion last quarter.
- Capital spending rose to $45.2 billion last quarter, yet Microsoft still produced $18.6 billion of free cash flow while Alphabet’s turned negative.
- Microsoft guided 49% to 50% Azure growth for the December quarter, and its report expected in late January will test that and Office growth.
Microsoft’s newest rival in office software is also one of its biggest cloud customers.
Microsoft (MSFT) shares slid as much as 3% on Tuesday after Anthropic launched a set of workplace tools inside Claude. The lineup includes Claude Sheets, a spreadsheet service that closely resembles Excel and Google Sheets from Alphabet (GOOGL).
The timing adds pressure. Anthropic is expected to make its Wall Street debut later this month, and its filing shows its revenue run rate rose by $10 billion in October.
Still, one sell-off doesn’t rewrite a business. Microsoft posted a quarter two weeks ago that beat on nearly every line.
Anthropic moves onto Office turf
Anthropic introduced three headline tools on Tuesday:
- Claude Sheets, a spreadsheet service with Claude built in
- Claude Whiteboards, for team brainstorming
- Claude Data, a dashboard builder
It also added a video call assistant, and many of the features launched in beta for paid users.
Even Anthropic is managing expectations. Product leader Nicholas Lin told Bloomberg that Claude Sheets is “fairly basic” for now. He added that Microsoft and Google products still fit more advanced enterprise work, such as financial modeling.
That nuance didn’t stop the selling. Yet the reaction looks big next to what Microsoft just reported…
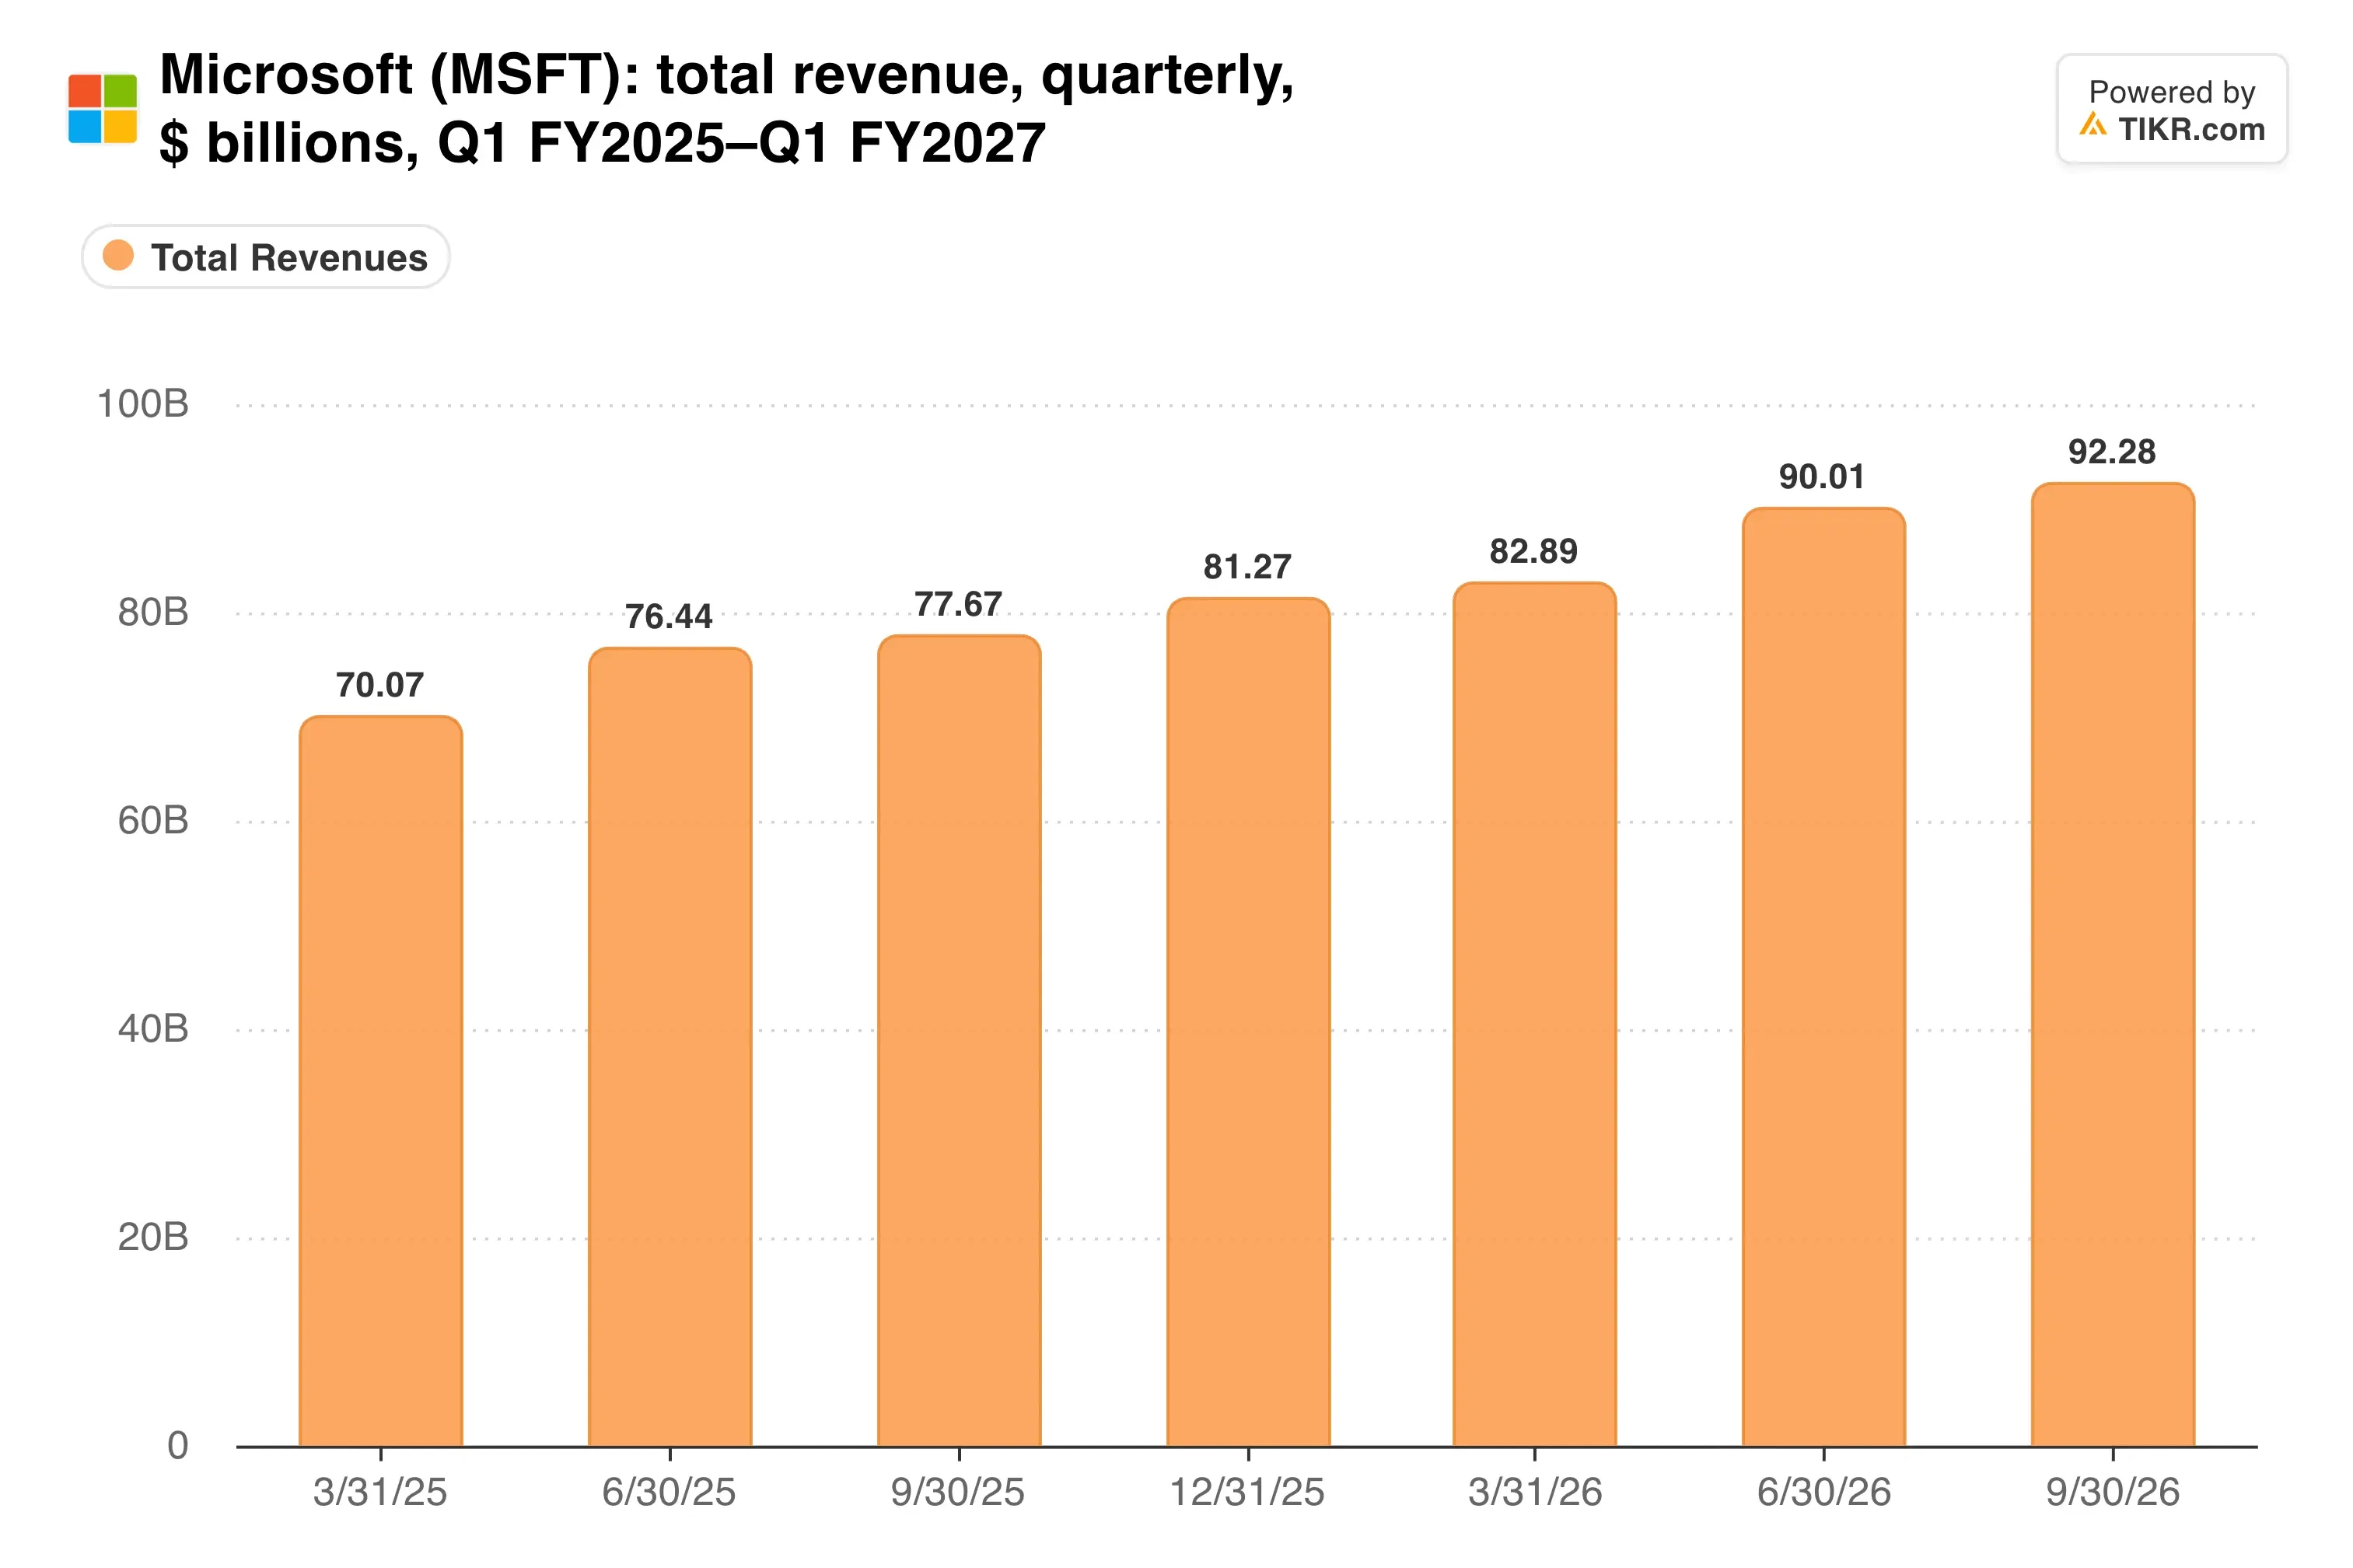
Revenue rose 19% to $92.3 billion in the September quarter. Adjusted EPS of $4.89 also topped the $4.73 consensus.
TIKR tracks 56 analysts on Microsoft. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Microsoft, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Microsoft’s Analyst Ratings
What Office actually earns
The worry centers on Microsoft 365 cloud, the subscription engine behind Excel, Word and Teams. It brought in $27.8 billion last quarter, up 17%, or about 30% of total revenue.
That business sits inside Agents and Infra, the segment that also holds Azure. Segment operating income reached $40.6 billion on $76.8 billion of revenue.
So how much margin is really at stake?
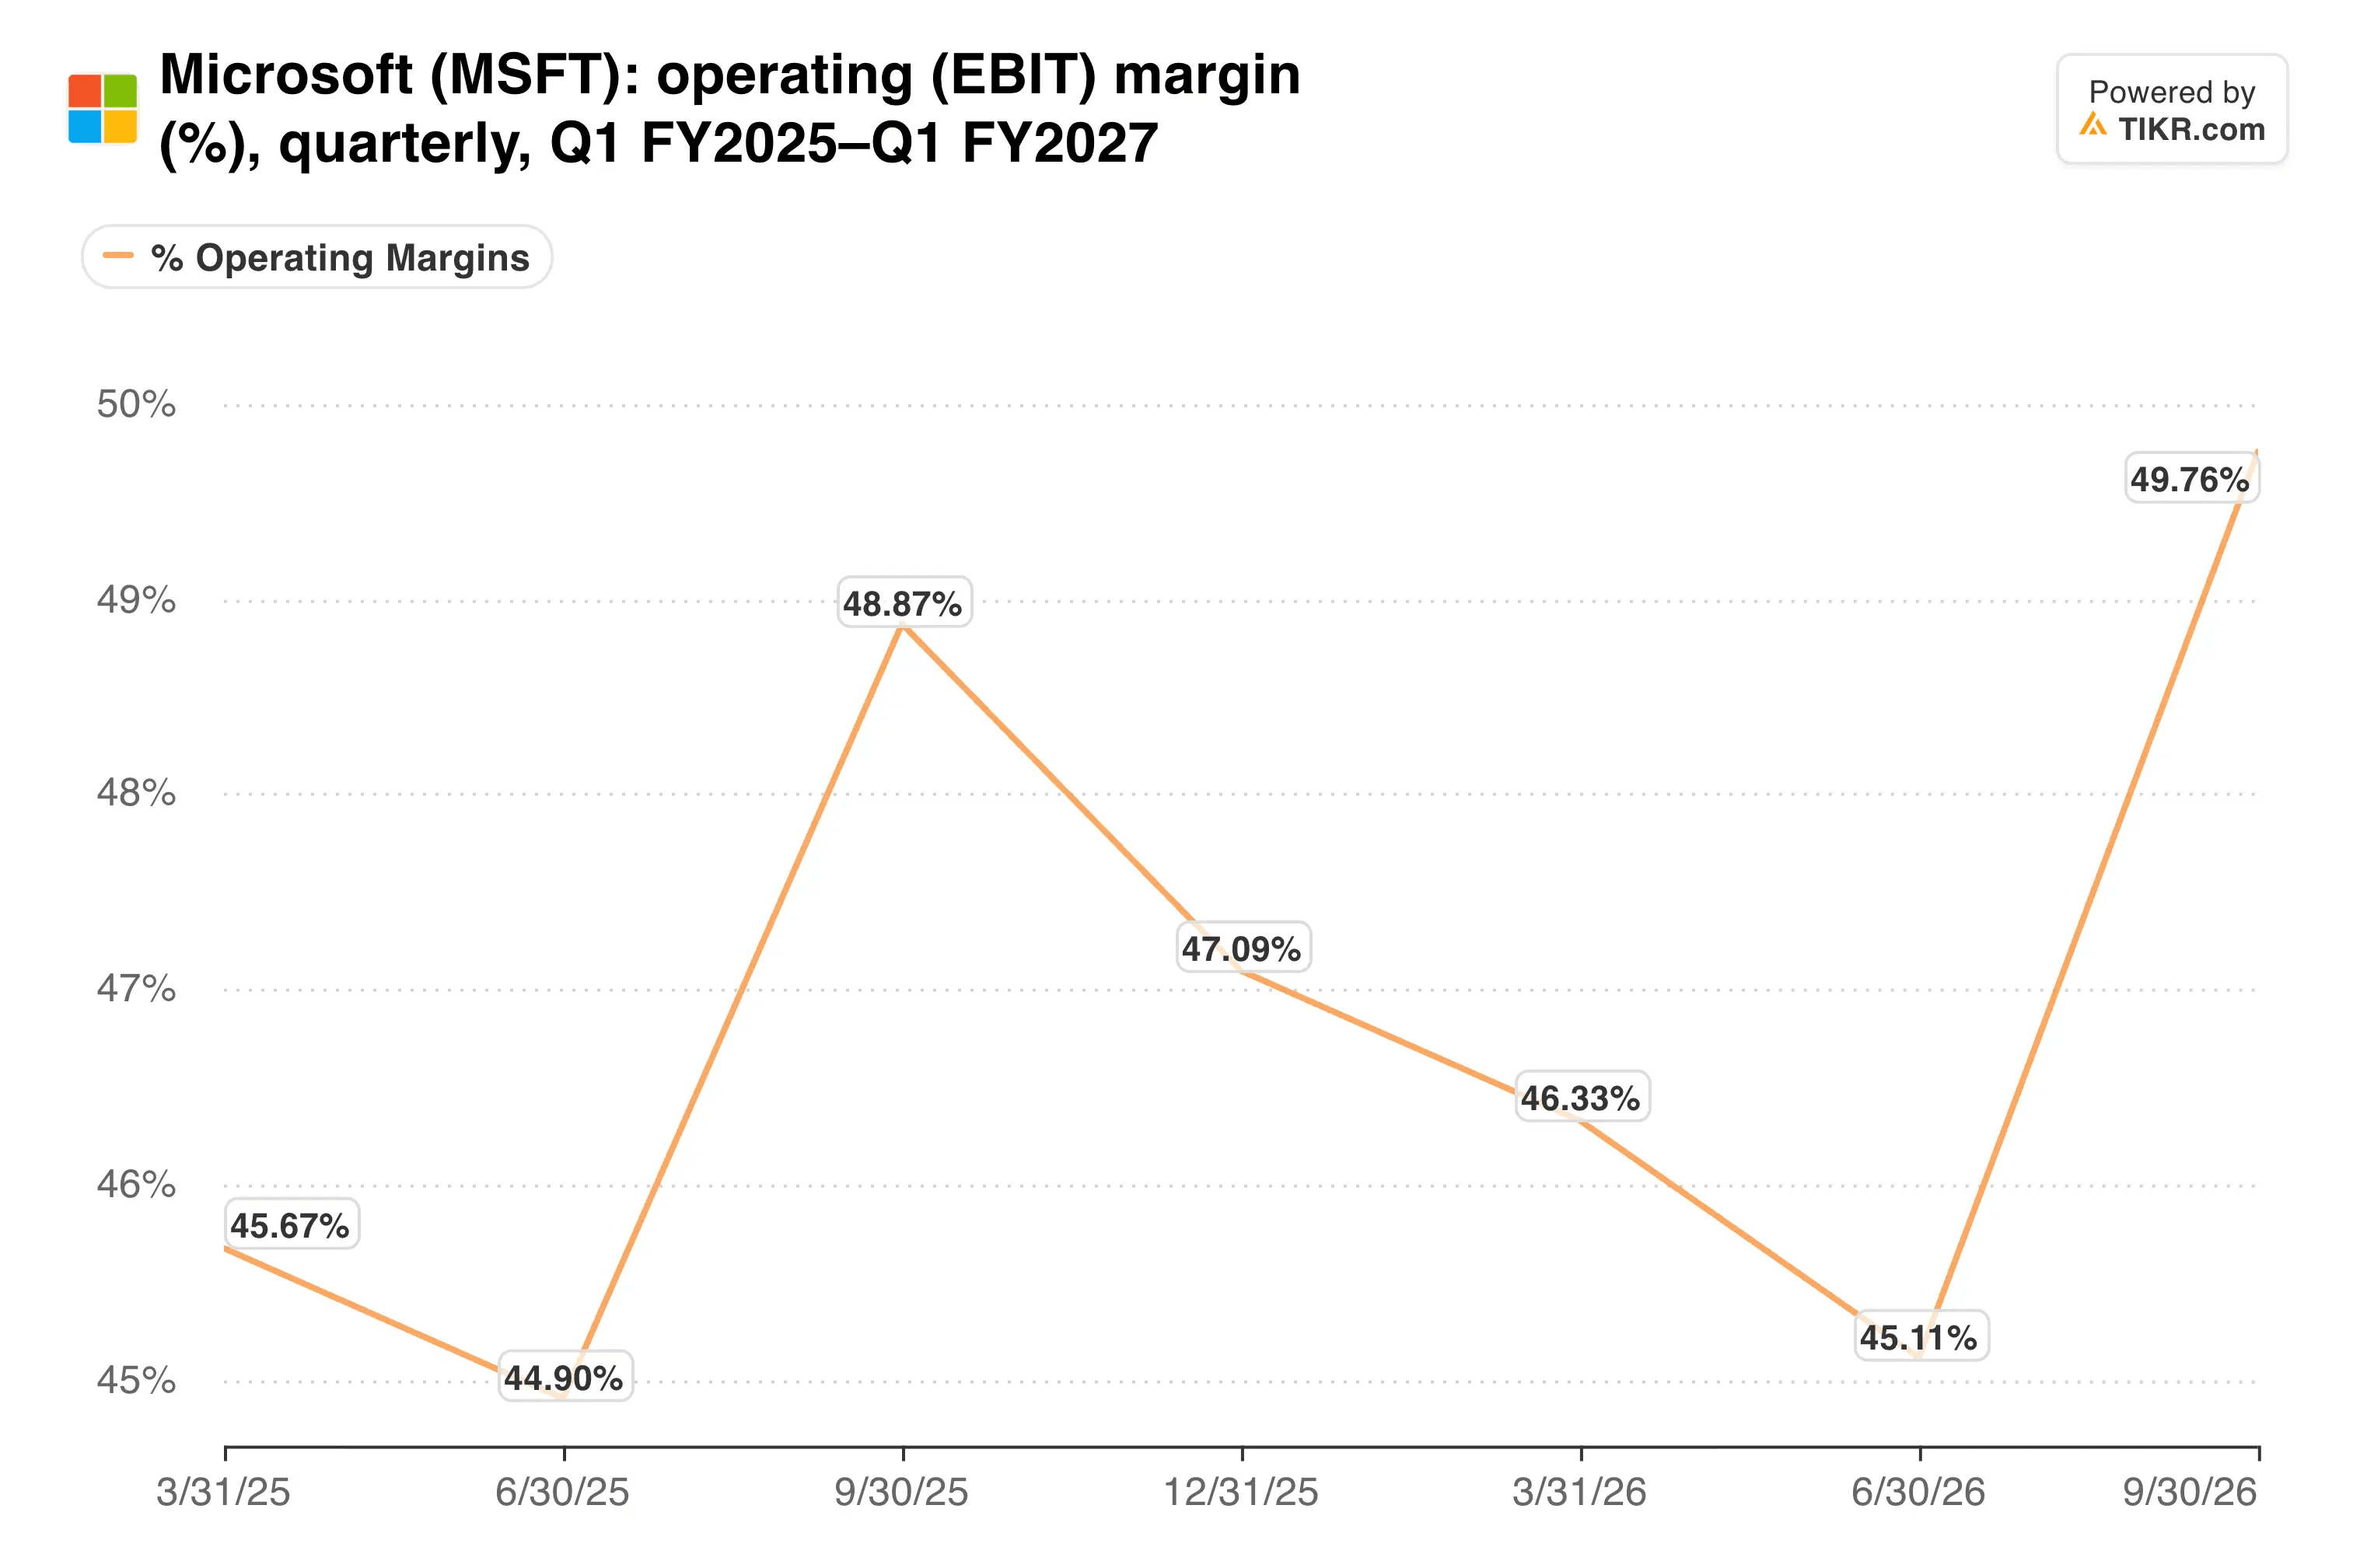
Operating margin reached 49.8% last quarter, up from 48.9% a year earlier.
Then there’s the awkward twist. Anthropic agreed in November 2025 to buy $30 billion of Azure compute, while Microsoft agreed to invest up to $5 billion in the company. That means part of Claude’s growth runs through Azure, where revenue jumped 48% to $33.2 billion.
Spending is the bigger test
Cost may be Microsoft’s harder problem. Capital spending, including finance leases, rose to $45.2 billion from $34.9 billion a year ago, and Microsoft expects more than $50 billion this quarter.
Even so, cash generation held up better than at peers. Microsoft produced $18.6 billion of free cash flow, down 27% from a year ago, while Alphabet posted negative free cash flow of $9.07 billion in its third quarter.
Here’s how that squeeze has built over two years.
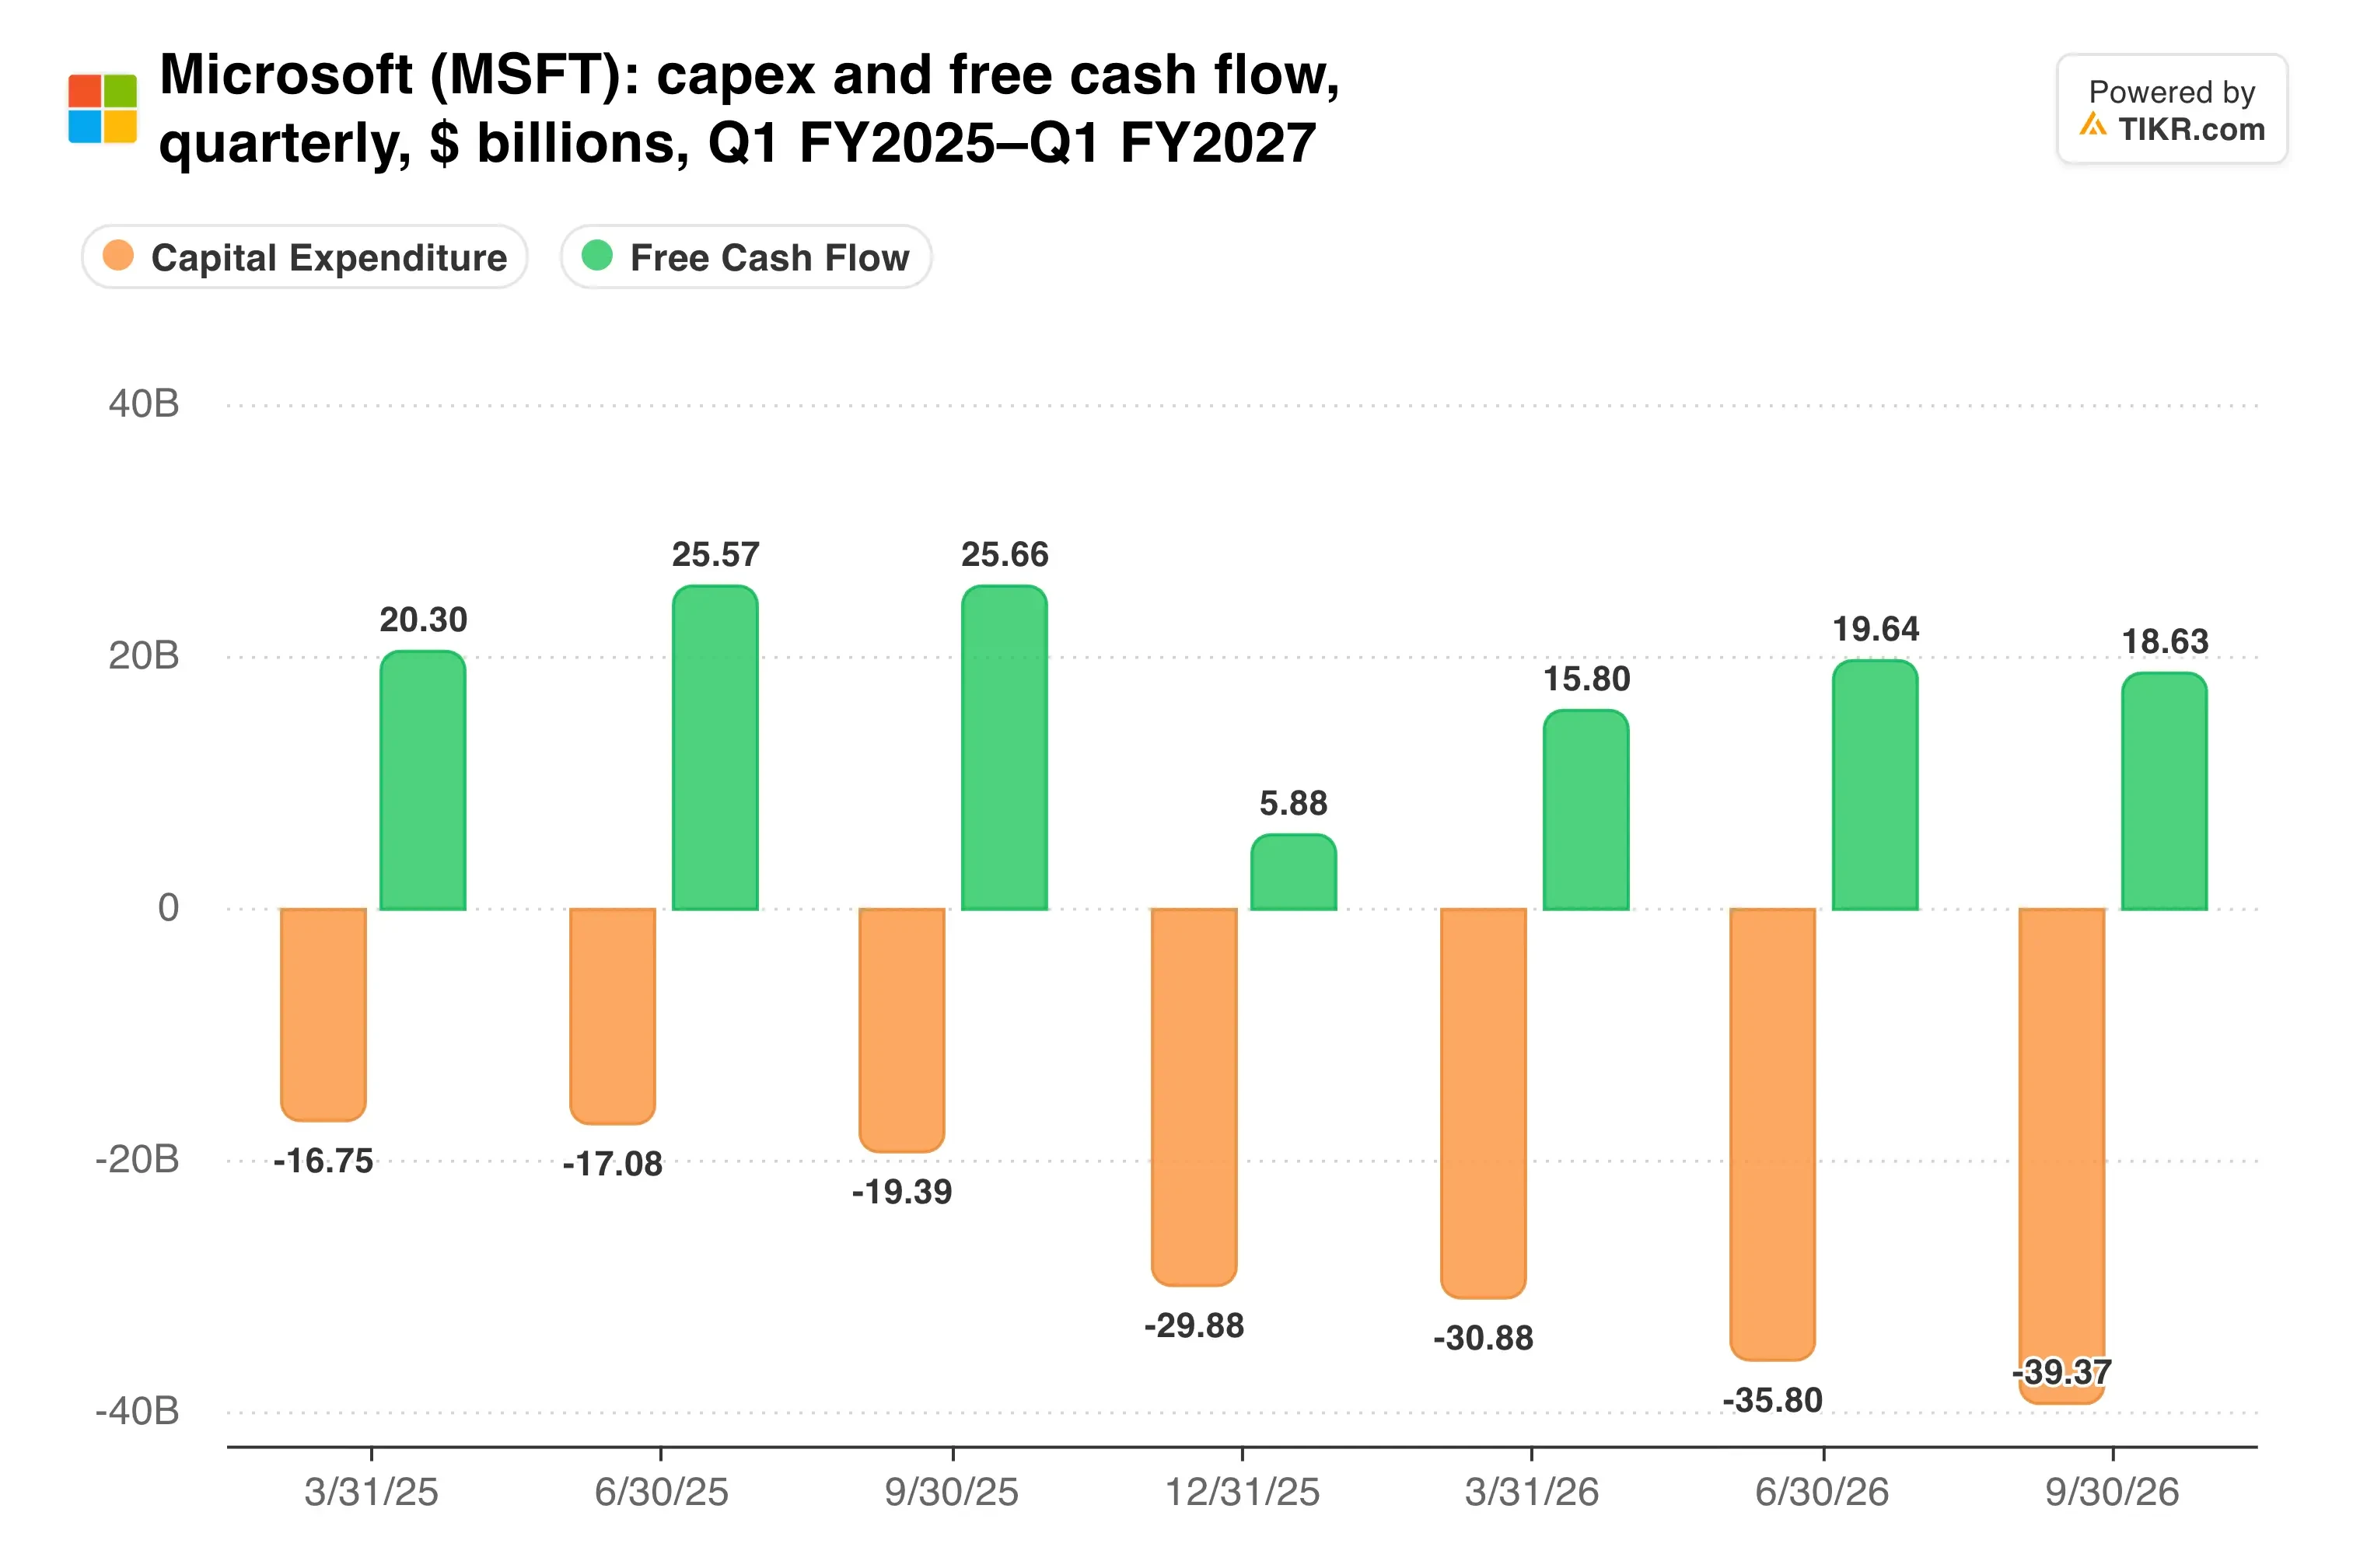
Operating cash flow climbed to $58.0 billion, which kept the gap manageable.
Microsoft is also getting choosier about rented capacity. Bloomberg reported Friday that it is winding down a deal to rent AI computing from Oracle as it reassesses billions of dollars in outside cloud partnerships.
For the December quarter, management guided revenue of $96.0 billion to $97.1 billion. Azure growth should land at 49% to 50%, ahead of the 47.6% analysts expected.
My take: Tuesday’s drop prices in a threat that Anthropic’s own team calls early. The real risk for Office is slower pricing power over several years, and one beta launch can’t show that yet. I’d watch Microsoft 365 cloud growth more closely than the headlines, because a high-teens pace would make this sell-off look like noise.
The next checkpoint is Microsoft’s fiscal second-quarter report, expected in late January. It will show whether Azure hits that 49% to 50% guide and whether Microsoft 365 cloud growth holds near 17%.
So what is Microsoft stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Microsoft could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any stocks mentioned. Thank you for reading, and happy investing!








