Key Takeaways
- Twenty-two big funds, including Tiger Global, Whale Rock, and Dragoneer, bought or added to Advanced Micro Devices (AMD) in Q2, and the stock is down 23% since June 30.
- Several of the same funds held fewer NVIDIA (NVDA) shares at June 30, and Dragoneer had sold its whole NVIDIA stake.
- Analysts expect AMD’s normalized EPS to more than double to $17.64 in 2027, while its forward P/E has fallen to 30x from 67x at June 30.
- AMD looks like a bargain at this price, and the warrants it has granted to customers are the main risk.
Twenty-two big funds bought Advanced Micro Devices in Q2, according to their 13Fs for the quarter ended June 30. The stock is down 23% since then, and it’s 31% below its 52-week high.
Those filings, made from late July to mid-August, are still the funds’ latest. Their Q3 13Fs are due by Nov. 16.
Some of the biggest bets were brand new
17 of the 22 positions were new in the quarter. Here are four of the biggest:
- Dragoneer Investment Group, which manages $37 billion: a new stake of 943,987 shares worth $548 million, 19.3% of its 13F holdings and its No. 2 holding.
- Whale Rock Capital, a hedge fund managing $13 billion: 1.51 million shares worth $877 million, 7.0% of its 13F holdings, after it raised its share count by 2,081%.
- Lee Ainslie’s Maverick Capital, a hedge fund managing $16 billion, added 976,326 shares worth $567 million, 5.1% of its 13F holdings, up 44%.
- Chase Coleman’s Tiger Global, a hedge fund managing $78 billion, added a new stake of 674,727 shares worth $392 million, 1.6% of its 13F holdings.
Several of them held less NVIDIA by the end of the quarter. Whale Rock cut its NVIDIA shares 64%, and Sands Capital, which opened a new AMD stake, cut 22%. Dragoneer held 3.73 million NVIDIA shares at March 31 and none at June 30.
TIKR tracks 53 analysts on AMD. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on AMD, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See AMD’s Analyst Ratings
Most of the drop came after an October high
Most of AMD’s business news since June 30 has been good. Q3 revenue rose 45% to $13.4 billion, management guided Q4 data center revenue by 50%, and production shipments of its Helios rack systems for AI data centers began in September.
The worry is what AMD is giving up to win those customers. It has granted OpenAI and Meta warrants for up to 320 million shares at a penny each, equal to 19.6% of its shares outstanding.
It also guarantees up to $4.1 billion of a partner’s data center lease and has pledged up to $5 billion to Anthropic. On Oct. 27, it committed $1 billion to Meta’s stock offering.
That puts the spotlight on how customers pay for all this. Meta signaled on Oct. 22 that it could issue billions of dollars of stock, Reuters reported, and AI stocks sold off that day. Meta has committed to up to 6 gigawatts of Helios.
Then in late October, Intel’s CFO said he expects the PC slowdown to last at least through the first half of next year, and AMD dropped 11% in a day.
AMD’s client segment, its PC chips, brought in $3.1 billion in Q2, about 27% of sales. This further dropped to $2.9 billion in Q3, about 22% of sales.
Analysts’ numbers kept rising
The fund’s case rests on earnings. Analysts expect AMD’s normalized EPS to go from $4.17 in 2025 to $8.09 this year, $17.64 in 2027, and $25.52 in 2028:
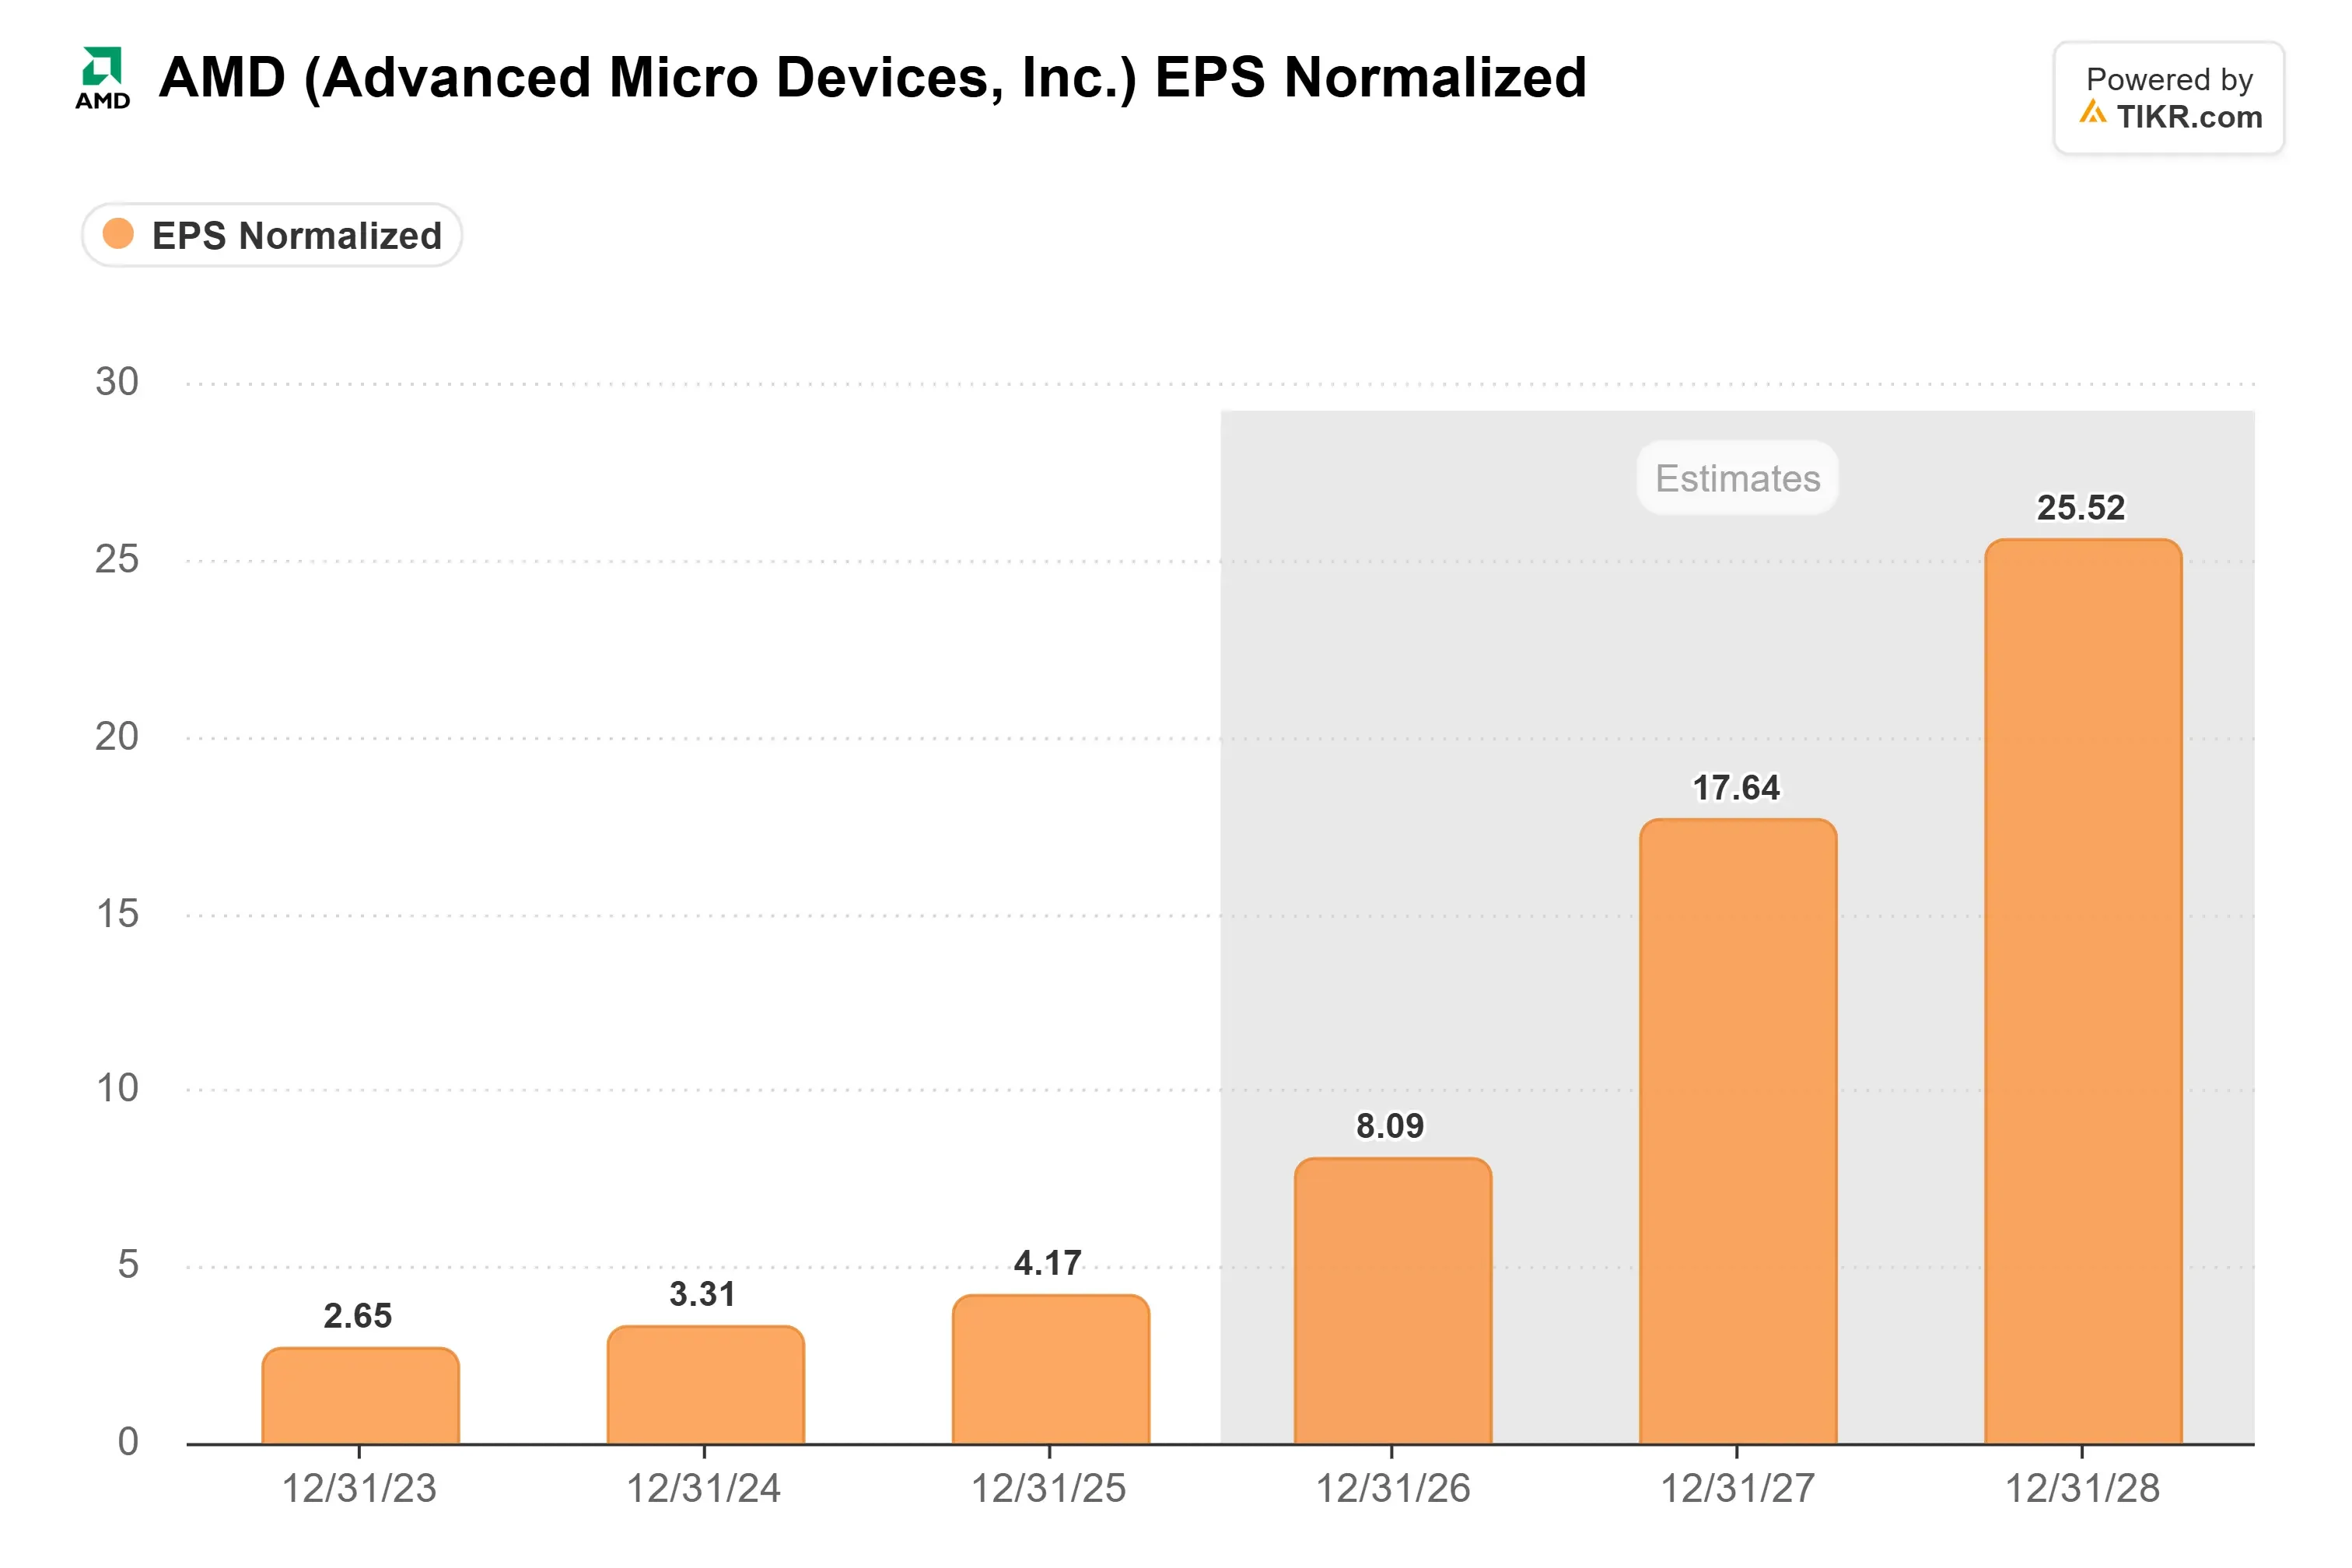
The 2027 estimate rose 20% in the 90 days to Oct. 23.
Management has guided server revenue up more than 70% in the second half of 2026, and its Data Center segment to more than double in 2027.
So investors are paying less for higher estimates. AMD trades at 30x forward earnings, down from 67x at June 30, its five-year high, but still above its five-year average of 35x.
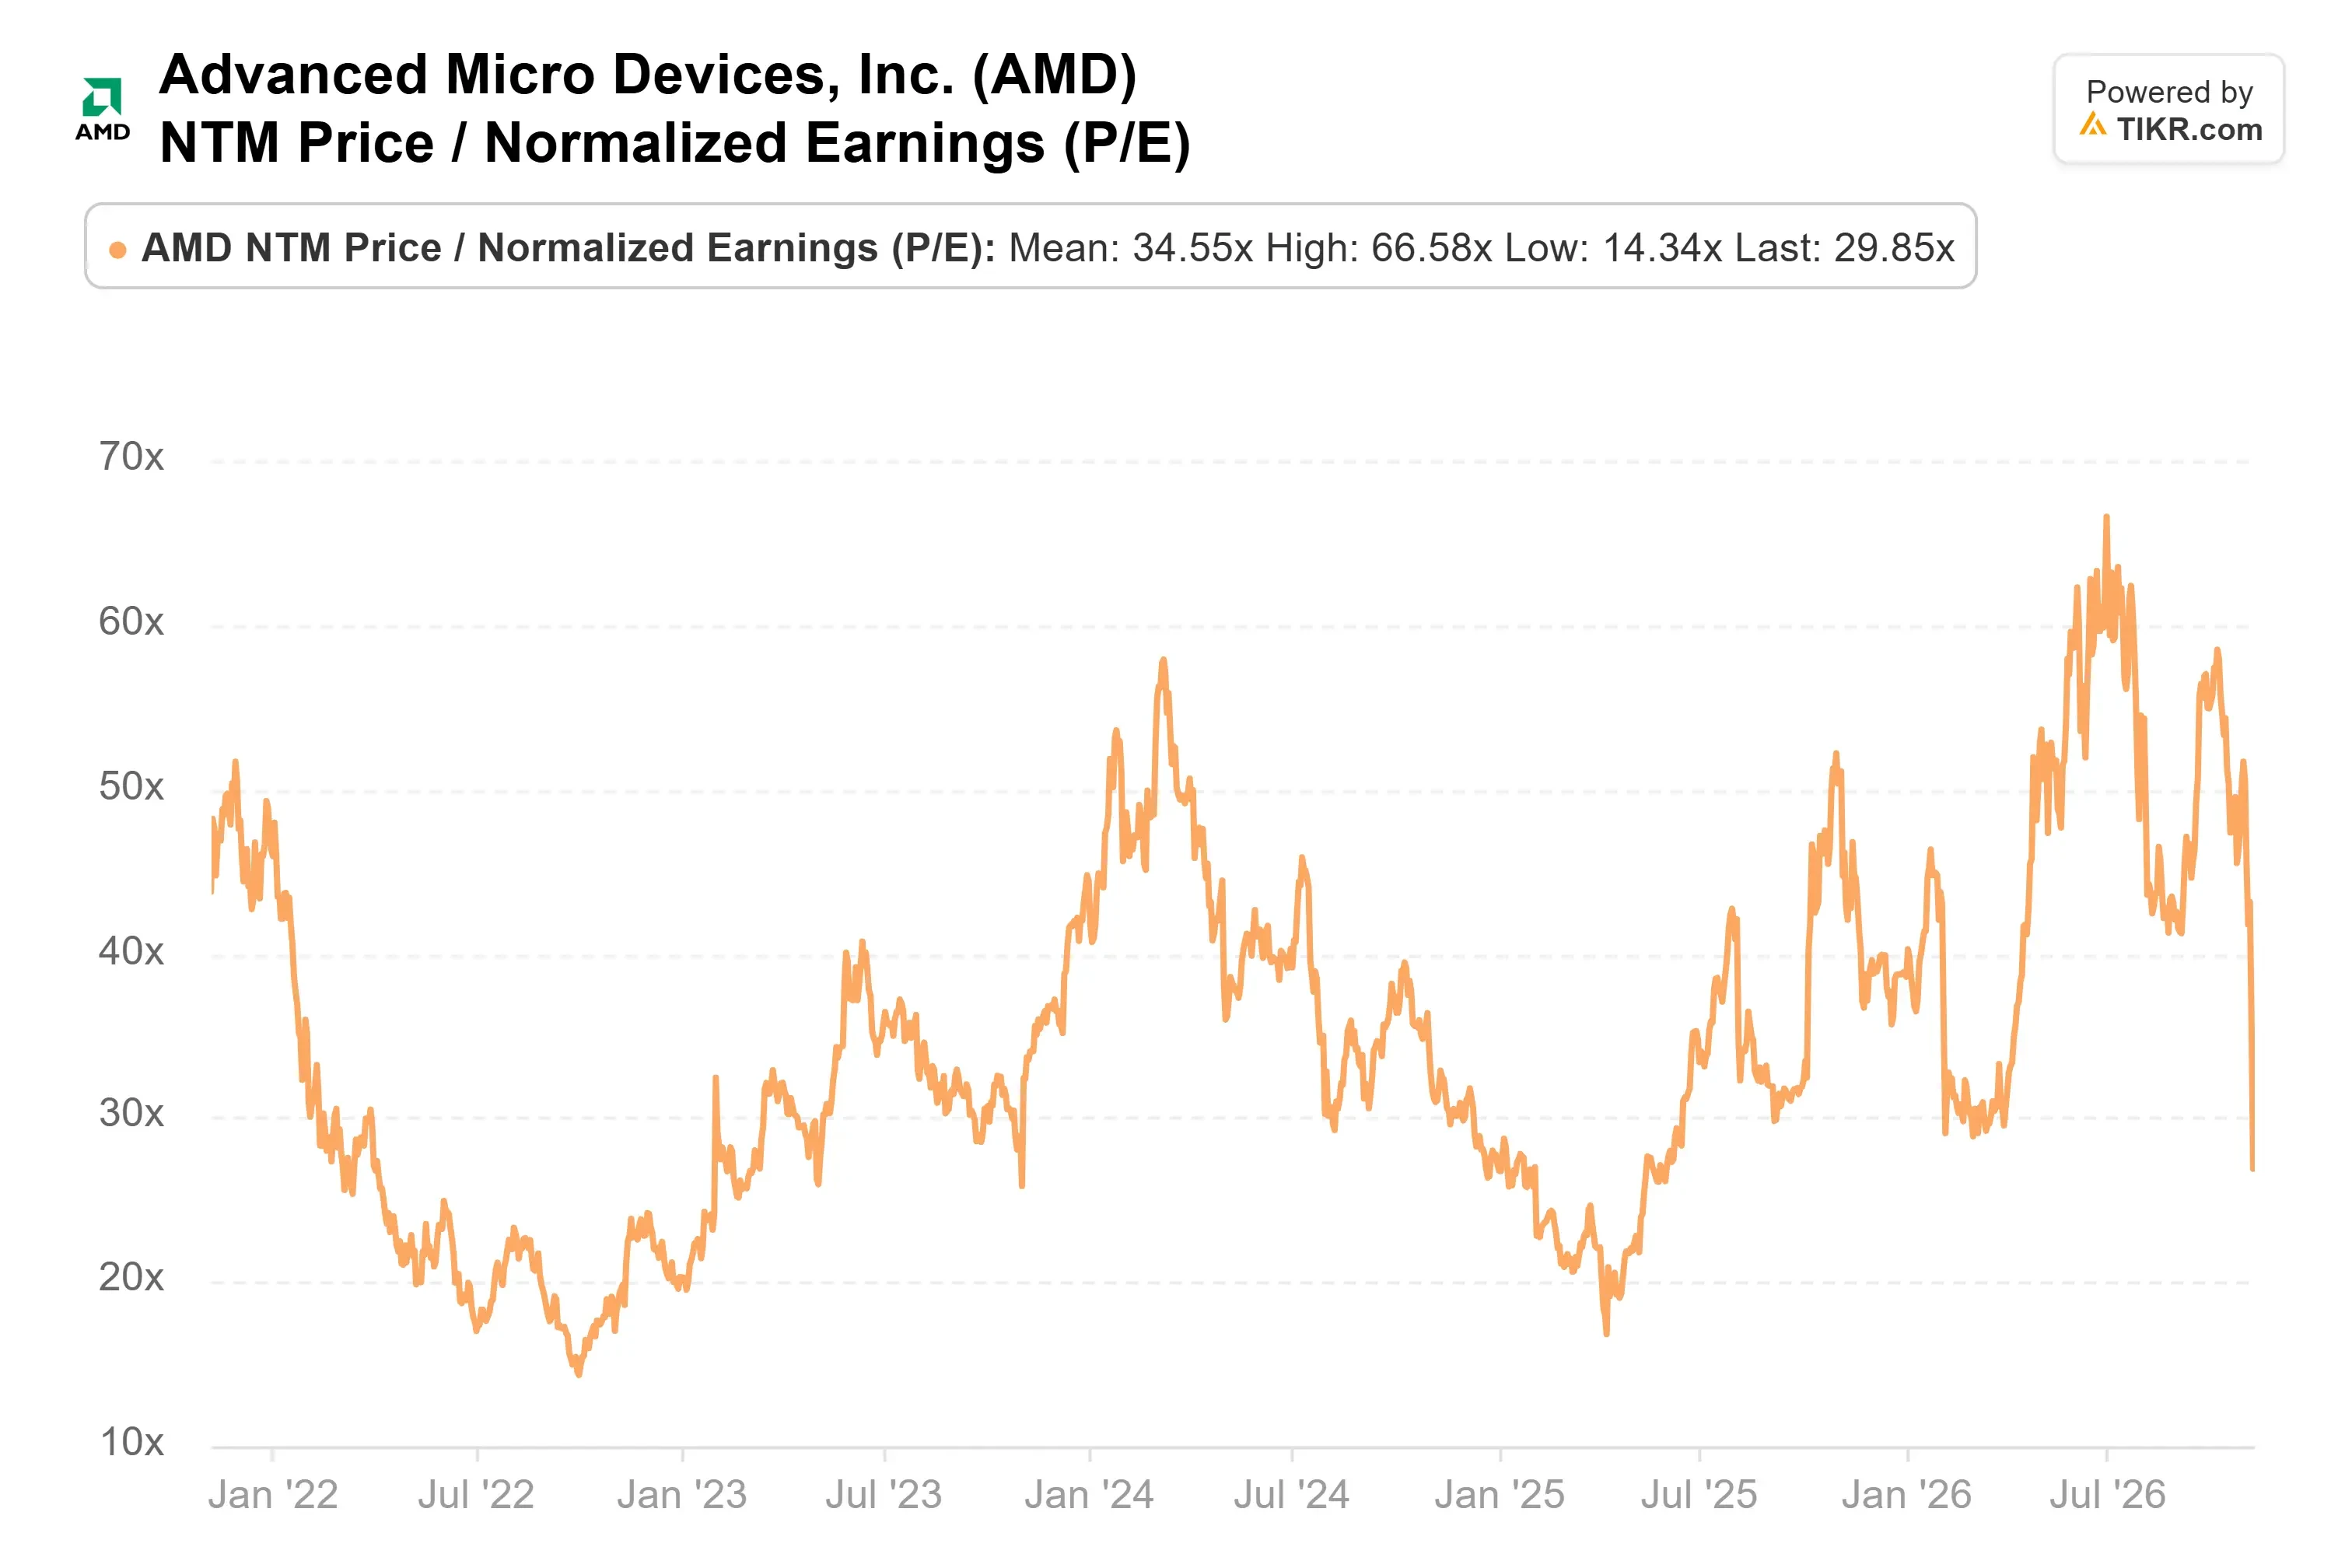
At that average, today’s price needs the kind of forward earnings that analysts don’t expect AMD to reach until sometime in 2027.
Wall Street’s price targets have risen along with the estimates. The 53 analysts covering AMD have an average target of $660, 47% above the Nov. 6 close and up from $272 a year ago.
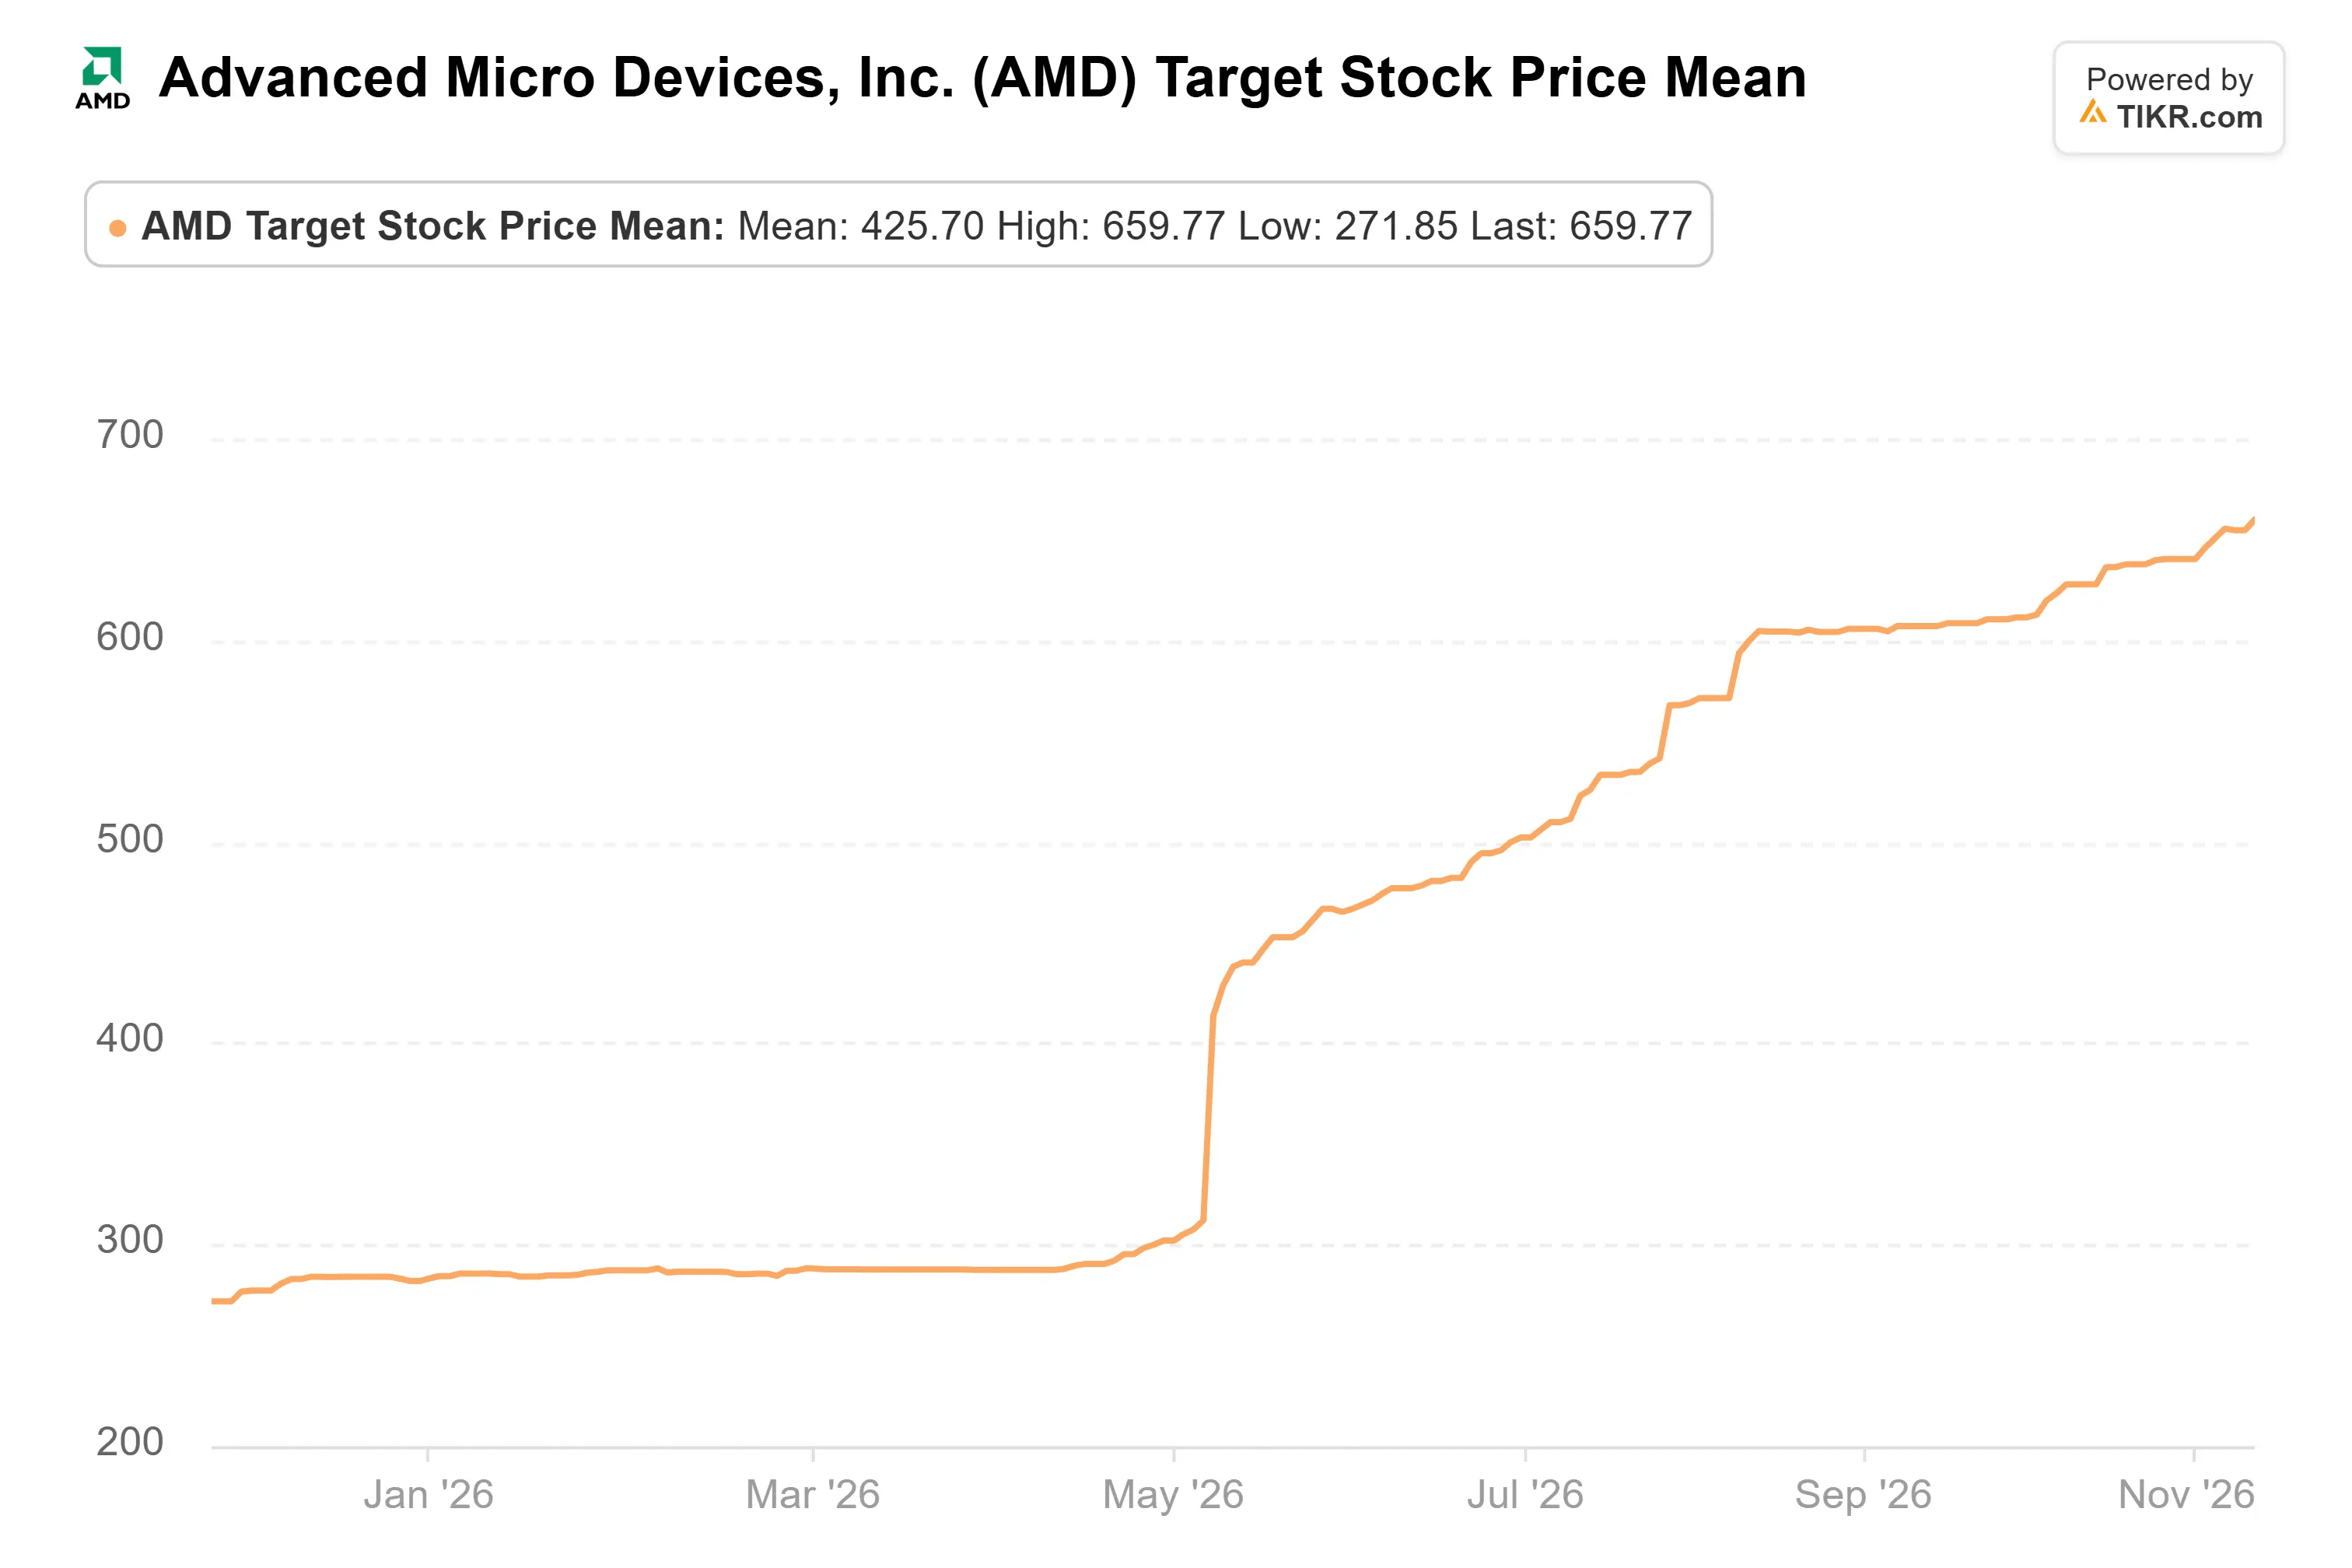
The range is wide, though. The lowest target, $490, is just above the Nov. 7 close, and the highest is $1,250.
I’d side with the funds
The risk is those warrants. Each one’s final tranche vests only after a full 6-gigawatt deployment and a $600 share price, so shareholders take the full dilution only if AMD delivers.
Frankly, I like AMD more now than at June 30. Analysts expect more from it, and investors are paying less for those earnings.
If the warrants vest in full, it’ll be because AMD shipped the gigawatts and the stock hit $600.
Of course, AMD reported Q3 results just a couple of days ago. Its Q4 guidance came in at $17 billion, ahead of $16.2 billion in revenue in the 2026 consensus at the time of reporting. It implies that Helios is shipping better or higher volumes than analysts expect.
The funds’ Q3 13Fs will also show who still held AMD at Sept. 30.
So what is AMD stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what AMD could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!