


Key Takeaways
- UBS assumed coverage of Amazon with a Buy rating and a $340 price target, 32% above the stock’s price and down from the firm’s previous $352.
- UBS lowered its AWS growth and margin estimates for 2027, but it still sees AWS making Amazon a defensive AI play.
- On analysts’ 2028 earnings estimates, $340 is about 24x, a little under Amazon’s 25x forward P/E today and about half its 48x average over the last five years.
- UBS’s target only needs earnings estimates to hold, so it looks conservative, and Amazon’s 2027 spending plan in early February is the next test.
Amazon (AMZN) is up 11% over the past year, and UBS thinks it has a lot further to go.
On Nov. 17, UBS analyst Karl Keirstead assumed coverage of Amazon with a Buy rating and a $340 price target, 32% above the stock’s $257.89 close that day. That’s down from the firm’s previous target of $352.
AWS is doing the heavy lifting
Amazon’s third-quarter report on Oct. 29 missed Wall Street’s revenue and earnings estimates, but it showed AWS sales up 39% to $46.0 billion, the cloud unit’s fastest growth in nearly five years. AWS earned $17.8 billion of Amazon’s $28.1 billion of operating income, and its backlog reached $578 billion. CEO Andy Jassy said in the release that AWS has “projected revenue growth rates of over 40% both in 2027 and in 2028.”
UBS trimmed its AWS numbers and still likes them
UBS’s case is that AWS works with any AI model and any chip. In its view, that makes Amazon a defensive AI play and a supplier to companies scaling up their AI spending in 2027 and beyond. The firm notes that AWS made up 23% of Amazon’s third-quarter revenue but 60% of its year-over-year revenue growth.
Along with the lower target, Keirstead cut UBS’s AWS growth estimates to 41% from 42% for the fourth quarter and to 43% from 48% for 2027. He also cut the 2027 AWS operating margin estimate to 40% from 45%. That brings UBS much closer to Amazon’s own outlook. A 43% growth rate is still above Jassy’s “over 40%,” and a 40% margin is just above AWS’s 38.7% in the third quarter.
TIKR tracks 62 analysts on Amazon. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Amazon, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Amazon’s Analyst Ratings
$340 needs no higher multiple
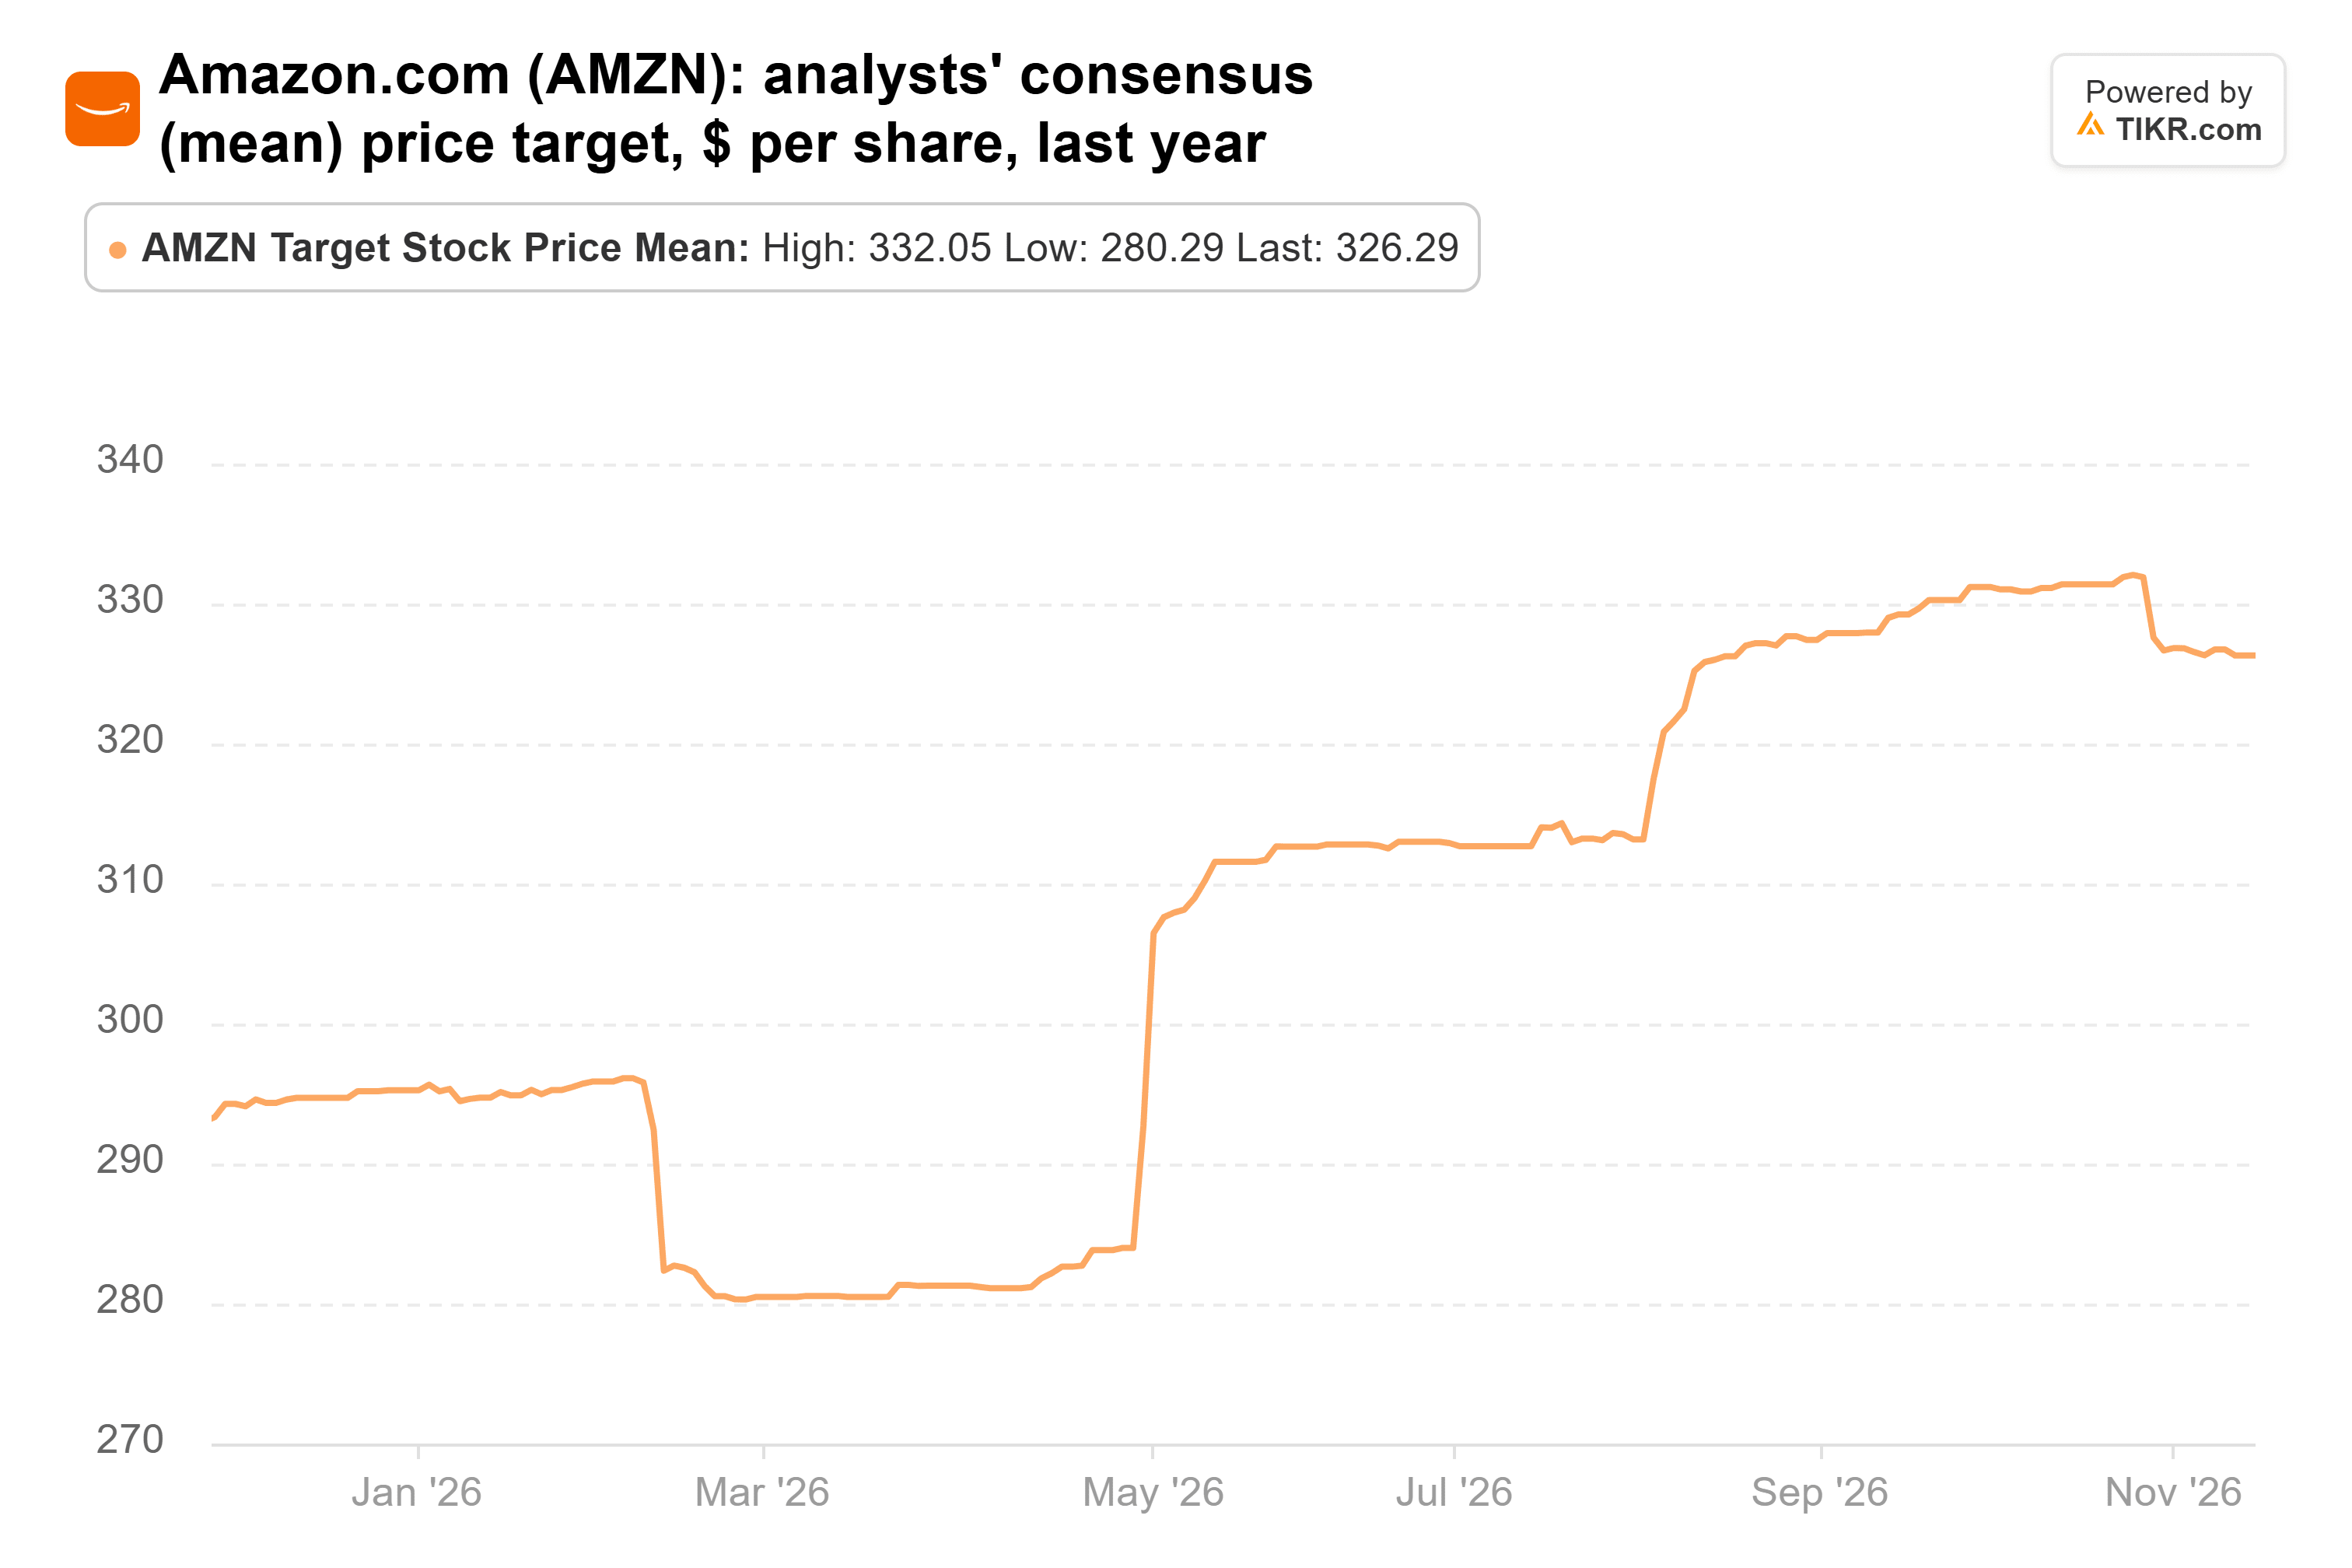
The 62 analysts covering Amazon have a consensus target of $326, 27% above the price. That’s up from $293 a year ago, even after a wave of target cuts that followed the third-quarter report:
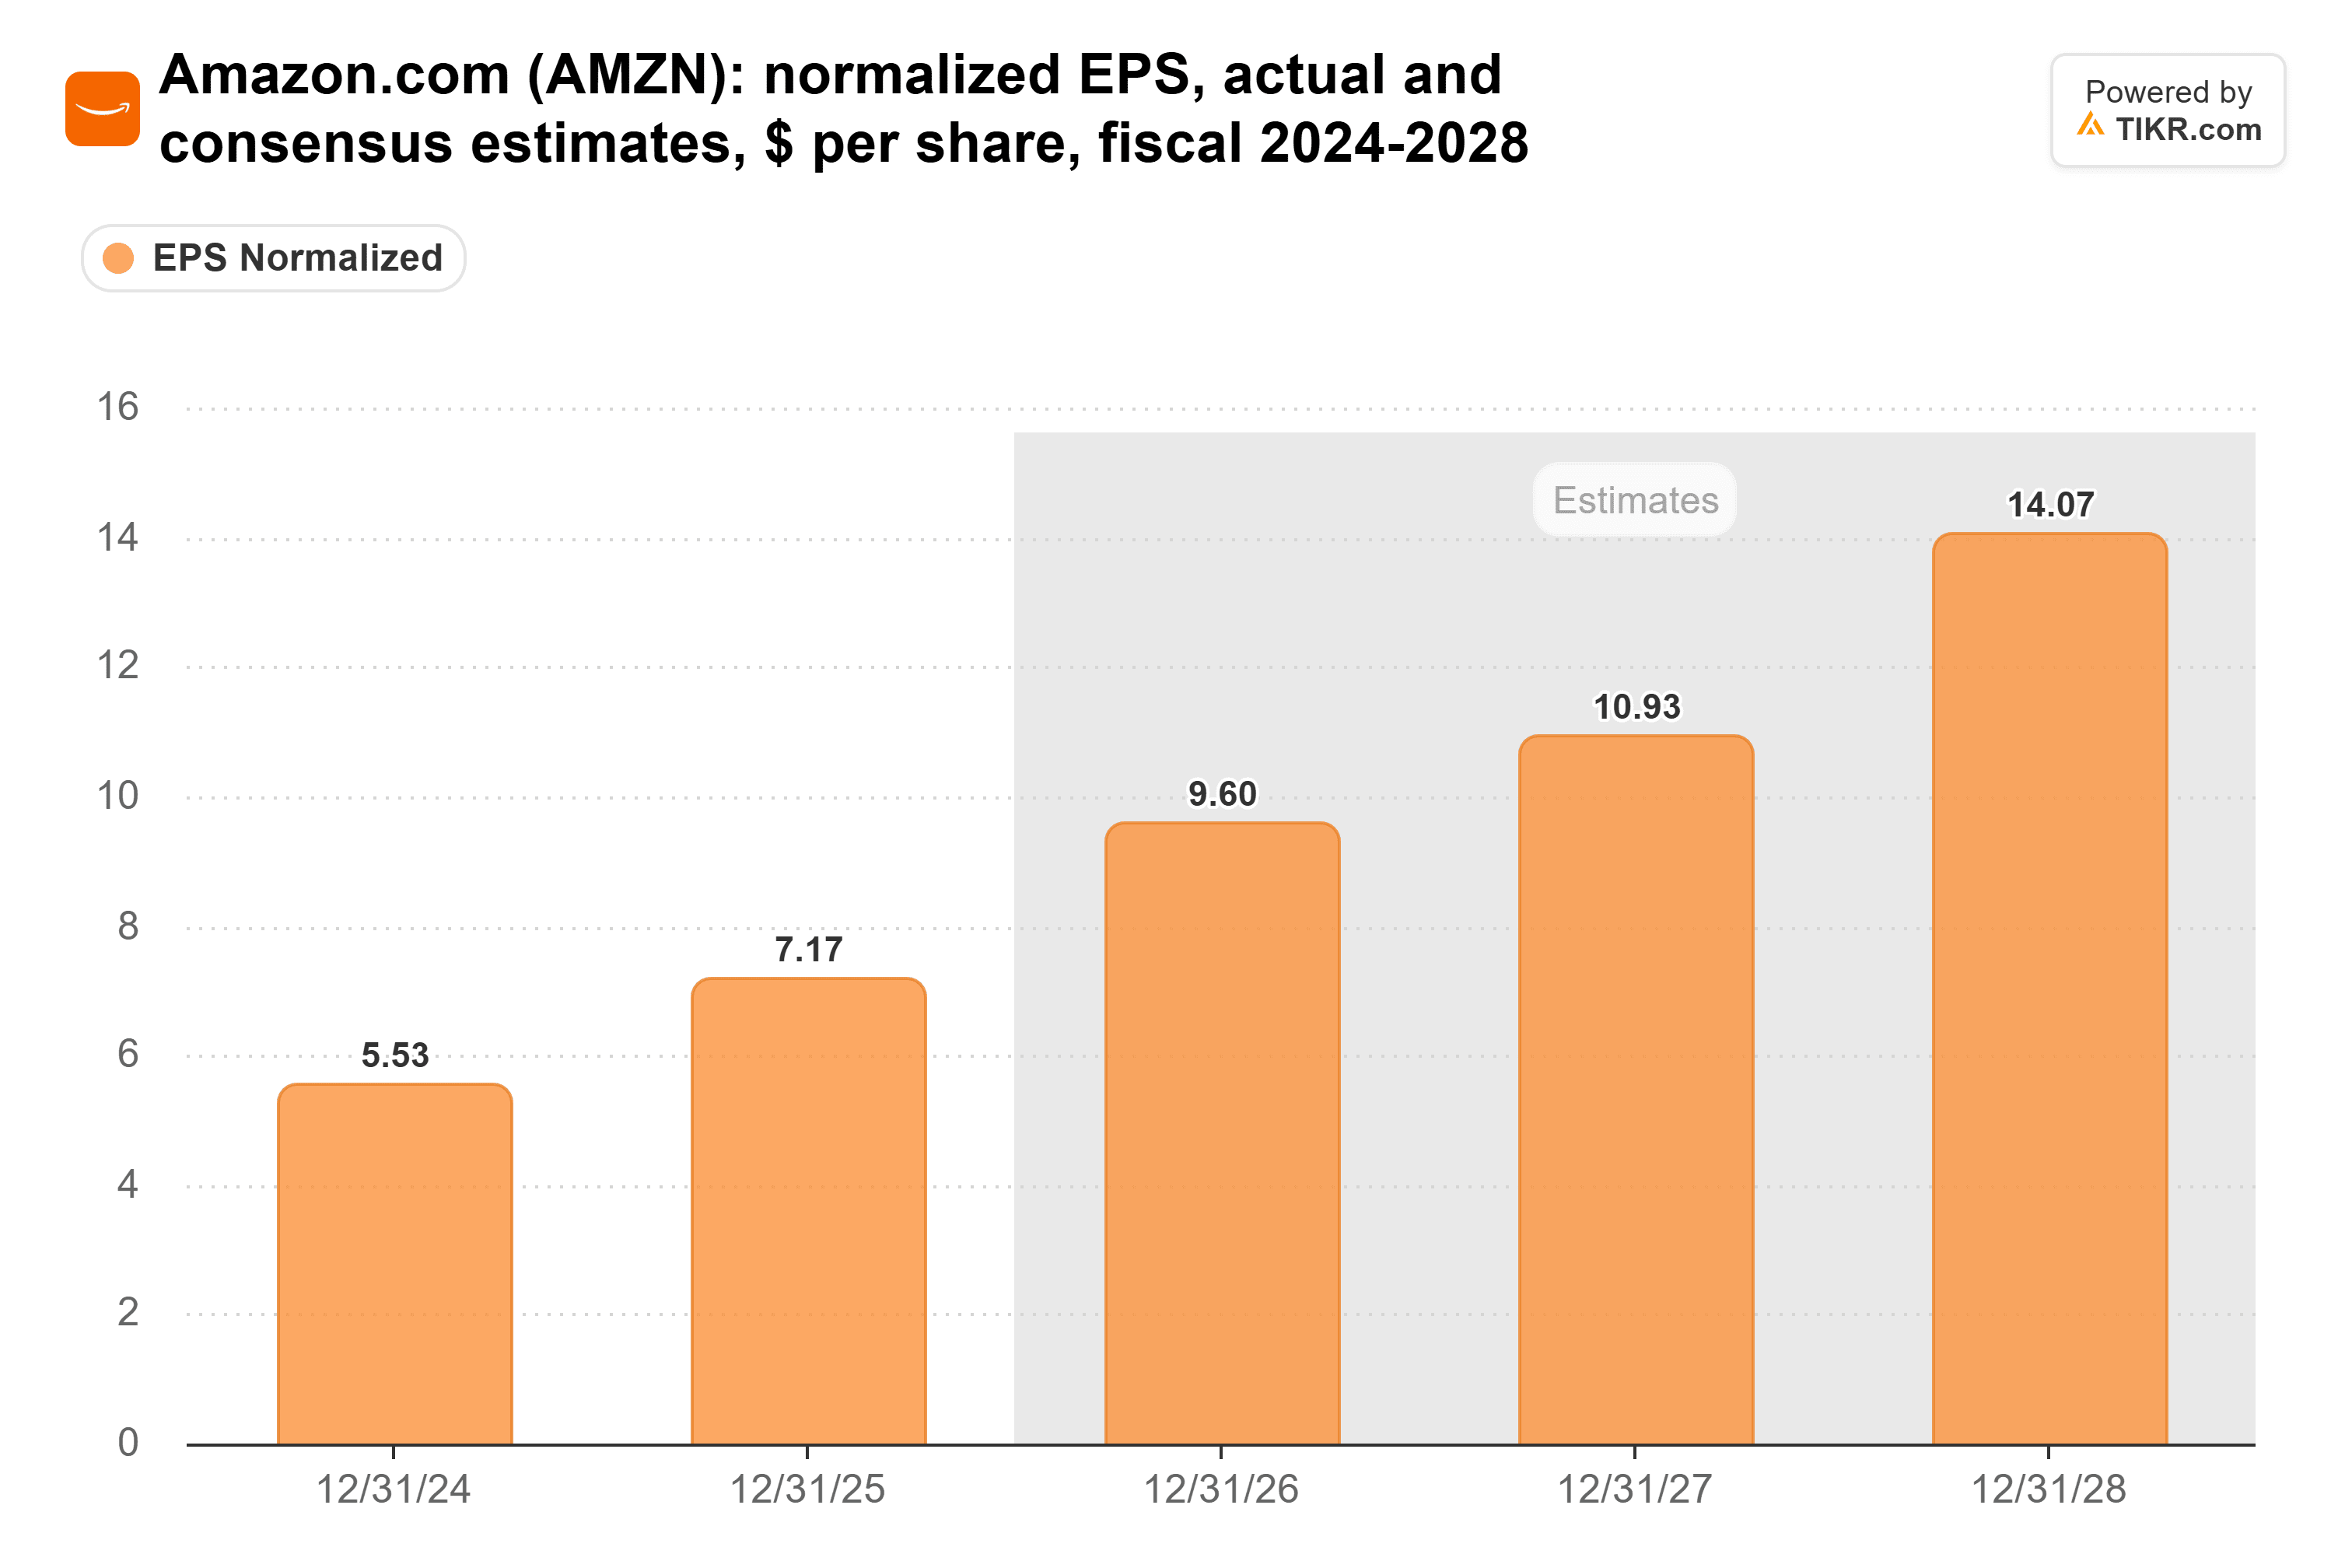
Analysts expect normalized EPS to nearly double, from $7.17 in 2025 to $14.07 in 2028, and the 2028 figure is up from $13.27 on Oct. 23, the week before the report:
Even so, Amazon trades at 25x forward earnings. That’s about half its 48x average over the last five years, and close to the 23x low it hit on Oct. 30, the day after the report:
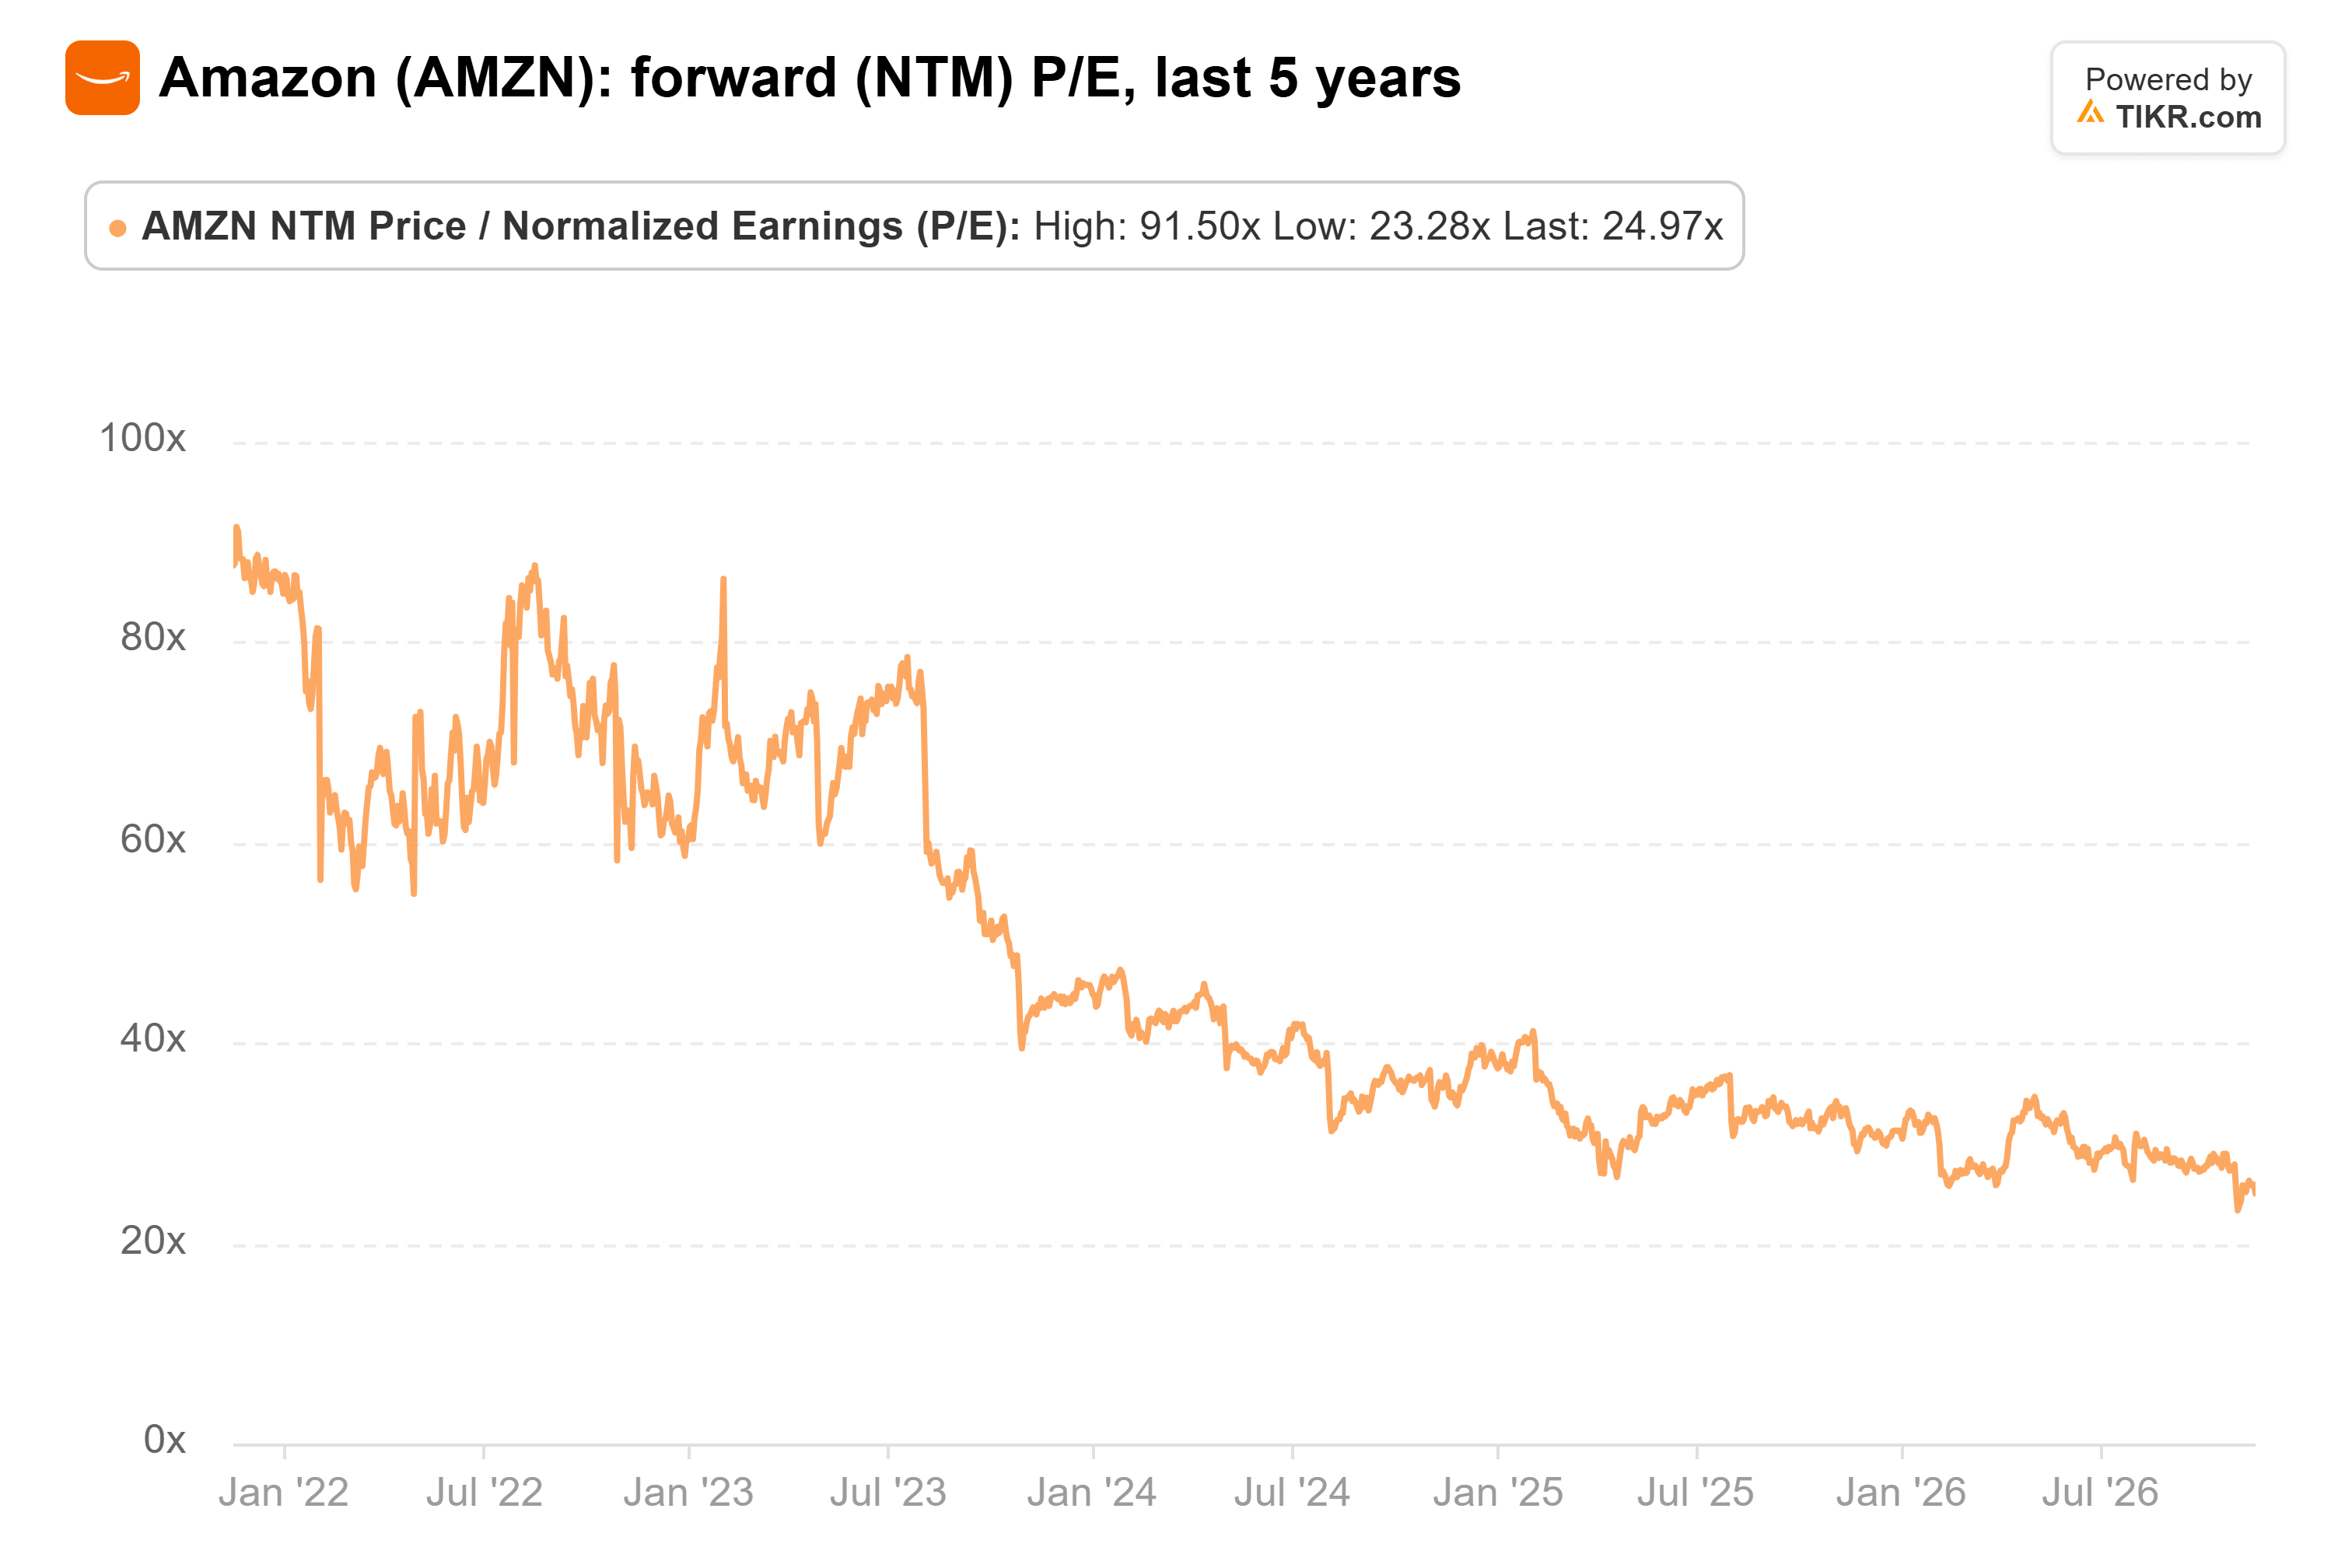
On 2028 EPS, $340 is about 24x, a little under today’s multiple. So all of the 32% upside would have to come from earnings growing about 36% from what analysts expect over the next twelve months.
The catch is the cash
That multiple sits low for a reason. Amazon’s free cash flow was a $42.4 billion outflow over the 12 months to Sept. 30. Jassy said on the call that after about $220 billion of capex this year, Amazon expects “to spend meaningfully more in 2027.”
Still, UBS’s $340 looks conservative. Keirstead cut his AWS numbers to roughly what Amazon already guides, and his target only needs the earnings estimates to hold.
The fourth-quarter report, expected in early February, is the next test. AWS growth at or above UBS’s 41% for the quarter, and a 2027 capex plan that grows more slowly than AWS’s sales, would keep $340 well within reach.
So what is Amazon stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Amazon could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!





