Key Takeaways
- Alibaba fell 25% in a month to a 52-week low as Washington moved to block Chinese companies from Nvidia chips rented abroad.
- Nvidia can’t sell its top chips in China anyway, so the curbs hurt Alibaba’s cloud far more.
- External cloud recurring revenue grew 67% last quarter, but CEO Eddie Wu said Alibaba’s 20 GW data-center target may be revised down.
- The stock looks cheap, but estimates have barely moved, so buying in small pieces makes sense.
Alibaba (BABA) stock is down 25% in the past month and hit a 52-week low on Nov. 20. The Nasdaq 100 fell 15% over the same stretch. The rest came from Washington, which is moving to cut Chinese companies off from the Nvidia (NVDA) chips they rent abroad.
Washington went after the chips Alibaba rents
On Nov. 9, the Financial Times reported that Alibaba is the largest client of Megaspeed, the Singapore company at the center of Nvidia’s scandal. On Nov. 11, The Information reported Commerce was close to finalizing a new rule. It would bar Chinese companies from advanced AI chips in data centers abroad, Singapore included. Alibaba fell 7% the next day. The rule took effect Nov. 19, giving data centers already serving Chinese companies 90 days to get licenses.
Nvidia is down 42% over the month, and Jensen Huang resigned as CEO on Nov. 12 amid the scandal. But its top chips are already barred from China, so it loses little from the curbs.
The cloud delivered, but the build may shrink
The Nov. 19 report showed real demand: external cloud customers’ recurring revenue rose 67%. But on the call, Wu said shifting compute policies “may lead to a downward revision of that long-term 20 GW target,” with “a certain impact” on capex. He guided cloud growth to 30% to 45% in the fiscal year starting April 2027.
After the report, Barclays cut its target to $155 from $200, citing the lower compute ambition. Mizuho raised its to $205 from $200.
TIKR tracks 41 analysts on Alibaba. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Alibaba, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Alibaba’s Analyst Ratings
Cheap, but the estimates haven’t caught up
Analysts still expect normalized EPS to rise about 62% in fiscal 2027 (the year to March 2027):
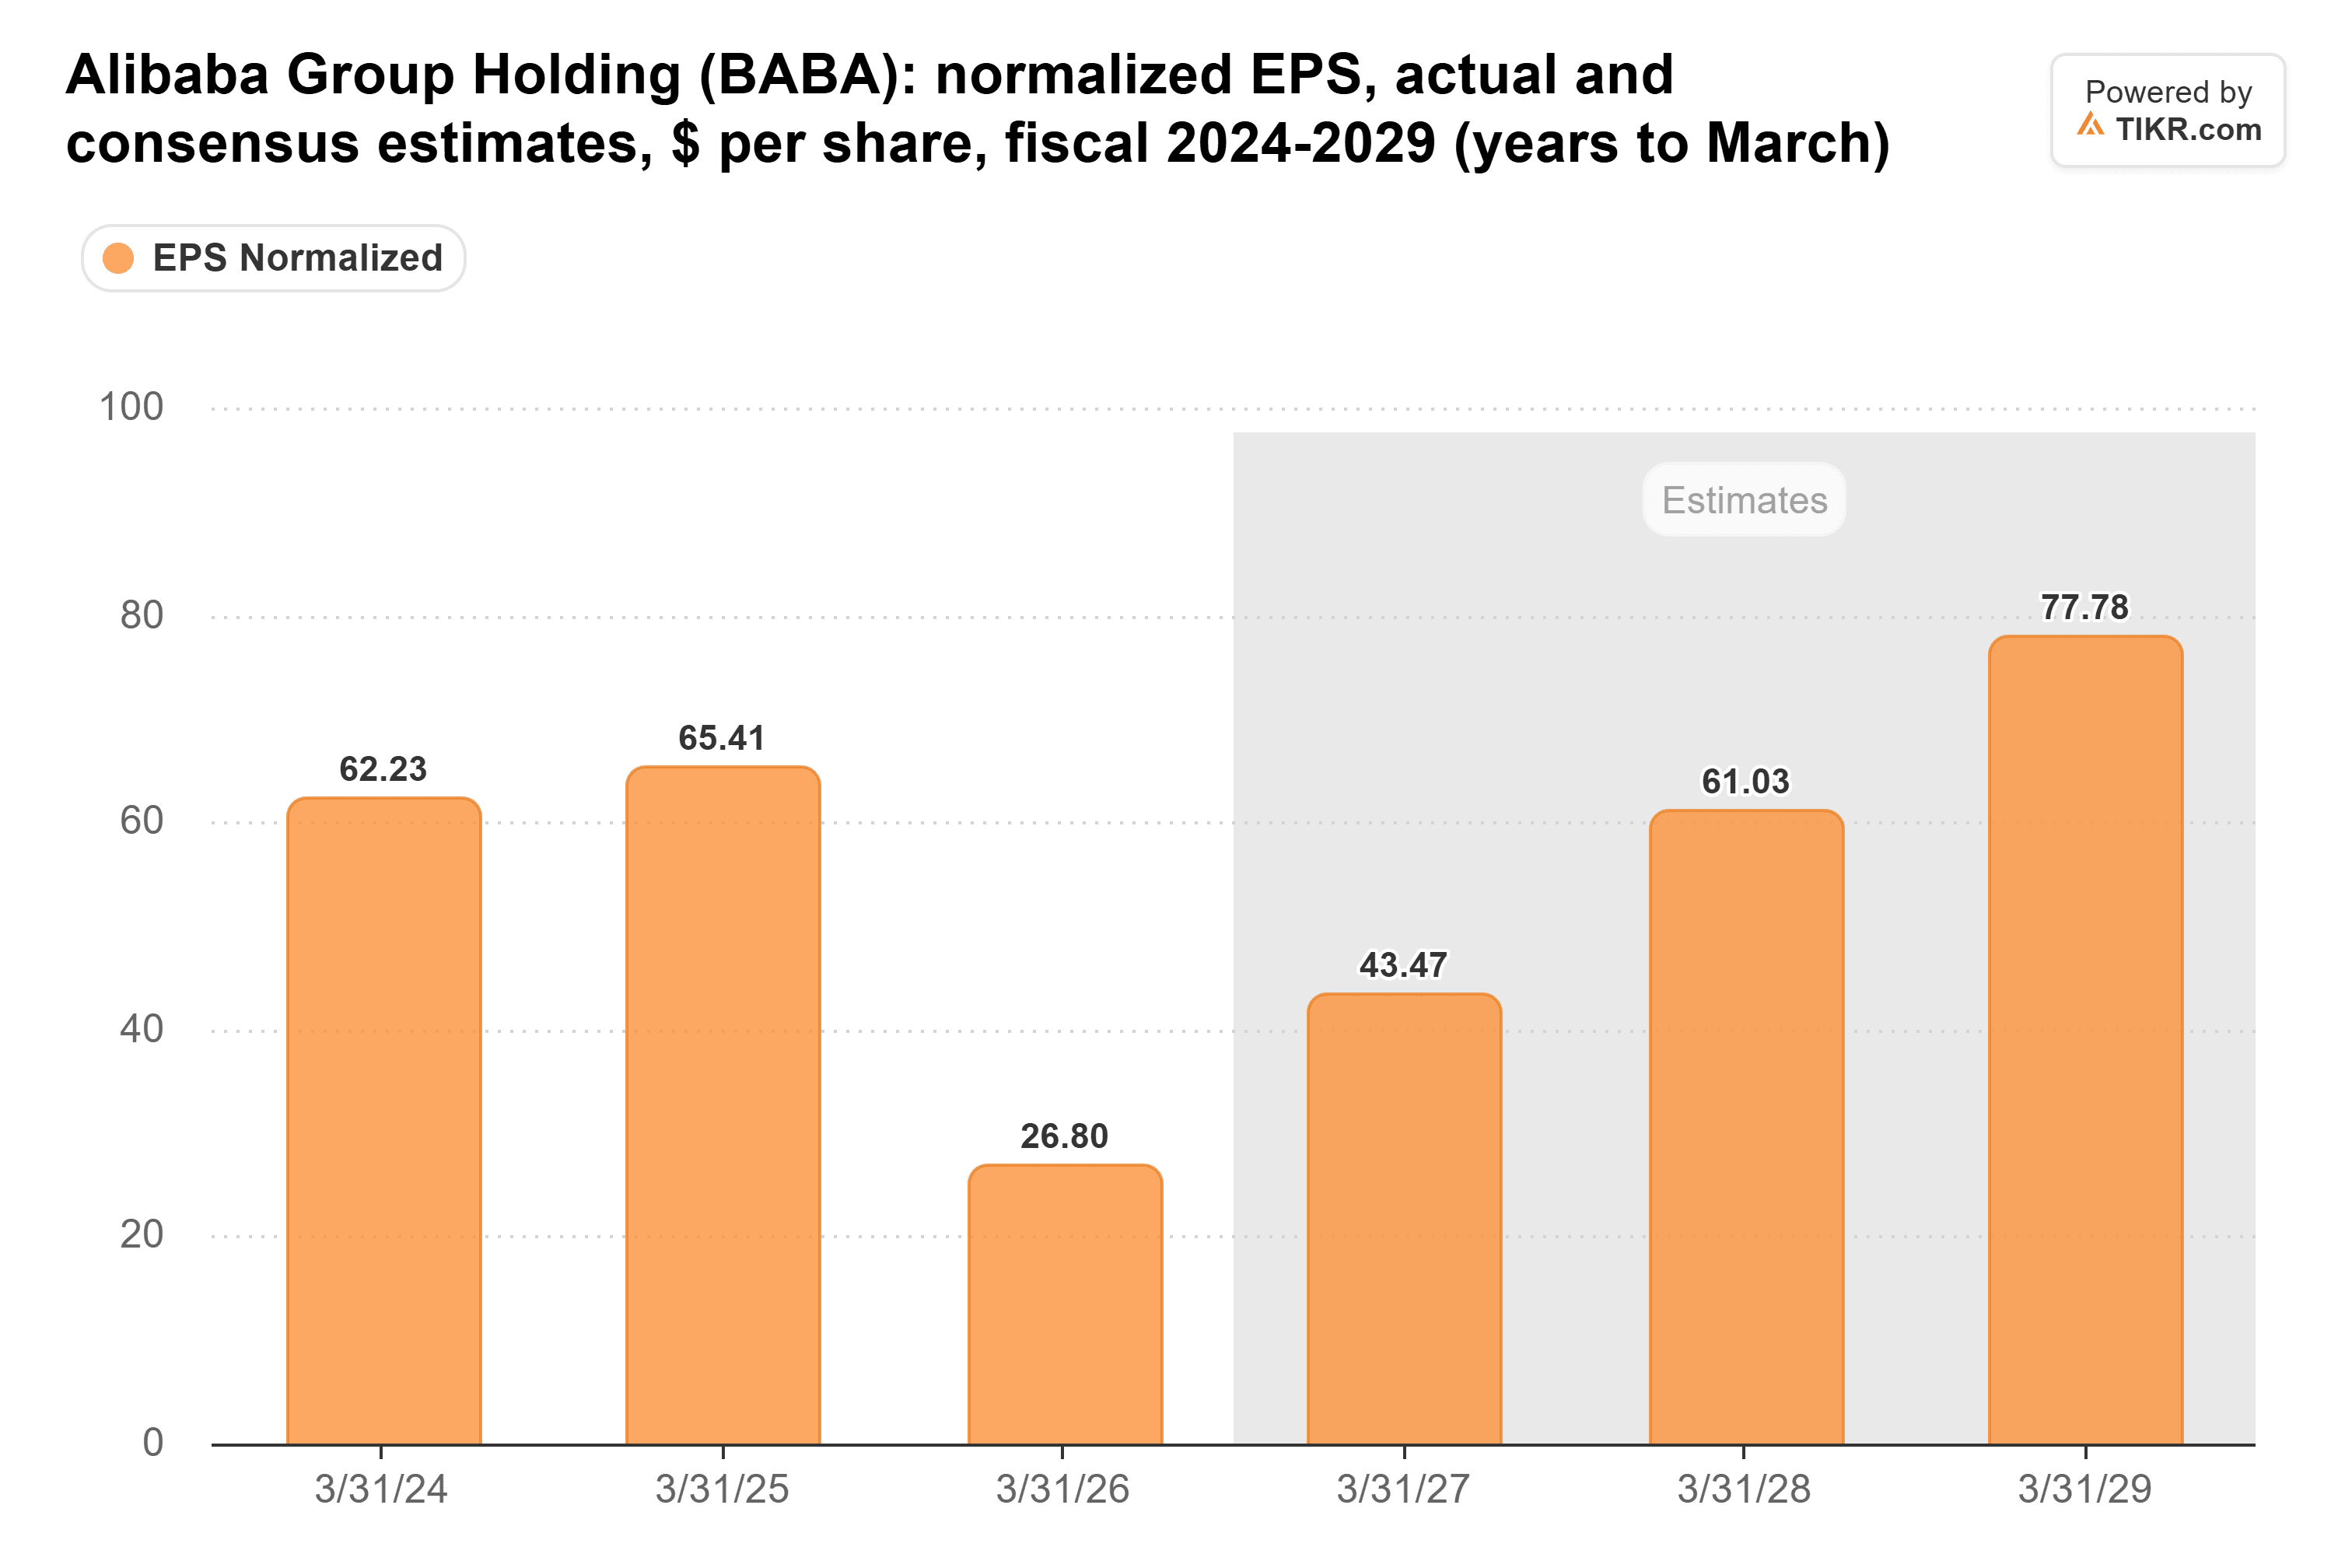
Those estimates are only about 2% lower than in October, and I’d expect cuts after Wu’s slower cloud range.
Still, the forward P/E was 10x on Nov. 19, against a five-year average of 13x:
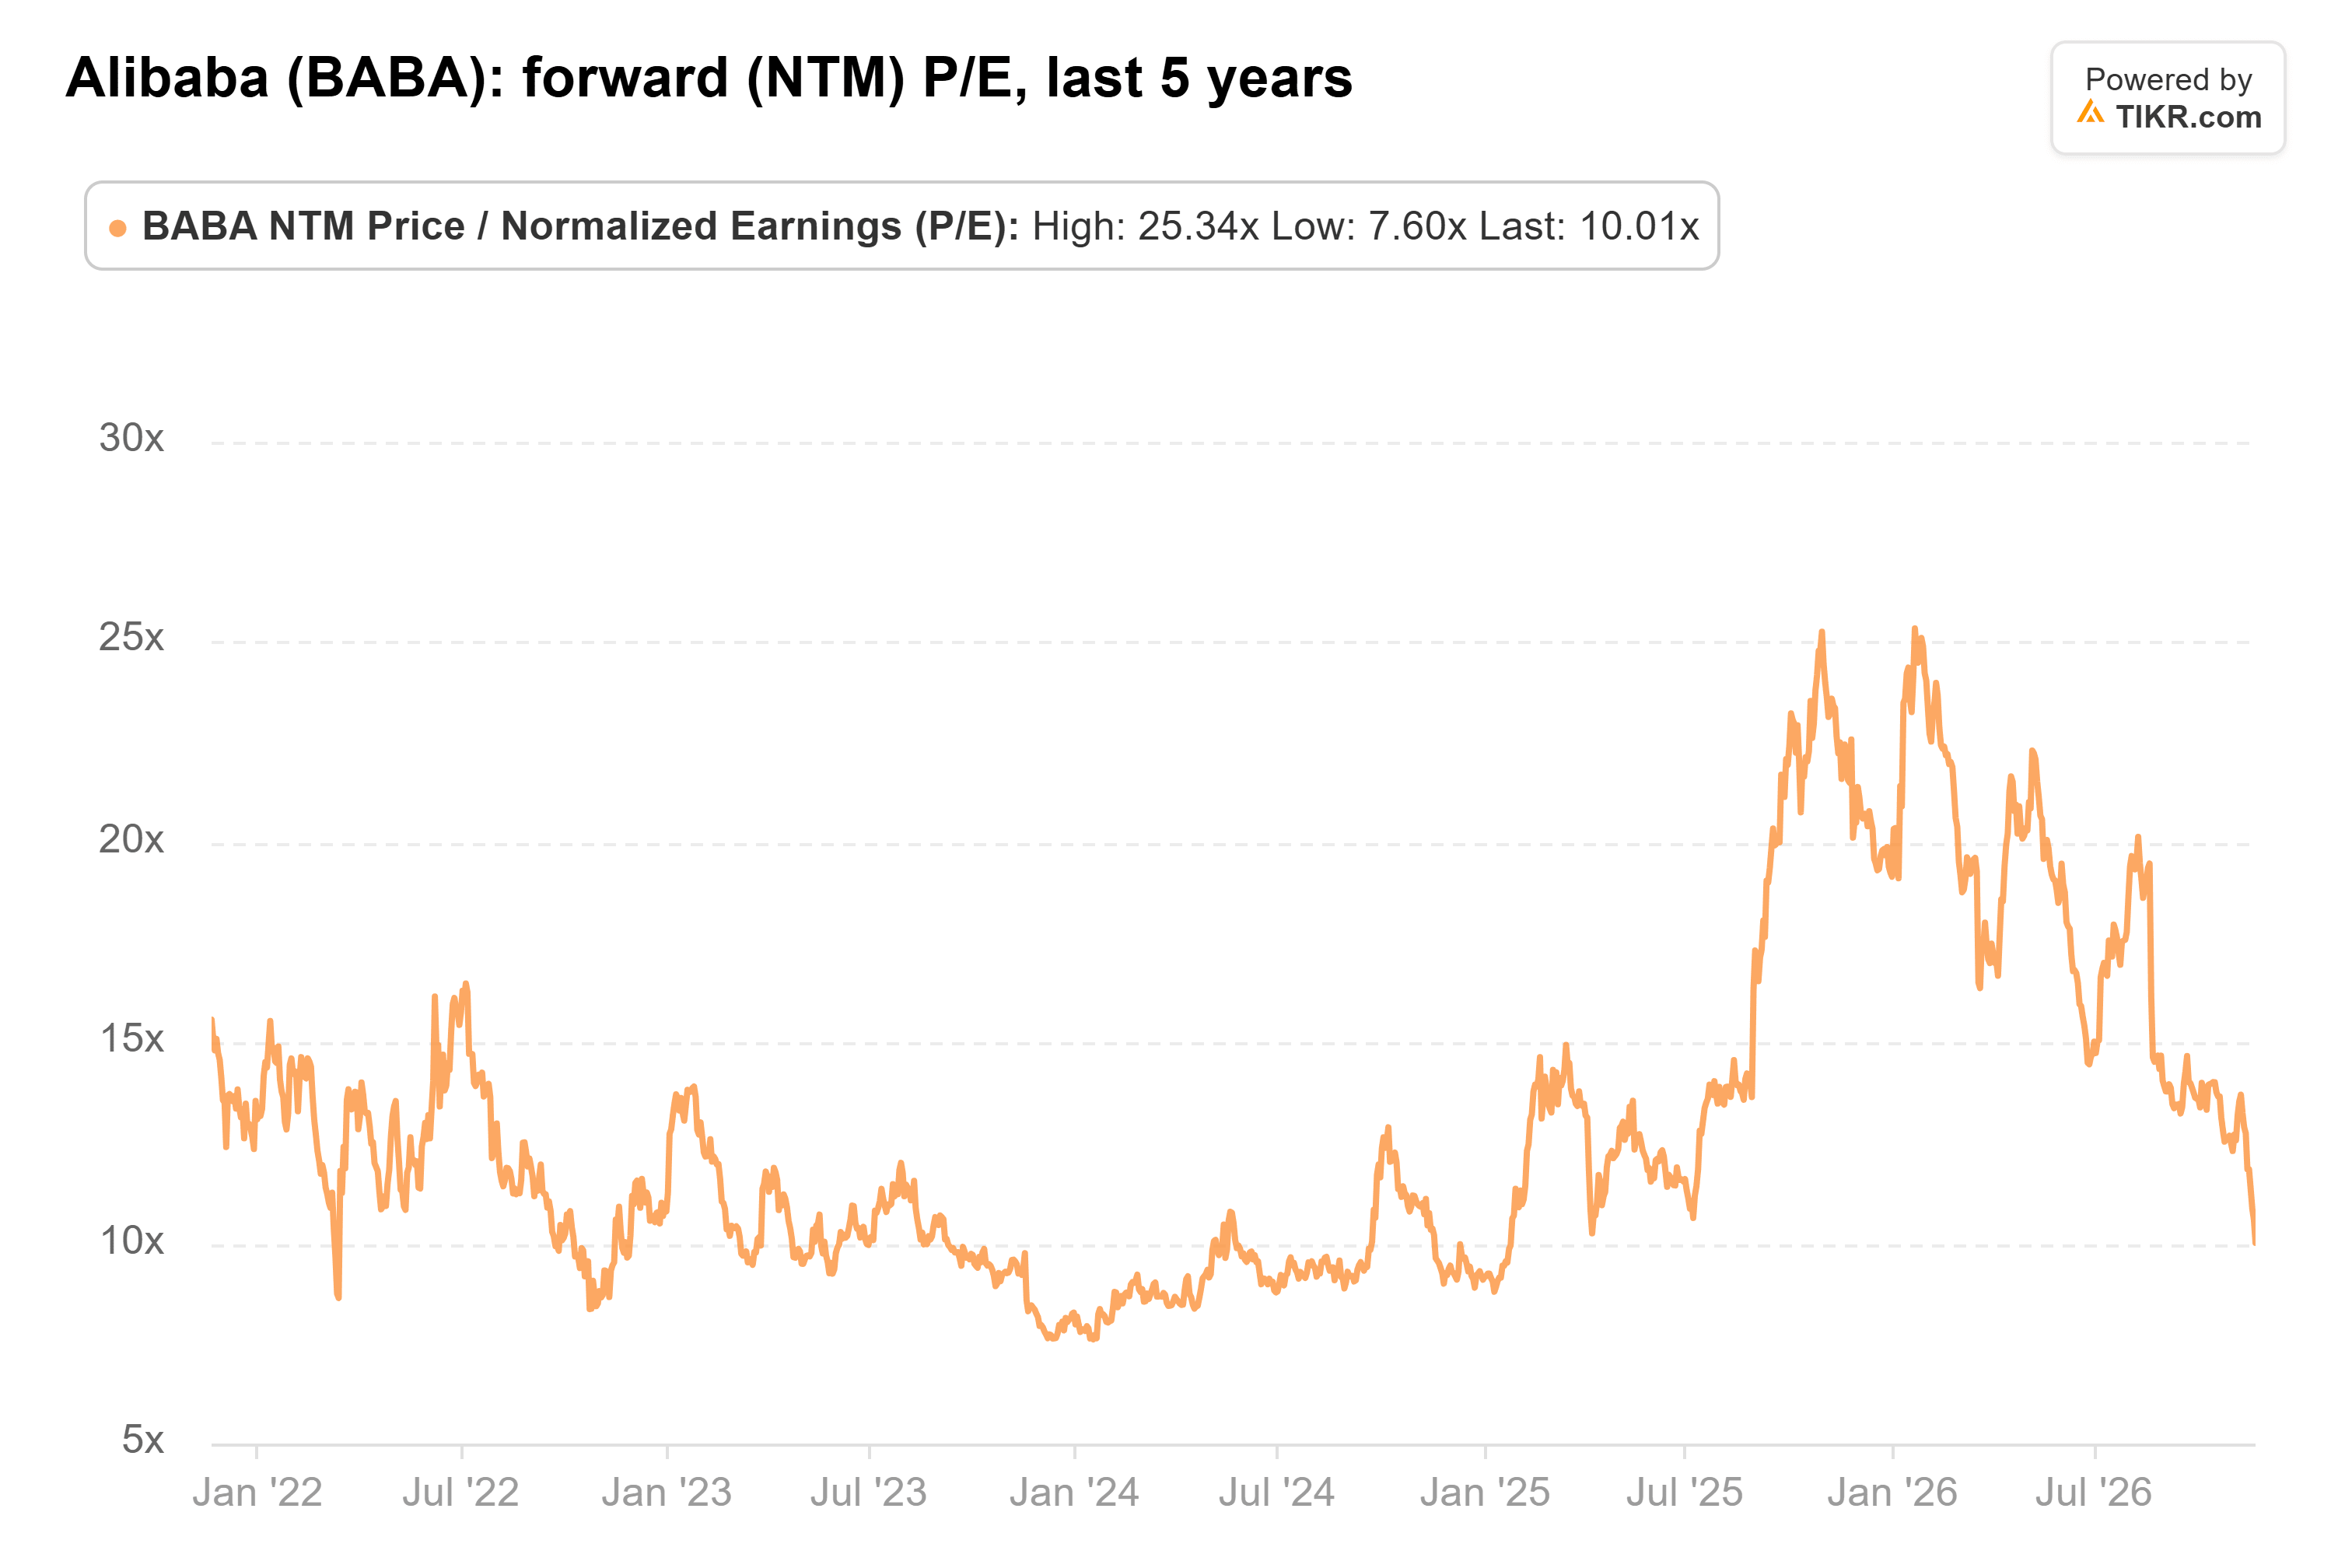
At the Nov. 20 close, it’s even lower.
With a lot of bad news priced in, I’d buy in small pieces and add once Alibaba puts a number on its smaller capacity target. If external cloud growth holds near 67% in the December-quarter report, due around February, the curbs will have cost less than feared.
So what is Alibaba stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alibaba could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!