


Key Takeaways
- Alibaba shares are down 41% from their closing high a year ago, and on Oct. 8 Jefferies kept its Buy rating with a $192 target, 79% above the Oct. 7 close.
- Normalized earnings per share fell by more than half in fiscal 2026, and heavy cloud spending meant RMB 44.7 billion more went out than came in (free cash flow) in the June quarter.
- Wall Street’s consensus target of $185 has barely moved in a year, and analysts expect earnings to recover by fiscal 2028.
- The $192 target implies 24.3x forward earnings, close to the stock’s five-year high, so the call looks plausible but stretched.
Alibaba Group Holding (BABA) has lost 41% since its closing high a year ago, and Jefferies still sees a big rebound. On Oct. 8, analyst Thomas Chong reiterated his Buy rating and raised his target to $192 from $190, 79% above the Oct. 7 close of $107.
What sank Alibaba
Earnings did the damage. Alibaba’s normalized earnings per share fell by more than half in fiscal 2026 (the year to March 2026), as it spent heavily on quick commerce and AI infrastructure.
The June quarter, reported Aug. 20, showed the spending still climbing. Adjusted EBITDA fell 30%, and free cash flow was an outflow of RMB 44.7 billion, against RMB 18.8 billion a year earlier, on RMB 67.7 billion of capex. CFO Toby Xu said the decline “was mainly attributed to the investment in cloud infrastructure.”
What Jefferies sees
That cloud build-out is what Jefferies is betting on. Cloud revenue grew 45% in the June quarter, and the firm expects growth of more than 50% in fiscal 2028, with cloud profits covering the losses in AI Lab and Applications in the December quarter. It keeps Alibaba as a Top Pick, though $192 is down from the $230 target Chong set a year ago.
Management agrees. CEO Eddie Wu said in August that “our AI and cloud revenue growth will accelerate further in the coming quarters, alongside continued improvement in profitability.”
Does $192 add up?
Jefferies has plenty of company. Wall Street’s consensus target has barely moved while the stock slid.

TIKR’s consensus target was $186 at the end of September 2025 and is $185 today, with 30 Buys, eight Outperforms, one Hold and one Underperform. Jefferies’ $192 sits just above the pack.
That optimism rests on a rebound in earnings.

Consensus has normalized EPS climbing in fiscal 2027 and back to about its fiscal 2024 level in fiscal 2028, and a solid September quarter, as Jefferies expects, gives no reason to cut it.
The multiple is where the call gets harder.
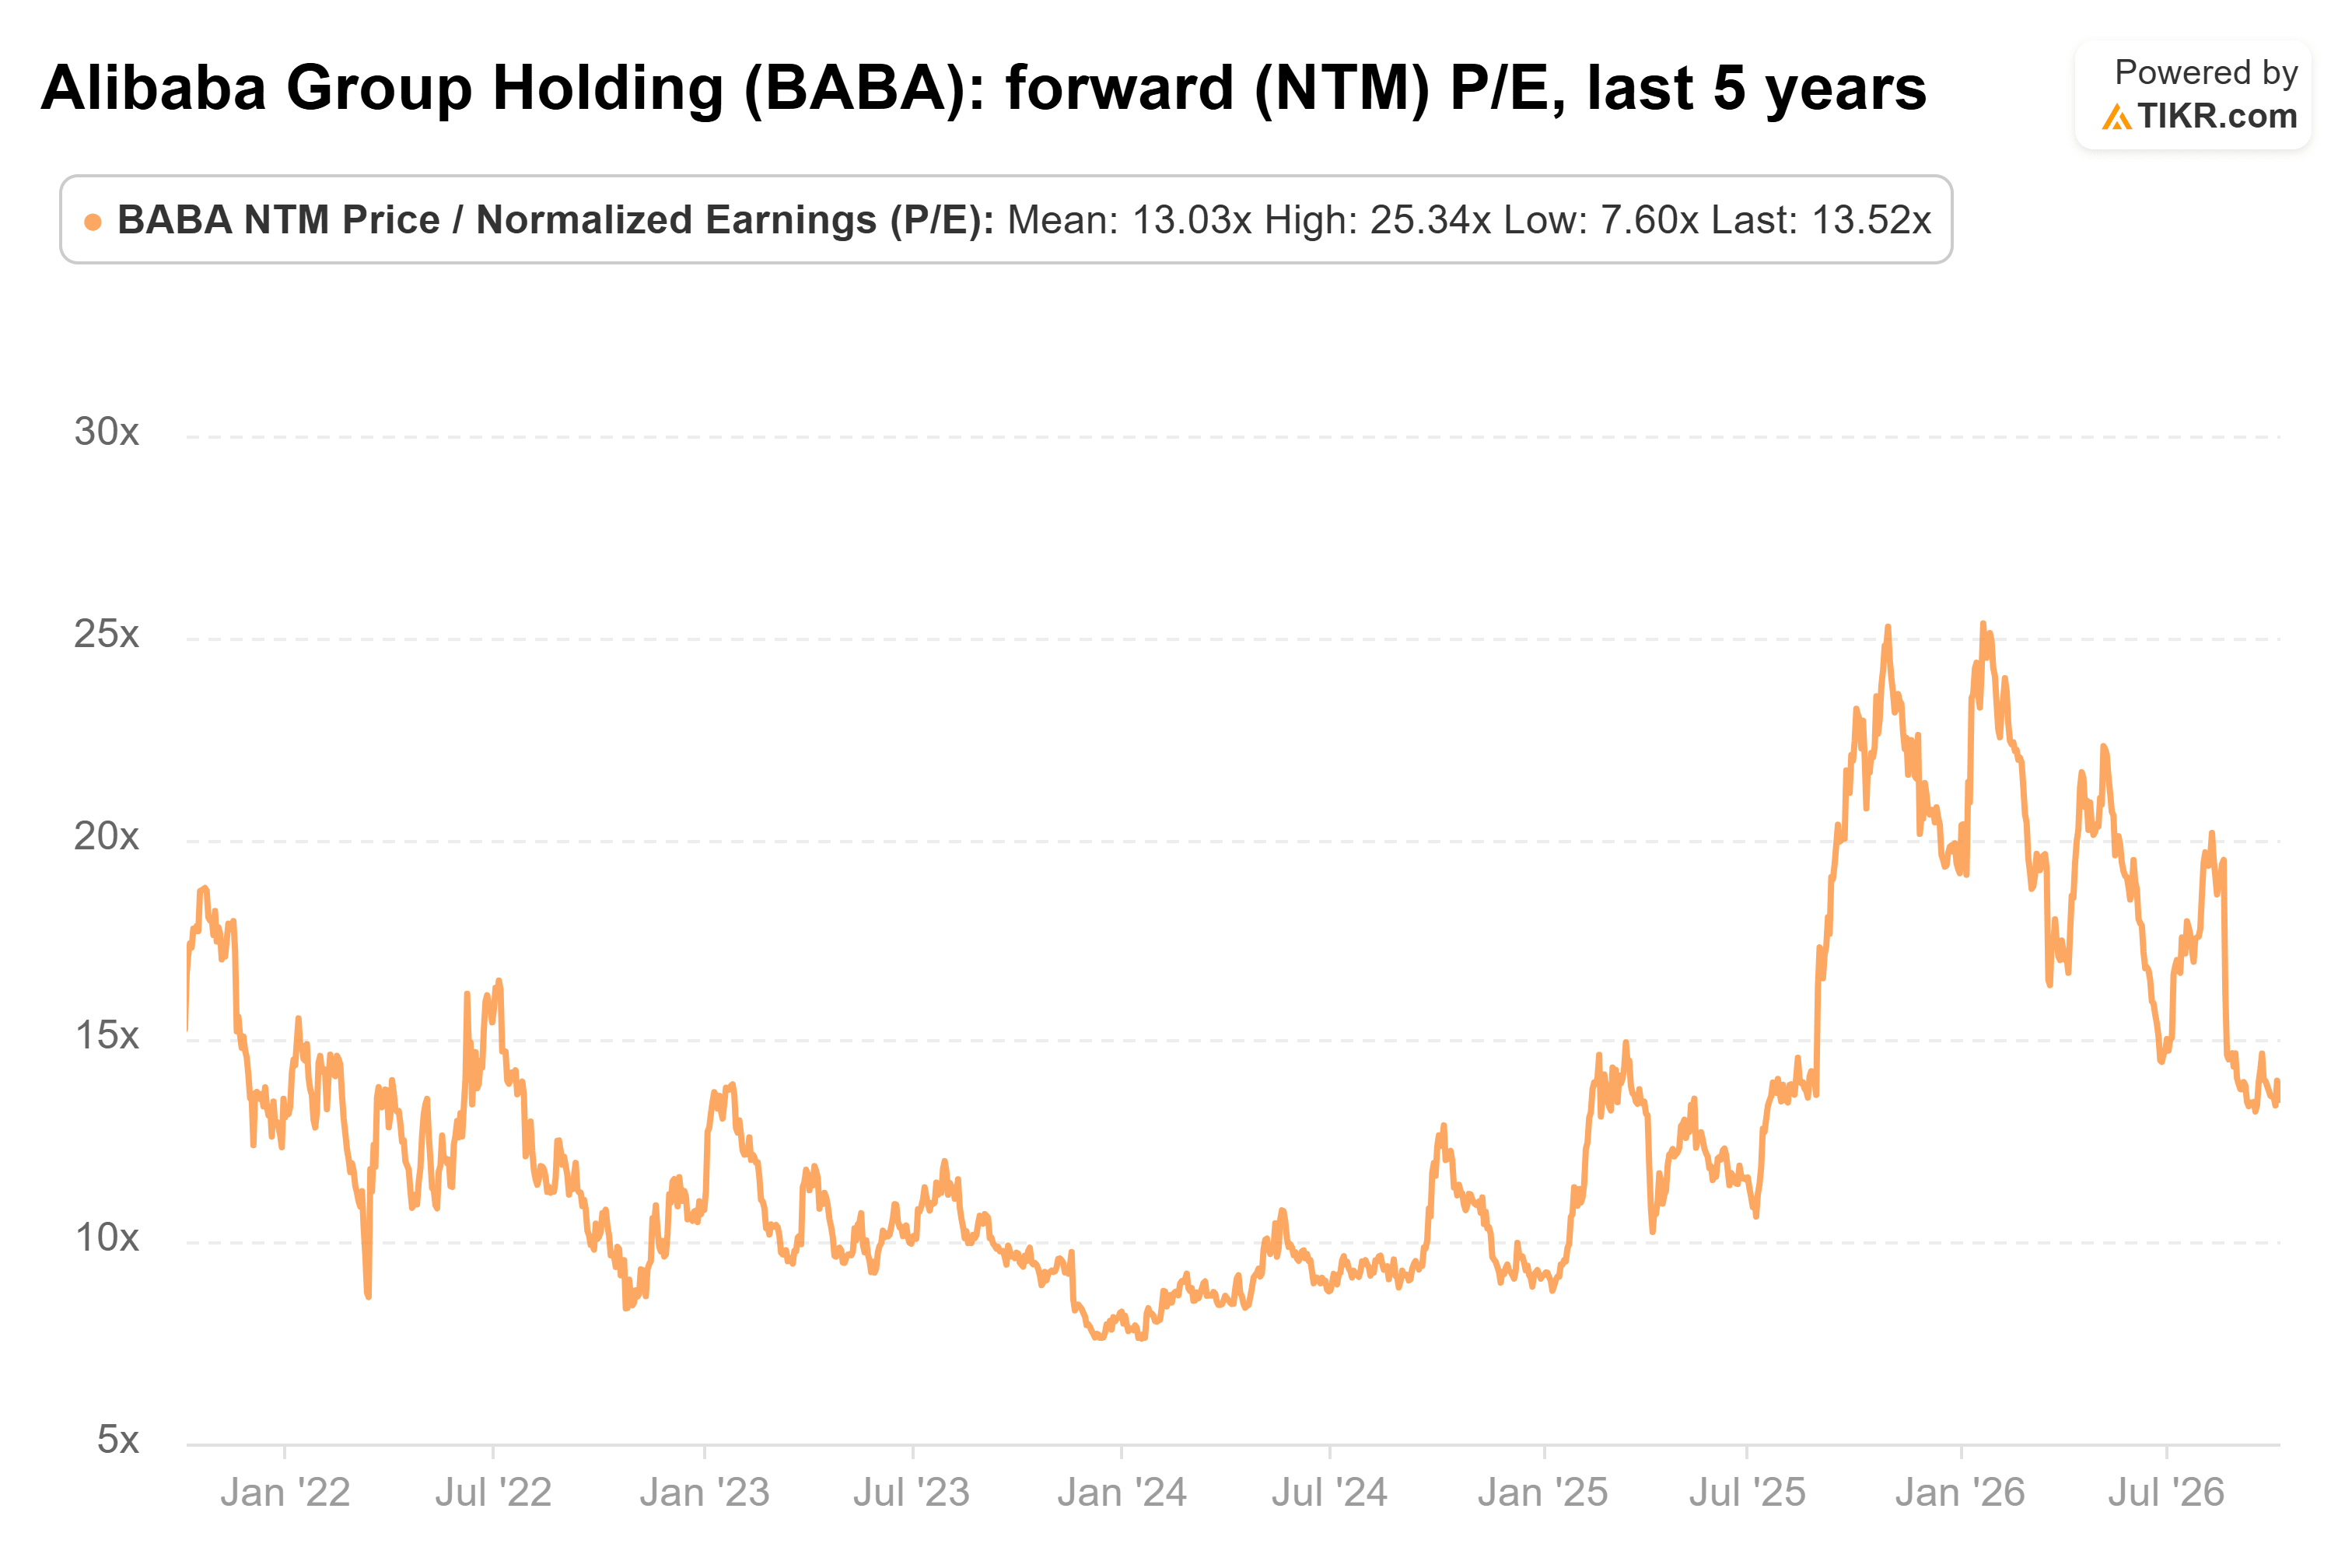
At 13.5x forward earnings, Alibaba trades close to its five-year average of 13.0x, far below its 25.3x peak in January 2026. $107 divided by 13.5x puts consensus earnings for the next twelve months at $7.91 a share. Divide $192 by $7.91, and Jefferies’ target implies 24.3x, close to that peak.
That gap narrows if the rebound arrives on schedule, as the higher fiscal 2028 estimate rolls into forward earnings. Even so, the multiple $192 implies would sit well above the stock’s usual one.
So is Jefferies right?
The risk is the spending: management says it’s committed to aggressive capex, and that June-quarter cash outflow shows the cost.
At 13.5x], the stock carries no premium for the cloud growth. But $192 needs both the earnings recovery and a multiple near the stock’s five-year high, so I’d call it plausible but stretched. The next test is Alibaba’s September-quarter report: if cloud growth tops June’s 45% and quick commerce losses keep narrowing, $192 gets a lot easier to defend.
So what is Alibaba stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Alibaba could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!


