Key Takeaways
- Accenture (ACN) stock is up 31% in the past month, and Wells Fargo and UBS have raised their price targets to $252 and $300.
- Analysts expect $14.66 a share for fiscal 2027, right in the middle of the guidance Accenture gave on Oct. 1, so the higher targets rest mostly on a higher multiple.
- Even after the rally, Accenture trades at 18x forward earnings, well below its five-year average of 24x, and its free cash flow rose to $11.6 billion in fiscal 2026.
- The higher multiple looks justified, but for the stock to keep climbing, the estimates probably need to rise, and the first test is the Q1 report.
Accenture stock is up 31% in the past month, and Wall Street has been chasing it. On Oct. 26, Wells Fargo raised its price target to $252 from $210, and UBS took its own to $300 from $278.
However, Baird downgraded the stock to Hold on Oct. 21, citing valuation, even as it nudged its target up to $252 from $245.
So for anyone holding the stock, the question is whether analysts now expect Accenture to earn more, or whether they’re just willing to pay more for the earnings they already expected.
TIKR tracks 30 analysts on Accenture. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Accenture, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Accenture’s Analyst Ratings
The estimates sit right where Accenture put them
Accenture’s last earnings report came on Oct. 1, weeks before either raise. Q4 revenue came in above the top of the company’s own guided range, and new bookings of $22.2 billion were 1.2 times the quarter’s revenue. For the full fiscal year ended August 2026, adjusted EPS rose 8% to $13.97.
For fiscal 2027, management guided to 3%-6% revenue growth in local currency and EPS of $14.39-$14.81, up 3%-6% from fiscal 2026’s adjusted figure.
TIKR’s consensus for the next two fiscal years lands almost exactly on that guidance:
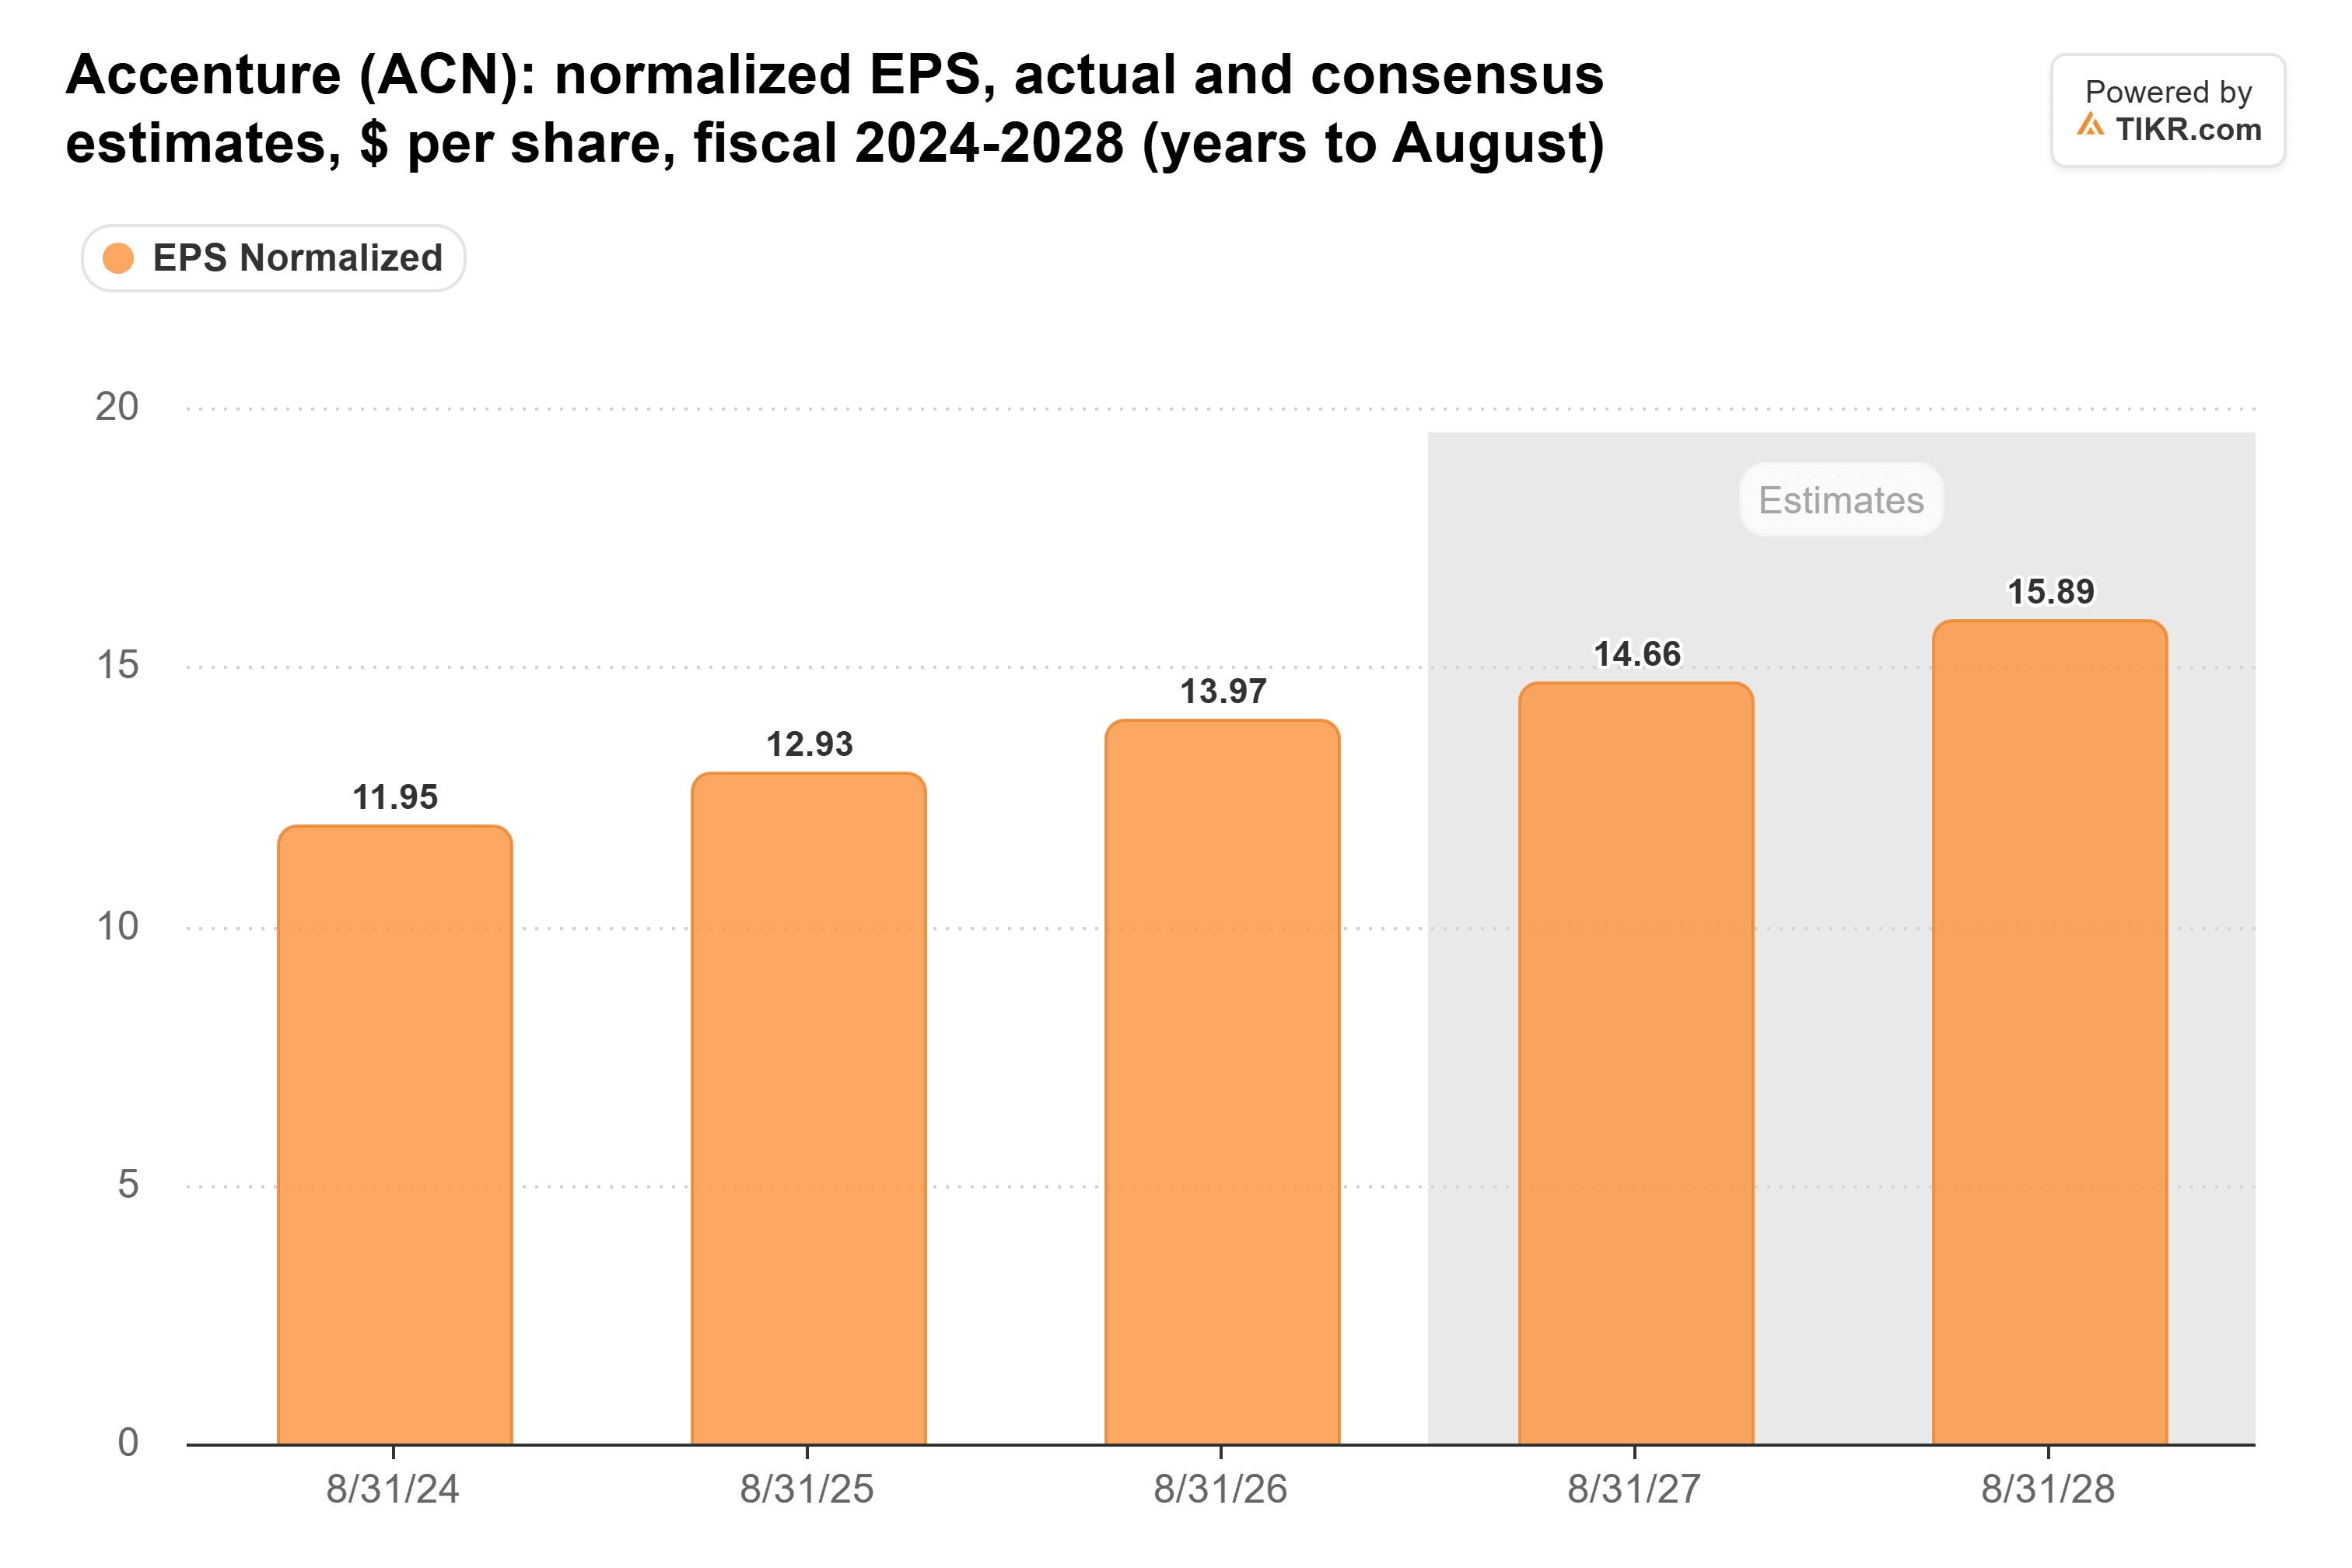
The 28 analysts behind the fiscal 2027 estimate expect $14.66 a share, a few cents above the midpoint of guidance and about 5% growth.
For fiscal 2028, the 26 analysts estimating it expect $15.89, up another 8%.
That faster step fits the plan Accenture laid out at its Oct. 14 investor day: at least mid-single-digit revenue growth, plus 10-30 basis points of operating margin gains a year through fiscal 2029.
Between that event and the target raises, the company put out no new numbers.
Analysts are paying a higher multiple
Set the targets against that $14.66, and the change is plain. Wells Fargo’s old $210 target was about 14x fiscal 2027 earnings, and its new $252 is about 17x.
UBS’s $300 works out to about 20x. (Wells Fargo has raised twice in a month, too: it went to $210 from $194 the day after the report.)
So the raises are a call on the multiple. Accenture’s forward P/E has climbed off its June low, but it’s still well under its five-year average:

At 18x, the stock trades far below its 24x five-year average. In June it bottomed at 8.6x, its lowest point in five years.
The slide earlier this year pushed the multiple down so far that a good chunk of the rebound is just the stock climbing back toward its usual valuation.
Even UBS’s $300 asks for less than that 24x average.
The cash backs it up
Accenture’s free cash flow has climbed for two straight years:
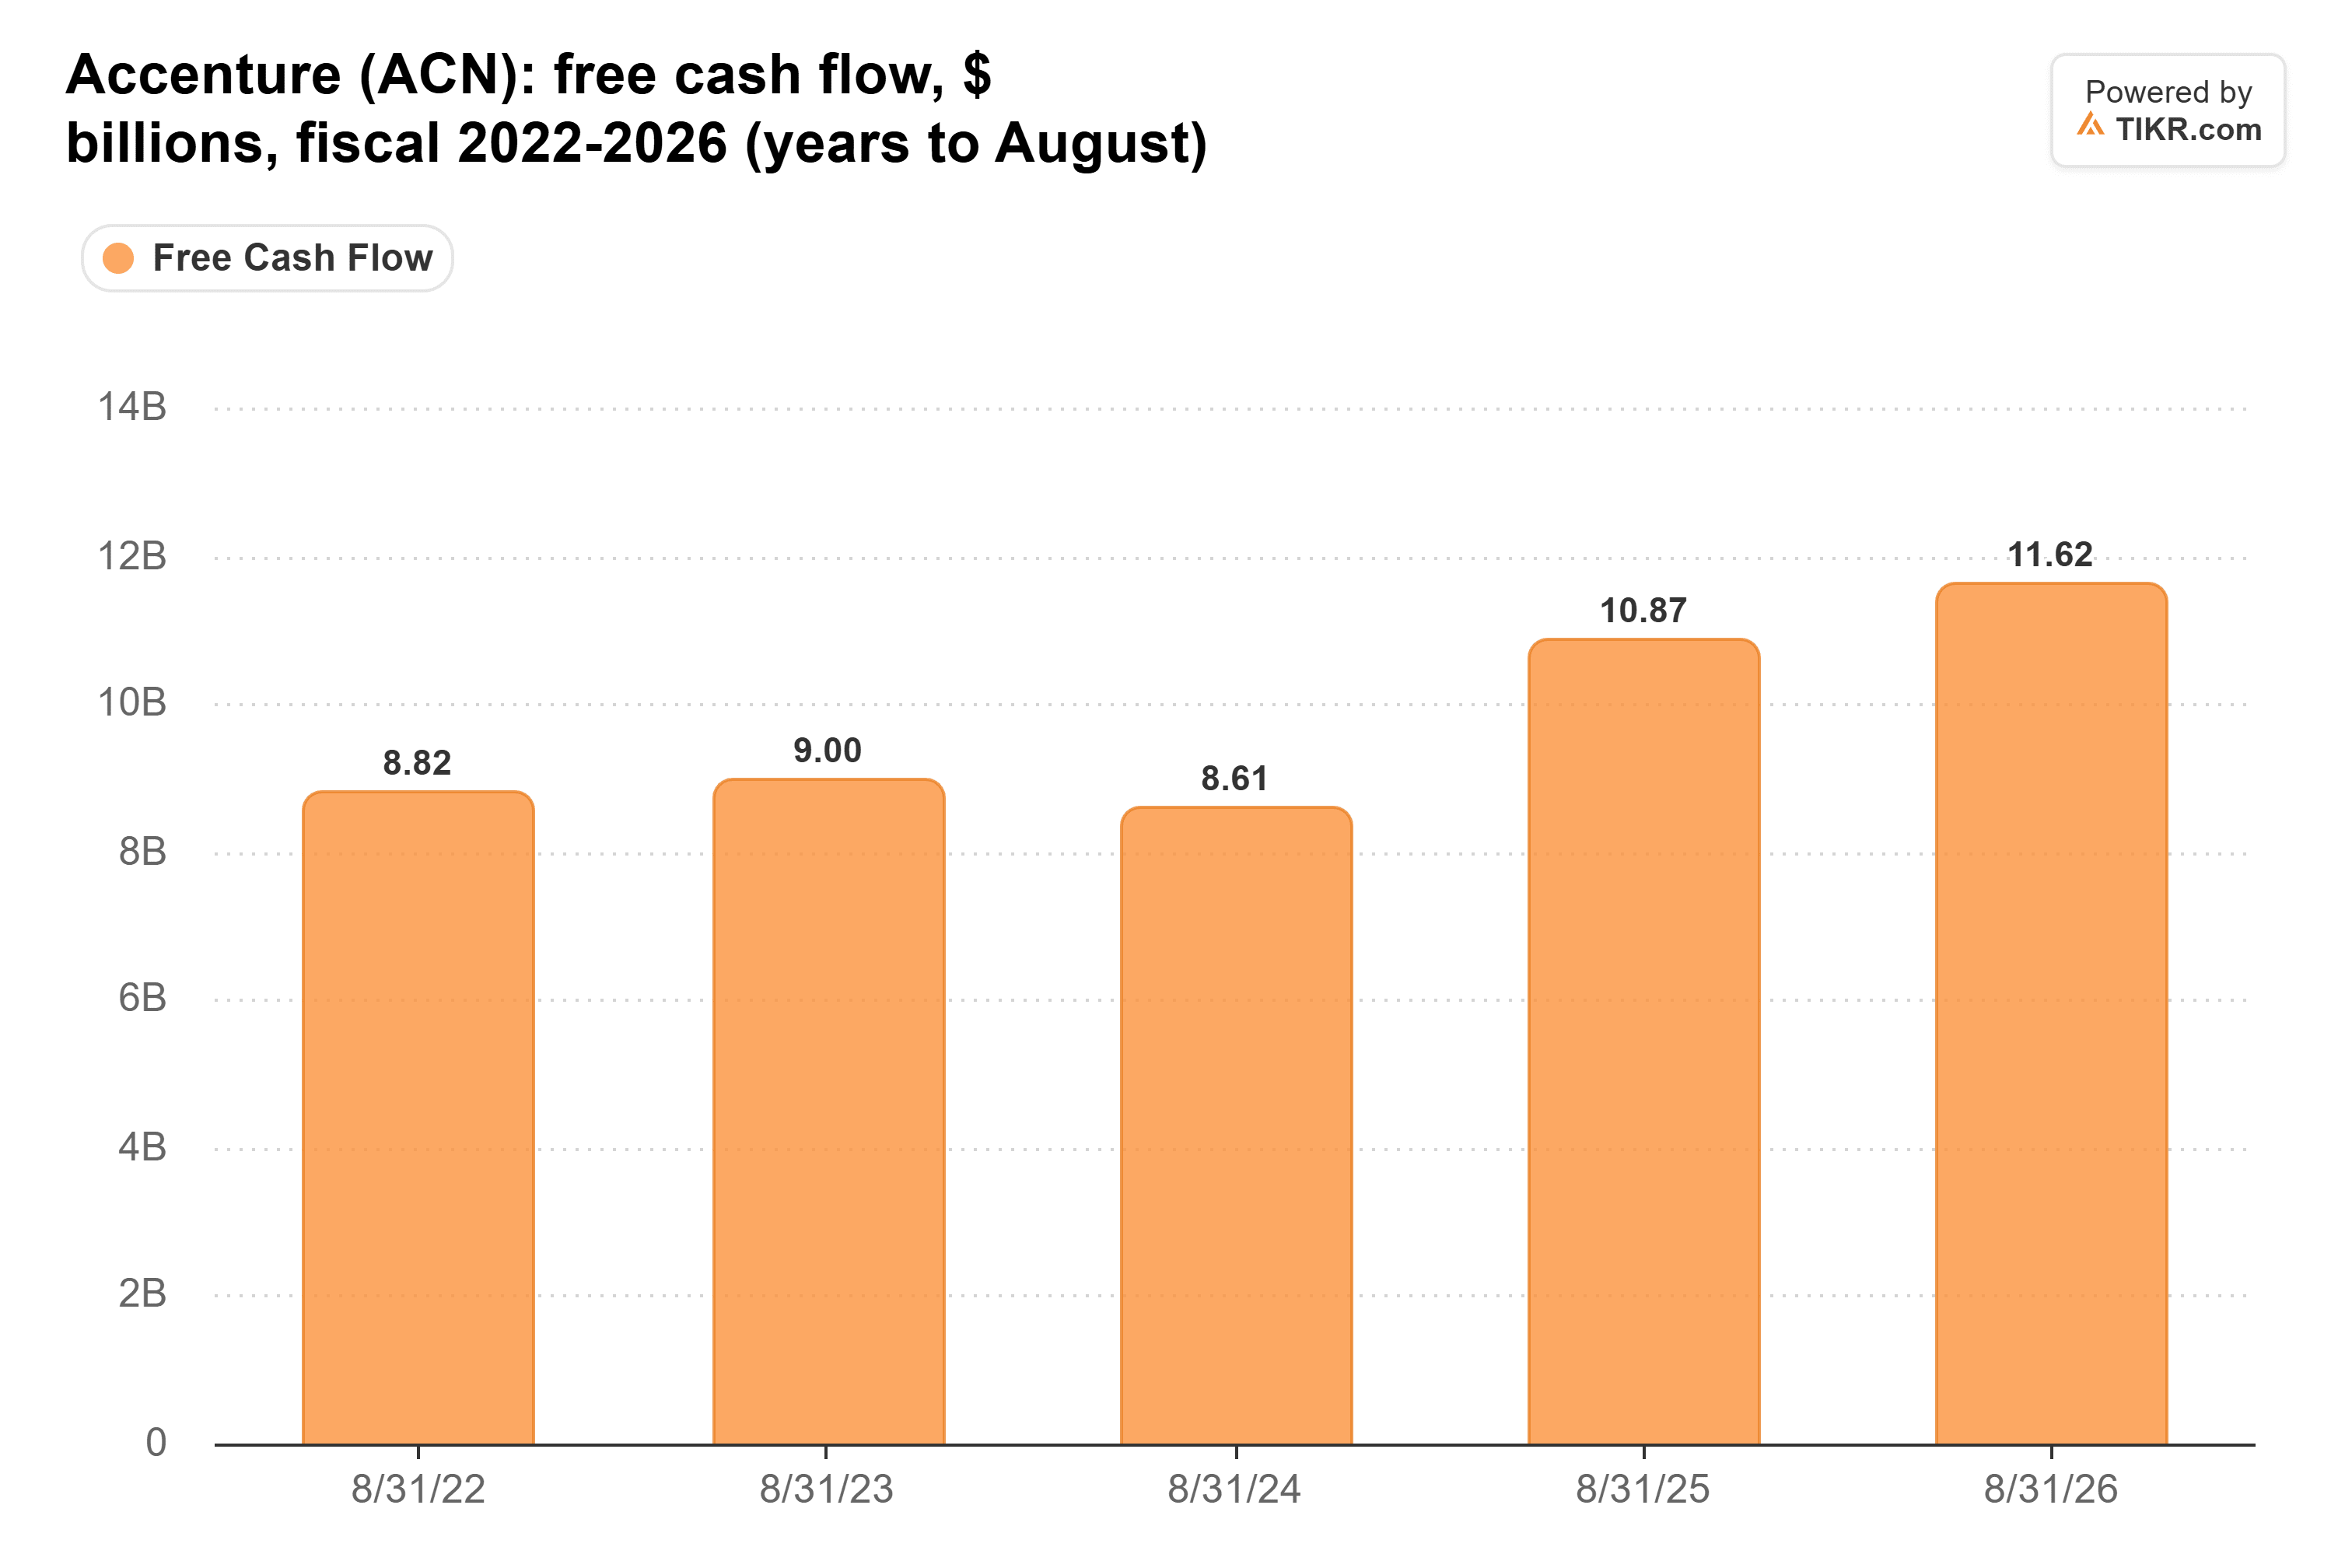
Fiscal 2026’s $11.6 billion was 35% above fiscal 2024’s $8.61 billion, and well ahead of the $9.8-$10.5 billion management first guided for the year.
Accenture returned $11.5 billion to shareholders in fiscal 2026, nearly all of it. A business turning out that much more cash makes a higher multiple easier to defend.
Room to run, if the estimates follow
Analysts’ forecasts sit where Accenture’s own guidance put them on Oct. 1, before the raises. The targets rose because analysts are willing to pay a higher multiple for those earnings.
And frankly, I think that’s fair. A stock that traded at 8.6x in June and still sits at 18x, with free cash flow at $11.6 billion and climbing, had plenty of room to re-rate.
The risk is growth: about 5% EPS growth this year doesn’t leave much cushion if the multiple stalls.
For the stock to keep climbing from here, though, I’d want to see the estimates rise too. The first test is the Q1 report, for the three months to Nov. 30.
A beat that pushes fiscal 2027 consensus toward the top of guidance would put UBS’s $300 well within reach.
So what is Accenture stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Accenture could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!