Key Takeaways
- Abrams Bison Investments raised its Applied Materials (AMAT) stake 36% to 752,000 shares in Q3, making it 19.4% of its 13F holdings.
- Applied Materials has fallen 36% since Sept. 30, while analysts’ fiscal 2027 EPS estimate has risen to $19.29 from $16.40 at the end of June.
- ASML Holding (ASML) had a record quarter and warned that its planned supply won’t meet chipmakers’ demand in 2027 and 2028, which suggests equipment spending will last.
- At 18x forward earnings, below its 21x five-year average, the numbers back the fund’s bet, as long as the estimates hold through ASML’s and Applied’s next reports.
Applied Materials is now the second-biggest holding at Abrams Bison Investments, a firm that manages $3.04 billion. Its 13F for the quarter ended Sept. 30, filed Nov. 16, shows 752,000 shares worth $385 million, 19.4% of its 13F holdings.
That’s a big bet on chipmakers’ equipment budgets holding up through the AI build-out. The same spending drove the record quarter ASML Holding reported in October.
It’s No. 2 holding, and growing
Abrams Bison held 36% more Applied shares than it did the quarter before. Its 13F has just 12 positions, worth $1.98 billion at quarter-end prices.
A 13F only shows what a fund held on the last day of the quarter, so there’s no telling when it bought or what it paid.
Since Sept. 30, Applied has fallen 36%. Abrams Bison had company on the buy side, including David Tepper’s Appaloosa, but the big funds that have filed split almost evenly on Applied, 26 buyers to 27 sellers.
TIKR tracks 40 analysts on Applied Materials. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Applied Materials, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Applied Materials’ Analyst Ratings
Earnings estimates keep climbing
Investors are paying a lot less for Applied’s earnings than they were in the summer.
At an investor event on Oct. 13, management set 2030 targets of a 54% non-GAAP gross margin and a 40% non-GAAP operating margin, but gave no forecast for next year’s equipment market.
Then the stock fell after a record quarter as analysts cut their targets, even though Q4 non-GAAP gross margin came in at 50.6%, beating the company’s own 50.4% guide.
Meanwhile, analysts expect normalized EPS to nearly double from fiscal 2026’s $12.89 to $24.63 in fiscal 2028:
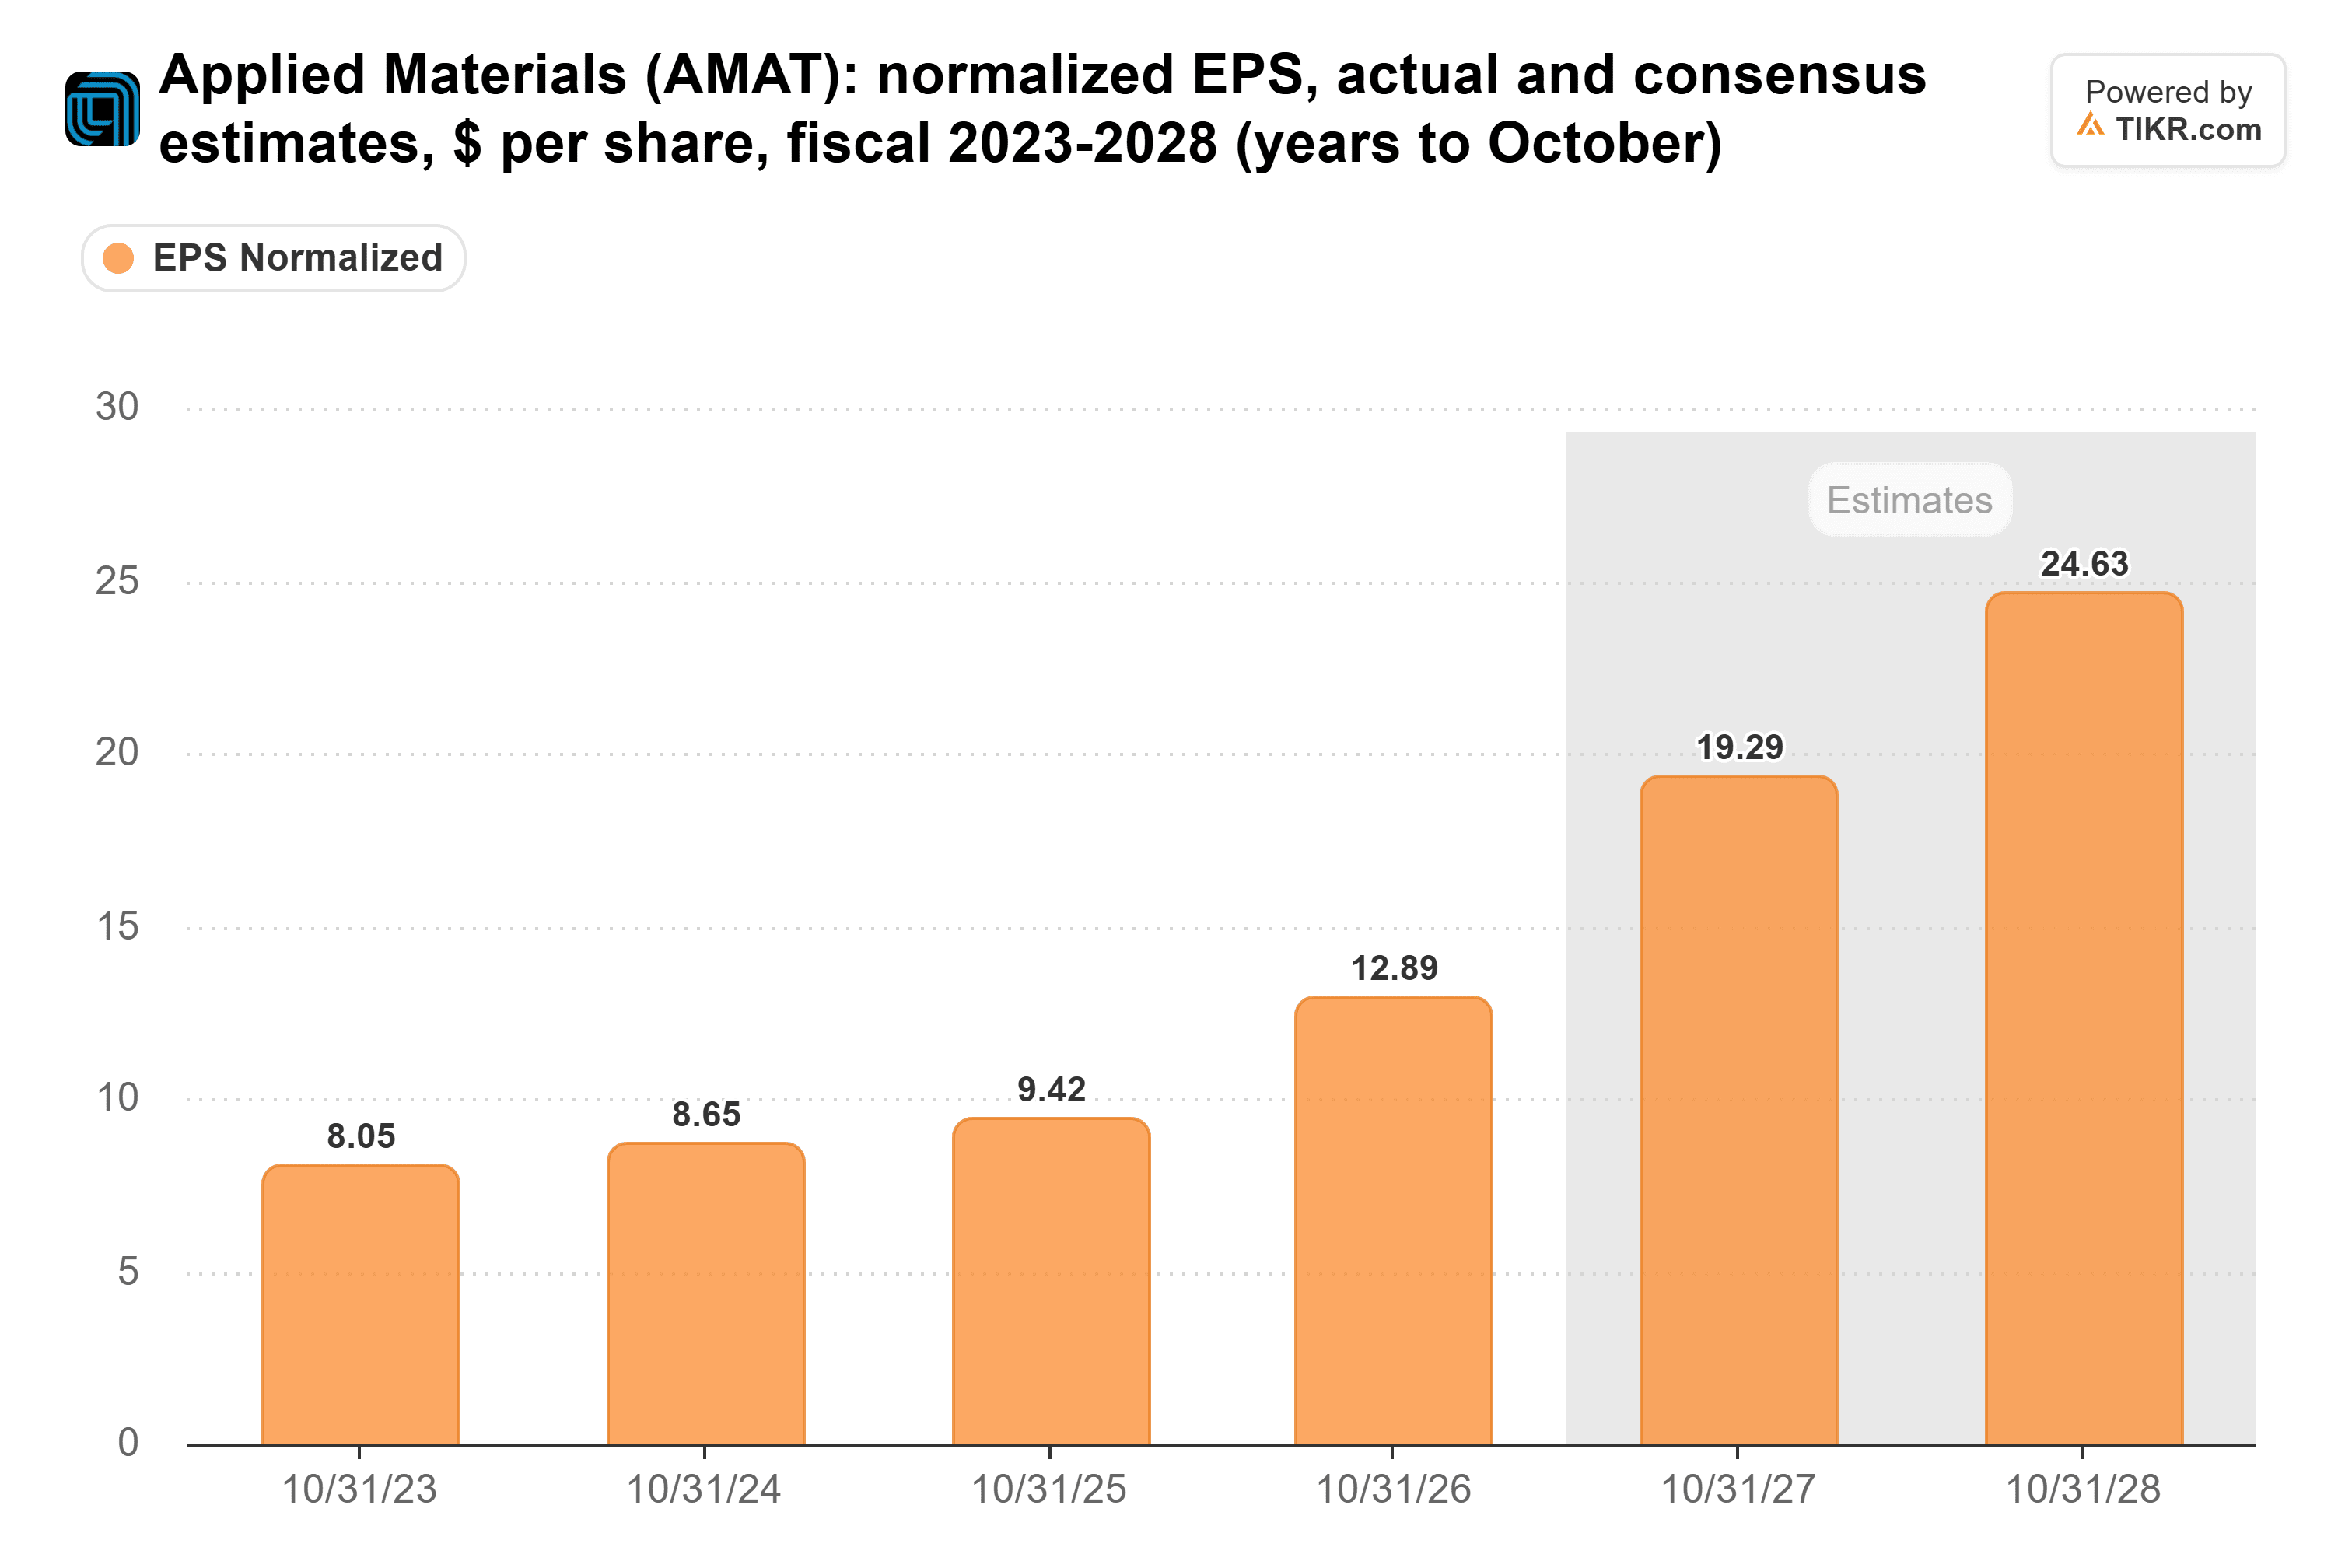
The fiscal 2027 estimate of $19.29 was $16.40 at the end of June.
ASML’s latest quarter backs those numbers. It reported record Q3 sales of €11.7 billion on Oct. 14, and President and CEO Christophe Fouquet said customers “continue to increase their short- and medium-term equipment demand forecasts with us.”
He added that ASML’s supply as planned for 2027 and 2028 “will not fully meet the demand of our customers.”
Some customers also want to place orders for 2029 and 2030. That’s the same build-out Applied’s estimates depend on.
Cheaper than usual, on bigger earnings
Applied trades at 18x forward earnings. That’s below its 21x five-year average, and far from the 49x it hit at the end of June:
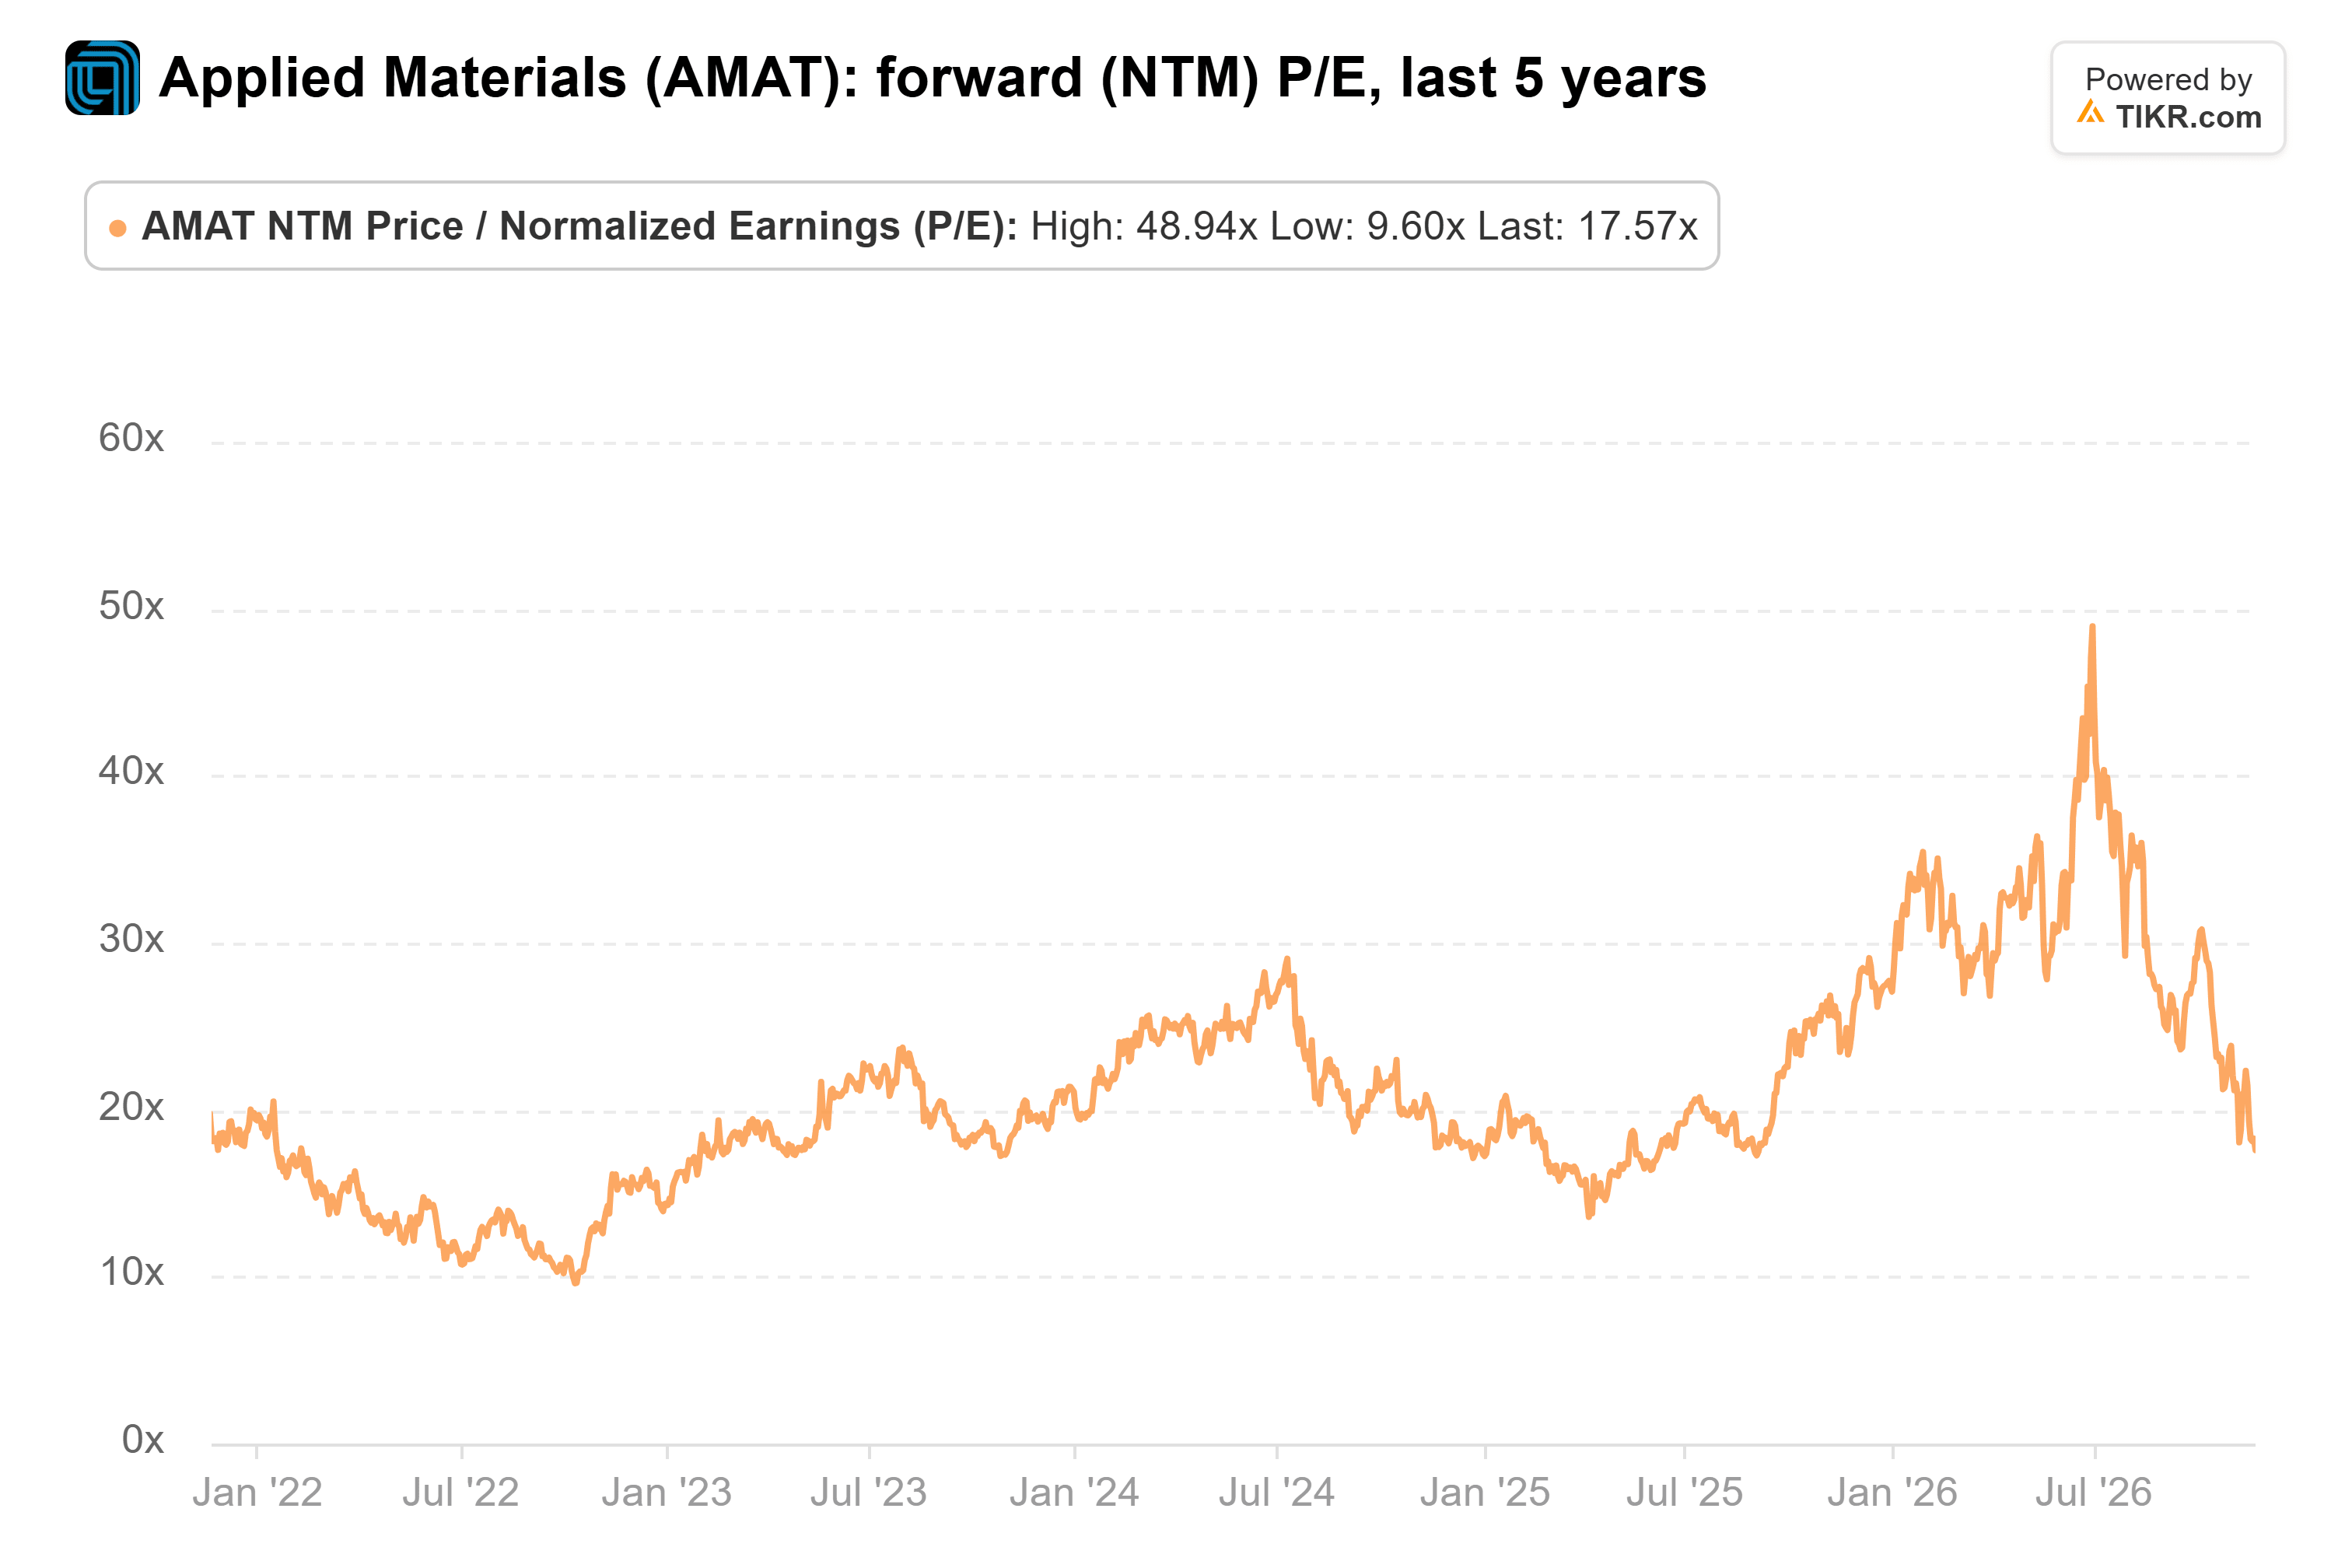
(It got as low as 9.6x in October 2022, so 18x isn’t a floor.)
The Street’s average target has come down too, though it’s still well above the stock:
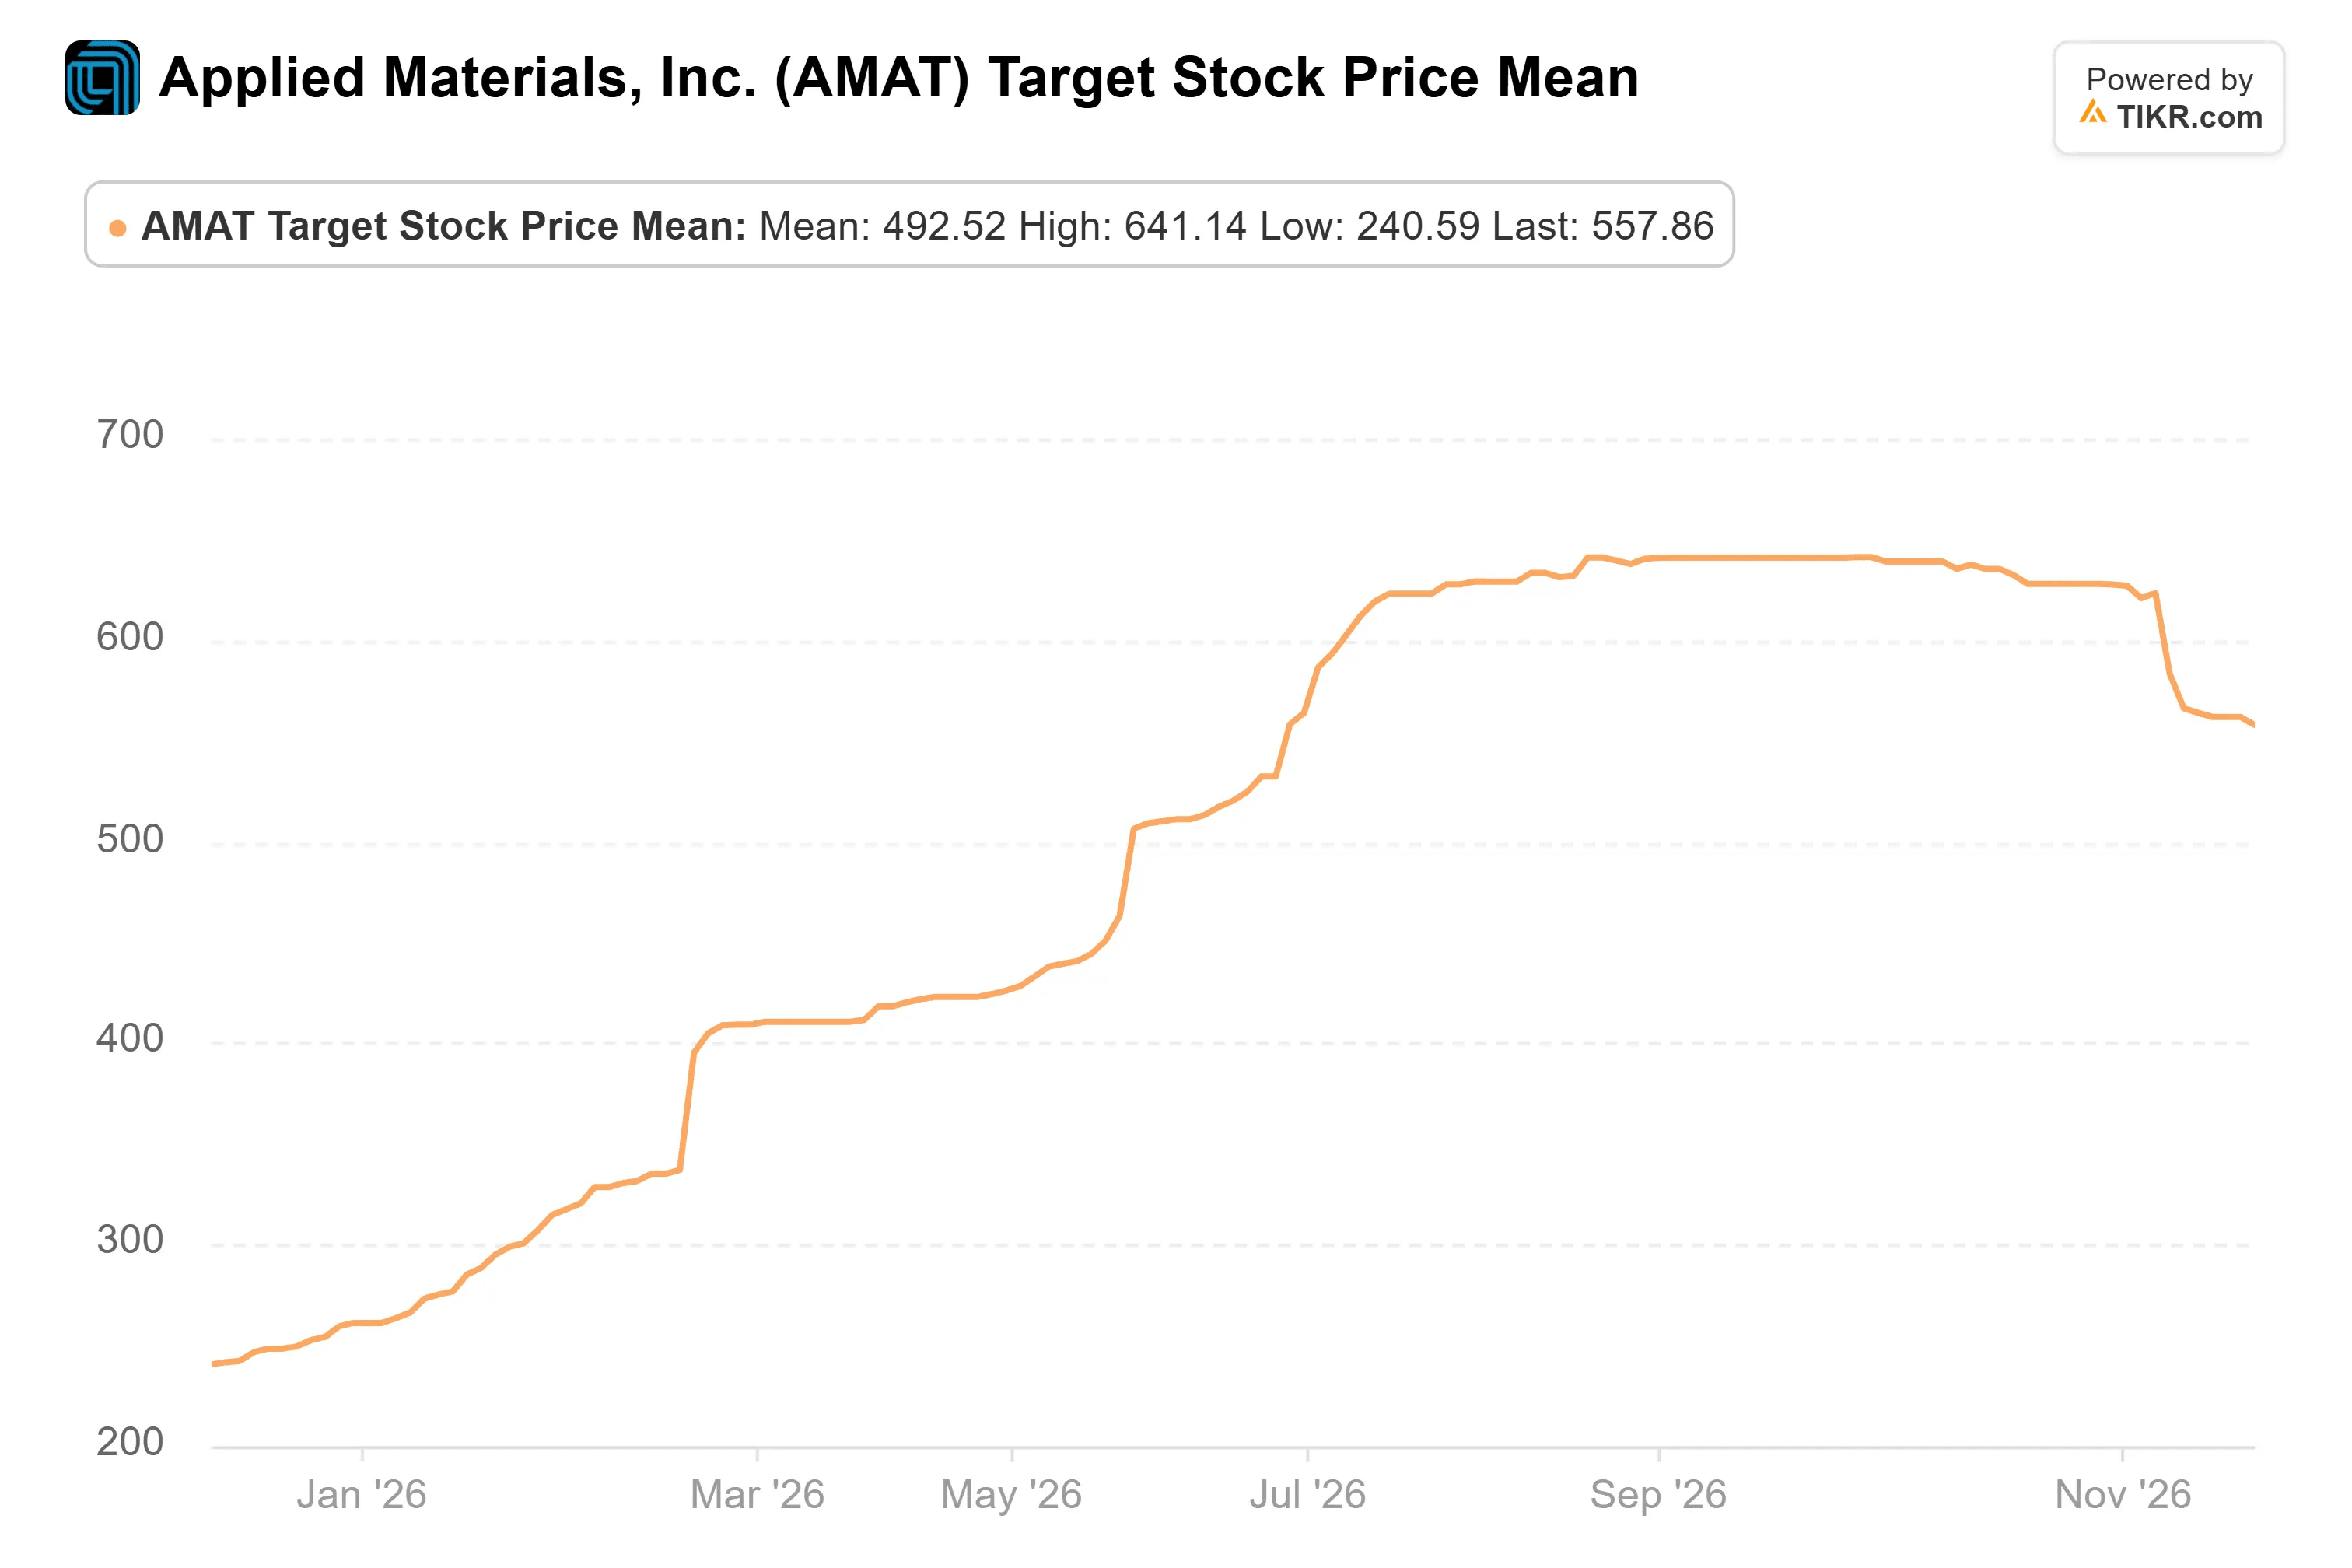
At $562, the consensus target is down from $641 in late September, but it’s still about two-thirds above the last close of $338.93. Even the lowest target, $358, is above that close.
By my math, $562 works out to about 23x the fiscal 2028 EPS estimate of $24.63, a bit above the 21x average.
So roughly half the upside to the target comes from earnings growth, and half from the multiple getting back to normal. And if the multiple just holds at 18x, those estimates would put the stock around $430 a year from now.
The numbers back Abrams Bison
Equipment booms do end, though. Two customers made up 34% of Applied’s revenue in the first nine months of fiscal 2026, so one big customer pulling back would show up fast.
Still, I think Abrams Bison has this one right. Applied trades below its usual multiple, its earnings estimates kept rising through the selloff, and the stock doesn’t need a re-rating to work from here.
ASML reports on Jan. 27 with its view of 2027, and Applied’s fiscal Q1 report follows in February. If the fiscal 2027 estimate holds at $19.29 or better through both reports, the case holds.
A cut would make the lower multiple look justified. Abrams Bison’s next 13F, due in mid-February, will show whether it held on.
So what is Applied Materials stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what Applied Materials could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Value Applied Materials for free
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!