Key Takeaways
- ExxonMobil shares are down 11% in the past month as oil prices fell on hopes for an end to the Iran war, alongside a broad market selloff.
- Refining earned more than half of Exxon’s third-quarter adjusted profit, and the market treats that kind of windfall as temporary.
- Refiner Marathon Petroleum and producer ConocoPhillips face the same slide, and analysts expect earnings to fall next year at all three companies.
- At about 15x analysts’ 2028 earnings, Exxon looks fairly valued, and fourth-quarter results around the end of January are the next test of CEO Darren Woods’ claim.
ExxonMobil (XOM) is down 11% in the past month and now sits 16% below the 52-week high it set on Oct. 30, the day it reported third-quarter results.
Oil did most of the damage. Brent peaked at $116.31 a barrel on Oct. 28 and dipped below $90 on Nov. 10. The US and Iranian presidents had both said they were open to a deal, and President Trump said the war could end “fairly soon.” Meanwhile, the S&P 500 fell 7% over the same month.
The slide reached the rest of the oil patch. Marathon Petroleum (MPC) booked the same kind of refining windfall in the third quarter, and ConocoPhillips (COP), with no refineries, sells straight into lower oil prices.
Darren Woods, Exxon’s chairman and CEO, said in its third-quarter release that the gains will last: “These are lasting improvements, not simply the result of favorable prices and margins.”
TIKR tracks 26 analysts on Exxon Mobil. How many say “Buy”?
See the full breakdown of Buy, Hold, and Sell ratings on Exxon Mobil, along with Wall Street’s revenue and earnings estimates, all in one place. More than 500,000 investors use TIKR to research stocks like this one. See Exxon Mobil’s Analyst Ratings
Refining did the heavy lifting
Exxon’s adjusted earnings rose to $17.5 billion, or $4.23 a share, in the third quarter, from $14.7 billion in the second. Energy Products, its refining business, earned more than half of that: $9.05 billion, up from $4.10 billion, as the refining margin Exxon tracks averaged $50.30 a barrel against $29.00. Upstream earnings fell to $7.31 billion from $9.19 billion as Exxon’s realized US crude price dropped to $84.82 from $97.58.
Marathon shows how the market prices that kind of profit. Its refining margin hit $45.70 a barrel in the third quarter, against $17.60 a year earlier. Even so, it trades at just 5.1x forward earnings, and analysts see its EPS falling 13% in 2027. They expect Exxon’s to fade too:
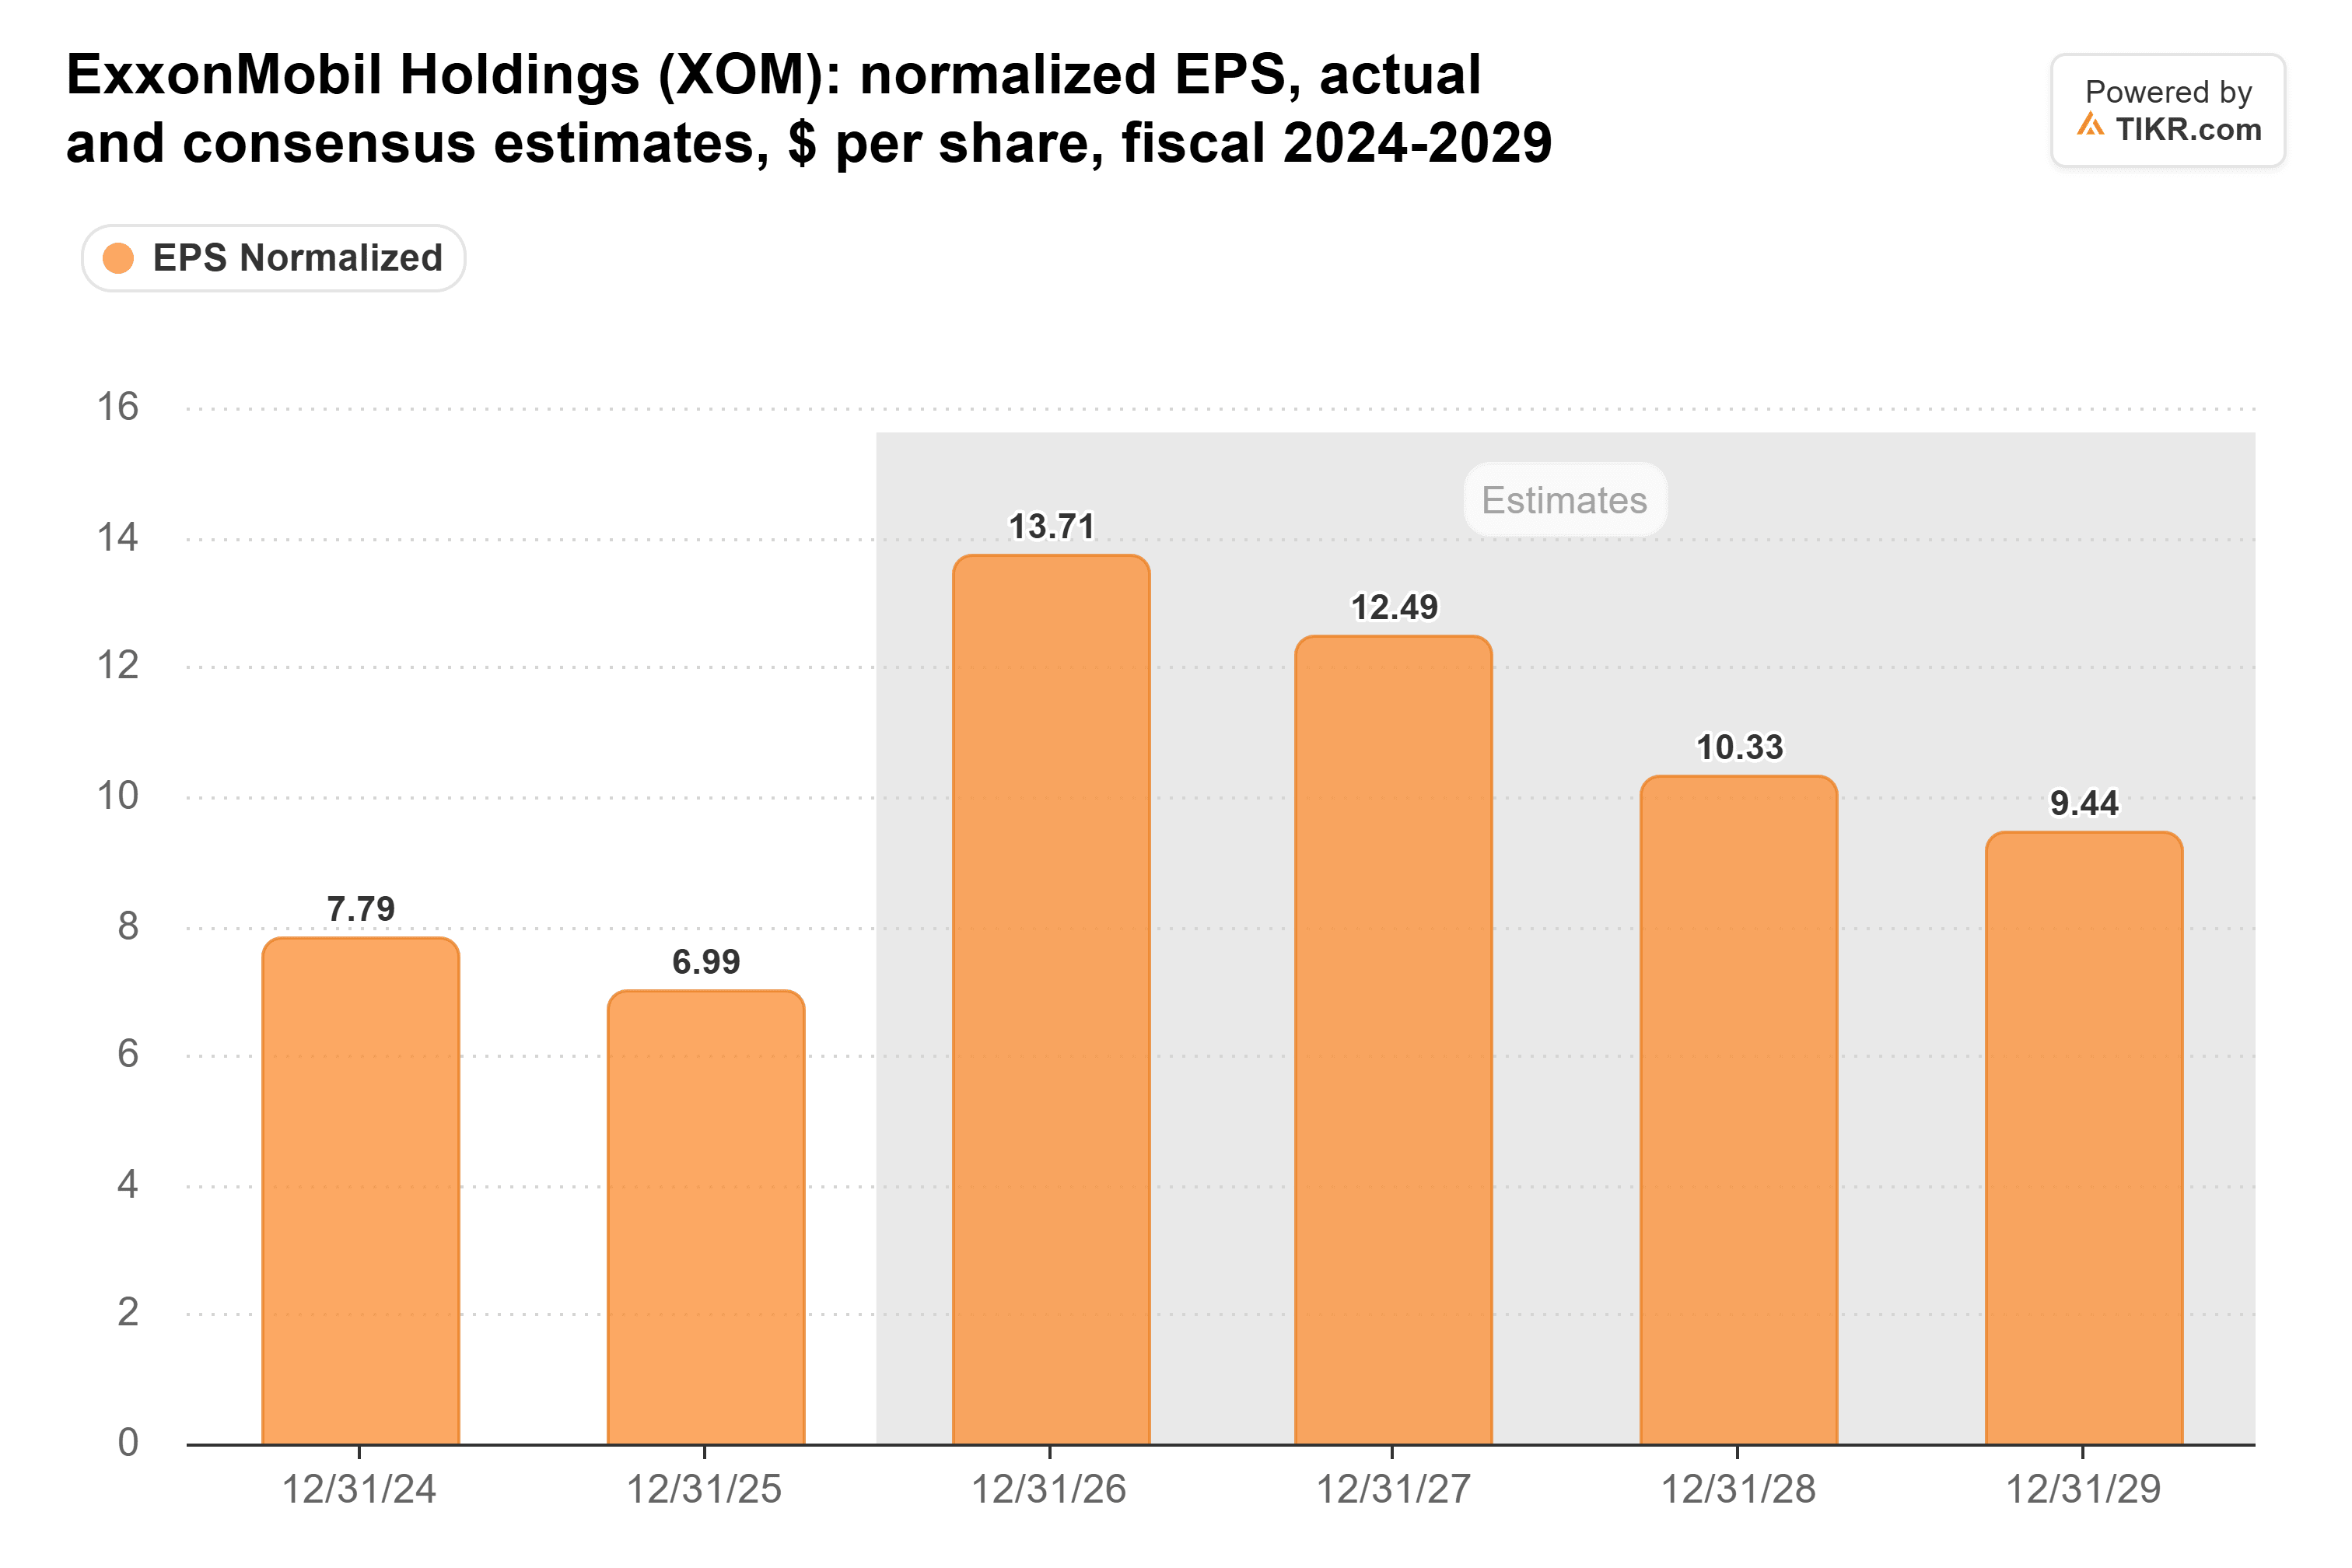
For the fourth quarter, analysts expect $4.11 a share. With Brent below the third quarter’s $97.01 average, I’d expect that figure to come down.
The parts that don’t need $100 oil
On Nov. 16, Exxon started production at Uaru, its fifth Guyana development, lifting Guyana’s installed capacity to 1.1 million barrels a day. The third quarter’s $19.1 billion of free cash flow covered $9.4 billion of dividends and buybacks twice over, and net debt was just $22.1 billion at Sept. 30. Exxon also raised its dividend for a 44th straight year and plans $20 billion of buybacks in 2027.
ConocoPhillips is the cleaner look at oil without refineries. It also trades at about 11x forward earnings, but analysts expect its EPS to slip just 4% next year, against a 9% drop for Exxon. Refining lifted Exxon’s 2026 more, so it has more to give back.
Is ExxonMobil a buy at this price?
On forward earnings, Exxon looks cheaper than usual:
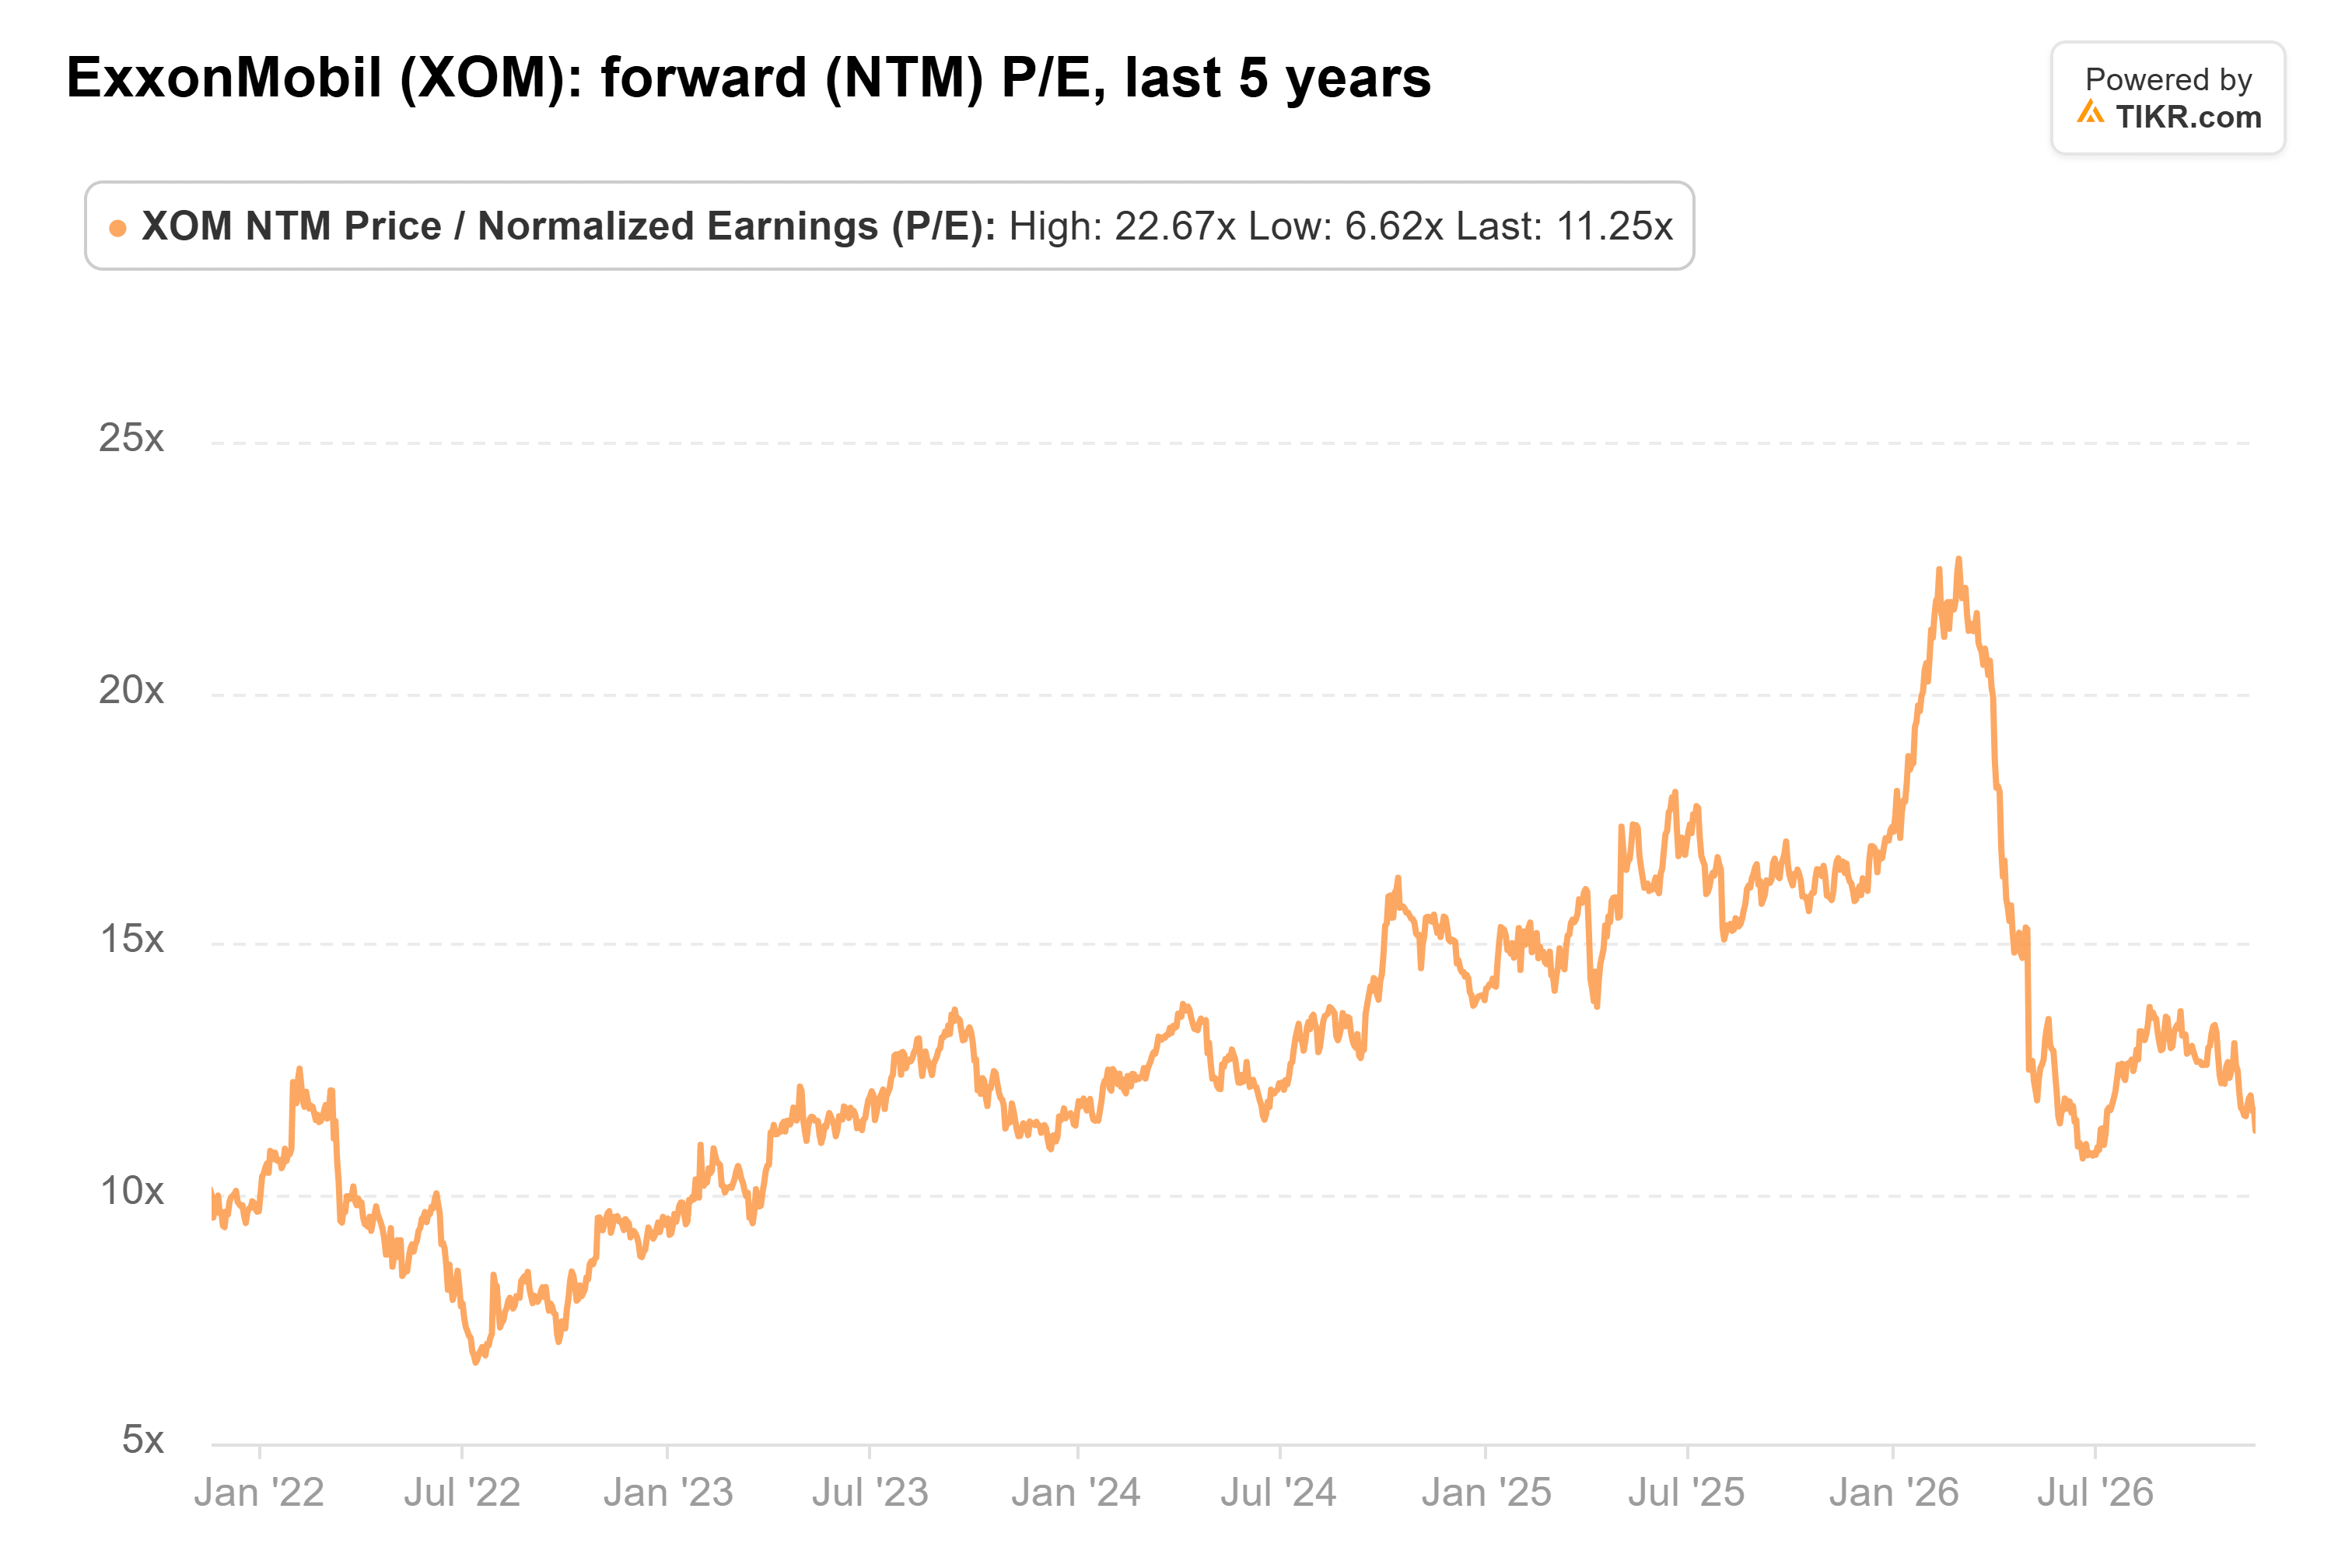
It trades at about 11x, against a 13x average over five years. But those forward earnings still include the war’s windfall. On analysts’ 2028 estimate of $10.33, the stock trades at about 15x.
Barclays raised its target to $206 from $200 on Nov. 13. A day earlier, Bernstein cut its target to $186 from $193. By our math, $206 is about 20x 2028 earnings, and the $184 consensus target is about 18x.
That’s a lot to pay for earnings that analysts expect to fall every year through 2029. Exxon is a solid business, but at this price I’d call the stock fairly valued and the Street’s targets too high.
The next test is fourth-quarter results, due around the end of January. Adjusted EPS near $4.11 or better, with Brent below $97, would back Woods’ claim. A big miss would mean the windfall is fading faster than analysts expect.
So what is ExxonMobil stock actually worth?
TIKR lets you forecast the future price of any stock in less than a minute. Just enter a few assumptions into TIKR’s valuation model and see what ExxonMobil could be worth. Start from Wall Street consensus estimates, or adjust the inputs to reflect your own view of the business. It’s free to use.
Disclaimer:
Please note that the articles on TIKR are not intended to serve as investment or financial advice from TIKR or our content team, nor are they recommendations to buy or sell any stocks. We create our content based on TIKR Terminal’s investment data and analysts’ estimates. Our analysis might not include recent company news or important updates. TIKR has no position in any of the stocks mentioned. Thank you for reading, and happy investing!